
 Industrial Floor Scrubber Market | 2026-2036
Industrial Floor Scrubber Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Floor Scrubber Market Outlook
The capital-intensity gap between robotic platform developers and conventional walk-behind manufacturers is collapsing. Tennant leverages autonomous navigation patents to sustain premium positioning in rider scrubbers. Nilfisk anchors European distribution through direct service networks while Kärcher competes on battery-electric platform breadth across compact and medium-size classes.
An industrial floor scrubber is a motorized cleaning machine combining cylindrical or disc brushes, a solution tank, and a vacuum recovery system to strip debris from hard flooring in commercial and industrial environments. Battery-powered variants now dominate new equipment specifications due to zero-emission operation requirements in enclosed warehousing and healthcare corridors. Walk-behind units retain volume leadership in retail and compact facility applications where maneuverability constraints limit rider adoption. Robotic scrubbers represent the fastest-expanding technology segment as labor cost pressures and overnight cleaning protocols reshape procurement criteria in large-scale manufacturing and distribution centers.
OSHA workplace safety standards and EPA emissions guidelines shape equipment specifications and operator training mandates in the United States. The EU Green Deal and REACH chemical compliance frameworks are accelerating lithium-ion battery transitions while restricting traditional cleaning solution formulations across European manufacturing and healthcare end users. Stakeholders must monitor regulatory divergence between battery certification standards and autonomous operation liability frameworks as procurement criteria split across geographic markets.
Market Dynamics
The collision between autonomous navigation patents and collapsing lithium-ion battery costs is compressing the premium tier in rider scrubbers while expanding addressable demand in mid-size warehousing fleets.
Growth Catalysts
- EU Green Deal battery mandates:REACH compliance frameworks and zero-emission corridor requirements in German manufacturing hubs are accelerating lithium-ion transitions across enclosed facility specifications.
- Overnight cleaning protocols:Distribution centers in the United States are deploying robotic scrubbers to eliminate labor cost premiums for second-shift maintenance operations.
- Healthcare corridor hygiene tightening:EPA emissions guidelines and OSHA workplace safety standards are stripping propane-powered units from hospital procurement lists in favor of sealed battery systems.
Market Restraints
- Lithium supply concentration:Cathode material processing bottlenecks in concentrated Asian supply nodes are transmitting volatility into scrubber OEM cost structures.
- Autonomous liability fragmentation:Divergent national frameworks for robotic equipment operator certification are creating compliance drag for cross-border fleet standardization.
- Walk-behind substitution ceiling:Compact retail footprints under 10,000 square feet face physical constraints that cap rider and robotic penetration regardless of labor economics.
Strategic Opportunities
- Indian warehousing expansion:PLI scheme incentives for cold chain infrastructure are creating first-mover whitespace for battery-electric scrubber specifications in temperature-controlled logistics.
- CE marking convergence with ISO 18650:Unified battery safety certification pathways are reducing duplicate testing costs for European market entry.
- Sensor fusion with SLAM navigation:Convergence of lidar and computer vision is opening semi-autonomous retrofit kits for installed walk-behind fleets.
Industry Challenges
- Mechatronics technician scarcity:Robotic scrubber maintenance requires hybrid mechanical-electrical competencies that vocational pipelines in mature markets have not scaled to match deployment rates.
- Legacy fleet integration:Facilities with mixed-vendor installed bases face telemetry protocol incompatibilities that complicate centralized fleet management software rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Floor Scrubber Market |
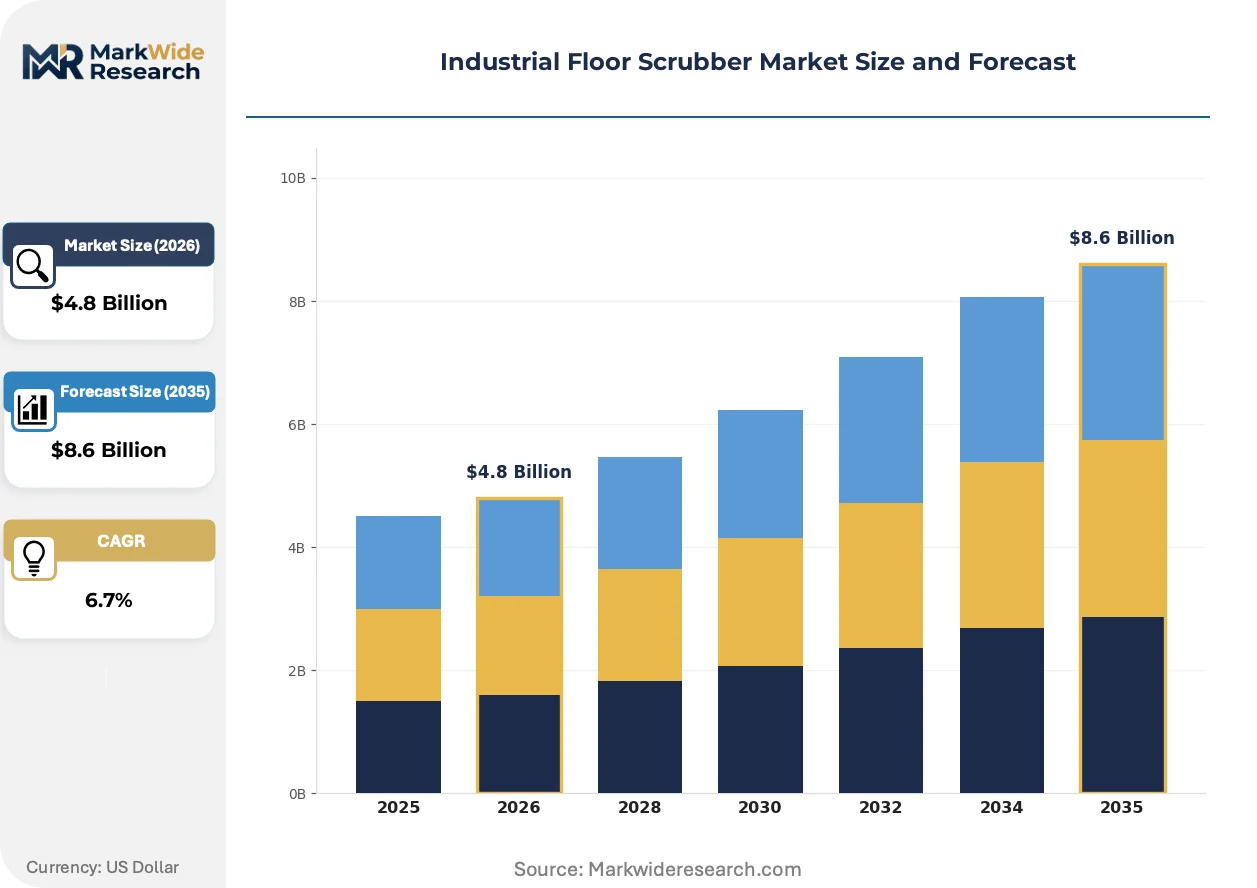
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Rider, Robotic, Combination Technology: Battery-Powered, Electric, Pneumatic, Hydraulic End User: Manufacturing, Warehousing, Retail, Healthcare Size: Compact, Medium, Large, Heavy-Duty |
| Companies Covered | Powerboss, Minuteman, Tennant, Truvox International, Hako, Kärcher, Factory Cat, Advance, Nilfisk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Floor Scrubber Market Strategic Shifts
Equipment intelligence is separating into two performance tiers while regulatory chemistry restrictions and procurement centralization reshape how buyers evaluate total cost of ownership across facility types.
Lithium iron phosphate battery chemistry is bifurcating the powertrain landscape in medium-duty scrubbers. German automotive suppliers and Dutch pharmaceutical distributors are specifying LFP packs for thermal stability in 24/7 operations. This chemistry shift is compressing nickel-manganese-cobalt premium positioning while extending cycle life warranties that alter residual value calculations in fleet financing.
REACH chemical authorization is restricting traditional cleaning solution formulations across European manufacturing and healthcare end users. The regulation is forcing reformulation partnerships between scrubber OEMs and chemical suppliers to maintain cleaning efficacy under tightened surfactant limits. German industrial cleaning standards are tightening fastest, creating specification divergence between EU member states that complicates pan-European fleet standardization.
Facility managers are consolidating vendor relationships through equipment-as-a-service contracts that bundle machines, consumables, and predictive maintenance. Third-party logistics operators in the United States are displacing transactional purchase models with per-square-meter pricing that transfers utilization risk to OEMs. This restructuring is most visible in e-commerce fulfillment networks where seasonal volume spikes demand flexible capacity scaling without capital commitment.
Industrial Floor Scrubber Market Segmentation
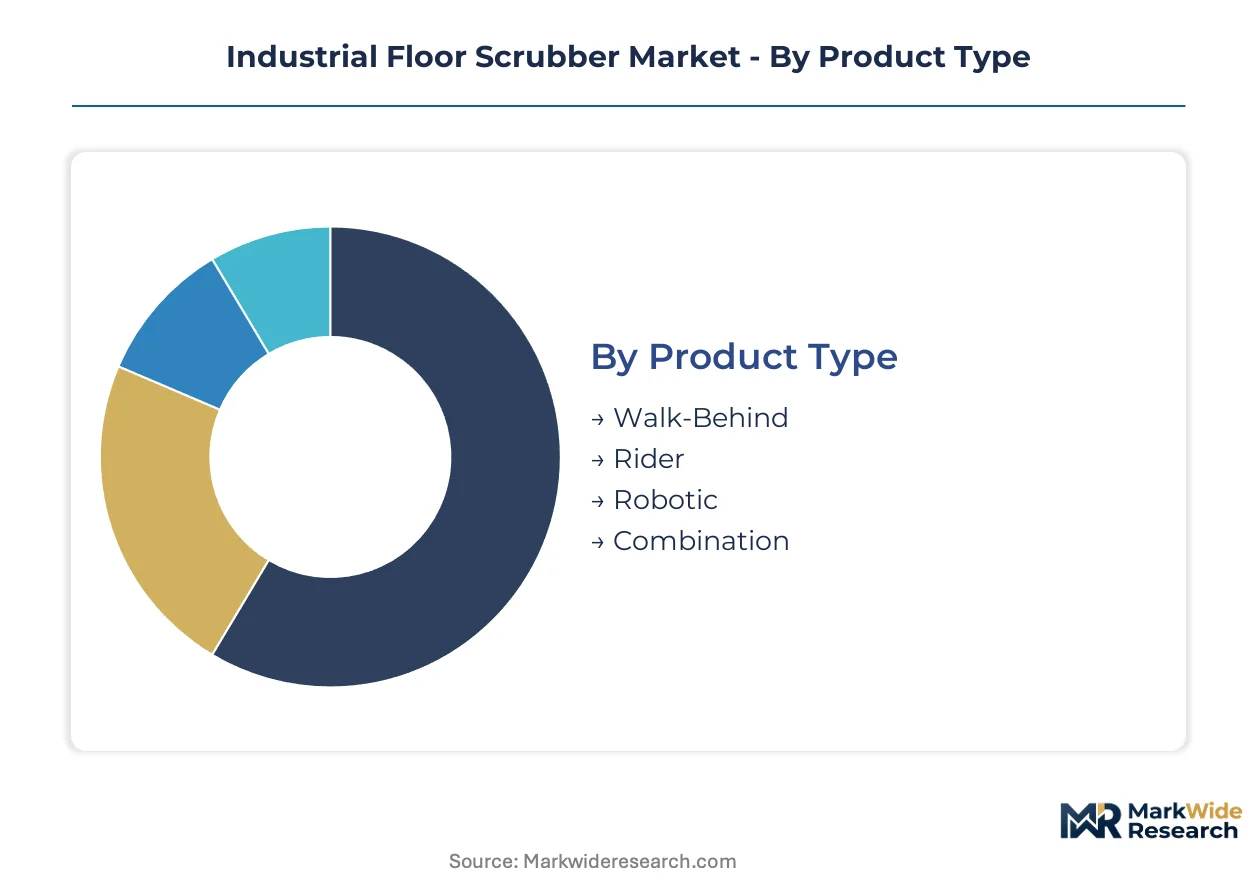
Equipment procurement in the industrial floor scrubber market splits across facility scale, emission mandates, and labor automation economics. Buyers evaluate total cost of ownership through the lens of cleaning protocol intensity and square footage throughput requirements.
Product Type:
EU Green Deal zero-emission corridor rules and OSHA workplace safety standards are creating divergent specification pathways across enclosed facilities versus open manufacturing floors.
- Walk-Behind:Compact units with operator-controlled steering and 20-26 inch cleaning paths dominate retail footprints under 10,000 square feet. German pharmaceutical distributors specify these for narrow corridor maintenance where rider maneuverability fails.
- Rider:Sit-down platforms with 32-40 inch decks and 200+ liter solution tanks handle high-throughput warehousing. Distribution centers in the United States deploy these for single-shift coverage of 100,000+ square foot facilities.
- Robotic:Autonomous navigation with SLAM-based mapping enables overnight operation without labor supervision.
- Combination:Modular attachments switch between scrubbing and sweeping functions for mixed-debris environments.
Rider units handle the majority of throughput; robotic systems are gaining share fastest in large-scale logistics networks.
Technology:
Cost tier differentiation separates premium lithium-ion specifications from legacy powertrain alternatives in fleet replacement cycles.
- Battery-Powered:Lithium iron phosphate packs deliver thermal stability for 24/7 pharmaceutical and automotive operations. Dutch cold chain facilities specify these for enclosed temperature-controlled corridors where propane emissions violate EPA guidelines.
- Electric:Corded mains connection limits mobility but eliminates battery capital expense for fixed-route cleaning.
- Pneumatic:Compressed air systems serve explosion-risk environments in chemical processing plants.
- Hydraulic:Fluid power transmission persists in heavy-duty outdoor applications with extreme debris loads.
Battery-powered configurations dominate new equipment specifications; electric corded units retain niche positioning in budget-constrained municipal procurement.
End User:
Application intensity creates divergent durability and certification requirements across facility types.
- Manufacturing:Heavy grease and metal shaving loads demand cylindrical brush systems with sealed bearings. German automotive suppliers specify IP54-rated machines for welding slag environments.
- Warehousing:High-frequency cleaning of polished concrete drives demand for pad-driver disc systems with quick-change attachments.
- Retail:Aesthetic finish requirements prioritize quiet operation and streak-free squeegee systems for customer-facing hours.
- Healthcare:Infection control protocols mandate sealed battery systems and autoclavable components for operating theater adjacencies.
Warehousing generates the highest equipment volume; healthcare specifications are climbing fastest on regulatory tightening.
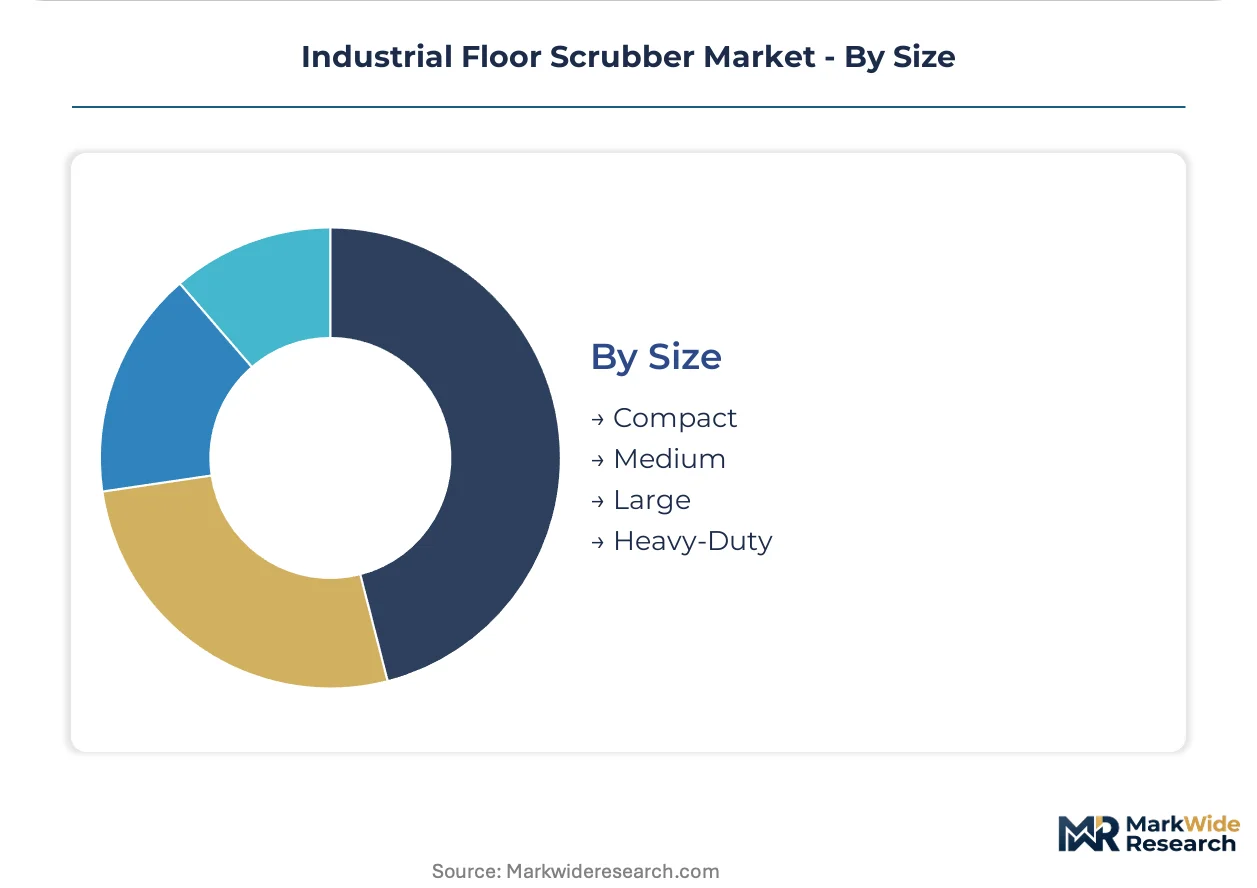
Size:
Customer facility scale determines machine dimensions and brush configuration economics.
- Compact:Sub-20 inch decks navigate retail aisles and elevator-accessible floors in multi-story buildings.
- Medium:20-32 inch platforms balance coverage rate with maneuverability in light manufacturing.
- Large:32-40 inch rider decks serve distribution centers with wide-span racking and minimal obstruction density.
- Heavy-Duty:40+ inch specialized machines handle airport terminals and stadium concourses with extreme daily duty cycles.
Medium-size equipment handles the broadest facility mix; heavy-duty specifications are expanding most quickly in transportation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for industrial floor scrubbers diverges sharply across procurement contexts. German automotive suppliers absorb lithium-ion premiums for thermal stability, while municipal buyers in Southern Europe prioritize capital expenditure minimization over operating cost optimization.
United States
Third-party logistics operators drive volume through equipment-as-a-service contracts that transfer utilization risk to OEMs. OSHA workplace safety standards mandate sealed battery systems in healthcare corridors, stripping propane units from hospital procurement lists. E-commerce fulfillment networks in the Midwest deploy robotic scrubbers for overnight cleaning protocols that eliminate second-shift labor premiums.
Germany
Automotive suppliers and pharmaceutical distributors specify lithium iron phosphate packs for 24/7 thermal stability in enclosed manufacturing hubs. EU Green Deal zero-emission corridor requirements accelerate fleet transitions ahead of neighboring member states. Industrial cleaning standards tighten fastest in Baden-Württemberg, creating specification divergence that complicates pan-European fleet standardization for multi-site operators.
China
Domestic warehousing expansion absorbs mid-size battery-electric units for polished concrete maintenance in distribution centers. Dual carbon goals and GB standards push lithium-ion transitions in state-owned logistics networks. Yangtze River Delta manufacturing clusters specify IP54-rated machines for welding slag environments in automotive supplier parks.
India
PLI scheme incentives for cold chain infrastructure create first-mover whitespace for battery-electric specifications in temperature-controlled logistics. Central warehousing corporation procurement favors medium-size walk-behind units for maneuverability in legacy facility footprints. Maharashtra and Gujarat pharmaceutical hubs adopt sealed battery systems to meet tightening hygiene protocols in export-oriented manufacturing.
Netherlands
Dutch cold chain facilities specify lithium iron phosphate configurations for enclosed temperature-controlled corridors where emissions compliance is non-negotiable. REACH chemical authorization restricts traditional cleaning solution formulations, forcing reformulation partnerships between OEMs and chemical suppliers. Rotterdam port logistics operators consolidate vendor relationships through predictive maintenance bundles that bundle machines with consumables.
Industrial Floor Scrubber Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with autonomous navigation patents sustaining premium positioning for robotics developers while battery pack scale economies favor integrated manufacturers. The market structure splits across three tiers: multinational platform developers with direct service networks, regional specialists with distribution partnerships, and contract fabricators supplying private-label programs. Consolidation pressure concentrates among mid-size European manufacturers facing lithium supply volatility and certification cost inflation. Dominant competitive moves include strategic partnerships for sensor fusion integration and geographic expansion into Indian warehousing through PLI-aligned distribution.
Within the autonomous platform tier, Tennant and Nilfisk exemplify divergent approaches to premium positioning—Tennant leveraging navigation patents for rider scrubber intelligence, Nilfisk anchoring European coverage through owned service infrastructure. Kärcher occupies a position spanning compact and medium-size battery-electric breadth, competing on platform modularity rather than single-segment dominance. These three represent distinct archetypes: patent-protected robotics, service-integrated distribution, and portfolio breadth across facility scales.
| Leading Market Players |
|---|
| Powerboss |
| Minuteman |
| Tennant |
| Truvox International |
| Hako |
| Kärcher |
| Factory Cat |
| Advance |
| Nilfisk |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lithium battery lead times compress OEM working capital cycles and amplify pricing power for cathode material processors in concentrated Asian supply nodes. This inventory intensity forces scrubber manufacturers to pre-position cell stockpiles, embedding carrying costs into equipment quotations while transferring volatility downstream to fleet buyers.
Pricing Analysis
After-sales service contracts and predictive maintenance bundles now drive lifetime value capture beyond equipment margins. Three-tier pricing structure across premium autonomous platforms, standard rider configurations, and economy walk-behind units stratifies procurement tiers. Cost compression in mid-size battery-electric segments intensifies as lithium iron phosphate pack scale economies erode nickel-manganese-cobalt premiums. Municipal buyers in Southern Europe exhibit highest price sensitivity, while German automotive suppliers absorb lithium-ion premiums for thermal stability certification.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for cathode active materials and battery management systems. Lithium processing concentrates in China, South Korea, and Japan, with electrode manufacturing drawing from these nodes. Raw material dependencies span lithium carbonate, nickel sulfate, and copper foil substrates. Single-source vulnerability in cathode precursor supply creates structural risk. Distribution runs through OEM direct service networks and specialized industrial equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as overnight cleaning protocols and EU Green Deal mandates splinter procurement criteria across facility types, creating specialist niches that generalist platforms cannot address uniformly.
For Market Incumbents: Secure autonomous navigation patent portfolios against emerging sensor fusion specialists threatening rider scrubber premium tiers. Deepen backward integration into lithium battery pack assembly to offset cathode material cost volatility. Anchor channel control through predictive maintenance software lock-in that complicates multi-vendor fleet telemetry integration for competitors. For New Entrants and Emerging Players: Anchor in Indian cold chain warehousing expansion where PLI scheme infrastructure buildout outpaces established OEM distribution coverage. Target battery-electric walk-behind specifications for legacy facility footprints under 10,000 square feet where maneuverability constraints cap robotic penetration. Pursue equipment-as-a-service contract structures that transfer utilization risk and differentiate against transactional purchase models. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-size European manufacturers facing REACH compliance cost inflation and lithium supply volatility without scale to absorb certification overhead. Long-term viability centers on autonomous platform developers with installed telemetry bases capable of software monetization. Watch for inflection when autonomous liability frameworks converge across German, Dutch, and US regulatory jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Partnership | Convergence of lidar and computer vision enables semi-autonomous retrofit kits for installed walk-behind fleets. |
| Lithium Battery Backward Integration | In-house pack assembly reduces cathode material cost transmission and secures thermal stability certification pathways. |
| Predictive Maintenance Platform | Telemetry protocol standardization locks fleet managers into recurring revenue streams beyond equipment sales. |
| PLI-Aligned Indian Distribution | Cold chain infrastructure incentives create first-mover whitespace for battery-electric specifications in temperature-controlled logistics. |
| REACH Chemical Reformulation Alliance | OEM-chemical supplier partnerships maintain cleaning efficacy under tightened surfactant limits in German manufacturing hubs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment manufacturer filings, and EU regulatory authorization databases. Maintenance directors at automotive supplier parks, plant engineers in pharmaceutical distribution centers, OEM procurement teams, and aftermarket service heads provided operational validation. Bottom-up equipment shipment tallies triangulate against top-down facility stock estimates across warehousing, healthcare, and manufacturing end uses.
Segmentation dimensions modeled span product type architecture, battery chemistry tier, facility scale category, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and fleet penetration assumptions across the projection horizon. Industry-specific forecast inputs include lithium battery cost curves and autonomous navigation adoption thresholds in large-scale logistics networks.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and lithium supply concentration; material deviation would warrant model refresh. Forecasts reflect embedded assumptions about REACH chemical authorization timelines and OSHA workplace safety standard evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Trim Press Market
Tools
Bandsaw Machines Market
Tools
Tapping Machine Market
Tools
US Hitter Based Hand Tools Market
Tools
Boring-Milling Machines Market
Tools
Reamer Market
Tools
Hand Saw Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Grease Gun Market
Tools
Total Station Market
Tools
Drill Set Market
Tools
Riveting Tools Market
Tools
Fiber Laser Cutting Machines Market
Tools
Portable Heat Press Machine Market
Tools
Spray Painting Machine Market
Tools
Woodworking Sanders Market