
 Stress Test Chamber Market | 2026-2036
Stress Test Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Test Chamber Market Analytics
Multi-source procurement for critical subsystems is restructuring how tier-one chamber buyers manage supplier relationships. ESPEC CORP leverages captive compressor manufacturing to insulate margins from refrigerant supply volatility. Weiss Technik anchors European aerospace certification workflows through proximity to EASA testing hubs. Thermotron Industries competes on turnaround speed for custom thermal shock configurations in U.S. defense subcontracting.
Stress test chambers are enclosed environmental simulation systems that reproduce temperature extremes, humidity gradients, altitude pressure differentials, and mechanical vibration loads to validate product durability before field deployment; typical specifications span negative seventy degrees Celsius to positive one hundred eighty degrees Celsius with humidity control from ten to ninety-eight percent relative humidity. Their primary purpose is accelerating failure-mode discovery in electronics, automotive components, and aerospace assemblies under controlled reproducible conditions. Environmental chambers dominate installed base value due to breadth of cross-industry applicability, while vibration chambers command premium pricing in satellite and avionics qualification. Automated systems with integrated data acquisition are displacing manually operated units in high-throughput quality assurance labs.
NHTSA battery safety protocols, EPA refrigerant phase-down rules under AIM Act provisions, and EU F-Gas Regulation compliance deadlines collectively reshape chamber design requirements and refrigerant selection across manufacturing footprints. ISO 17025 accreditation mandates from national metrology institutes constrain market access for uncertified equipment suppliers in regulated testing environments. Stakeholders must monitor evolving refrigerant chemistries and corresponding retooling cycles as climate regulations tighten.
Market Dynamics
Stringent refrigerant phase-down mandates under the AIM Act and EU F-Gas Regulation are forcing chamber manufacturers to redesign thermal systems around low-GWP alternatives, compressing product development cycles and raising qualification costs for suppliers lacking in-house compressor engineering.
Growth Catalysts
- EV Battery Certification Surge:NHTSA thermal runaway protocols mandate expanded chamber capacity for lithium-ion validation, pulling demand from automotive OEMs and tier-one testing labs.
- REACH-Compliant Material Testing:European chemical safety assessments require environmental stress screening of polymer housings and electronic enclosures, sustaining chamber utilization in ECHA-registered facilities.
- Spacecraft Qualification Intensity:Satellite constellation deployments drive thermal vacuum chamber demand for component outgassing and thermal cycling validation before launch integration.
Market Restraints
- Refrigerant Supply Volatility:HFC quota reductions under Montreal Protocol Kigali Amendment create input cost uncertainty for chamber cooling subsystem producers.
- Specialized Compressor Concentration:German and Japanese captive manufacturers control premium hermetic compressor supply, exposing non-integrated chamber builders to allocation risk.
- Extended ISO 17025 Accreditation Timelines:National metrology institute certification delays constrain new market entrants from accessing regulated aerospace and automotive testing contracts.
Strategic Opportunities
- Indian BIS Certification Expansion:Mandatory IS standards for automotive electronics and medical devices create chamber demand from domestic testing laboratories seeking accreditation.
- Modular Chamber-as-a-Service Models:Leasing structures with embedded maintenance and calibration reduce capital barriers for mid-size contract testing houses.
- Hydrogen Fuel Cell Validation:METI-funded Japanese hydrogen infrastructure programs require specialized explosion-proof environmental chambers for fuel cell stack durability testing.
Industry Challenges
- Thermal Engineering Talent Scarcity:Refrigeration system design expertise concentrates among aging specialists, constraining R&D throughput for next-generation low-GWP chamber architectures.
- Legacy Data Acquisition Integration:Automated chamber control systems face protocol friction when interfacing with established laboratory information management systems in multi-vendor testing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Test Chamber Market |
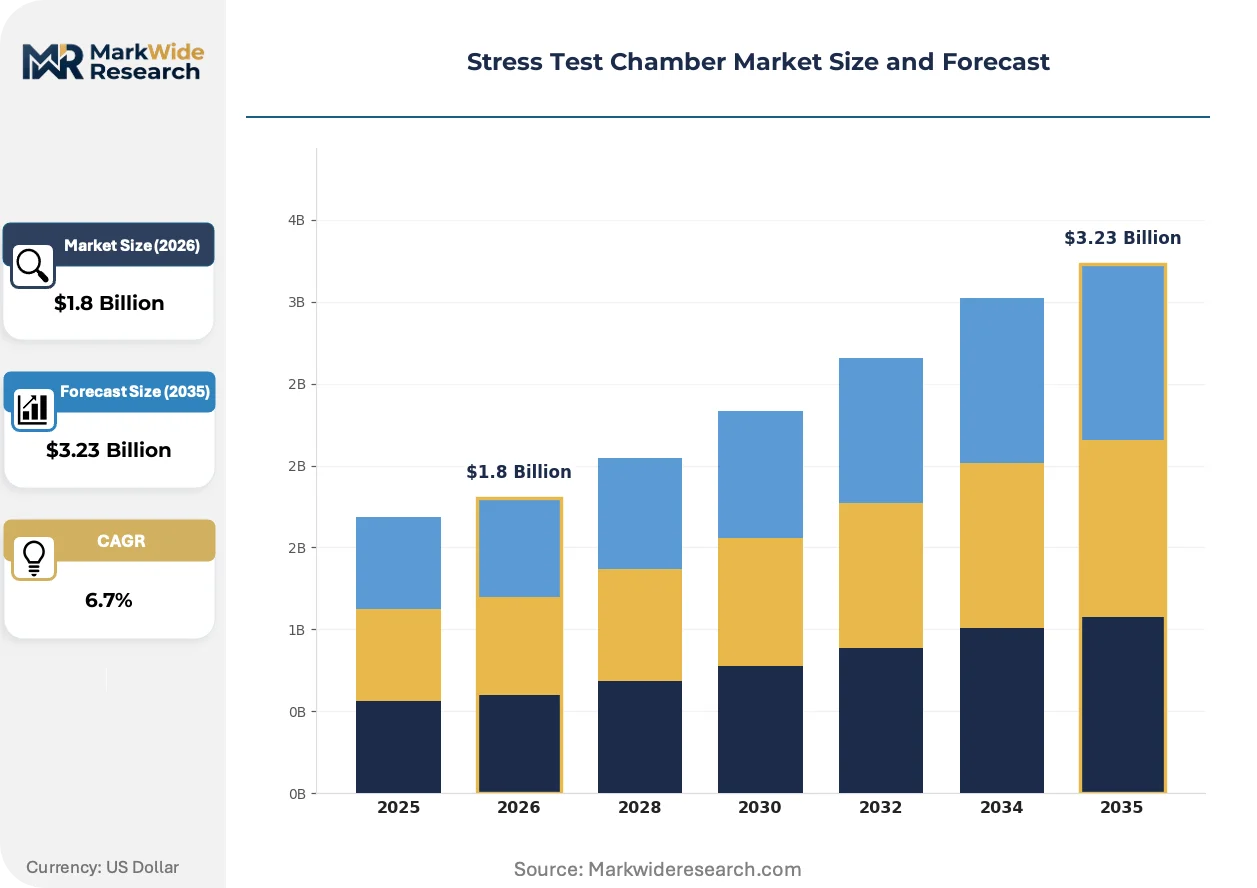
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Environmental Chambers, Thermal Chambers, Altitude Chambers, Vibration Chambers Application: Aerospace Testing, Automotive Testing, Electronics Testing, Material Testing End User: Manufacturers, Research Institutions, Quality Assurance Labs, Government Agencies Technology: Programmable Controllers, Data Acquisition Systems, Software Interfaces, Automated Systems |
| Companies Covered | ESPEC CORP, Weiss Technik, Thermotron Industries, Russells Technical Products, BINDER GmbH, Memmert GmbH + Co. KG, CM Envirosystems, KOMEG Technology Ind Co., Ltd, Angelantoni Test Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Test Chamber Market Evolving Landscape
Digital twin simulation and edge-computing sensor networks are compressing the boundary between physical chamber testing and virtual qualification, reshaping how manufacturers validate designs before committing to full environmental stress campaigns.
Edge-enabled predictive maintenance architectures are decentralizing chamber uptime assurance away from scheduled technician visits. Automotive testing labs in Stuttgart and Detroit deploy vibration-hardened IoT sensors to forecast compressor bearing degradation, shifting maintenance from calendar-based to condition-triggered interventions. This compression of unplanned downtime is extending effective chamber utilization rates without expanding physical fleet capacity.
EPA Significant New Alternatives Policy determinations are accelerating R-454B and R-1234yf adoption across North American chamber manufacturing footprints. The industrial consequence is a bifurcation between legacy R-404A service networks and new low-GWP installation bases, with California Air Resources Board enforcement timelines pulling forward retrofit decisions among West Coast testing facilities.
Consolidated procurement through multi-site framework agreements is compressing vendor negotiation leverage for standalone chamber purchases. Tier-one automotive suppliers in Wolfsburg and Shanghai now mandate centralized sourcing with volume commitments spanning five-year replacement cycles, displacing single-unit transactional relationships that previously dominated mid-market segments.
Stress Test Chamber Market Segmentation
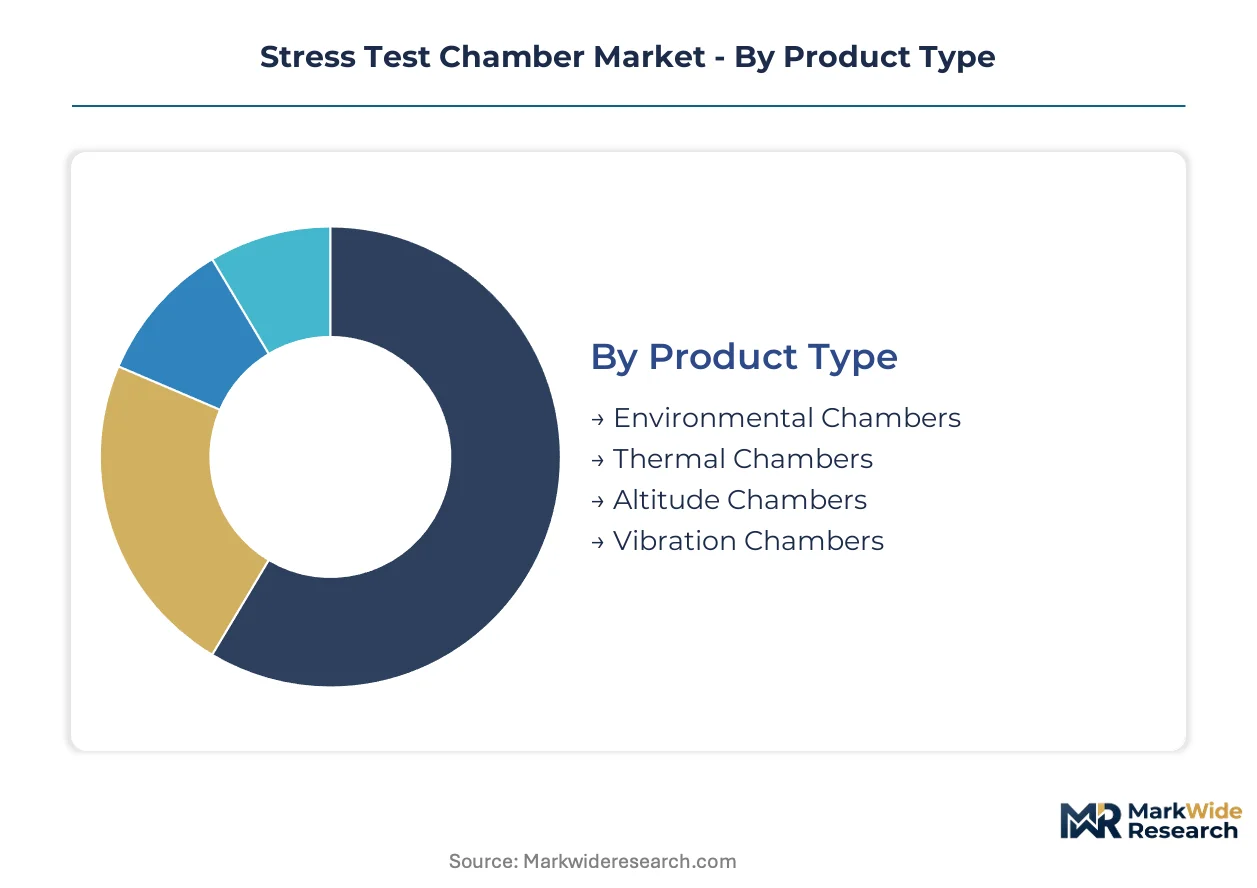
Stress test chamber procurement patterns diverge sharply between high-volume environmental screening and premium-priced specialized validation. Understanding these splits reveals where margin concentration and capacity expansion investments flow.
Product Type:
Environmental chambers dominate installed base volume while vibration and altitude variants capture disproportionate margin.
- Environmental Chambers:Broad-spectrum temperature and humidity simulation from negative seventy to positive one hundred eighty degrees Celsius with ten to ninety-eight percent relative humidity control. Automotive OEMs in Stuttgart and Detroit deploy these for EV battery thermal runaway validation under NHTSA protocols, sustaining the largest procurement volumes across all product categories.
- Vibration Chambers:Mechanical load simulation combined with thermal cycling for structural fatigue assessment. Satellite manufacturers in Toulouse and Denver command premium pricing for these units, driven by EASA and FAA launch qualification mandates for constellation hardware.
- Thermal Chambers:Rapid temperature transition systems for thermal shock testing of electronic assemblies.
- Altitude Chambers:Pressure differential simulation for aerospace and high-altitude electronics validation.
Today's leader: Environmental Chambers. Tomorrow's challenger: Vibration Chambers.
Application:
Automotive testing absorbs the greatest chamber capacity while aerospace applications sustain the highest per-unit pricing.
- Automotive Testing:Battery pack validation, power electronics thermal cycling, and component durability screening under EPA refrigerant phase-down constraints. Chinese EV manufacturers in Shenzhen and Shanghai are expanding chamber procurement fastest to meet domestic certification requirements for exported vehicles.
- Aerospace Testing:Avionics qualification, satellite thermal vacuum cycling, and material outgassing assessment. German aerospace clusters around Munich anchor European demand, with EASA accreditation requirements limiting supplier access.
- Electronics Testing:Semiconductor package validation and PCB reliability screening.
- Material Testing:Polymer aging, composite stress analysis, and REACH-compliant chemical safety assessment.
Automotive testing commands current capacity. Aerospace testing climbs the fastest.
End User:
Quality assurance labs drive replacement cycles while research institutions pioneer advanced simulation requirements.
- Quality Assurance Labs:High-throughput contract testing facilities with ISO 17025 accreditation requirements. Tier-one suppliers in Wolfsburg and Toyota City centralize procurement through multi-site framework agreements, compressing vendor negotiation leverage.
- Manufacturers:Captive testing facilities at automotive OEMs and electronics producers.
- Research Institutions:Universities and national laboratories developing next-generation validation protocols.
- Government Agencies:Defense and space administration qualification facilities with specialized security requirements.
Quality assurance labs anchor present demand. Research institutions shape future specifications.
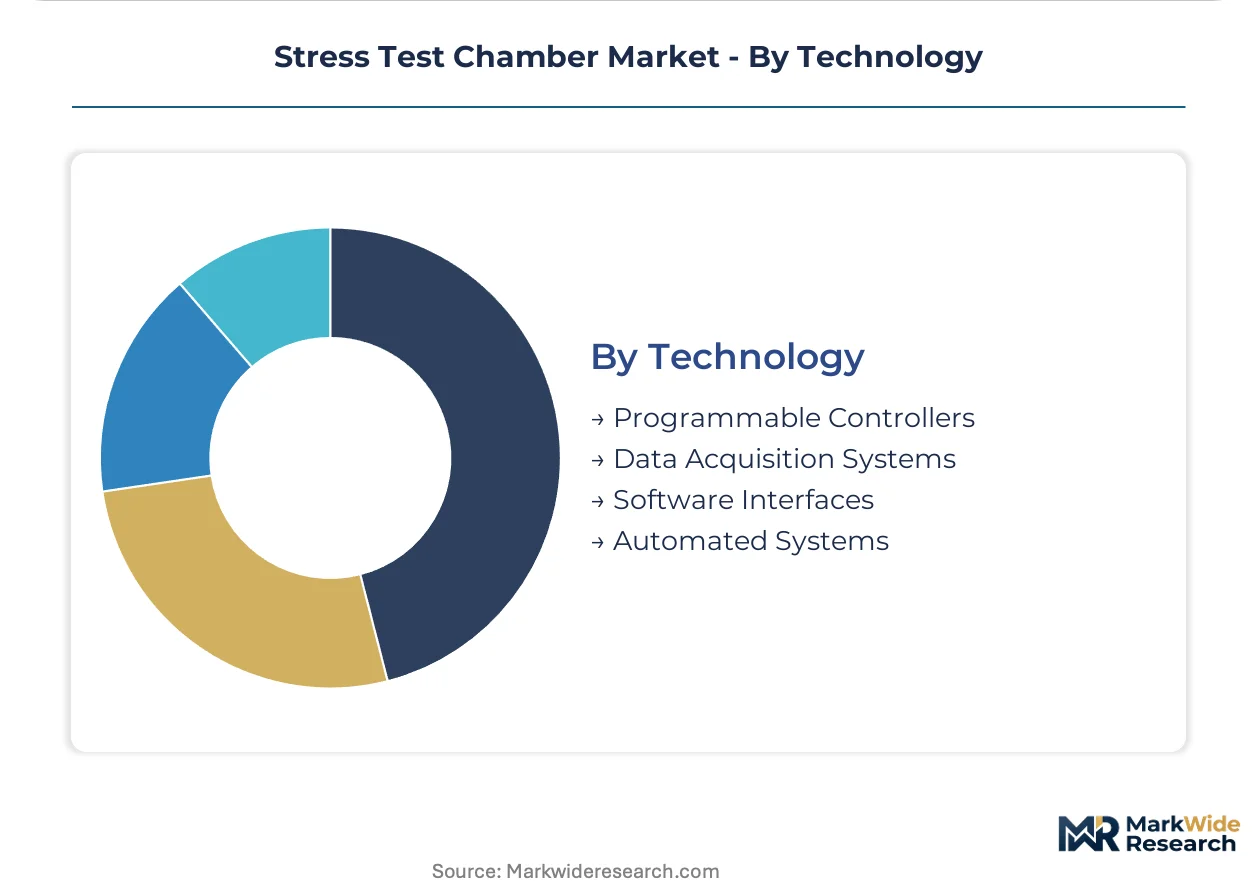
Technology:
Automation intensity separates premium installations from legacy manual systems.
- Automated Systems:Integrated chamber control with robotic sample handling and unattended operation sequences. U.S. defense subcontractors in Huntsville and San Diego prioritize these configurations for throughput and traceability compliance.
- Data Acquisition Systems:Multi-channel sensor logging with laboratory information management system integration.
- Programmable Controllers:Profile-based temperature and humidity sequencing with remote monitoring capability.
- Software Interfaces:Digital twin connectivity and edge-computing predictive maintenance architectures.
Automated systems lead current investment. Software interfaces gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive testing corridor concentrates the highest density of environmental chamber installations worldwide, driven by EV battery validation mandates from German regulators and tier-one supplier captive facilities.
United States
NHTSA thermal runaway protocols and EPA refrigerant phase-down timelines under AIM Act provisions pull demand from Detroit and Huntsville testing clusters. Tier-one automotive suppliers centralize procurement through multi-site framework agreements, compressing vendor negotiation leverage for standalone chamber purchases.
Germany
EASA aerospace certification workflows and REACH-compliant polymer testing sustain chamber utilization across Munich and Hamburg metropolitan zones. KBA vehicle type-approval requirements tighten validation protocols for exported automotive electronics, sustaining premium equipment demand.
China
Domestic EV manufacturer expansion in Shenzhen and Shanghai accelerates chamber procurement to meet GB standards certification for battery exports. MIIT dual carbon goals and SAMR quality enforcement reshape refrigerant selection criteria across manufacturing footprints.
Japan
METI-funded hydrogen infrastructure programs require specialized explosion-proof chambers for fuel cell stack durability testing in Nagoya and Tokyo industrial corridors. JIS standards compliance and aging thermal engineering talent scarcity constrain R&D throughput for next-generation architectures.
India
BIS mandatory IS standards for automotive electronics and medical devices create chamber demand from domestic testing laboratories in Pune and Chennai seeking accreditation. PLI scheme incentives for electronics manufacturing expand quality assurance infrastructure requirements.
Stress Test Chamber Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular service models and hydrogen validation specializations. The vendor base stratifies across captive compressor manufacturers, European aerospace proximity players, and North American defense subcontracting specialists. Three archetypes dominate: integrated thermal system builders, regional certification workflow anchors, and rapid-turnaround custom configurators. Capacity expansion and backward integration into compressor manufacturing represent the dominant competitive moves.
Among Japanese and German fabricators, ESPEC CORP and BINDER GmbH exemplify the integrated thermal system archetype through geographic naming conventions and corporate structure. Weiss Technik occupies a position within the European aerospace certification workflow tier. These named entities anchor industry-level commentary on refrigerant supply management and proximity-based competitive positioning without ascribing specific strategic actions or market share figures.
| Leading Market Players |
|---|
| ESPEC CORP |
| Weiss Technik |
| Thermotron Industries |
| Russells Technical Products |
| BINDER GmbH |
| Memmert GmbH + Co. KG |
| CM Envirosystems |
| KOMEG Technology Ind Co., Ltd |
| Angelantoni Test Technologies |
| Others |
Value Network & Pricing Analysis
Captive compressor manufacturing among Japanese and German fabricators anchors both supply security and pricing power, insulating integrated chamber builders from refrigerant quota volatility under Montreal Protocol Kigali Amendment timelines while compressing margin flexibility for non-integrated assemblers sourcing from third-party thermal subsystem vendors.
Pricing Analysis
Input-cost pass-through from hermetic compressor allocation and low-GWP refrigerant transitions dominates pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels separates EASA-accredited aerospace configurations from automotive validation units and basic environmental screening chambers. Pricing pressure stems from HFC quota reductions forcing thermal system redesigns, with cost compression most acute in mid-market segments lacking backward integration. Contract testing houses in Stuttgart and Detroit exhibit highest price sensitivity due to centralized procurement frameworks, while satellite manufacturers in Toulouse demonstrate lowest sensitivity given launch qualification mandates.
Supply Chain Analysis
ISO 17025 accreditation gating constrains supplier access to regulated aerospace and automotive testing contracts, filtering chamber distribution through certified fabrication networks. Germany, Japan, and the United States anchor hermetic compressor supply, with Chinese fabricators expanding capacity for domestic EV battery validation demand. Copper refrigeration tubing, aluminum heat exchangers, and low-GWP refrigerant chemistries constitute critical input dependencies. Single-source vulnerability concentrates in premium compressor supply controlled by captive manufacturers. Distribution runs through direct OEM relationships for tier-one automotive suppliers and multi-site framework agreements, while mid-market contract labs access equipment through specialized distribution partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between refrigerant transition timelines in North America under EPA AIM Act provisions and slower EU F-Gas Regulation enforcement cycles, creating cost-advantaged manufacturing windows for suppliers with dual-continent footprints.
For Market Incumbents: Hedge refrigerant supply volatility through backward integration into compressor manufacturing or long-term offtake agreements with Japanese and German captive suppliers. Defensive consolidation of thermal engineering talent pools addresses R&D throughput constraints from aging specialist demographics. Priority investment in low-GWP thermal architectures ahead of California Air Resources Board enforcement timelines protects margin position against retrofit cost spikes. For New Entrants and Emerging Players: Mid-size Indian contract testing laboratories seeking BIS accreditation represent an underserved buyer archetype with limited incumbent penetration. White-space targets include modular chamber-as-a-service leasing structures for Pune and Chennai facilities, and specialized explosion-proof configurations for METI-funded hydrogen fuel cell validation programs. Go-to-market execution through embedded calibration and maintenance bundling reduces capital barrier friction. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 17025 accreditation delays constrain new entrant access to regulated testing contracts, favoring acquisition of certified regional players over greenfield certification timelines. Long-term viability centers on refrigerant chemistry adaptability and software-enabled predictive maintenance architectures. Acquisition target archetype: mid-cap European fabricators with EASA proximity and captive thermal engineering capabilities. Signal to watch: EPA Significant New Alternatives Policy determinations accelerating R-454B and R-1234yf adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Insulates margins from HFC quota volatility under Montreal Protocol Kigali Amendment provisions. |
| Low-GWP Thermal Architecture Development | Aligns product portfolios with EPA AIM Act and EU F-Gas Regulation compliance deadlines. |
| Modular Chamber-as-a-Service Launch | Reduces capital barriers for mid-size contract testing houses in India and Southeast Asia. |
| Digital Twin Integration | Compresses validation cycles for automotive OEMs in Stuttgart and Detroit testing corridors. |
| Explosion-Proof Chamber Specialization | Captures METI-funded hydrogen fuel cell stack durability testing demand in Nagoya industrial zone. |
Research Methodology
Bottom-up automotive and aerospace testing facility modeling reconciled against top-down compressor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with chamber procurement directors at tier-one automotive suppliers, quality assurance lab managers, thermal engineering specialists, and refrigerant supply planners combined with secondary validation from NHTSA protocol documentation, EPA AIM Act regulatory filings, EASA certification guidelines, and customs trade data for environmental simulation equipment. Triangulation across stakeholder inputs and secondary sources ensures segment-level precision.
Historical trendline analysis of installed base replacement cycles and refrigerant-driven retooling waves informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user category, automation intensity, and regional regulatory cluster. CAGRs derive from capacity expansion announcements, accreditation pipeline tracking, and thermal engineering talent supply constraints. Industry-specific forecast inputs incorporate EV battery validation protocol evolution and satellite constellation deployment schedules.
Underlying measurement precision varies by segment; automated systems with integrated data acquisition carry tighter precision than legacy manual configurations due to transparent vendor reporting. Forecasts reflect assumptions regarding refrigerant chemistry transition timelines and accreditation throughput at national metrology institutes. Model refresh is warranted upon material change in EPA Significant New Alternatives Policy determinations or Montreal Protocol amendment protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
RF Test Equipment Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Europe Electronic Test and Measurement Market
Test and Measurement
Metrology Systems Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Density Tester Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Digital Multimeter Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Pump Testers Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Shock Testing System Market