
 Global Source Measure Unit Market | 2026-2036
Global Source Measure Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Source Measure Unit Market Outlook
Silicon carbide is consolidating its position in power semiconductor test applications, displacing traditional silicon-based measurement configurations in high-voltage source measure units. Keithley Instruments leverages its legacy in precision DC sourcing to anchor North American R&D demand. Advantest Corporation competes through advanced digital SMU architectures for memory test applications. Yokogawa Electric differentiates via hybrid analog-digital platforms serving automotive power electronics validation.
A source measure unit combines precision voltage sourcing and current measurement in a single instrument, typically achieving resolution below one femtoampere for semiconductor characterization and materials research. The device serves as the fundamental building block for parametric test systems in wafer-level probing and device reliability screening. Power supply segments lead in absolute revenue contribution due to their ubiquity across automotive and aerospace testing workflows, while wireless-enabled SMU architectures represent the fastest-growing technology category as remote monitoring protocols penetrate distributed test environments. Test labs and research institutions command disproportionate margin pools because their procurement cycles prioritize accuracy specifications over unit volume.
FDA oversight of medical device semiconductor components shapes traceability requirements for SMU calibration records in healthcare electronics manufacturing. REACH and RoHS frameworks in Europe restrict hazardous substance content in test equipment assemblies, influencing supplier qualification processes for OEMs serving EU markets. The FCC regulates electromagnetic emissions from wireless-enabled SMU platforms deployed in North American facilities. Stakeholders must weigh calibration standard migration against capital replacement timelines as IEEE and IEC measurement protocols evolve.
Market Dynamics
Silicon carbide power semiconductors are compressing test equipment refresh cycles as automotive electrification and renewable energy storage systems demand higher-voltage characterization capabilities. Wafer fabs in Taiwan and South Korea are expanding parametric test floors to accommodate advanced node complexity.
Growth Catalysts
- EU Chips Act capital redirection:European semiconductor manufacturing subsidies are creating dedicated test equipment procurement streams for SMU vendors qualifying under local content rules.
- Automotive power electronics validation:Electric vehicle inverter and onboard charger programs in Germany and Japan are multiplying high-voltage SMU deployment in tier-one supplier labs.
- FDA medical device traceability:Healthcare electronics manufacturers must maintain calibrated SMU records for implantable semiconductor components, locking in recurring service revenue.
Market Restraints
- Precision analog component supply concentration:Specialized ADC and voltage reference manufacturing concentrates in Japanese and Taiwanese foundries, exposing lead time vulnerability.
- Calibration standard migration costs:IEEE and IEC protocol updates force capital replacement or expensive retrofitting of installed base instruments.
- Wireless test equipment substitution:Modular PXI-based measurement systems are capturing lower-precision applications from benchtop SMU configurations.
Strategic Opportunities
- India PLI scheme fabrication buildout:Domestic semiconductor manufacturing incentives are creating first-mover advantage for SMU vendors establishing local calibration and service infrastructure.
- Wireless-enabled remote monitoring:Distributed test environments in aerospace and satellite manufacturing are adopting networked SMU architectures for unmanned test floor operation.
- Silicon carbide-analog convergence:Hybrid measurement platforms combining wide-bandgap power cycling with femtoampere resolution are opening new materials research applications.
Industry Challenges
- Femtoampere measurement expertise scarcity:Specialized analog design and low-noise shielding engineering talent pools are shallow relative to digital test equipment skill bases.
- Legacy system integration complexity:New SMU platforms must interface with decades-old wafer prober hardware and proprietary software stacks in mature fabs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Source Measure Unit Market |
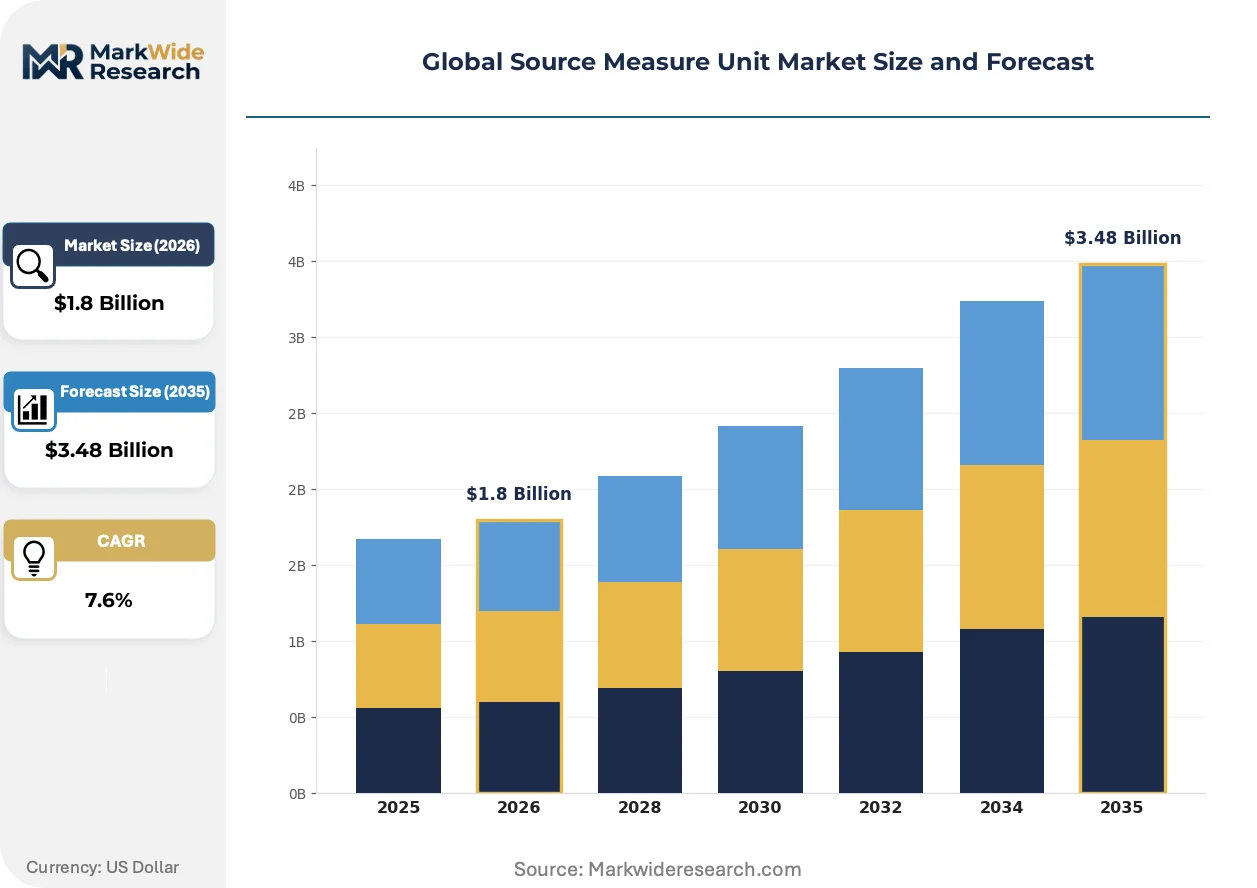
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Multimeter, Programmable Load, Power Supply, Electronic Load End User: OEMs, Test Labs, Research Institutions, Universities Technology: Analog, Digital, Hybrid, Wireless Application: Automotive Testing, Electrical Testing, Aerospace Testing, R&D Testing |
| Companies Covered | Keysight Technologies, Keithley Instruments, Tektronix, Rohde & Schwarz, Chroma ATE, Yokogawa Electric, National Instruments, Advantest Corporation, B&K Precision Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Source Measure Unit Market Strategic Shifts
Measurement architectures are fragmenting between ultra-high-precision analog heritage and digitally-native flexible platforms. Test floor automation and remote diagnostics are compressing the acceptable response time for instrument calibration and failure analysis.
Gallium nitride power stages are absorbing switching frequency demands that silicon-based SMU output stages cannot satisfy. Automotive inverter test labs in Germany and Japan are adopting GaN-equipped units for transient response characterization. This absorption is compressing the performance gap between dedicated power analyzers and general-purpose SMU platforms.
REACH and RoHS substance restrictions are forcing redesign of test equipment assemblies for European market access. ECHA substance of very high concern listings are eliminating specific solder alloys and enclosure plastics from qualified supplier lists. Medical device and automotive SMU vendors are accelerating material certification pipelines to maintain CE marking eligibility.
Service contract unbundling is separating hardware procurement from calibration and application support agreements. Research institutions and university labs are purchasing instruments through capital budgets while sourcing metrology services through operational spending channels. This bifurcation is most pronounced in North American and Western European academic markets where funding source restrictions dictate purchasing flexibility.
Global Source Measure Unit Market Segmentation
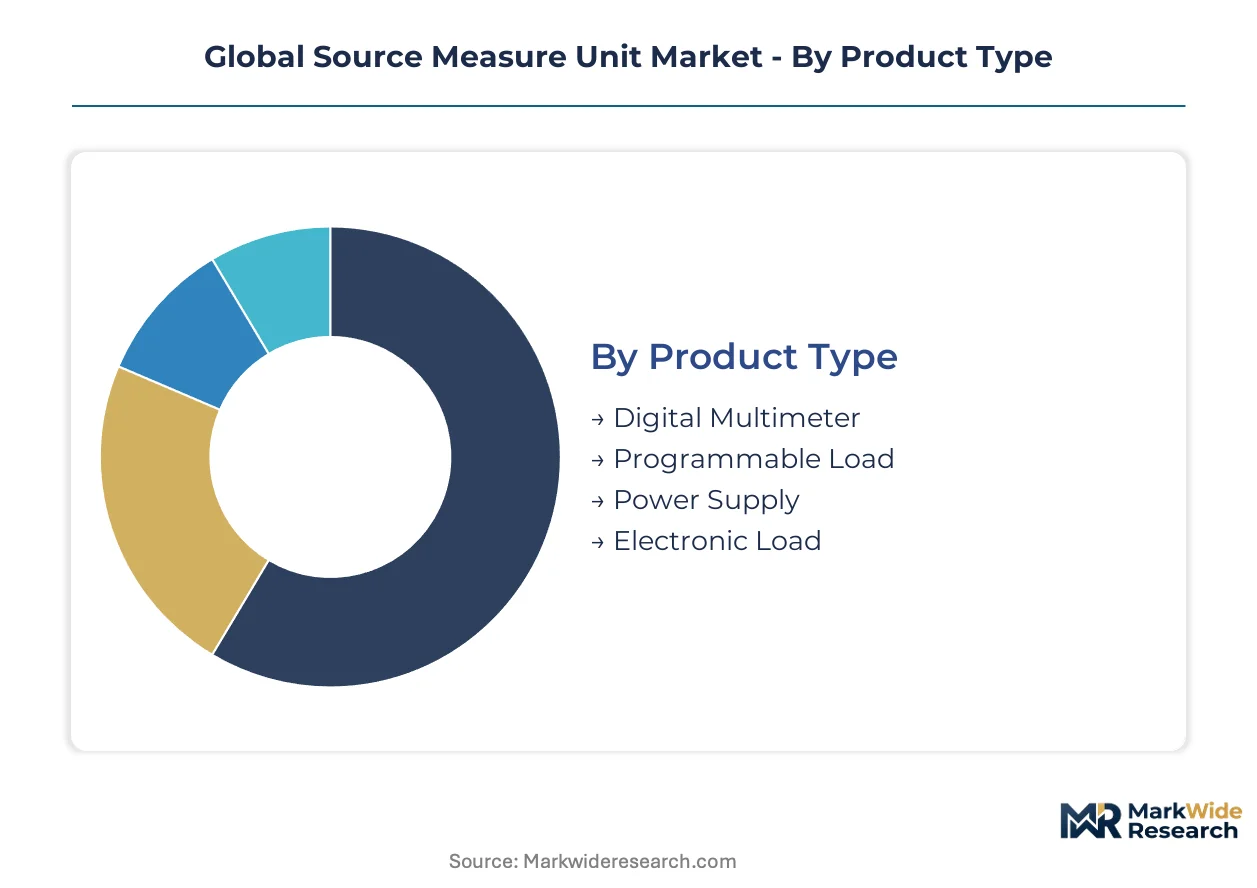
SMU procurement patterns diverge sharply across buyer archetypes. Semiconductor fabs prioritize precision specifications over unit economics, while academic institutions optimize capital allocation against grant funding cycles.
Product Type:
Capital intensity and calibration frequency drive purchase decisions across instrument categories.
- Power Supply:These units deliver precision voltage sourcing with femtoampere measurement resolution for wafer-level parametric testing. Automotive electrification programs in Germany and Japan are expanding high-voltage power supply deployment for inverter validation workflows.
- Digital Multimeter:Benchtop configurations combine sourcing and sensing in compact footprints for distributed test floors. Taiwan and South Korea fabs are refreshing multimeter fleets to accommodate advanced node characterization complexity.
- Programmable Load:Dynamic current sinking capabilities support battery and power supply validation in tier-one automotive supplier labs.
- Electronic Load:High-dissipation architectures serve aerospace power electronics stress testing with extended thermal operating ranges.
Volume sits with power supply configurations; growth tilts toward digital multimeter platforms gaining share in wireless-enabled remote monitoring applications.
End User:
Procurement authority and funding source constraints fragment purchasing behavior across institutional types.
- Test Labs:Commercial validation facilities command premium pricing tolerance due to throughput-dependent revenue models. FDA traceability requirements for medical device semiconductor testing lock in recurring calibration service contracts.
- Research Institutions:National laboratories and corporate R&D centers prioritize measurement accuracy specifications over capital cost in grant-funded procurement cycles.
- OEMs:Integrated device manufacturers and automotive tier-one suppliers balance instrument performance against fleet standardization objectives.
- Universities:Academic labs unbundle hardware purchase from metrology service agreements to navigate capital versus operational budget restrictions.
Margin concentration favors test labs; universities are expanding most quickly as India PLI scheme fabrication buildout drives academic-industry partnership instrumentation.
Technology:
Architecture selection trades heritage analog performance against digital flexibility and connectivity integration.
- Wireless:Networked SMU architectures enable unmanned test floor operation in satellite manufacturing cleanrooms and distributed aerospace facilities. FCC emission regulations in the US and CE marking requirements in Europe constrain radio module certification timelines.
- Hybrid:Analog-digital convergence platforms combine femtoampere resolution with programmable digital interfaces for materials research applications.
- Analog:Heritage architectures maintain installed base dominance in mature wafer fabs with decades-old prober hardware integration requirements.
- Digital:Native digital platforms capture lower-precision applications from modular PXI-based measurement system competition.
Revenue weight remains with analog heritage; wireless platforms are climbing the fastest as remote diagnostics compress acceptable calibration response times.
Application:
End-use voltage and throughput requirements dictate instrument specification thresholds.
- Automotive Testing:Silicon carbide and gallium nitride power semiconductor characterization demands high-voltage sourcing with nanosecond transient response capabilities. REACH and RoHS substance restrictions force equipment redesign for European market access.
- R&D Testing:Materials science and novel device exploration require sub-femtoampere resolution with minimal thermal drift specifications.
- Aerospace Testing:Radiation-hardened component validation and satellite power system qualification drive extended temperature range requirements.
- Electrical Testing:General-purpose component screening and production line go/no-go testing prioritize measurement speed over ultimate precision.
Procurement volume concentrates in automotive testing; R&D testing shows the steepest expansion trajectory as wide-bandgap materials research accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian manufacturing clusters where semiconductor fabrication investment is accelerating. Taiwan and South Korea fabs are expanding parametric test floors for advanced node chips. The EU Chips Act is redirecting capital toward European test equipment supply chains.
United States
FDA oversight of medical device semiconductor components shapes traceability requirements for SMU calibration records in healthcare electronics manufacturing. The FCC regulates electromagnetic emissions from wireless-enabled SMU platforms deployed in North American facilities. Research institutions in Greater Boston and the Pacific Northwest are unbundling hardware procurement from metrology service agreements to navigate funding source restrictions.
Germany
Automotive inverter and onboard charger programs are multiplying high-voltage SMU deployment in tier-one supplier labs. REACH and RoHS frameworks restrict hazardous substance content in test equipment assemblies, influencing supplier qualification processes for OEMs serving EU markets. Bavaria-based automotive power electronics validation centers are adopting GaN-equipped units for transient response characterization.
Japan
Specialized ADC and voltage reference manufacturing concentrates in Japanese foundries, exposing lead time vulnerability for precision analog component supply. METI industrial policy supports domestic test equipment supply chain resilience. Nagoya-area automotive testing clusters are refreshing instrument fleets to accommodate silicon carbide power semiconductor characterization demands.
South Korea
Wafer fabs are expanding parametric test floors to accommodate advanced node complexity driven by memory and logic chip investment. The country's national semiconductor regulator aligns with IEC measurement protocol standards for equipment qualification. Seoul Capital Area manufacturing clusters are prioritizing wireless-enabled SMU architectures for unmanned test floor operation.
India
Domestic semiconductor manufacturing incentives under the PLI scheme are creating first-mover advantage for SMU vendors establishing local calibration and service infrastructure. BIS certification requirements shape equipment qualification timelines for imported test instruments. Karnataka and Gujarat fabrication buildouts are driving academic-industry partnership instrumentation through university labs.
Global Source Measure Unit Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heritage analog instrument makers holding installed base dominance in mature fabs while digitally-native platforms capture lower-precision applications. The vendor base clusters around three strategic archetypes: precision DC sourcing specialists, advanced digital SMU architects, and hybrid analog-digital platform providers. Consolidation pressure is intensifying through technology licensing agreements and strategic partnerships for wireless module certification. Geographic expansion into India PLI scheme corridors represents the dominant competitive move alongside portfolio diversification into silicon carbide test applications.
Within the heritage precision tier, Keithley Instruments and Advantest Corporation exemplify divergent architectural philosophies. Keithley anchors North American R&D demand through its legacy in femtoampere-resolution DC sourcing. Advantest occupies a position among memory test application specialists competing through advanced digital SMU architectures. Yokogawa Electric sits within the hybrid analog-digital convergence space, serving automotive power electronics validation workflows in Germany and Japan. These three represent the competitive fault lines between analog heritage and digital flexibility that are reshaping procurement patterns across test labs and research institutions.
| Leading Market Players |
|---|
| Keysight Technologies |
| Keithley Instruments |
| Tektronix |
| Rohde & Schwarz |
| Chroma ATE |
| Yokogawa Electric |
| National Instruments |
| Advantest Corporation |
| B&K Precision Corporation |
| Others |
Value Chain & Pricing Dynamics
Automotive electrification mandates in Germany and Japan are compressing procurement timelines for high-voltage characterization equipment, forcing suppliers to absorb expedited manufacturing costs while fabs in Taiwan and South Korea lock in multi-year calibration service contracts. This demand-side urgency concentrates pricing power with heritage analog instrument makers holding femtoampere-resolution capabilities.
Pricing Analysis
Volume concentrates in power supply configurations serving tier-one automotive supplier labs, while margin pools accrue to hybrid analog-digital platforms for silicon carbide validation. Pricing stratifies across precision tiers defined by measurement resolution specifications and FDA traceability certification levels. Cost compression in standard-grade benchtop units intensifies as modular PXI-based systems capture lower-precision applications. Universities exhibit highest price sensitivity due to capital budget restrictions, whereas test labs prioritize accuracy specifications over unit economics.
Supply Chain Analysis
Refurbishment flows for decade-old wafer prober hardware extend instrument lifecycles in mature fabs, creating secondary markets that compete with new equipment procurement. Precision ADC and voltage reference manufacturing concentrates in Japan and Taiwan, exposing lead time vulnerability for specialized analog components. Supply chain risk centers on single-source dependency for femtoampere-grade shielding materials and low-noise voltage references. Distribution runs through direct OEM relationships with semiconductor fabs and tier-one automotive suppliers, supplemented by regional service partnerships for calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as silicon carbide and gallium nitride power semiconductors displace silicon-based measurement configurations, rendering legacy voltage sourcing architectures obsolete for automotive electrification applications.
For Market Incumbents: Acquire femtoampere-resolution analog design talent pools to defend against digitally-native platform encroachment. Consolidate calibration service infrastructure in India PLI scheme corridors before local content rules harden. Backward integration into specialized voltage reference manufacturing reduces exposure to Japanese and Taiwanese foundry concentration. For New Entrants and Emerging Players: Wireless-enabled remote monitoring architectures offer technology-first entry points into satellite manufacturing cleanrooms and distributed aerospace facilities. White-space concentrates in academic-industry partnership instrumentation driven by Karnataka and Gujarat fabrication buildouts. GaN-equipped transient response characterization units for automotive inverter test labs represent the most penetrable application wedge. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid analog-digital platform specialists given silicon carbide-analog convergence catalysts accelerating materials research applications. Long-term viability favors vendors combining femtoampere heritage with programmable digital interfaces. Monitor IEEE and IEC protocol update timelines for inflection signals on capital replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Module Certification Investment | FCC and CE marking compliance unlocks unmanned test floor deployment in US and European aerospace facilities. |
| India Calibration Infrastructure Buildout | BIS certification readiness captures PLI scheme procurement streams before local content rules mature. |
| Silicon Carbide Test Application Diversification | High-voltage characterization capabilities align with automotive inverter validation demand in Germany and Japan. |
| Service Contract Unbundling | Separate hardware and metrology agreements match university capital versus operational budget restrictions. |
| GaN Output Stage Integration | Transient response specifications satisfy automotive power electronics validation requirements compressing analyzer-SMU performance gaps. |
Study Parameters
Multi-period observation of wafer fab capital expenditure patterns and automotive electrification program timelines anchored the trend analysis, supplemented by interviews with parametric test floor managers, precision analog design engineers, semiconductor equipment procurement leads, and calibration service directors. Secondary validation drew from SEC equipment supplier filings, IEC measurement protocol documentation, EU Chips Act implementation reports, and India PLI scheme disbursement records. Bottom-up instrument shipment tracking triangulated against top-down semiconductor fabrication investment forecasts.
Input-output matrices mapped sourcing voltage ranges and measurement resolution specifications to end-use applications across the projection horizon. Segmentation dimensions modeled include instrument architecture type, precision tier, end-user institutional category, and geographic manufacturing cluster. CAGRs derived from equipment refresh cycle compression rates and protocol migration timelines. Forecast inputs incorporated silicon carbide power semiconductor adoption curves and wireless-enabled test floor penetration assumptions.
Several conditions sit outside the modeled scope, including unforeseen IEEE protocol revision scope, acute precision analog component supply disruptions, and automotive OEM insolvency cascades. Practitioners should monitor EU Chips Act local content rule enforcement and India BIS certification timeline acceleration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Humidity Testers Market
Test and Measurement
Global NVH Testing Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Tribometer Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Ultrasonic Wall Thickness Gauges Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Calibration Services Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market