
 In-Process Composite Layup Monitoring Sensors and Test Equipment Market | 2026-2036
In-Process Composite Layup Monitoring Sensors and Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
In-Process Composite Layup Monitoring Sensors and Test Equipment Market Insights
Germany is narrowing the gap between manual inspection and fully automated in-process monitoring across its aerospace manufacturing corridor. Virtek Vision International leverages its laser projection and vision systems to dominate ply alignment verification for automated fiber placement. LAP GmbH sustains its position through precision laser measurement tailored to wind turbine blade production lines. Hexagon AB extends its metrology portfolio into composite-specific inspection workflows, competing on software integration with hardware platforms.
In-process composite layup monitoring sensors and test equipment encompass real-time sensing systems that track fiber orientation, resin flow, void formation, and cure kinetics during automated or manual composite manufacturing, typically operating at spatial resolutions below one millimeter and temporal sampling rates exceeding ten hertz to enable immediate process correction. These systems serve primarily to eliminate post-cure nondestructive testing bottlenecks and reduce material scrap in high-performance composite structures. Optical sensors and laser scanning technology capture the largest installed base due to maturity in ply mapping applications, while dielectric analysis represents the fastest-growing segment as manufacturers embed capacitive sensors directly into tooling for through-thickness cure monitoring. Fiber optic sensors attract concentrated R&D investment from Tier-1 suppliers seeking distributed strain and temperature data across complex geometries.
FAA airworthiness standards for composite primary structures mandate traceable manufacturing records, pushing OEMs toward sensor-based process verification rather than batch sampling. EASA's continuing adoption of ASTM standards for automated fiber placement reinforces harmonized equipment requirements across European aerospace supply chains. ISO 19001 quality management frameworks increasingly specify in-process monitoring as a prerequisite for supplier qualification in automotive and wind energy applications. Stakeholders must weigh capital intensity against scrap reduction gains when selecting between retrofit sensor packages and integrated new-build systems.
Market Dynamics
Aerospace OEMs are automating fiber placement and cure monitoring to compress scrap rates and satisfy FAA airworthiness documentation requirements for composite primary structures. This structural pull toward sensor-based process verification is reshaping capital allocation across high-performance manufacturing.
Growth Catalysts
- EU Green Deal mandates:Lighter transport materials requirements accelerate real-time quality verification in automotive and aerospace supply chains across Germany and France.
- Automated fiber placement:Wind turbine blade manufacturers embed dielectric sensors directly into tooling for through-thickness cure monitoring, eliminating post-cure inspection bottlenecks.
- Bavaria-Hamburg corridor:Germany's concentrated aerospace manufacturing cluster drives concentrated demand for laser-based ply alignment systems.
Market Restraints
- Capital intensity:Integrated new-build sensor systems require substantial upfront investment compared to retrofit packages, slowing adoption among mid-tier suppliers.
- Optical sensor maturity:Established laser scanning technology for ply mapping creates switching friction against emerging dielectric and fiber optic alternatives.
- Temporal sampling requirements:Equipment must exceed ten hertz sampling rates for immediate process correction, raising hardware complexity and validation costs.
Strategic Opportunities
- EASA-ASTM harmonization:Standardized equipment requirements across European aerospace supply chains reduce vendor qualification friction for compliant sensor platforms.
- Fiber optic convergence:Distributed strain and temperature sensing across complex geometries attracts concentrated R&D investment from Tier-1 suppliers seeking differentiation.
- Automotive qualification:ISO 19001 quality frameworks increasingly specify in-process monitoring for supplier qualification, opening adjacent verticals beyond aerospace.
Industry Challenges
- Spatial resolution demands:Sub-millimeter accuracy requirements for fiber orientation tracking strain calibration protocols and operator training programs.
- Legacy system integration:Retrofit sensor packages must interface with existing automated fiber placement equipment without disrupting production line throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Process Composite Layup Monitoring Sensors and Test Equipment Market |
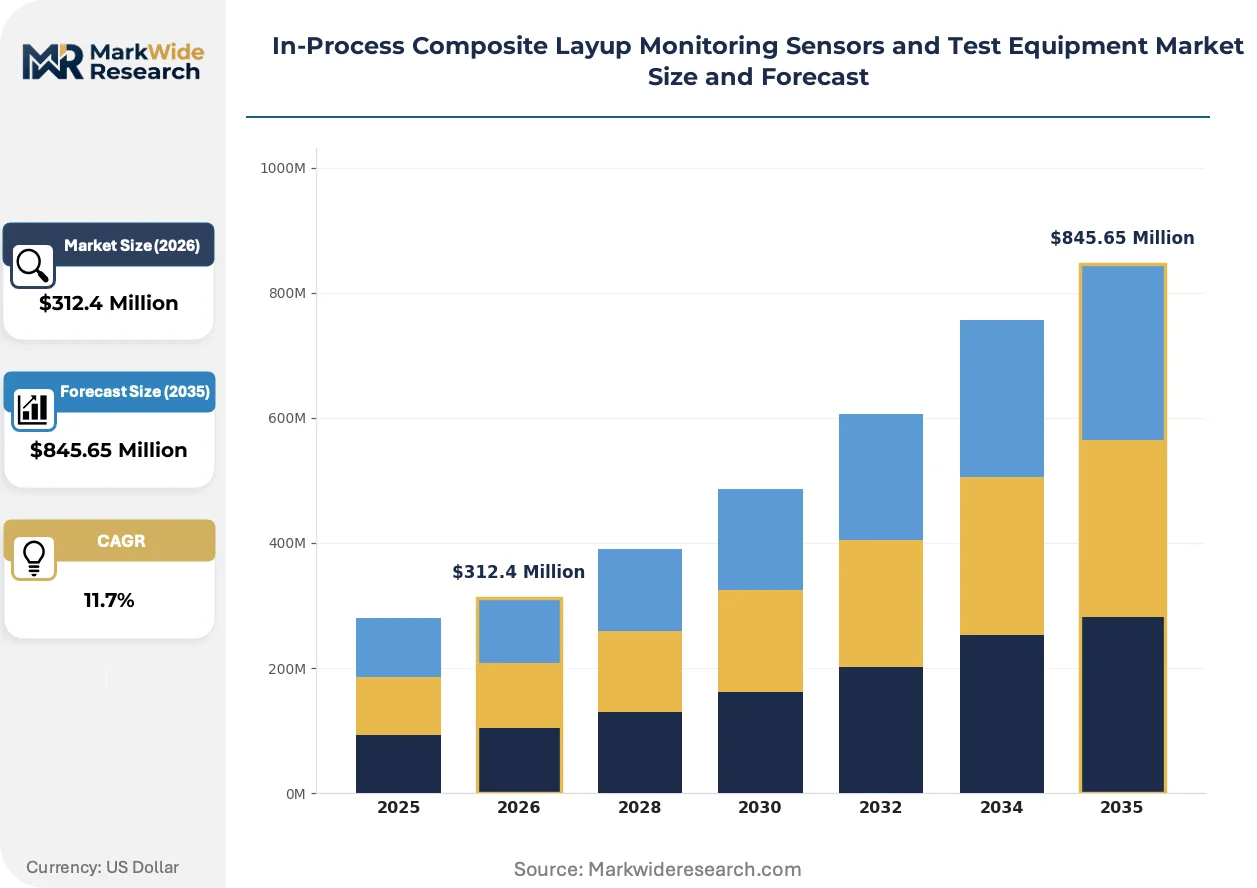
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Optical Sensors, Thermal Sensors, Pressure Sensors, Fiber Optic Sensors Technology: Acoustic Emission, Digital Image Correlation, Infrared Thermography, Laser Scanning, Dielectric Analysis Application: Aerospace, Marine Vessels, Sporting Goods, Wind Energy, Construction Materials End User: OEMs, Tier-1 Suppliers, Quality Assurance Labs, Research Institutions |
| Companies Covered | Virtek Vision International, LAP GmbH, FARO Technologies, Electroimpact, Hexagon AB, ZEISS, Renishaw, Keyence, National Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Process Composite Layup Monitoring Sensors and Test Equipment Market Trends and Innovations
Real-time sensing architectures are migrating from post-process inspection stations onto the production line itself. This shift compresses feedback loops and redefines quality assurance from batch sampling to continuous verification.
Dielectric analysis is collapsing the distinction between cure monitoring and structural validation by embedding capacitive sensors directly into composite tooling. Aerospace manufacturers in Germany and the United States are adopting this approach for primary structure production. The technology is collapsing capital requirements for separate thermal validation equipment while accelerating production cycle times.
REACH compliance deadlines for hazardous substance restrictions in manufacturing equipment are accelerating sensor material substitutions in European supply chains. Equipment vendors must reformulate sensor housings and conductive elements to satisfy substance transparency requirements. Wind energy OEMs in Denmark and Spain face compressed certification timelines as they retrofit existing lines with compliant monitoring hardware.
Service unbundling is fragmenting traditional equipment procurement into sensor hardware, analytics software, and calibration service components. Tier-1 aerospace suppliers now source dielectric sensors from specialized vendors while retaining data analytics in-house. This pattern is most visible in Germany's aerospace corridor, where LAP GmbH and Virtek Vision International compete on modular platform architectures rather than integrated system bundles.
In-Process Composite Layup Monitoring Sensors and Test Equipment Market Segmentation
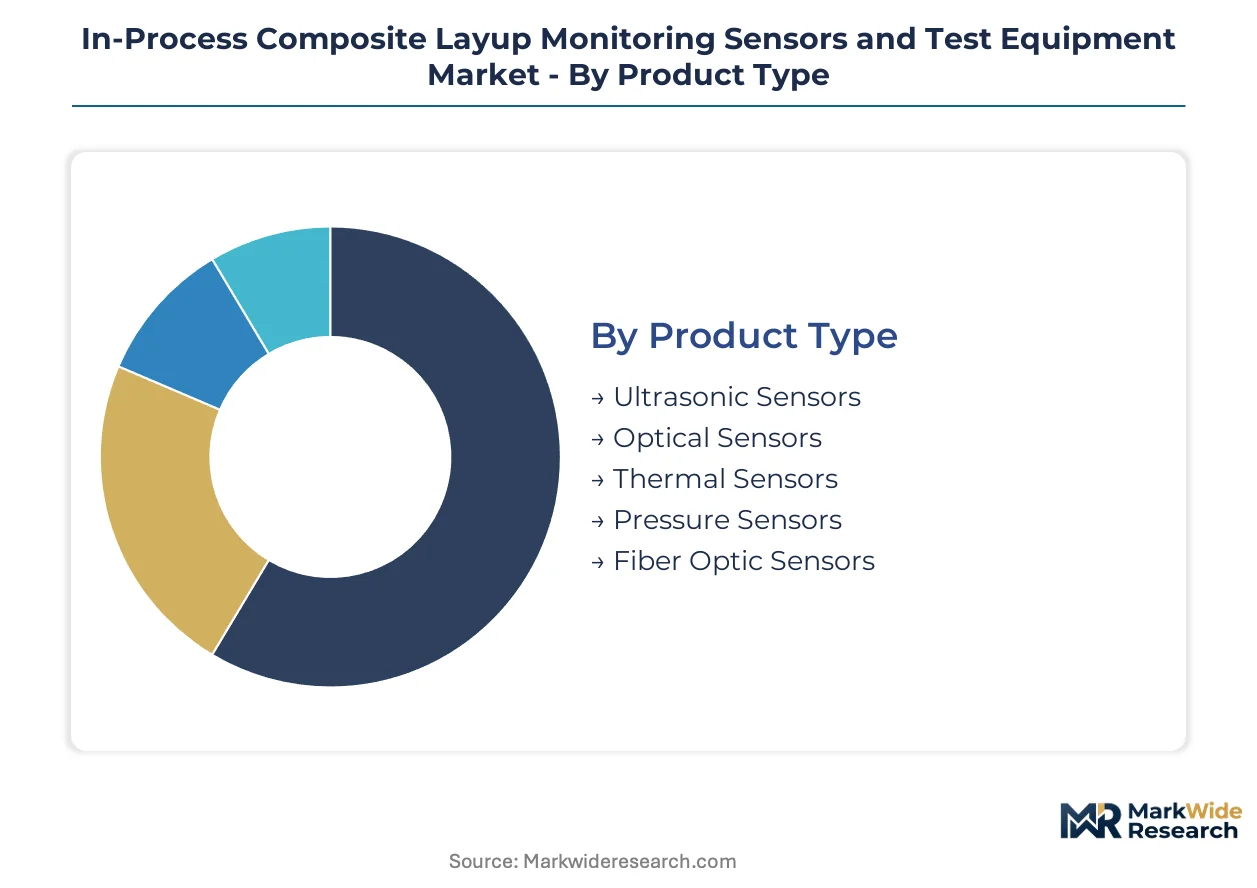
Technology maturity and application specificity determine equipment selection in composite manufacturing. Segmentation reveals where capital concentrates and which sensing modalities are displacing legacy inspection methods.
Product Type:
Mature optical and ultrasonic platforms dominate installed base volumes while fiber optic architectures attract development investment for distributed sensing applications.
- Ultrasonic Sensors:Piezoelectric transducers operating at 1-10 MHz frequencies detect void formation and delamination through thickness. Aerospace OEMs in Germany specify these for primary structure validation where FAA traceability requirements mandate documented defect detection.
- Optical Sensors:CCD and CMOS-based vision systems capture ply orientation at sub-millimeter resolution. These handle the majority of automated fiber placement verification across Bavaria and Hamburg manufacturing corridors, constrained by line-of-sight requirements on complex tool geometries.
- Thermal Sensors:Infrared arrays monitor exothermic cure reactions in real-time. Wind turbine blade producers embed these for through-thickness temperature mapping.
- Pressure Sensors:Piezoresistive elements track vacuum bag consolidation forces. Marine vessel manufacturers deploy these for large-contour hull sections where resin flow uniformity determines structural performance.
- Fiber Optic Sensors:Distributed strain and temperature sensing via embedded Bragg gratings. Tier-1 suppliers are climbing the fastest on share as they seek geometrically flexible alternatives to point-measurement systems.
Optical sensors handle the majority of throughput; fiber optic sensors are the fastest mover on share.
Technology:
Cost tier separates established metrology methods from emerging embedded sensing platforms requiring extensive calibration protocols.
- Acoustic Emission:Piezoelectric sensors detect stress-wave emissions from fiber breakage and matrix cracking. These serve quality assurance labs performing failure analysis on returned components.
- Digital Image Correlation:Stereo camera arrays track full-field deformation patterns. Research institutions deploy these for material characterization studies preceding production qualification.
- Infrared Thermography:Thermal cameras visualize heat distribution during cure cycles. Construction materials manufacturers favor these for large-format panel production where point sensors prove inadequate.
- Laser Scanning:Structured light and time-of-flight systems map ply boundaries. This technology commands the premium tier in aerospace applications where EASA-ASTM harmonization mandates specific measurement uncertainty budgets.
- Dielectric Analysis:Capacitive sensors embedded in tooling monitor ionic conductivity changes during cure. The steepest expansion trajectory belongs here as automated fiber placement lines integrate cure validation directly into production tooling.
Laser scanning captures the highest equipment margins; dielectric analysis is expanding most quickly into new-build system specifications.
Application:
Customer type and certification burden segment demand intensity across end-use verticals.
- Aerospace:Primary structure manufacturing drives the most stringent sensor specifications. FAA airworthiness documentation requirements push OEMs toward continuous process verification rather than batch sampling.
- Marine Vessels:Large-contour hull sections require distributed sensing arrays. Shipyards in Northern Europe specify retrofit sensor packages compatible with existing infusion equipment.
- Sporting Goods:High-volume bat and racket production prioritizes throughput over traceability. Tier-1 suppliers here favor low-cost optical alignment systems.
- Wind Energy:Blade manufacturers embed dielectric sensors directly into tooling for through-thickness cure monitoring. EU Green Deal mandates for lighter transport materials accelerate real-time quality verification investments.
- Construction Materials:Prefabricated composite panels for infrastructure applications. ISO 19001 frameworks increasingly specify in-process monitoring for supplier qualification in this segment.
Aerospace commands the highest equipment specification density; wind energy is gaining share fastest as blade dimensions expand beyond manual inspection feasibility.
End User:
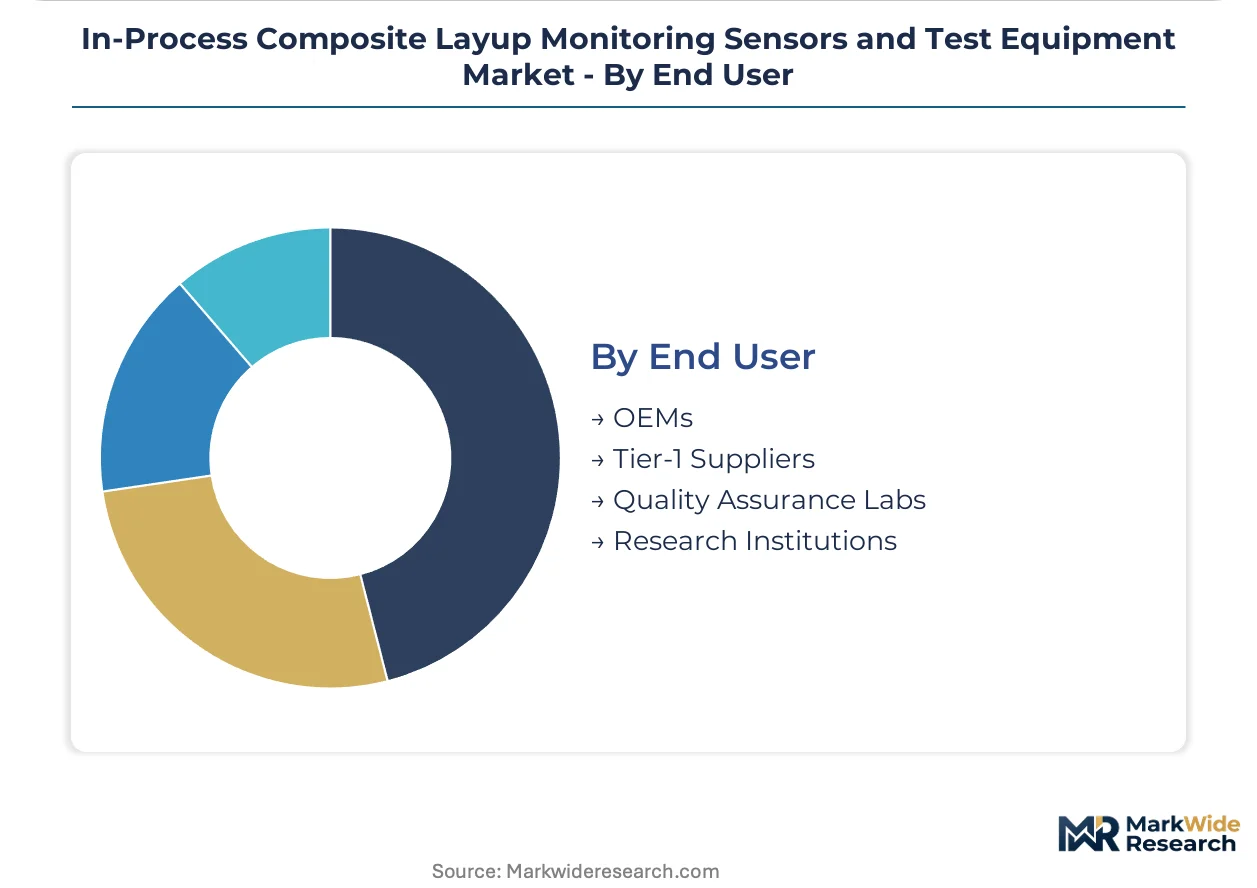
Integration depth and data ownership preferences separate procurement patterns across the value chain.
- OEMs:Vertical aircraft and wind turbine manufacturers specify integrated new-build systems. These buyers retain analytics in-house while sourcing modular sensor hardware from specialized vendors.
- Tier-1 Suppliers:Subcontracted component producers face capital constraints favoring retrofit packages. Service unbundling allows these users to acquire sensors separately from calibration and software subscriptions.
- Quality Assurance Labs:Independent testing facilities require portable equipment serving multiple manufacturing clients. Acoustic emission and digital image correlation systems concentrate here.
- Research Institutions:Universities and national laboratories drive early-stage technology validation. Fiber optic sensing architectures receive concentrated R&D investment from this user category.
OEMs direct the largest capital commitments; tier-1 suppliers are the fastest adopter category as modular platform architectures reduce qualification friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness documentation requirements anchor the United States as the primary demand center for in-process composite monitoring equipment, with EASA-ASTM harmonization extending standardized equipment specifications across European aerospace supply chains.
United States
Boeing and Lockheed Martin automate fiber placement lines to satisfy FAA traceability mandates for composite primary structures. The FAA's continued enforcement of airworthiness standards for bonded joints pushes OEMs toward sensor-based process verification. Seattle-Tacoma and Charleston manufacturing corridors concentrate demand for laser-based ply alignment systems from specialized equipment vendors.
Germany
Airbus operations in Hamburg and Bavaria drive concentrated procurement of dielectric sensors embedded directly into production tooling. EASA adoption of ASTM standards for automated fiber placement reduces vendor qualification friction across German aerospace supply chains. The Munich-Stade manufacturing corridor hosts the densest cluster of composites research centers and Tier-1 aerostructures suppliers in Europe.
China
COMAC's C919 production ramp and wind turbine blade exports accelerate real-time quality verification investments. MIIT guidelines for advanced manufacturing equipment increasingly reference in-process monitoring for supplier qualification in aviation applications. The Yangtze River Delta cluster around Shanghai concentrates domestic sensor system integrators serving both aerospace and renewable energy OEMs.
France
Airbus Toulouse and Safran operations mandate continuous process verification for composite fan blades and nacelle structures. ANSM oversight of manufacturing equipment materials interacts with REACH substance transparency requirements for sensor housings. The Occitanie aerospace cluster drives demand for modular platform architectures that unbundle hardware from analytics software.
Japan
Toray and Mitsubishi Heavy Industries embed fiber optic sensors for distributed strain monitoring in satellite and aircraft primary structures. METI funding for next-generation manufacturing technology accelerates R&D investment in geometrically flexible sensing alternatives to point-measurement systems. The Nagoya aerospace cluster concentrates precision equipment procurement from domestic metrology specialists.
In-Process Composite Layup Monitoring Sensors and Test Equipment Market Competitive Landscape
Laser projection specialists and precision metrology conglomerates split the market between application-specific depth and platform breadth. Equipment vendors cluster into three strategic archetypes: vision-system purists competing on ply-mapping accuracy, diversified metrology houses leveraging software integration, and embedded-sensor developers monetizing through-thickness cure data. Consolidation pressure intensifies as Tier-1 suppliers unbundle procurement into discrete hardware, analytics, and calibration components. Geographic expansion and technology licensing dominate competitive moves as vendors seek EASA-ASTM qualification across multiple regulatory jurisdictions.
Among Germany-based precision equipment fabricators, LAP GmbH and Virtek Vision International exemplify the vision-system archetype through laser projection and alignment verification platforms. Hexagon AB occupies a position bridging metrology hardware with composite-specific inspection workflows. These three anchors illustrate how modular platform architectures are displacing integrated system bundles across European aerospace supply chains.
| Leading Market Players |
|---|
| Virtek Vision International |
| LAP GmbH |
| FARO Technologies |
| Electroimpact |
| Hexagon AB |
| ZEISS |
| Renishaw |
| Keyence |
| National Instruments |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main freight corridor channels precision sensor components from Bavarian fabrication centers to Hamburg aerospace assembly lines, with logistics cost differentials between integrated new-build systems and modular retrofit packages widening price spreads across European supply chains. This transport-cost wedge reinforces tiered equipment procurement patterns as OEMs absorb premium pricing for embedded dielectric platforms while Tier-1 suppliers negotiate volume discounts on laser alignment hardware.
Pricing Analysis
German equipment commands price premiums over Asian alternatives, with laser scanning systems from Bavaria-Hamburg corridor manufacturers carrying certification-grade markups against lower-tier optical sensors sourced through Shanghai distributors. Pricing stratifies across premium, standard, and economy tiers based on FAA traceability documentation and EASA-ASTM harmonization compliance, with dielectric analysis platforms facing margin compression from embedded-sensor commoditization. Tier-1 suppliers exhibit highest price sensitivity due to capital constraints favoring unbundled procurement of sensor hardware separate from analytics subscriptions.
Supply Chain Analysis
Export-control restrictions under dual-use technology classifications limit fiber optic sensor component flows from Japanese suppliers to Chinese wind turbine manufacturers, constraining distributed sensing architectures in Yangtze River Delta production clusters. Manufacturing concentration centers on Germany, the United States, and Japan for precision laser measurement systems, with piezoelectric transducer substrates drawing from South Korean semiconductor foundries. Single-source vulnerability in Bragg grating fabrication creates supply chain risk for fiber optic sensor vendors. Distribution runs through specialized metrology distributors serving aerospace OEMs directly while channel partners handle Tier-1 supplier retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
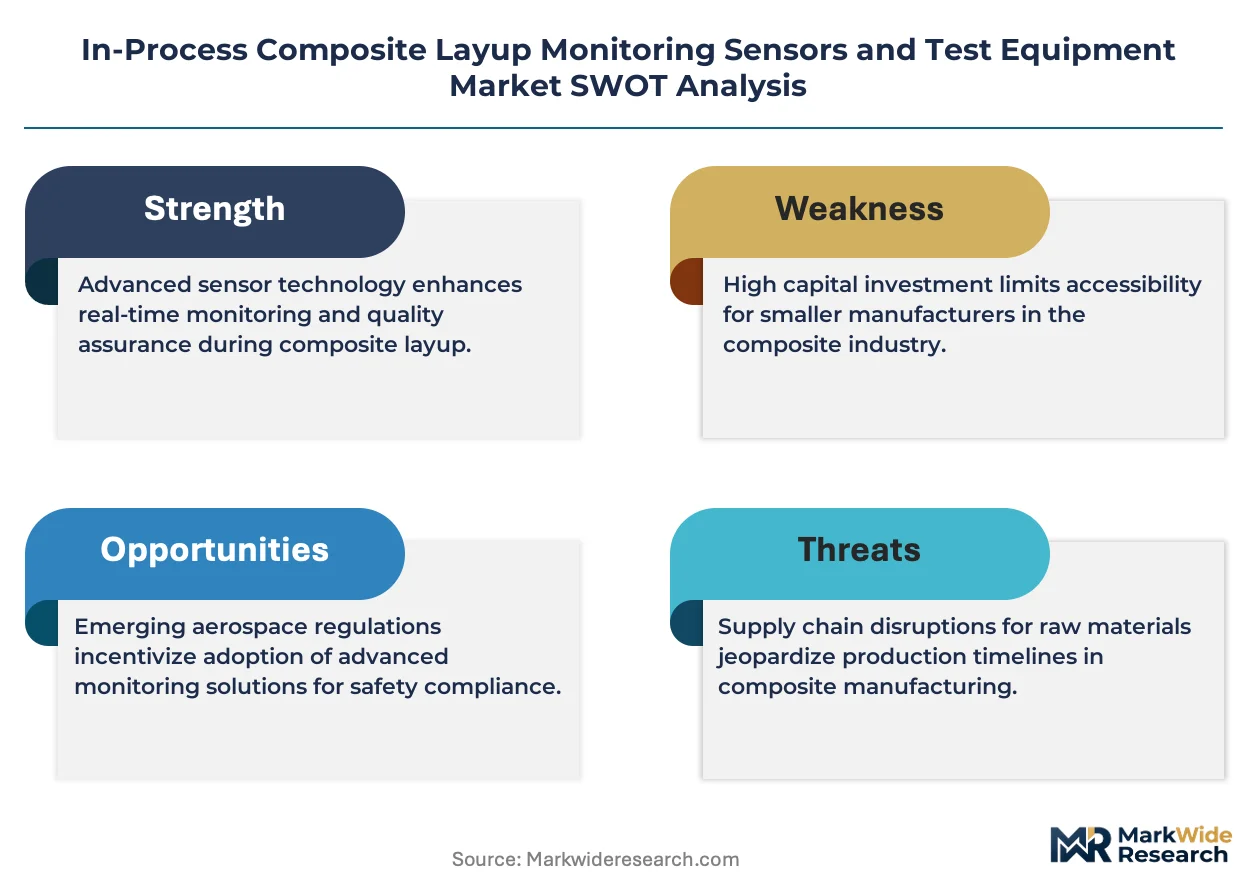
This market sits in early-cycle expansion as automated fiber placement lines displace manual inspection stations across aerospace manufacturing corridors, with EU Green Deal mandates for lighter transport materials accelerating penetration beyond traditional airframe applications.
For Market Incumbents: Harden platform architectures against modular unbundling by deepening software integration with hardware calibration protocols, defending against specialized dielectric sensor vendors eroding tooling-embedded market share. Prioritize EASA-ASTM qualification investments across multiple regulatory jurisdictions to reduce vendor switching friction for European aerospace OEMs.
For New Entrants and Emerging Players: Pursue white-space opportunities in automotive Tier-1 supplier qualification under ISO 19001 frameworks, where in-process monitoring penetration lags aerospace by substantial margins. Target construction materials prefabrication segments with portable retrofit sensor packages compatible with existing panel production lines, leveraging direct sales to bypass established distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified metrology conglomerates seeking to divest non-core composite inspection divisions, particularly European precision equipment fabricators with stranded aerospace exposure. Monitor fiber optic sensor patent filing velocity from Japanese research institutions as an inflection indicator for distributed sensing technology maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Sensor Platform Integration | Dielectric analysis convergence with automated fiber placement tooling collapses separate cure validation equipment requirements at Boeing Charleston. |
| Modular Architecture Unbundling | Service separation into hardware, analytics, and calibration components reduces Tier-1 supplier qualification friction across German aerospace corridors. |
| EASA-ASTM Harmonization Compliance | Standardized equipment specifications reduce vendor requalification costs for laser scanning platforms serving Airbus Hamburg operations. |
| Fiber Optic Distributed Sensing R&D | Bragg grating architectures attract concentrated investment from Toray and Mitsubishi Heavy Industries for satellite primary structures. |
| REACH Substance Substitution | Sensor housing material reformulation satisfies European hazardous substance restrictions for wind energy OEMs in Denmark and Spain. |
Research Methodology
A standing panel of aerospace manufacturing engineers, metrology equipment procurement managers, composite materials R&D directors, and FAA certification specialists provided ongoing calibration against secondary validation from EASA regulatory filings, ASTM standardization committee minutes, and SEC 10-K equipment vendor disclosures. Primary fieldwork combined structured interviews with automated fiber placement line operators and quality assurance directors across Bavaria-Hamburg and Seattle-Tacoma manufacturing corridors. Bottom-up equipment shipment data triangulated against top-down OEM capital expenditure patterns.
Scenario-bracketing around EU Green Deal implementation timelines and FAA airworthiness standard enforcement intensity shaped projections across the analysis window. Segmentation modeling incorporated technology maturity tiers, application-specific certification burdens, and end-user integration depth preferences. CAGRs derived from equipment replacement cycle analysis and greenfield facility commissioning schedules, with dielectric sensor adoption curves and fiber optic R&D investment flows serving as industry-specific forecast inputs.
Sensitivities concentrate around EASA-ASTM harmonization pace and REACH compliance deadline shifts for sensor material substitutions. Forecasts reflect assumptions regarding automated fiber placement line conversion rates and Tier-1 supplier capital availability. Material shifts in FAA composite primary structure documentation requirements or MIIT supplier qualification guidelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Tensile Testers Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Automated Ultrasonic Testing Market