
 Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market | 2026-2036
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market Insights
Aftermarket service revenue for recertification and field audit support is fragmenting across equipment OEMs and third-party metrology labs. HORIBA leverages its captive gas blending technology to lock in long-term service contracts. TSI Incorporated competes through portable reference-grade photometers that reduce laboratory dependency. Thermo Fisher Scientific anchors high-end demand with gravimetric primary standards traceable to NIST.
Indoor air quality multi-pollutant sensor calibration test equipment comprises precision gas generation systems, photometric analyzers, and electrochemical simulators designed to verify sensor accuracy against traceable reference concentrations, typically operating at ppb to ppm resolution across temperature and humidity-controlled chambers. Dynamic gas generation equipment dominates installed base value due to its role in continuous certification workflows for regulatory compliance. Automated calibration methods represent the fastest-expanding segment as environmental testing laboratories face throughput pressure from expanding building certification mandates. Manual methods retain niche positions in academic research centers where protocol flexibility outweighs speed requirements.
The EPA Office of Air and Radiation shapes demand through mandatory calibration traceability for sensors deployed under federal indoor air quality guidelines, while NIST maintains primary gas standards that anchor national measurement infrastructure. The EU F-Gas Regulation restricts synthetic carrier gases used in dilution systems, forcing equipment redesign toward natural reference blends. Stakeholders must monitor whether emerging state-level ventilation standards in California and New York will mandate shorter recertification intervals than federal baselines.
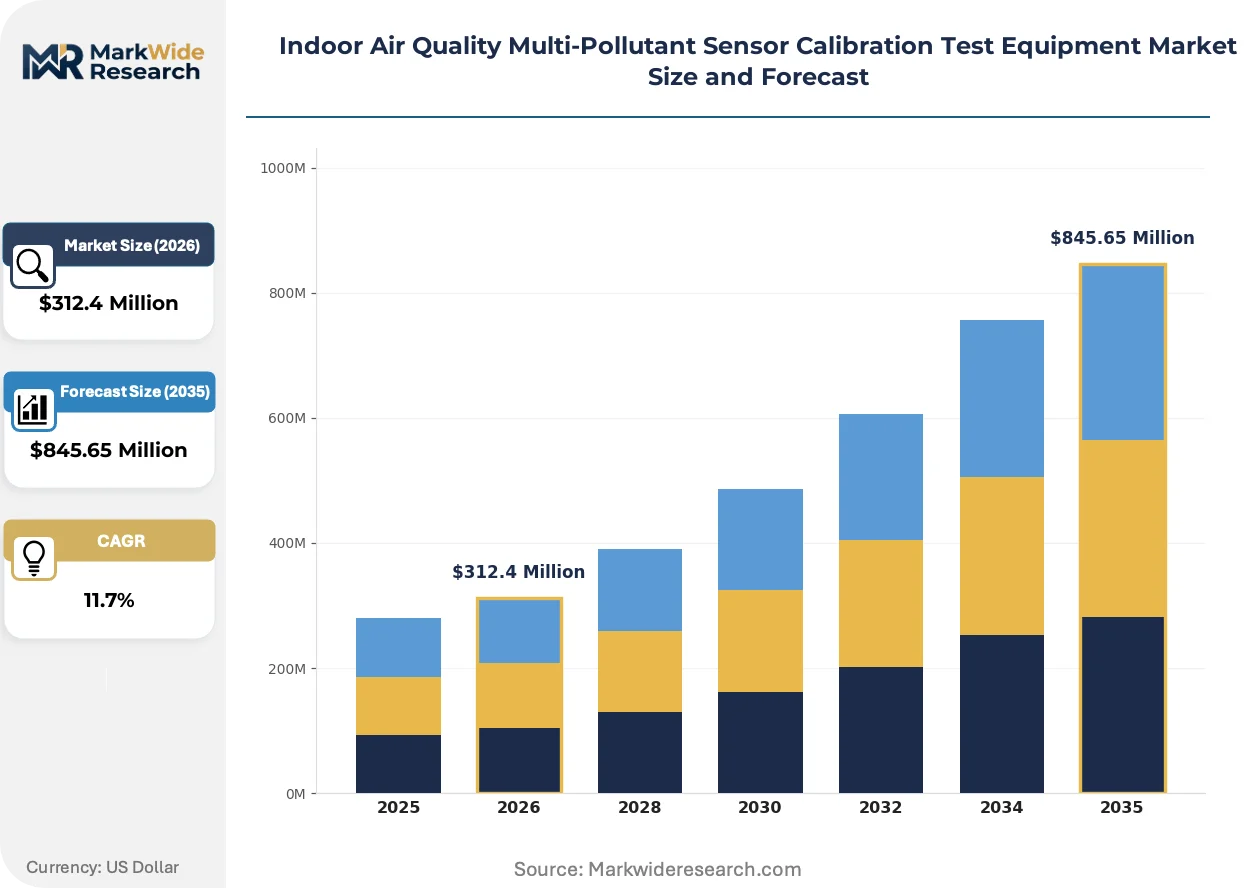
Market Dynamics
LEED v4.1 and WELL certification mandates are compressing recertification cycles for commercial building sensor networks, forcing test equipment vendors to prioritize throughput automation over laboratory-grade precision.
Growth Catalysts
- Regulatory Certification Mandates:The EPA Office of Air and Radiation requires traceable calibration for federal indoor air quality deployments, creating baseline demand for NIST-anchored reference systems.
- Building Automation Integration:Smart HVAC retrofits in Germany and Japan require continuous sensor validation, driving dynamic gas generation equipment into facility management workflows.
- EU F-Gas Regulation:Restrictions on synthetic carrier gases force equipment redesign toward natural reference blends, accelerating replacement of legacy dilution systems.
Market Restraints
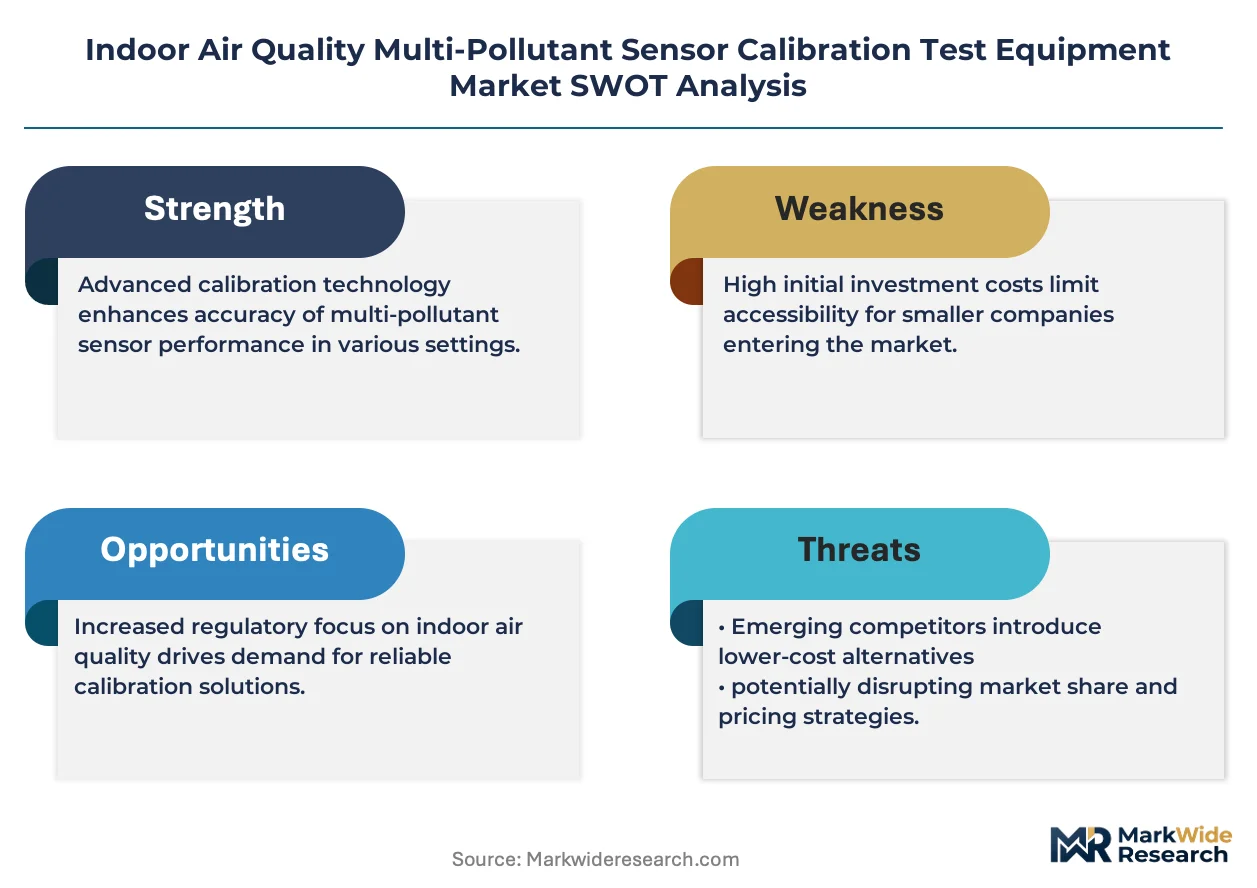
- Primary Standard Scarcity:Gravimetric certification requires access to national metrology institutes concentrated in Germany, Japan, and the United States, limiting vendor geographic expansion.
- Helium Supply Volatility:Carrier gas cost fluctuations impact dynamic generation system operating economics, particularly for high-dilution ratio applications.
- Technical Resolution Ceilings:Electrochemical simulators face fundamental limits at sub-ppb concentrations for formaldehyde and ozone reference generation.
Strategic Opportunities
- Field-Portable Calibration Services:Third-party metrology labs in California and New York can bypass fixed laboratory infrastructure by deploying mobile reference photometers for on-site sensor audits.
- Natural Refrigerant Blends:Equipment manufacturers can capture EU market share by engineering dilution systems compatible with CO2 and hydrocarbon carrier gases ahead of F-Gas phase-down deadlines.
- Automated Throughput Systems:Environmental testing laboratories facing WELL certification volume surges present demand for robotic sample handling integrated with multi-pollutant chambers.
Industry Challenges
- Metrology Talent Shortage:Gas standard preparation and uncertainty quantification require specialized training that outpaces university program output in the United States and Germany.
- Legacy System Integration:Manual calibration benches in academic research centers resist automation retrofit due to protocol customization requirements.
- Multi-Jurisdiction Certification Timelines:Equipment vendors must sequence EPA, NIST, and EU F-Gas compliance testing, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Dynamic Gas Generation, Static Gas Dilution, Photometric Analyzers, Electrochemical Simulators, Gravimetric Standards Calibration Method: Automated, Manual, Hybrid, Batch, Real-time Application: Indoor Air Quality Monitoring, HVAC System Testing, Emission Source Evaluation, Laboratory Research End User: Environmental Testing Laboratories, Regulatory Agencies, Industrial Safety Departments, Academic Research Centers |
| Companies Covered | HORIBA, Acoem, Environics, Weiss Technik, TSI Incorporated, Kanomax, 2B Technologies, Thermo Fisher Scientific, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market Trends and Innovations
Digital twin architectures and synthetic reference generation are compressing the boundary between laboratory calibration and field validation, enabling continuous compliance monitoring without physical gas consumption.
Cloud-based calibration management software is virtualizing sensor traceability documentation. Commercial building operators in Germany now upload calibration certificates directly to LEED online platforms. This architecture eliminates manual audit preparation and compresses recertification timelines from weeks to hours.
The EU F-Gas Regulation is banning hydrofluorocarbon carrier gases above specific global warming potential thresholds by 2030. Equipment manufacturers in the Netherlands and Denmark are engineering CO2-based dilution systems. These redesigns sacrifice some dynamic range precision but secure regulatory compliance for EU environmental testing laboratories.
Facility managers are unbundling calibration service contracts from equipment purchase agreements. Third-party metrology providers in California now compete directly with OEM service divisions through subscription-based field audit programs. This shift fragments aftermarket revenue streams and pressures equipment vendors to defend margin through captive gas blending technology.
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market Segmentation
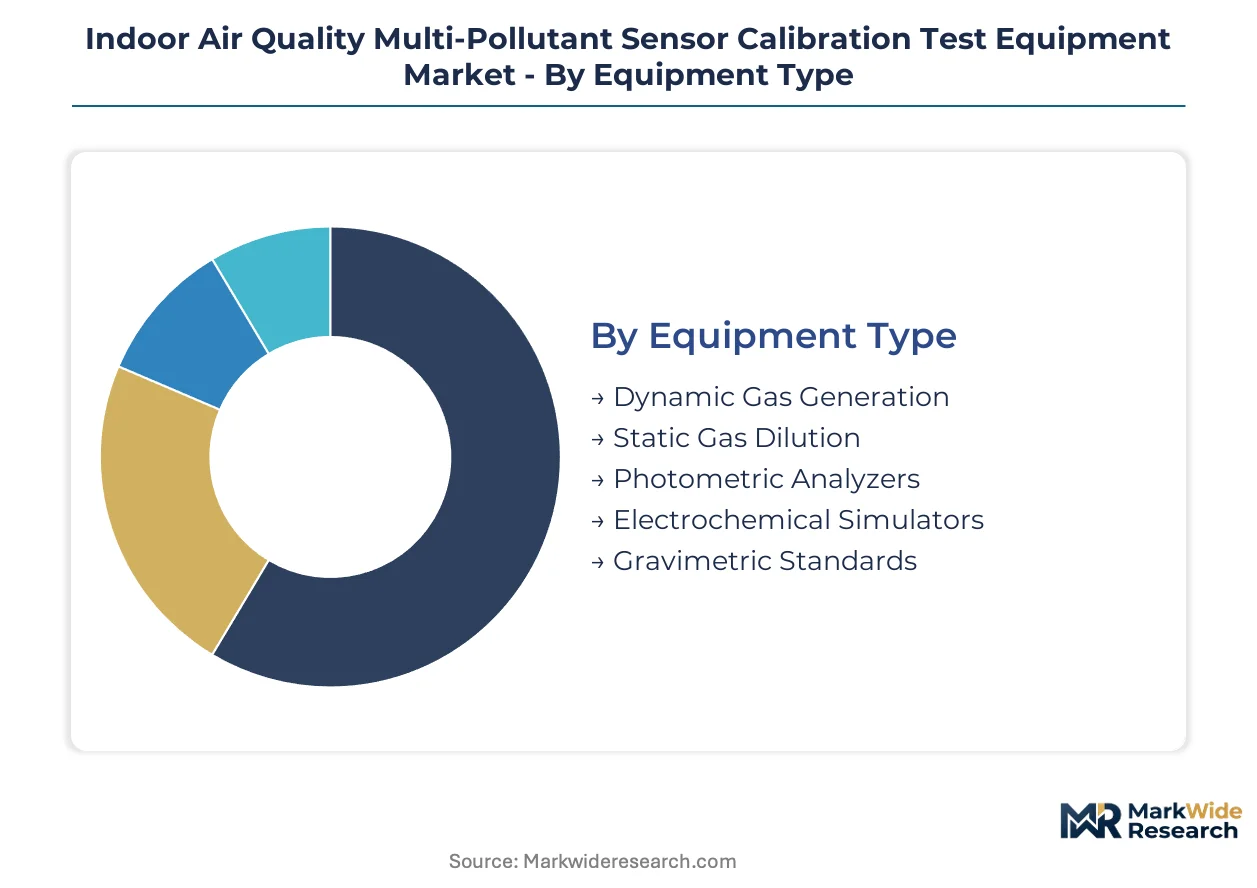
Equipment configuration determines aftermarket service intensity across this market. Dynamic gas generation systems demand continuous recertification and carrier gas logistics, while photometric analyzers require periodic photometric standard replacement. Understanding segment-specific service attach rates clarifies vendor profitability beyond initial hardware sales.
Equipment Type:
After-sales service intensity varies dramatically by equipment category, with dynamic systems generating recurring revenue through gas standard replenishment and chamber maintenance contracts.
- Dynamic Gas Generation:Continuous-flow systems blend carrier gases with trace-level pollutant standards to produce ppb-to-ppm reference concentrations on demand. Environmental testing laboratories in Germany and Japan deploy these for LEED certification workflows where throughput automation reduces per-sensor calibration labor. Equipment OEMs capture margin through captive gas blending technology and long-term service contracts.
- Photometric Analyzers:Reference-grade optical instruments measure light extinction or fluorescence to verify sensor response against NIST-traceable particulate or gas-phase standards. Third-party metrology labs in California compete with OEM service divisions by deploying portable units for field audit programs, fragmenting aftermarket revenue streams.
- Static Gas Dilution:Pre-mixed certified reference materials in high-pressure cylinders deliver fixed concentration points for point-source calibration. Academic research centers favor these for protocol flexibility despite higher per-test gas consumption.
- Electrochemical Simulators:Electronic signal injection mimics sensor response curves without physical gas consumption, reducing operating costs for basic functional checks. Sub-ppb resolution limits constrain formaldehyde and ozone reference applications.
- Gravimetric Standards:Primary mass-based certification systems anchor national measurement infrastructure at metrology institutes in Germany, Japan, and the United States. Access scarcity limits vendor geographic expansion beyond these concentration points.
By volume, Dynamic Gas Generation leads. By growth pace, Photometric Analyzers are expanding most quickly.
Calibration Method:
Cost tier stratification separates high-throughput automation from budget-constrained manual alternatives, with hybrid architectures emerging to bridge laboratory and field workflows.
- Automated:Robotic sample handling and software-controlled gas blending execute calibration sequences without operator intervention. WELL certification volume surges in commercial buildings drive demand as environmental testing laboratories face throughput pressure.
- Manual:Operator-directed gas handling and data recording retain protocol customization for academic research centers where flexibility outweighs speed requirements. Legacy bench resistance to automation retrofit persists due to specialized experimental designs.
- Hybrid:Semi-automated workflows combine software-controlled gas generation with manual sensor mounting and verification steps. Mid-tier environmental testing laboratories adopt these to balance throughput gains against capital constraints.
- Batch:Simultaneous multi-sensor processing in temperature-humidity controlled chambers maximizes equipment utilization for large sensor network deployments. Commercial building operators in Germany leverage batch methods for seasonal recertification cycles.
- Real-time:Continuous validation architectures integrated with building automation systems enable immediate fault detection. Smart HVAC retrofits in Japan incorporate real-time calibration verification into facility management workflows.
Automated systems command premium pricing. Real-time architectures are gaining share fastest among new installations.
Application:
Customer maturity separates compliance-driven routine testing from exploratory research applications, with divergent requirements for documentation depth and protocol flexibility.
- Indoor Air Quality Monitoring:Sensor validation for CO2, VOC, and particulate detection in occupied spaces under LEED v4.1 and WELL schemes. Commercial building operators in the United States compress recertification timelines from annual to quarterly cycles.
- HVAC System Testing:Commissioning and performance verification for ventilation equipment integrated with sensor feedback loops. Smart building retrofits in Germany require continuous validation to maintain energy efficiency certifications.
- Emission Source Evaluation:Trace-level pollutant quantification from building materials, furnishings, and cleaning products. Product certification laboratories face tightening EPA indoor air standards for formaldehyde and ozone precursor emissions.
- Laboratory Research:Protocol development and sensor characterization studies at academic and government research centers. Manual calibration benches dominate due to experimental customization requirements that resist standardization.
Indoor Air Quality Monitoring generates the largest equipment volume. HVAC System Testing shows the steepest expansion trajectory.
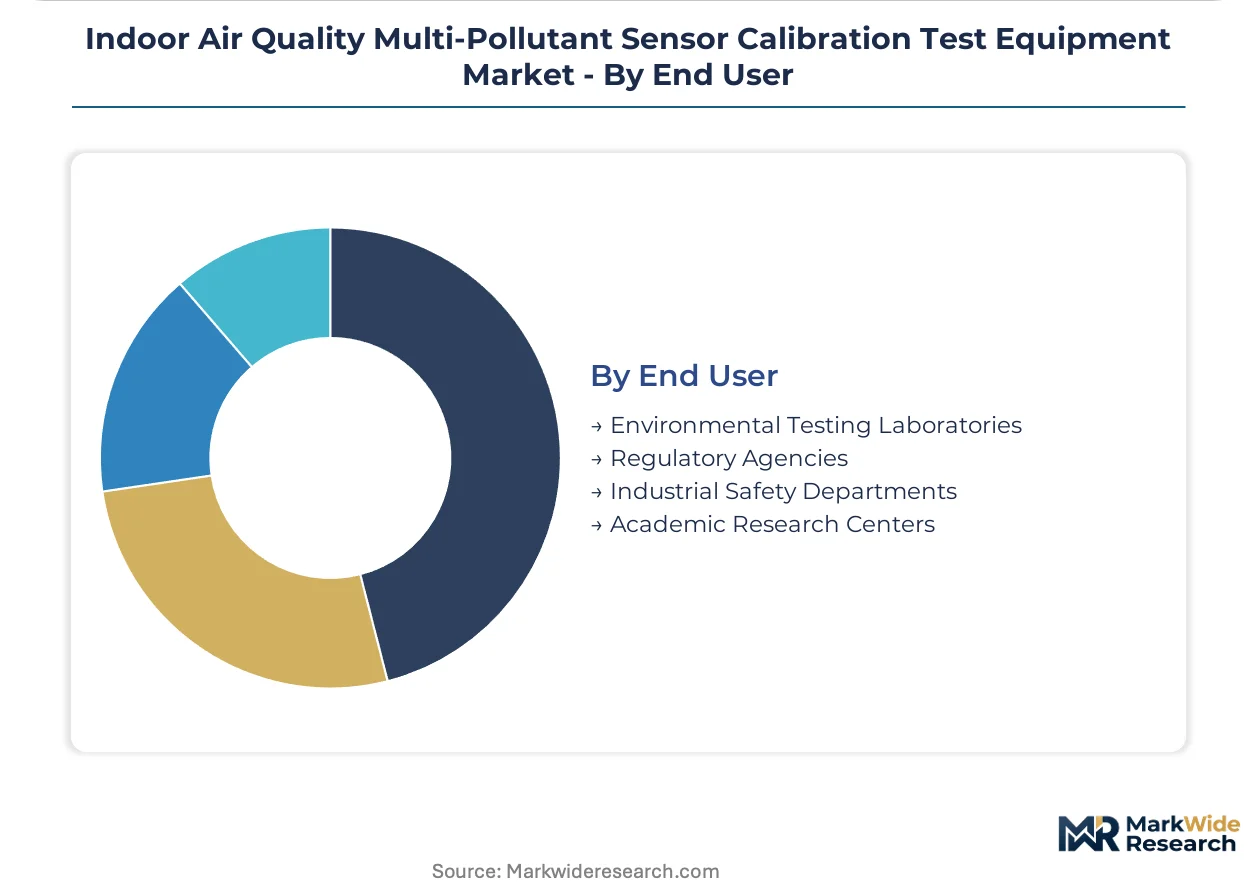
End User:
Procurement authority concentration distinguishes centralized regulatory laboratories from distributed industrial safety departments, with divergent purchasing cycles and technical support expectations.
- Environmental Testing Laboratories:Commercial and government facilities executing certification testing for building products and ventilation systems. WELL certification mandates in California and New York drive volume surges requiring automated throughput systems.
- Regulatory Agencies:EPA Office of Air and Radiation and state environmental departments mandating calibration traceability for federal indoor air quality deployments. NIST-anchored reference systems anchor procurement specifications.
- Industrial Safety Departments:Corporate occupational health units monitoring workplace exposure limits and ventilation performance. Subscription-based field audit programs from third-party metrology providers compete directly with OEM service divisions.
- Academic Research Centers:University and institute laboratories developing novel sensor technologies and calibration protocols. Manual methods retain dominance where experimental flexibility outweighs throughput optimization.
Environmental Testing Laboratories represent the largest customer base by unit volume. Industrial Safety Departments are climbing the fastest as facility managers unbundle service contracts from equipment purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate lowest price elasticity due to stringent metrology requirements, while commercial building operators in the United States prioritize throughput automation over absolute precision. Demand concentrates where national measurement institutes maintain primary gas standards.
United States
Commercial building operators compress recertification cycles from annual to quarterly intervals under LEED v4.1 mandates. The EPA Office of Air and Radiation requires NIST-traceable calibration for federal indoor air quality deployments. Environmental testing laboratories in California and New York deploy automated throughput systems to manage WELL certification volume surges.
Germany
Smart HVAC retrofits require continuous sensor validation to maintain energy efficiency certifications. The EU F-Gas Regulation restricts synthetic carrier gases, forcing equipment redesign toward natural reference blends. Metrology institutes in Berlin and Munich anchor primary gravimetric standards that limit vendor geographic expansion beyond these concentration points.
Japan
Facility management workflows integrate real-time calibration verification into building automation systems. METI standards for sensor traceability drive demand for dynamic gas generation equipment. Industrial clusters in Tokyo and Osaka concentrate procurement authority for automated batch calibration systems serving seasonal recertification cycles.
Netherlands
Equipment manufacturers engineer CO2-based dilution systems ahead of F-Gas phase-down deadlines. REACH compliance for reference gas mixtures adds regulatory complexity to product development. Technical universities in Eindhoven and Delft collaborate with vendors on synthetic reference generation architectures.
China
Environmental testing laboratories face throughput pressure from expanding building certification mandates adopted from Western standards. GB standards for indoor air quality monitoring create baseline demand for traceable calibration protocols. Manufacturing clusters in Shanghai and Shenzhen drive localization of dynamic gas generation equipment for regional supply chains.
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market Competitive Landscape
Precision instrumentation conglomerates and specialized environmental test equipment fabricators split the market between captive gas blending technology and portable reference-grade systems. Three strategic archetypes dominate: diversified analytical instrumentation groups with metrology institute relationships, dedicated air quality testing equipment specialists with regional service networks, and gas generation technology purists with carrier gas logistics expertise. Competitive moves concentrate on backward integration into gas standard preparation and geographic expansion through third-party metrology lab partnerships.
Among diversified analytical instrumentation groups, HORIBA and Thermo Fisher Scientific exemplify archetypes leveraging captive technology to lock in long-term service contracts. TSI Incorporated occupies a distinct position within the portable reference-grade tier, competing through reduced laboratory dependency. These three anchors illustrate how vendor profitability extends beyond initial hardware sales into aftermarket service intensity.
| Leading Market Players |
|---|
| HORIBA |
| Acoem |
| Environics |
| Weiss Technik |
| TSI Incorporated |
| Kanomax |
| 2B Technologies |
| Thermo Fisher Scientific |
| Teledyne Technologies |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor anchors cost dynamics for carrier gas cylinders and precision photometer components, compressing margins for equipment vendors while enabling three-tier pricing differentiation between NIST-traceable premium systems, mid-grade automated benches, and economy manual configurations.
Pricing Analysis
After-sales service contracts and captive gas blending agreements generate lifetime value exceeding initial hardware sales by substantial multiples. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost, with NIST-anchored systems commanding substantial premiums in Germany and Japan. Cost compression in mid-tier automated equipment is intensifying because third-party metrology labs in California fragment service revenue through subscription field audit programs. Environmental testing laboratories exhibit highest price sensitivity due to throughput pressure, while regulatory agencies demonstrate lowest elasticity for primary gravimetric standards.
Supply Chain Analysis
Supplier financing facilities with extended payment terms have become critical for equipment manufacturers managing helium inventory volatility and precision optics procurement. Component sourcing draws from Germany for gravimetric certification hardware, Japan for photometric analyzers, and the United States for dynamic gas generation controllers. Raw material dependencies center on high-purity carrier gases, certified reference materials, and optical-grade sapphire windows. Single-source vulnerability concentrates in national metrology institute access for primary standards. Distribution runs through direct OEM service divisions competing against third-party metrology lab partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas standard replenishment and recertification service layers expand faster than hardware sales, transforming vendor profitability models toward recurring revenue architectures.
For Market Incumbents: Pre-empt third-party metrology encroachment by deepening backward integration into captive gas blending technology and locking long-term service contracts with environmental testing laboratories facing WELL certification volume surges. Accelerate EU F-Gas compliance redesigns ahead of 2030 phase-down deadlines to defend market position against natural refrigerant specialists. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with GB standard adoption creating baseline demand for traceable calibration protocols without incumbent service network saturation. Portable reference-grade photometers for field audit programs offer a direct go-to-market angle bypassing fixed laboratory infrastructure requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical instrumentation groups seeking to divest non-core environmental testing divisions. Long-term viability hinges on service attach rate expansion rather than hardware shipment growth. Monitor EU F-Gas implementation enforcement intensity as the critical inflection signal for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas Standard Preparation | Captive blending technology locks recurring revenue and defends margin against third-party metrology labs. |
| Natural Refrigerant Dilution System Development | CO2-based architectures secure EU market access ahead of F-Gas synthetic carrier gas phase-down deadlines. |
| Cloud-Based Calibration Management Platform Launch | Virtualized traceability documentation compresses recertification timelines for LEED and WELL certification workflows. |
| Third-Party Metrology Lab Partnership Network | Geographic expansion bypasses primary standard scarcity constraints in Germany, Japan, and the United States. |
| Automated Throughput System Scale-Up | Robotic sample handling addresses environmental testing laboratory capacity constraints from building certification mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, NIST technical standards documentation, EU F-Gas Regulation implementation reports, and customs trade data for precision instrumentation imports. Primary interviews incorporated equipment OEM product managers, environmental testing laboratory operations directors, third-party metrology service heads, and facility management procurement officers across Germany, Japan, and the United States. Bottom-up equipment shipment tracking and top-down market sizing triangulate volume and value estimates.
Forecast inputs include equipment type segmentation by dynamic gas generation, photometric analyzer, and electrochemical simulator categories; calibration method differentiation across automated, manual, and real-time architectures; and end-user concentration among environmental testing laboratories, regulatory agencies, and industrial safety departments. CAGRs derive from regression analysis of historical certification mandate expansion and replacement cycle compression across the projection horizon. Industry-specific inputs incorporate LEED v4.1 adoption trajectories and EU F-Gas phase-down enforcement schedules.
Macroeconomic conditions sit as an overlay; deviation in commercial construction spending, helium commodity pricing, or metrology institute funding allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory mandate expansion and service contract unbundling trends. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
DSL Tester Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Video Measuring System Market
Test and Measurement
X-Ray Inspection System Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Simulation and Test Data Management Market