
 Ground Grid Tester Market | 2026-2036
Ground Grid Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Grid Tester Market Foresight
The divergence between premium digital testers and commodity analog units is repositioning procurement patterns across the sector. Megger Group Limited leverages its heritage in insulation diagnostics to anchor the high-performance segment. Fluke Corporation competes through channel density and field-service integration. Chauvin Arnoux, Inc. specializes in European certification standards, extending its reach into utility specifications.
A ground grid tester measures electrical resistance and integrity of grounding systems using injected current and potential probe arrays, typically operating at frequencies from 45 Hz to 400 Hz to avoid soil ionization errors. Its primary purpose is verifying safety compliance for personnel protection and equipment integrity in high-voltage environments. The portable tester category dominates field deployments where substation crews require battery-operated units under 15 kg. Digital testers command margin concentration through data-logging and Bluetooth reporting features that utility companies now specify. AC ground testing technology leads volume while earth ground system integration into SCADA networks represents the fastest-expanding specification.
IEEE 81, OSHA 1910.269, and NFPA 70E collectively shape product standards by mandating periodic ground impedance verification and documented test traceability. The EPA's substation environmental compliance rules indirectly drive retesting frequency by linking spill containment integrity to electrical grounding performance. Stakeholders must monitor how IEEE revision cycles incorporate wideband frequency sweep requirements that could obsolete single-frequency instrument portfolios.
Market Dynamics
Substation modernization programs across North American utilities are tightening test frequency mandates and forcing equipment refresh cycles. IEEE 81 compliance revisions now require documented traceability that legacy analog testers cannot deliver.
Growth Catalysts
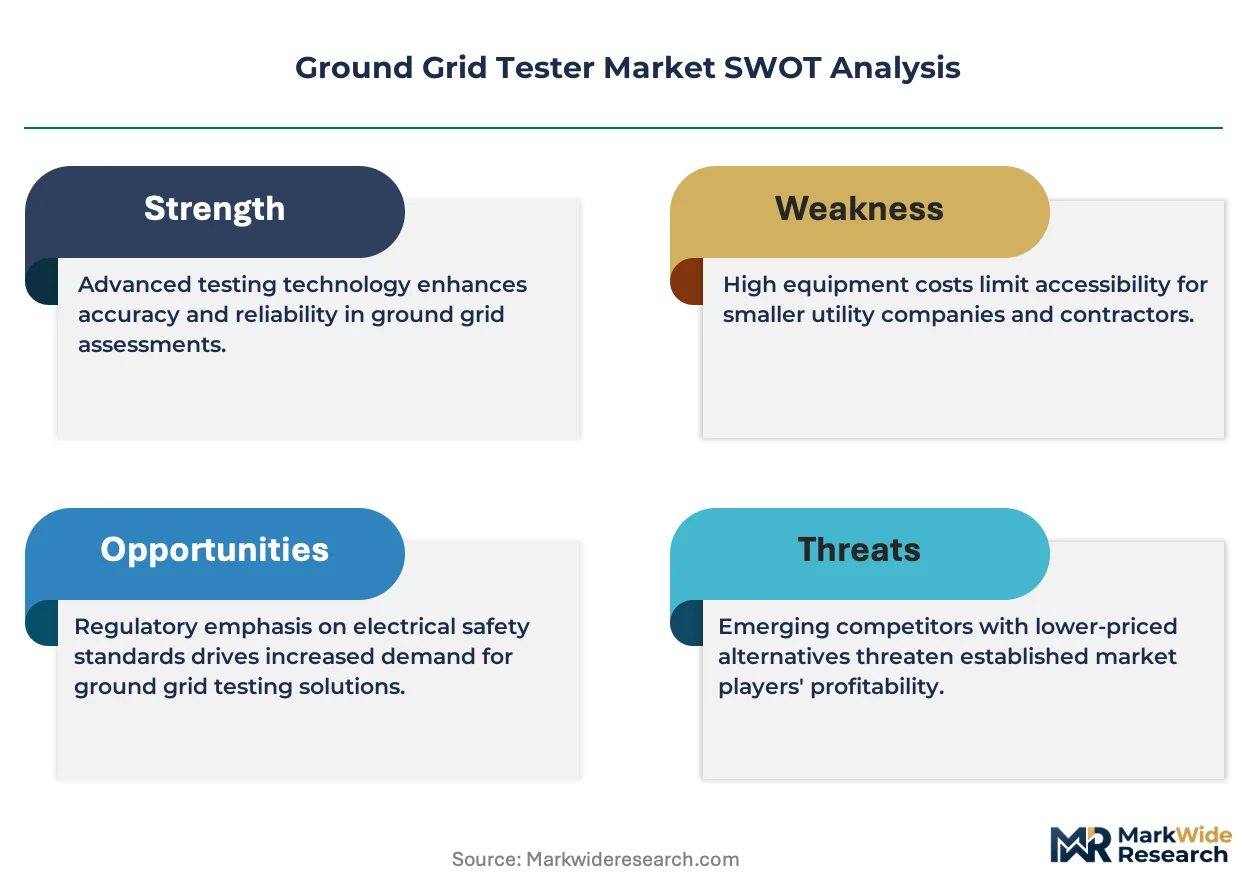
- Grid Hardening Investment:United States utility capital allocation toward storm-resilient infrastructure drives replacement of obsolete ground testing fleets. Substation crews require portable units for field deployment.
- IEEE 81 Frequency Mandates:Updated standards compel quarterly impedance verification rather than annual cycles. Documented test records become enforceable compliance items.
- Wideband Sweep Technology:Multi-frequency testing protocols eliminate soil ionization errors that plagued single-frequency instruments. Digital architectures enable automated frequency sequencing.
Market Restraints
- Copper Probe Cost Volatility:Potential probe arrays consume substantial copper and steel, exposing manufacturers to London Metal Exchange price swings. Input cost pass-through remains contested in utility procurement.
- Calibration Infrastructure Concentration:Certified calibration laboratories cluster in Germany and the United States, creating logistics friction for Latin American and Southeast Asian operators.
- Soil Condition Variability:Frozen ground and high-resistivity terrain limit test seasonality in northern climates. Seasonal deployment constraints compress annual utilization rates.
Strategic Opportunities
- SCADA Integration Specifications:Earth ground system data streams into substation automation networks. Real-time impedance monitoring replaces periodic manual testing.
- Battery Chemistry Advancement:Lithium iron phosphate packs extend field operation beyond nickel-cadmium limitations. Hot-swappable modules eliminate crew downtime.
- Bluetooth Reporting Mandates:Utility companies now specify wireless data logging for immediate cloud upload. Elimination of handwritten field records reduces transcription errors.
Industry Challenges
- Field Technician Certification Gaps:Competent person training under OSHA 1910.269 requires arc flash and grounding-specific credentials. Utility workforce development programs struggle to match retirement-driven attrition.
- Legacy Analog Fleet Amortization:Thousands of functional analog testers remain on utility balance sheets. Capital committees resist premature replacement despite compliance exposure.
- Interoperability with Proprietary Protocols:SCADA integration demands compatibility with vendor-specific communication stacks. DNP3, Modbus, and IEC 61850 implementations fragment development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Grid Tester Market |
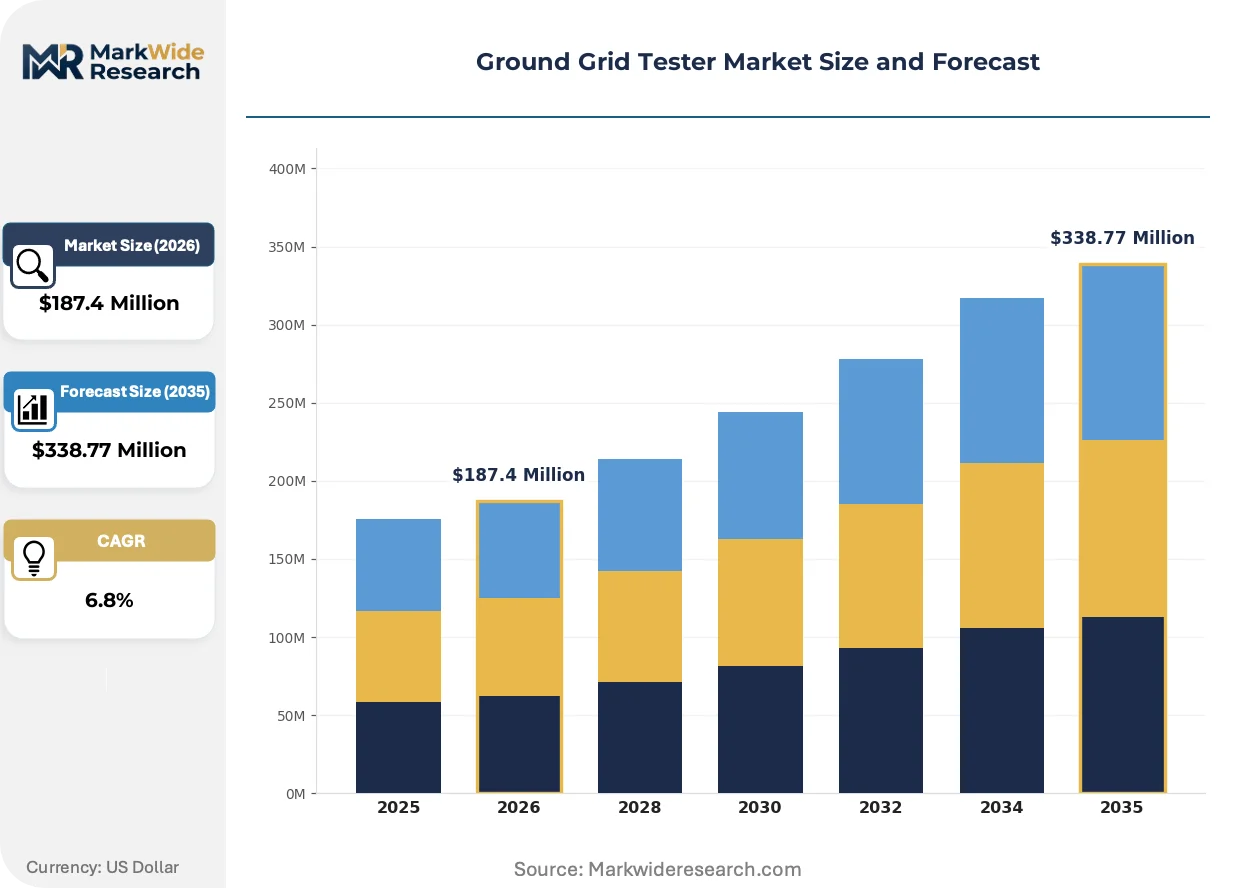
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tester, Digital Tester, Analog Tester, Multimeter Technology: AC Ground Testing, DC Ground Testing, Resistance Measurement, Earth Ground System End User: Utility Companies, Construction Firms, Industrial Plants, Maintenance Services Installation: Fixed Installation, Temporary Setup, On-site Testing, Laboratory Testing |
| Companies Covered | Fluke Corporation, Megger Group Limited, Chauvin Arnoux, Inc., Hioki E.E. Corporation, Extech Instruments Corporation, AEMC Instruments, CATU, Kyoritsu Electrical Instruments Works Ltd., Di-Log Test Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Grid Tester Market Shifts & Advancements
Digital architectures are absorbing functionality that previously required separate instruments, collapsing product categories while expanding margin capture for integrated platforms.
Wideband frequency sweep technology is absorbing the measurement role previously split across multiple single-frequency units. Digital testers now sequence automatically from 45 Hz through 400 Hz, eliminating manual frequency selection and reducing crew time per test. Utility specifications increasingly mandate this capability, compressing demand for legacy analog portfolios.
OSHA 1910.269 enforcement memoranda now explicitly reference ground impedance verification as an energized work prerequisite. Field audits in the United States have elevated documented testing from recommended practice to inspected requirement. Contractors performing live-line maintenance now carry portable digital units as standard personal protective equipment.
Utility procurement departments are consolidating vendor relationships and demanding outcome-based service agreements. Integrated calibration, repair, and firmware update contracts displace transactional equipment purchases. This concentration favors suppliers with dense North American service networks and penalizes regional distributors lacking technical support infrastructure.
Ground Grid Tester Market Segmentation
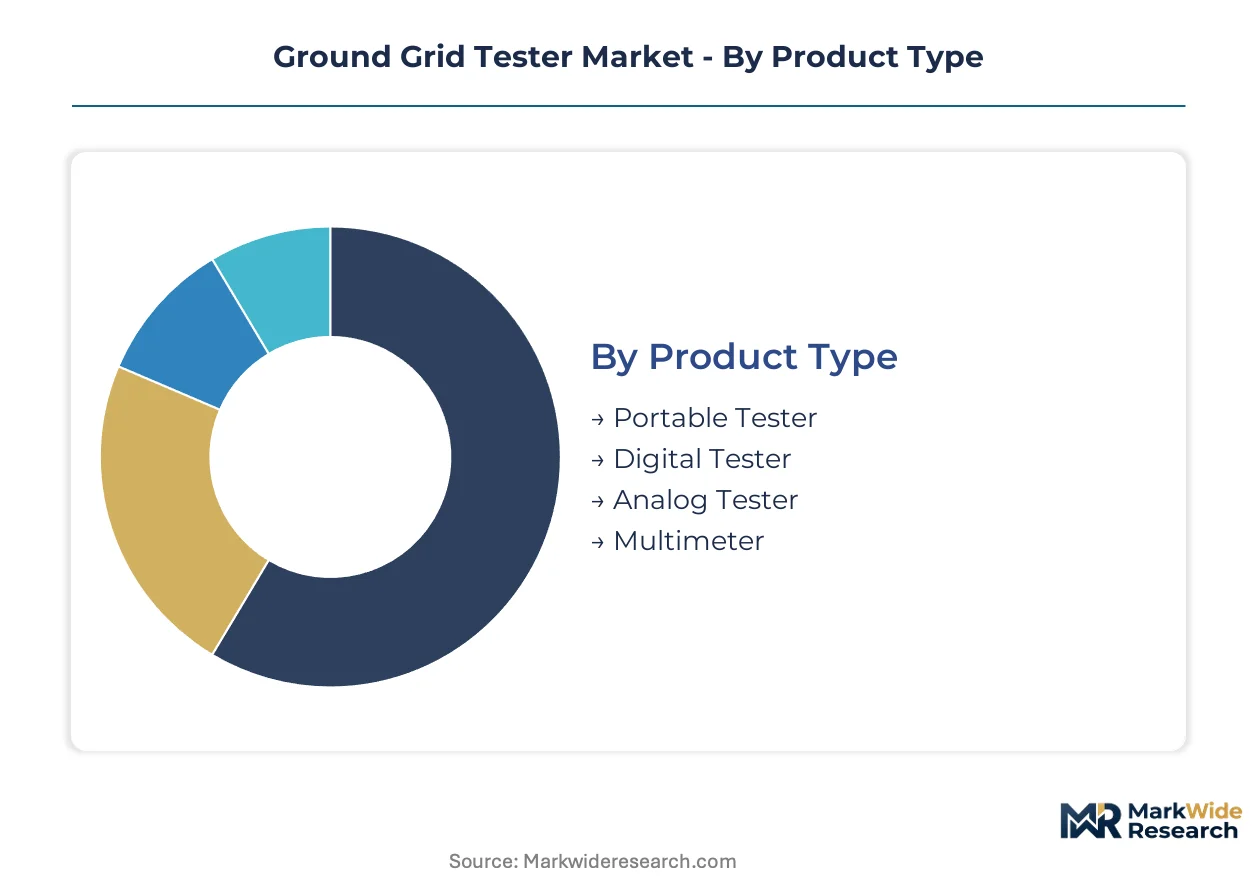
Ground grid tester procurement patterns diverge sharply across product architectures, testing methodologies, and deployment contexts. Utility capital committees, construction project managers, and industrial safety officers each impose distinct specification requirements that reshape vendor positioning.
Product Type:
Weight constraints and battery autonomy drive field crew preferences between stationary and mobile configurations.
- Portable Tester:Battery-operated units under 15 kg dominate substation maintenance crews requiring hot-swappable power modules. United States utility storm-response teams specify these for rapid deployment across distributed infrastructure.
- Digital Tester:Data-logging architectures with Bluetooth reporting capture margin concentration through firmware-upgradable platforms. IEEE 81 compliance traceability mandates accelerate displacement of legacy alternatives.
- Analog Tester:Electromechanical gauges persist on amortized utility balance sheets despite documentation limitations.
- Multimeter:General-purpose instruments serve secondary verification roles where ground testing represents occasional duty cycles.
Portable units lead on deployment scale; digital architectures lead on specification momentum.
Technology:
Frequency selection protocols determine measurement accuracy across soil resistivity variations.
- AC Ground Testing:Variable frequency injection from 45 Hz to 400 Hz avoids soil ionization artifacts that corrupt single-frequency readings. United States substation modernization programs specify multi-frequency sequencing as baseline procurement.
- Earth Ground System:Integrated impedance monitoring platforms stream data into SCADA automation networks. Real-time ground integrity surveillance replaces periodic manual verification cycles.
- DC Ground Testing:Galvanic measurement methods retain niche applications in corrosion-sensitive environments.
- Resistance Measurement:Stand-alone ohmmeter functions address basic compliance documentation without frequency agility.
AC methods anchor current volume; earth ground system integration climbs the fastest.
End User:
Regulatory exposure and workforce scale differentiate procurement sophistication across buyer categories.
- Utility Companies:Capital-intensive fleets demand outcome-based service contracts bundling calibration, repair, and firmware updates. OSHA 1910.269 enforcement elevates documented testing from recommended to inspected practice.
- Construction Firms:Project-based acquisition favors rental and lease arrangements over capital ownership.
- Industrial Plants:NFPA 70E compliance drives periodic verification in manufacturing environments with high fault current exposure.
- Maintenance Services:Contractor technicians carry portable units as standard personal protective equipment for live-line work authorization.
Utility companies dominate absolute demand; maintenance services expand most quickly.
Installation:
Mobility requirements and environmental exposure shape hardware durability specifications.
- On-site Testing:Field-deployable configurations withstand temperature extremes and moisture ingress across seasonal construction windows. Frozen ground constraints in northern climates compress annual utilization rates.
- Temporary Setup:Rapid deployment architectures serve storm-response and emergency restoration scenarios.
- Fixed Installation:Permanent monitoring stations integrate into substation automation infrastructure.
- Laboratory Testing:Controlled-environment calibration and certification activities support metrology traceability chains.
On-site testing leads deployment frequency; fixed installation gains share through SCADA convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified substation technicians cluster most densely in United States utility corridors, with secondary concentrations forming around German industrial zones and Japanese electrical manufacturing hubs.
United States
Storm-hardening capital programs at Duke Energy and Southern Company drive fleet replacement cycles. OSHA 1910.269 enforcement memoranda now mandate documented ground impedance verification before energized work authorization. Houston-Gulf Coast substation clusters deploy portable digital units for hurricane-response mobilization.
Germany
Grid modernization under the Energiewende transition prioritizes substation automation integration. CE marking and IEC 61508 functional safety standards shape procurement specifications for impedance monitoring platforms. Bavarian industrial zones around Munich anchor calibration laboratory infrastructure serving Central European utilities.
Japan
TEPCO and Chubu Electric post-Fukushima resilience investments accelerate earth ground system deployments. METI safety directives require real-time monitoring integration with existing SCADA architectures. Nagoya-Chubu manufacturing corridors concentrate precision instrument production for domestic utility specifications.
China
State Grid Corporation ultra-high voltage transmission expansion creates demand for wideband frequency sweep capabilities. GB/T standards for electrical safety testing tighten documentation requirements for substation commissioning. Yangtze River Delta clusters around Shanghai manufacture probe arrays and portable tester assemblies.
India
Central Electricity Authority mandates for rural electrification reliability drive ground testing fleet expansion at state distribution companies. BIS certification requirements for electrical safety equipment filter procurement toward documented traceability platforms. Gujarat industrial corridors deploy temporary setups for renewable energy substation commissioning.
Ground Grid Tester Market Competitive Landscape
Top-tier vendors anchor the premium digital segment, while regional distributors and legacy analog specialists occupy lower-margin tiers. The vendor base stratifies across three archetypes: heritage insulation diagnostics manufacturers, channel-dense field-service integrators, and European certification-focused specialists. Consolidation pressure intensifies as utility procurement departments demand bundled outcome-based service agreements spanning calibration, repair, and firmware updates. Geographic expansion through certified calibration laboratory partnerships represents a dominant competitive move alongside portfolio diversification into integrated SCADA-compatible platforms.
Within the heritage diagnostics tier, Megger Group Limited and Fluke Corporation exemplify contrasting strategic positions. Megger Group Limited, a UK-registered entity, occupies a position associated with insulation testing heritage and high-performance instrument architectures. Fluke Corporation, a US-based corporation, represents channel density advantages and field-service integration capabilities. Chauvin Arnoux, Inc., a French-registered specialist, anchors the European certification standards segment with utility specification reach extending from continental European markets.
| Leading Market Players |
|---|
| Fluke Corporation |
| Megger Group Limited |
| Chauvin Arnoux, Inc. |
| Hioki E.E. Corporation |
| Extech Instruments Corporation |
| AEMC Instruments |
| CATU |
| Kyoritsu Electrical Instruments Works Ltd. |
| Di-Log Test Equipment |
| Others |
Supply & Pricing Matrix
Digital-versus-analog performance divergence splits procurement into outcome-based service bundles and transactional hardware purchases. Utility capital committees now specify firmware-upgradable platforms with integrated calibration contracts, while construction contractors acquire unbundled units through rental channels. This bifurcation concentrates margin capture among vendors with dense North American service networks and compresses pricing power for regional distributors lacking technical support infrastructure.
Pricing Analysis
Bundled service contracts encompassing calibration, repair, and firmware updates command premium positioning against unbundled transactional equipment sales. Price differentiation rests on IEEE 81 compliance certification tier and Bluetooth-enabled data-logging capability. Pricing pressure intensifies in the analog segment as utility procurement departments consolidate vendor relationships and demand documented traceability that legacy electromechanical gauges cannot deliver. Construction firms exhibit highest price sensitivity due to project-based acquisition cycles, while utility companies prioritize total cost of ownership over unit purchase price.
Supply Chain Analysis
Probe array manufacturing rests on copper and steel supply from Chinese and German metal processors. Precision instrument assembly concentrates in Japan, Germany, and the United States around established electrical testing equipment hubs. London Metal Exchange price volatility for copper inputs creates margin compression risk for manufacturers unable to pass through material cost swings. Distribution runs through authorized distributor networks serving utility procurement departments, with direct OEM relationships dominating fleet-scale acquisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA 1910.269 enforcement memoranda mandating documented ground impedance verification before energized work authorization structurally expand replacement demand.
For Market Incumbents: Anticipate IEEE revision cycles incorporating wideband frequency sweep requirements that could obsolete single-frequency instrument portfolios. Defend market position by deepening backward integration into lithium iron phosphate battery pack production and securing certified calibration laboratory partnerships across Latin American and Southeast Asian markets. Channel control through exclusive service agreements with storm-hardening utility programs represents the critical defensive lever. For New Entrants and Emerging Players: Enter via temporary setup configurations for renewable energy substation commissioning in Gujarat industrial corridors and rural electrification reliability programs at Indian state distribution companies. Maintenance services contractors carrying portable units as standard personal protective equipment present the most penetrable segment given fragmented incumbent presence. A calibration-as-a-service subscription model bypasses capital-intensive fleet ownership barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where utility procurement departments demand bundled outcome-based service agreements spanning calibration, repair, and firmware updates. Long-term viability favors vendors with SCADA-compatible platform architectures and dense North American technical support infrastructure. Acquisition target archetypes include regional distributors with established utility relationships but limited digital portfolio breadth. The signal to watch is IEEE working group progress toward mandatory wideband sweep protocols.| Strategic Initiative | Industry Significance |
|---|---|
| SCADA Integration Development | Real-time impedance monitoring replaces periodic manual testing at Duke Energy and Southern Company substations. |
| Calibration Laboratory Partnership | Certified metrology infrastructure in São Paulo and Bangkok reduces logistics friction for regional operators. |
| Lithium Iron Phosphate Battery Transition | Hot-swappable power modules extend field operation beyond nickel-cadmium limitations for storm-response crews. |
| Bluetooth Reporting Platform Launch | Wireless data logging eliminates handwritten field records and enables immediate cloud upload for OSHA compliance. |
| Outcome-Based Service Contract | Integrated calibration, repair, and firmware update bundles displace transactional equipment purchases. |
Research Methodology
Bottom-up utility fleet modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with substation maintenance directors, utility procurement officers, electrical testing contractors, and calibration laboratory managers combined with secondary validation against IEEE standards documentation, OSHA enforcement memoranda, FERC capital expenditure filings, and utility integrated resource plans. Triangulation across these sources established volume and value estimates for each product architecture and deployment context.
Input-output matrices mapped unit demand across portable, digital, analog, and multimeter categories against AC ground testing, earth ground system, DC ground testing, and resistance measurement technologies. Segmentation dimensions included product type, testing methodology, end-user category, and installation context. CAGRs were derived from regression analysis of historical utility capital allocation patterns and projected IEEE compliance cycle frequencies. Forecast inputs incorporated substation modernization program announcements, grid hardening investment trajectories, and battery chemistry advancement timelines.
Inputs from utility procurement databases and manufacturer shipment records were available through the study window; gaps in real-time SCADA integration deployment rates introduce uncertainty bands around earth ground system segment projections. Forecasts reflect assumptions regarding IEEE 81 revision adoption timelines and OSHA enforcement intensity continuity. Copper price volatility, calibration infrastructure expansion pace, and frozen ground seasonality constraints represent specific risk factors that could revise projections. A small set of triggers—including wideband sweep mandate finalization and lithium iron phosphate cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
United States Borescope Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
EMC Testing Market
Test and Measurement
Digital Inspection Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Electrical Test Equipment Market