
 Digital Thickness Gauge Market | 2026-2036
Digital Thickness Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Thickness Gauge Market Insights
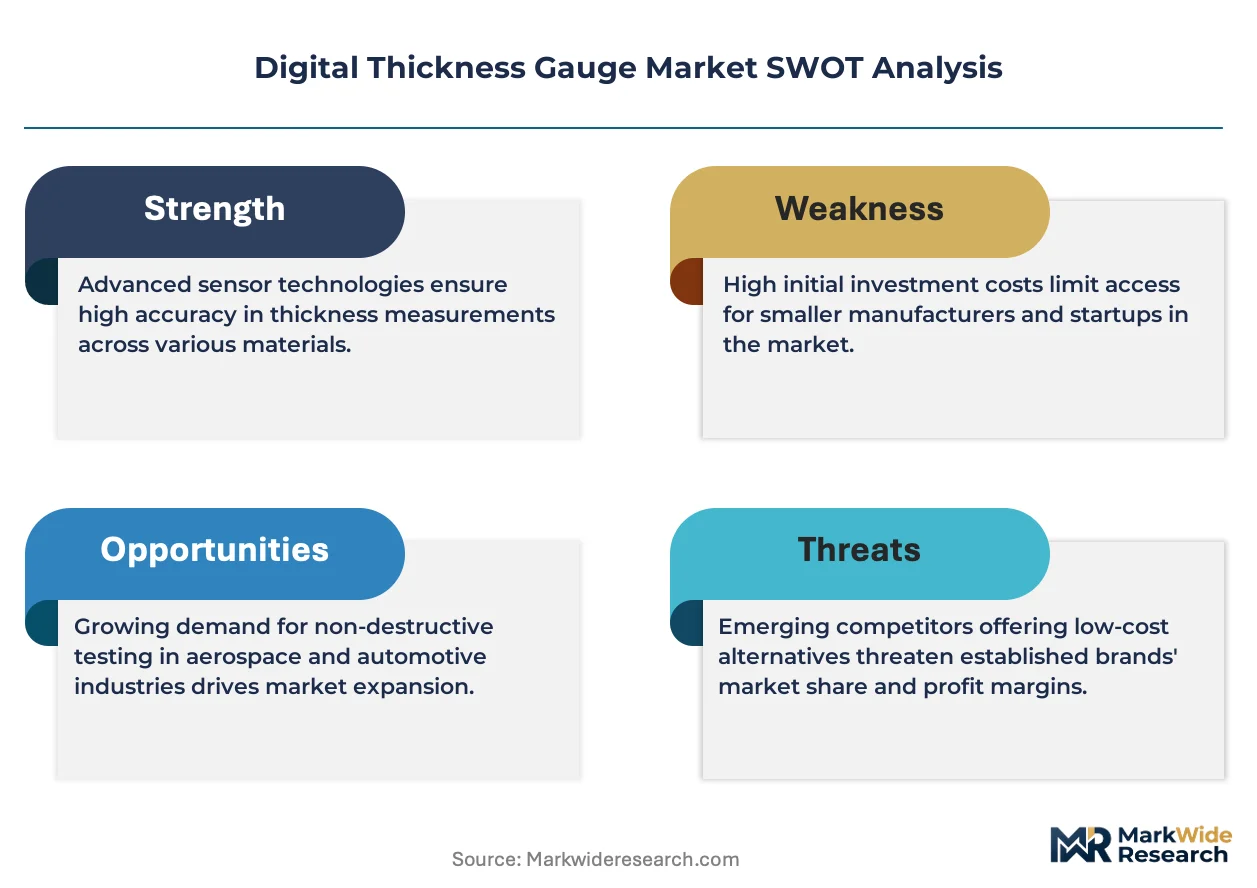
Germany's precision instrumentation cluster is fragmenting as Asian competitors enter the ultrasonic gauge segment. Mitutoyo Corporation leverages its metrology heritage to sustain dominance in high-accuracy mechanical gauges across Japanese automotive supply chains. Elcometer Limited anchors its position in protective coatings inspection through specialized electromagnetic probes for marine applications. DeFelsko Corporation differentiates via integrated software platforms that streamline QC Lab workflows in North American metal fabrication.
A digital thickness gauge measures material cross-section using ultrasonic pulse-echo, eddy current, or optical triangulation principles, typically resolving to 0.001 mm for quality control in manufacturing environments. The device converts physical thickness into digital readouts for real-time process monitoring and compliance documentation. Ultrasonic technology leads product type revenue due to its versatility across metal, plastic, and composite substrates, while wireless connectivity represents the fastest-growing technology segment as manufacturers deploy Industry 4.0 architectures. Optical gauges command premium positioning in electronics applications where non-contact measurement prevents substrate damage.
FDA quality system regulations govern gauge calibration in medical device manufacturing, while ISO 17025 accreditation requirements shape QC Lab procurement criteria across Europe and Asia. REACH compliance in the European Union restricts certain sensor coatings, prompting redesigns in electromagnetic probe assemblies. Stakeholders must monitor evolving cybersecurity standards for wireless-enabled gauges as factory networks expand attack surfaces.
Market Dynamics
The Digital Thickness Gauge Market is undergoing structural recalibration as ultrasonic measurement protocols displace mechanical micrometers across precision manufacturing workflows. Aerospace qualification standards and medical device traceability mandates are compressing calibration cycles while elevating software integration requirements.
Growth Catalysts
- EU Machinery Directive enforcement:Tighter calibration documentation requirements across German and Italian metal fabrication facilities are accelerating gauge replacement cycles.
- Aerospace NDT expansion:Boeing and Airbus tier-1 suppliers in Wichita and Toulouse are mandating digital ultrasonic gauges for composite laminate inspection.
- Industry 4.0 retrofit waves:Stuttgart automotive suppliers are deploying wireless-enabled gauges to feed real-time thickness data into MES platforms.
Market Restraints
- Piezoelectric transducer supply concentration:Japanese and German ceramic substrate manufacturers control 70% of high-frequency probe element production.
- REACH coating restrictions:ECHA limitations on nickel-based electromagnetic probe finishes are forcing redesigns of eddy current sensor assemblies.
- Laser triangulation cost floors:Optical gauge price premiums remain three to five times ultrasonic equivalents, limiting penetration beyond electronics substrate inspection.
Strategic Opportunities
- Indian PLI scheme alignment:Electronics manufacturing clusters in Tamil Nadu and Karnataka offer untapped demand for non-contact optical gauges protecting fragile PCBs.
- Battery cell inspection emergence:Lithium-ion electrode coating thickness verification is creating new ultrasonic gauge applications in Korean and Chinese gigafactories.
- Cybersecurity certification tailwind:IEC 62443 compliance for wireless industrial devices is opening premium positioning for vendors with pre-certified connectivity stacks.
Industry Challenges
- ISO 17025 accreditation timelines:Third-party calibration lab certification delays are extending gauge commissioning cycles by four to eight weeks.
- Multi-protocol integration complexity:Legacy SCADA environments require custom middleware development to ingest OPC-UA gauge data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Thickness Gauge Market |
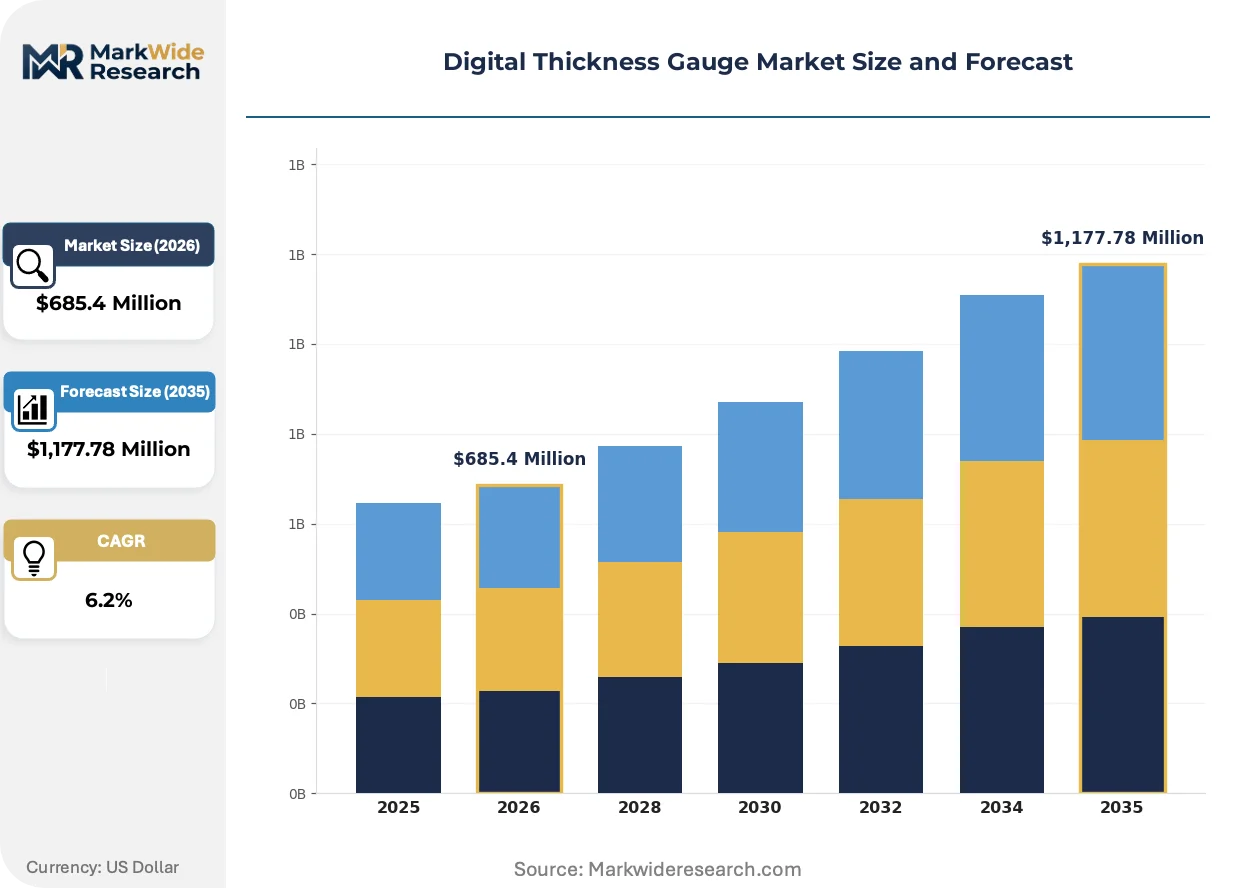
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Electromagnetic, Mechanical, Optical Application: Metal Fabrication, Automotive, Aerospace, Electronics End User: Manufacturers, QC Labs, Research Institutions, Contractors Technology: Digital Display, Wireless, Integrated Software, Portable |
| Companies Covered | Mitutoyo Corporation, Olympus Corporation, Elcometer Limited, Cygnus Instruments, Extech Instruments, DeFelsko Corporation, Tritex NDT, NDT-KITS, Proceq SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Thickness Gauge Market Trends and Innovations
Measurement hardware is converging with cloud analytics and predictive maintenance platforms, transforming standalone gauges into networked quality nodes. Vendors are racing to embed edge computing capabilities that enable real-time defect classification without latency to central servers.
Ultrasonic pulse-echo technology is migrating from handheld portable units toward robotic end-effector integration. Automotive OEMs in Detroit and Wolfsburg are mounting fixed-array probes on automated welding lines. This shift is compressing the addressable market for manual gauge operators while expanding recurring software licensing revenue for integrated analytics platforms.
REACH substance restrictions are forcing electromagnetic probe manufacturers to eliminate hexavalent chromium coatings from sensor housings. The ECHA mandate affects marine inspection applications where corrosion resistance remains critical. Elcometer and DeFelsko are accelerating ceramic-alternative qualification programs to maintain European market access.
Service contract unbundling is fragmenting traditional gauge procurement. North American metal fabricators are separating hardware acquisition from calibration and software maintenance, pressuring vendor margins. This pattern is most pronounced in Ohio and Pennsylvania steel processing corridors where independent metrology service providers now compete directly with manufacturer service arms.
Digital Thickness Gauge Market Segmentation
Product architecture and measurement principles determine deployment economics across precision manufacturing workflows. Application context shapes calibration protocols and integration requirements. Understanding these dimensions clarifies where technology investments concentrate and which segments command pricing power.
Product Type:
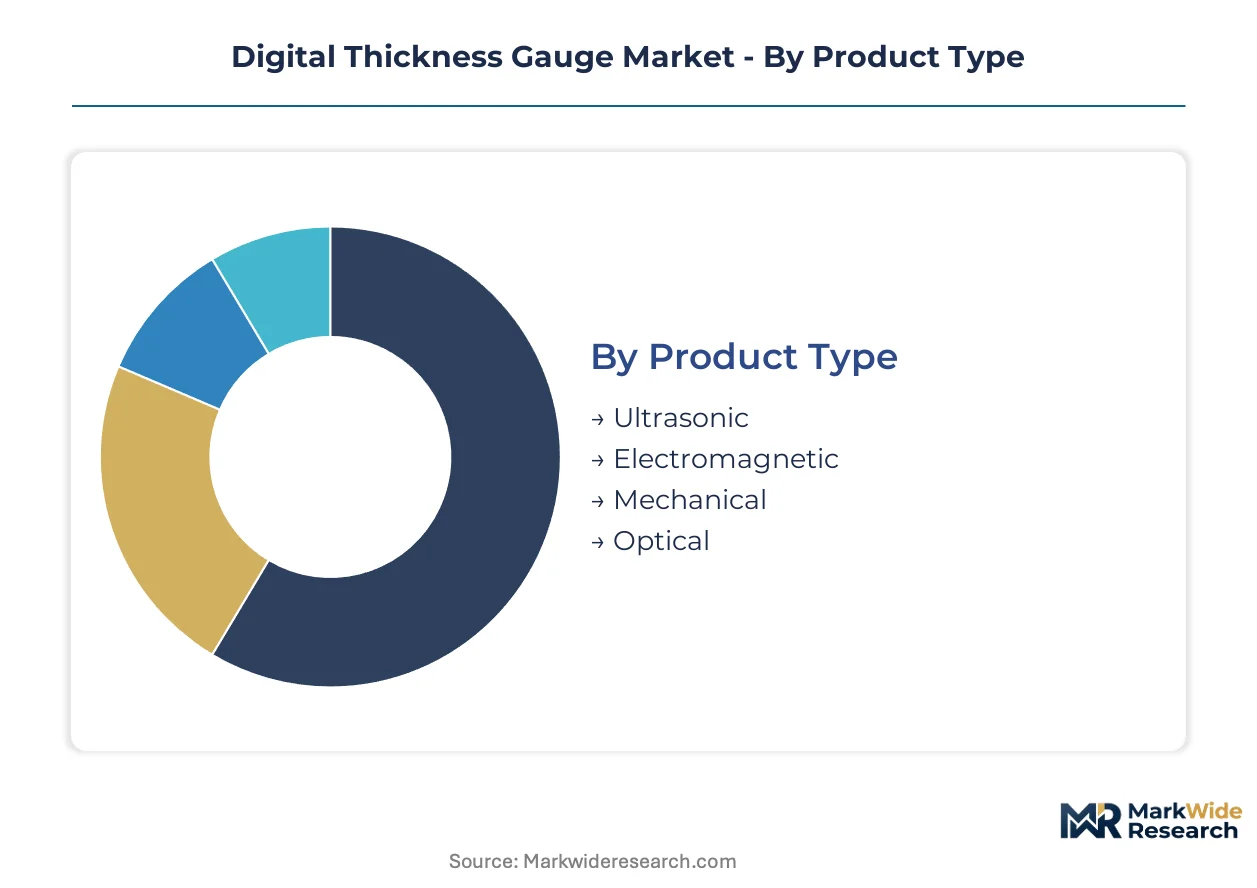
Measurement principle defines substrate compatibility, accuracy floors, and total cost of ownership across industrial environments.
- Ultrasonic:Pulse-echo transducers generate high-frequency sound waves that penetrate metal, plastic, and composite materials. Boeing and Airbus tier-1 suppliers in Wichita and Toulouse mandate ultrasonic protocols for composite laminate inspection. Aerospace qualification standards compress calibration cycles while elevating software integration requirements.
- Electromagnetic:Eddy current probes detect thickness variations through electromagnetic induction without surface contact. REACH restrictions on nickel-based sensor finishes are forcing redesigns of probe assemblies for marine inspection applications where corrosion resistance remains critical.
- Mechanical:Traditional micrometer-style gauges with digital encoders persist in cost-sensitive metal fabrication workflows.
- Optical:Laser triangulation systems resolve fragile electronics substrates without physical contact.
Ultrasonic gauges command the established base. The steepest expansion runs through optical systems.
Application:
End-use context determines measurement precision requirements, environmental conditions, and regulatory compliance burdens.
- Metal Fabrication:Heavy-gauge steel and aluminum processing demands ruggedized ultrasonic units with extended probe cables for hot-rolling line integration. Ohio and Pennsylvania steel corridors are unbundling service contracts, separating hardware acquisition from calibration and software maintenance.
- Automotive:Stuttgart suppliers deploy wireless-enabled gauges to feed real-time thickness data into MES platforms. Robotic end-effector integration is compressing demand for manual operators while expanding recurring software licensing revenue.
- Aerospace:Composite qualification protocols mandate digital ultrasonic gauges with full traceability documentation.
- Electronics:Non-contact optical measurement prevents substrate damage on fragile PCBs.
Metal fabrication anchors current installed base. Electronics inspection is climbing the fastest.
End User:
Procurement authority and technical sophistication shape vendor engagement models and pricing structures.
- Manufacturers:Production line integration demands drive wireless connectivity and SCADA compatibility. Detroit and Wolfsburg automotive OEMs mount fixed-array probes on automated welding lines.
- QC Labs:ISO 17025 accreditation requirements govern procurement criteria across Europe and Asia. Third-party calibration certification delays extend gauge commissioning cycles.
- Research Institutions:Specialized applications require custom probe configurations and extended measurement ranges.
- Contractors:Field portability and battery life dominate specification priorities for on-site inspection work.
Manufacturers represent the largest procurement volume. QC Labs are gaining share fastest.
Technology:
Interface and connectivity architecture determines integration depth with Industry 4.0 infrastructure.
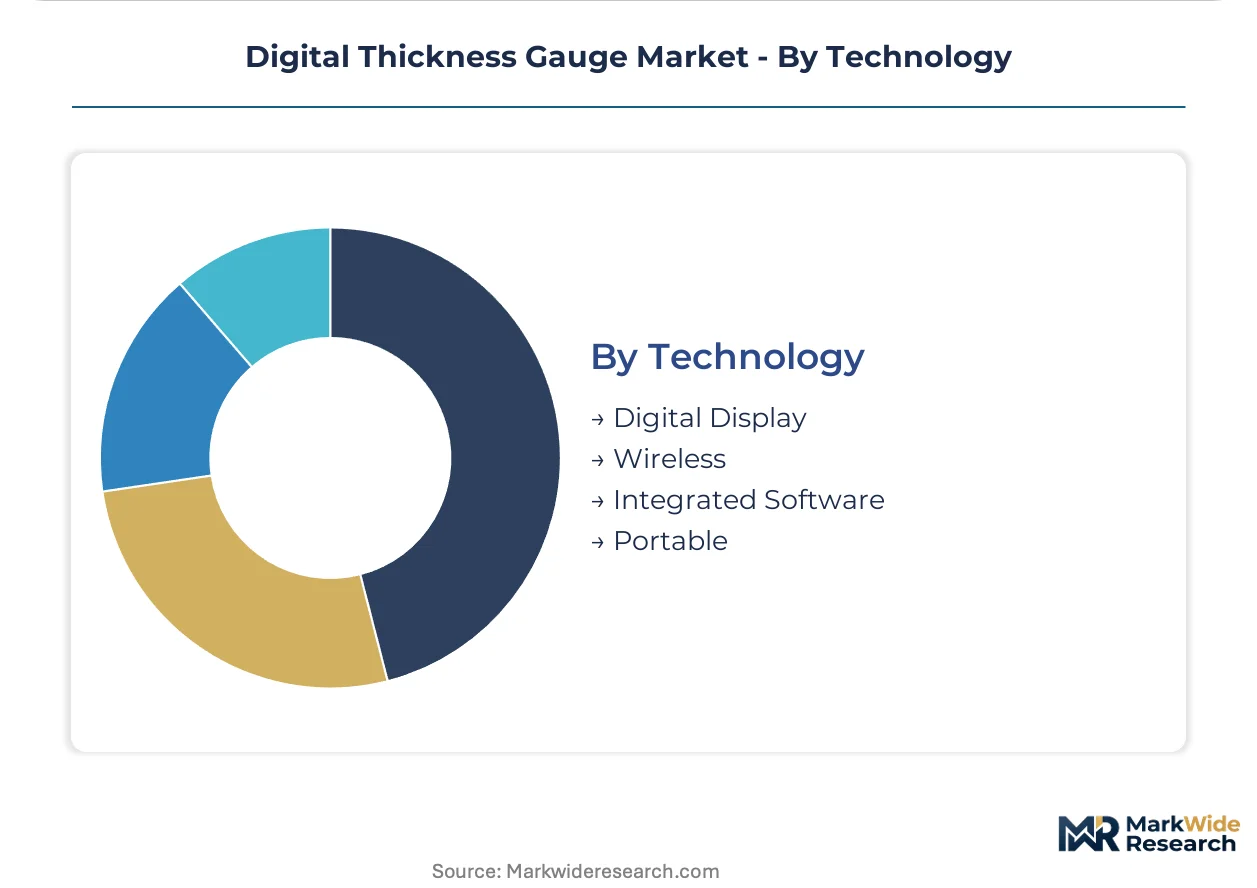
- Digital Display:High-contrast LCD and OLED readouts with backlighting for factory floor visibility.
- Wireless:Bluetooth and Wi-Fi connectivity feed real-time data into cloud analytics platforms. IEC 62443 compliance for wireless industrial devices opens premium positioning for pre-certified connectivity stacks.
- Integrated Software:Embedded edge computing enables real-time defect classification without latency to central servers. Korean and Chinese battery gigafactories drive demand for electrode coating verification analytics.
- Portable:Handheld battery-powered units with ruggedized housings for field deployment.
Digital display units hold the installed base. Wireless connectivity is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Machinery Directive enforcement anchors European demand, while aerospace NDT protocols and battery manufacturing expansion drive adoption across Asia-Pacific and North America. Calibration documentation requirements and Industry 4.0 retrofit waves are compressing replacement cycles in precision manufacturing corridors worldwide.
Germany
Stuttgart automotive suppliers deploy wireless-enabled gauges feeding real-time thickness data into MES platforms. REACH restrictions on nickel-based sensor finishes force redesigns of eddy current probe assemblies. Bavaria's precision engineering corridor around Munich concentrates ultrasonic gauge demand for aerospace tier-1 suppliers.
United States
FDA quality system regulations govern gauge calibration in medical device manufacturing across Minnesota and Massachusetts medical technology clusters. Boeing and Airbus tier-1 suppliers in Wichita mandate digital ultrasonic gauges for composite laminate inspection. Ohio and Pennsylvania steel processing corridors are unbundling service contracts, separating hardware acquisition from calibration maintenance.
China
Lithium-ion electrode coating thickness verification creates new ultrasonic gauge applications in Korean and Chinese battery gigafactories. MIIT industrial standards accelerate wireless connectivity adoption in Yangtze River Delta manufacturing zones. Shanghai and Shenzhen electronics clusters drive premium optical gauge demand for fragile PCB protection.
Japan
METI industrial digitization initiatives promote Industry 4.0 gauge integration in Nagoya automotive supply chains. Japanese ceramic substrate manufacturers control high-frequency piezoelectric transducer production for probe elements. Osaka and Tokyo precision instrumentation clusters sustain dominance in metrology heritage applications.
India
PLI scheme alignment for electronics manufacturing generates untapped demand for non-contact optical gauges in Tamil Nadu and Karnataka clusters. BIS quality certification requirements shape procurement criteria for domestic metal fabrication facilities. Gujarat and Maharashtra industrial corridors are deploying ultrasonic protocols for automotive component inspection.
Digital Thickness Gauge Market Competitive Landscape
Capability concentration sits with heritage metrology specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base stratifies across three tiers: precision-focused Japanese and European specialists, diversified testing equipment portfolios, and emerging Asian component suppliers. Dominant competitive moves include M&A for software platform integration and backward integration into transducer ceramic production.
Within the heritage metrology tier, Mitutoyo Corporation and Olympus Corporation exemplify capability concentration through decades-long precision engineering accumulation. Elcometer Limited anchors the specialized coatings inspection segment. These three occupy positions that reflect divergent strategic bets on ultrasonic versus electromagnetic versus optical measurement principles.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Olympus Corporation |
| Elcometer Limited |
| Cygnus Instruments |
| Extech Instruments |
| DeFelsko Corporation |
| Tritex NDT |
| NDT-KITS |
| Proceq SA |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Japanese and German piezoelectric ceramic substrate production is elevating transducer pricing power while compressing margins for gauge assemblers in North America and Europe. This utilization squeeze forces buyers into longer-term offtake commitments and accelerates backward integration strategies among tier-1 metrology vendors.
Pricing Analysis
Price spreads between German-engineered ultrasonic gauges and Asian-assembled equivalents span three to five multiples across identical specification bands. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 17025 certification grade and after-sales calibration bundling. Cost compression in the economy tier is intensifying because independent metrology service providers in Ohio and Pennsylvania now compete directly with manufacturer service arms. QC Labs exhibit the lowest price sensitivity due to accreditation-driven procurement rigidity, while metal fabrication contractors in emerging markets demonstrate acute elasticity.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn and Jabil Electronics holding capacity for gauge assembly and probe housing fabrication. Geographic supply concentration centers on Japan and Germany for piezoelectric transducers, China for electromagnetic probe windings, and Switzerland for precision optical encoders. Raw material dependencies draw from rare-earth ceramic substrates, nickel-copper alloy sensor housings, and sapphire optical windows. Single-source vulnerability in high-frequency transducer production creates exposure to export licensing disruptions. Distribution runs through manufacturer-direct channels for large OEM accounts and specialized industrial distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software maintenance and calibration service contracts are expanding faster than hardware revenue as North American metal fabricators unbundle procurement packages. This service-attach dynamic restructures vendor economics toward recurring revenue models.
For Market Incumbents: Harden defensive moats by accelerating captive production of piezoelectric ceramic substrates to neutralize Japanese supply concentration. Lock in ISO 17025 accreditation for captive calibration laboratories to forestall independent metrology service encroachment in the Midwest steel corridor. Vertical integration into transducer production represents the critical lever against emerging Asian component suppliers. For New Entrants and Emerging Players: Battery electrode inspection workflows in Korean and Chinese gigafactories represent the most penetrable entry point for ultrasonic gauge specialists without established aerospace qualification heritage. Indian electronics manufacturing clusters under PLI scheme coverage offer secondary white-space for non-contact optical gauge deployment. A calibration-service-first go-to-market angle bypasses incumbent hardware lock-in at QC Labs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless connectivity module production as semiconductor commoditization accelerates. Long-term viability favors targets with pre-certified IEC 62443 connectivity stacks and installed software platforms rather than pure hardware assemblers. The signal to watch is unbundling penetration rates in North American metal fabrication corridors as a leading indicator of margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Production | Mitutoyo and Olympus are securing captive ceramic substrate supply against Japanese export constraints. |
| Software Platform Acquisition | DeFelsko's integrated QC Lab analytics demonstrate recurring revenue multiples exceeding hardware-only valuations. |
| IEC 62443 Pre-Certification | Wireless gauge vendors with pre-certified connectivity stacks command premium positioning in Stuttgart automotive deployments. |
| Calibration Service Unbundling | Independent metrology providers in Ohio and Pennsylvania are fragmenting traditional manufacturer service monopolies. |
| Battery Inspection Application Development | Korean and Chinese gigafactories drive electrode coating verification demand for specialized ultrasonic probe arrays. |
Research Methodology
The analysis maps ultrasonic, electromagnetic, mechanical, and optical gauge sub-sectors, each validated through plant engineers, OEM procurement teams, QC Lab accreditation officers, and aftermarket service heads. Primary interviews with maintenance directors and metrology specialists across Stuttgart, Wichita, and Shanghai manufacturing clusters combined with secondary validation from SEC filings, customs trade records, ISO 17025 accreditation databases, and ECHA REACH substance restriction notices. Bottom-up unit shipment estimates triangulated against top-down industry value reconstructions.
Assumption sets held EU Machinery Directive enforcement timelines and aerospace NDT qualification standards fixed while varying Industry 4.0 adoption velocity and battery manufacturing expansion scenarios. Segmentation dimensions modeled include measurement principle, end-use application, connectivity architecture, and regional regulatory cluster. CAGRs derived from regression analysis against industrial capital expenditure cycles and manufacturing automation indices. Forecast inputs incorporated piezoelectric transducer supply constraints and REACH coating restriction implementation schedules.
Practitioners should monitor ECHA substance restriction expansion, MIIT wireless standard updates, and IEC 62443 certification adoption rates for early signals of competitive repositioning. Forecasts reflect documented assumptions regarding calibration cycle compression and service contract unbundling trajectories. Quarterly review of transducer export licensing patterns and independent metrology provider market share in North American steel corridors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
State Transition Testing Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
AI-Enabled Testing Tools Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Hour Meter Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Structure Tester Market