
 Metal Testing Equipment Market | 2026-2036
Metal Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Testing Equipment Market Foresight
Direct sales and distributor networks for metal testing equipment is fragmenting as manufacturers build hybrid channel models blending regional service centers with digital procurement portals. Thermo Scientific leverages its spectroscopy installed base to anchor recurring consumables revenue across North American quality control labs. ZwickRoell sustains dominance in European tensile testing through captive calibration services that lock in long-term contracts. Mitutoyo Corporation competes on dimensional metrology integration, extending its gauge portfolio into hardness testing workflows.
Metal testing equipment comprises instruments that measure mechanical properties, chemical composition, and structural integrity of metallic materials, typically operating across load ranges from nanonewtons to meganewtons and temperature extremes from cryogenic to over 1,000°C to certify fitness for industrial use. Spectrometers lead product type revenue due to their indispensability in foundry chemistry verification, while eddy current testing grows fastest in aerospace turbine blade inspection where surface defect detection demands non-contact methods. Among applications, automotive manufacturing remains the mature volume anchor, whereas oil and gas inspection commands premium pricing for hazardous-environment certification.
ASTM International governs tensile test protocols that dictate equipment specifications across U.S. manufacturing, while the EU Green Deal's embodied carbon tracking requirements force European mills to upgrade from periodic batch testing to continuous in-line spectrometry. Japan's METI maintains JIS standards that PMDA-aligned medical device manufacturers must satisfy for implant-grade titanium validation. Stakeholders must decide whether to prioritize destructive testing throughput for commodity metals or non-destructive precision for additive-manufactured aerospace components.
Market Dynamics
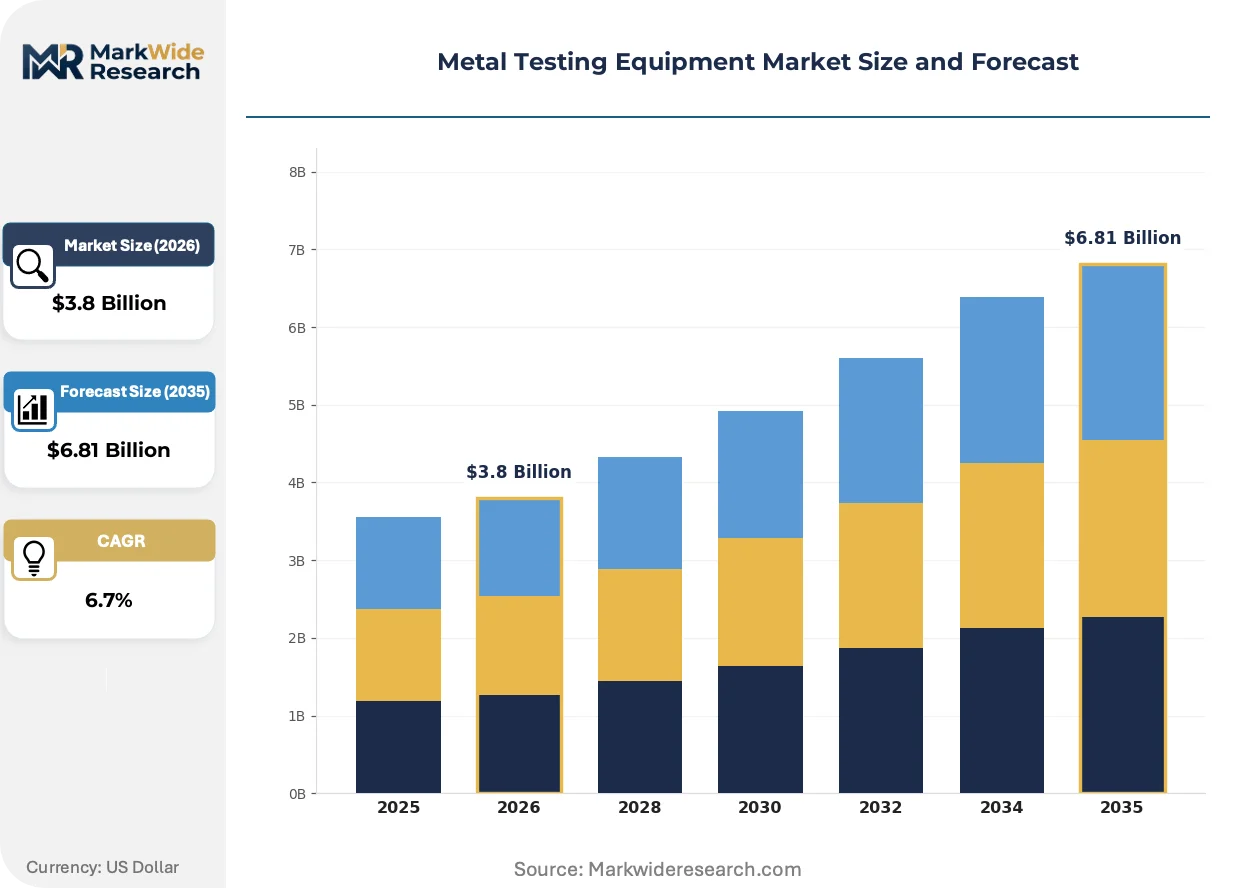
The transition from periodic batch testing to continuous in-line spectrometry is compressing equipment replacement cycles and forcing capital reallocation toward integrated quality systems that embed metrology directly within production lines.
Growth Catalysts
- EU Green Deal embodied carbon tracking:European steel mills must verify alloy chemistry at every production stage, mandating real-time spectrometer deployment across foundry operations.
- Additive manufacturing qualification protocols:Aerospace primes in Germany and the United States now require layer-by-line defect verification for titanium and nickel superalloy components, accelerating ultrasonic array adoption.
- Japan's precision instrument corridor:Concentrated demand from medical device manufacturers seeking JIS-certified implant-grade titanium validation drives hardness tester upgrades.
Market Restraints
- Helium supply concentration:Mass spectrometry leak detection depends on helium-3 and helium-4 sourcing concentrated in Qatar and the United States, exposing equipment utilization to geopolitical supply disruptions.
- High-purity reference material costs:Certified reference standards for calibrating optical emission spectrometers require rare earth elements subject to Chinese export licensing volatility.
- ASTM protocol revision lag:New additive manufacturing test methods await formal adoption, freezing capital commitment from risk-averse quality managers at Tier-1 automotive suppliers.
Strategic Opportunities
- South Korea shipbuilding quality labs:LNG carrier construction standards now mandate full-hull ultrasonic scanning, creating unserved demand for portable phased-array equipment in Ulsan and Geoje clusters.
- India BIS mandatory hallmarking expansion:Precious and non-precious metal purity verification requirements for jewelry and industrial alloys open distributor-channel potential for mid-range X-ray fluorescence units.
- Cloud-connected calibration services:Equipment vendors can unbundle after-sales revenue through subscription-based remote drift correction, targeting North American aerospace subcontractors with distributed facility networks.
Industry Challenges
- Multi-physics simulation expertise:Integrating eddy current, ultrasonic, and thermographic data requires physicists and data engineers scarce in traditional mechanical engineering talent pools.
- Legacy LIMS integration:New spectrometry platforms must interface with decades-old laboratory information management systems at Japanese automotive steel suppliers, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Testing Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardness Testers, Spectrometers, Ultrasonic Thickness Gauges, Tensile Test Machines Application: Aerospace, Automotive Manufacturing, Oil & Gas, Construction Technology: Non-Destructive Testing, Destructive Testing, X-Ray Fluorescence, Eddy Current Testing End User: Quality Control Labs, Research Institutions, Manufacturers, Third-Party Inspectors |
| Companies Covered | Thermo Scientific, ZwickRoell, Illinois Tool Works Inc., Mitutoyo Corporation, Shimadzu Corporation, Tinius Olsen, AMETEK Inc., QATM, Starrett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Testing Equipment Market Shifts & Advancements
Equipment architectures are converging around modular sensor platforms that decouple hardware from analytics software, enabling vendors to monetize through recurring calibration and algorithm updates rather than perpetual license sales.
Laser-induced breakdown spectroscopy is migrating from laboratory-bound alloy verification toward handheld field units for scrap metal sorting. Scrap processors in the United States and Germany now deploy LIBS guns at receiving docks to avoid melting contaminated batches. The technology is compressing the addressable market for traditional spark OES systems in secondary metals processing.
ASTM International's pending revision of E8/E8M tensile testing protocols will mandate digital image correlation for strain measurement, rendering manual extensometers non-compliant. U.S. automotive stampers and aluminum extruders face forced retooling of existing mechanical testing lines. The standard is accelerating servo-electric testing machine replacement of hydraulic frames.
Buyers now unbundle equipment purchase from service contracts, negotiating calibration and maintenance separately through third-party metrology providers. European automotive quality labs in Stuttgart and Wolfsburg lead this disintermediation, pressuring OEM-captive service organizations to match independent pricing. Channel margin compression is most severe in Germany where TÜV-affiliated competitors undercut manufacturer-direct service rates.
Metal Testing Equipment Market Segmentation
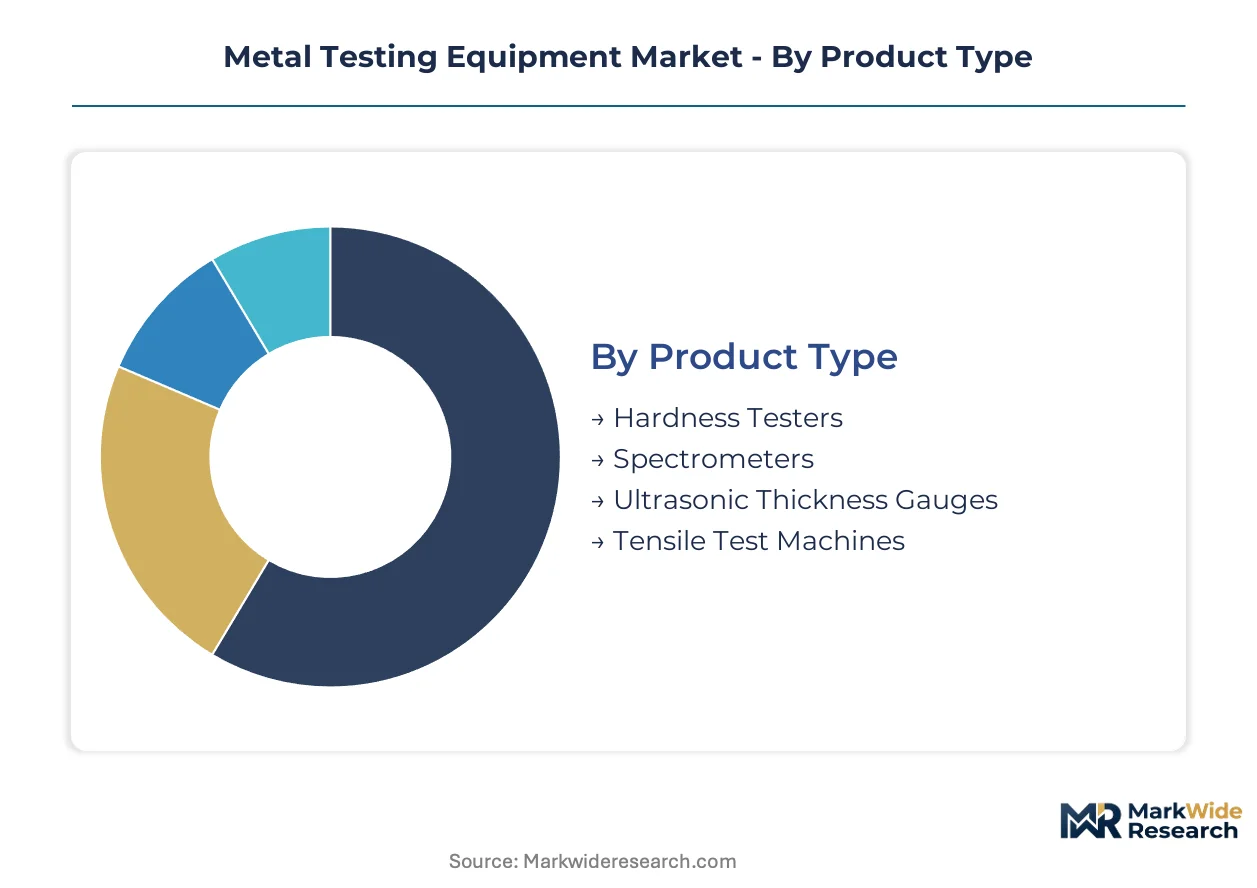
Equipment selection in metal testing follows distinct procurement rhythms. Capital-intensive tensile frames and spectrometers lock buyers into decade-long cycles, while portable hardness testers and ultrasonic gauges turn over faster as field inspection protocols evolve.
Product Type:
Replacement velocity varies sharply across instrument classes, with laboratory-bound systems exhibiting the longest depreciation schedules and handheld units refreshing on compressed timelines.
- Spectrometers:Optical emission and X-ray fluorescence systems analyze alloy chemistry through atomic excitation methods. Foundries in Germany and the United States deploy these at melt lines to verify chemistry before casting, driven by ASTM certification requirements and EU Green Deal embodied carbon tracking mandates.
- Hardness Testers:Rockwell, Brinell, and Vickers instruments measure resistance to localized plastic deformation through standardized indenter penetration. Japan's precision instrument corridor sustains demand from PMDA-aligned medical device manufacturers validating implant-grade titanium under JIS standards.
- Ultrasonic Thickness Gauges:Pulse-echo and phased-array systems measure wall thickness and internal defects through high-frequency sound wave propagation. South Korea's shipbuilding quality labs in Ulsan and Geoje deploy portable units for LNG carrier hull inspection.
- Tensile Test Machines:Servo-hydraulic and electromechanical frames apply controlled loads to characterize yield strength and elongation properties. U.S. automotive stampers face forced retooling as ASTM E8/E8M revisions mandate digital image correlation strain measurement.
Spectrometers dominate installed base. Ultrasonic thickness gauges are where expansion concentrates.
Application:
Pricing power concentrates in hazardous-environment certification, where failure consequences justify premium instrumentation spend.
- Oil & Gas:Pipeline integrity management and pressure vessel certification require hydrostatic testing and radiographic inspection protocols. Offshore platform operators in the North Sea and Gulf of Mexico specify equipment rated for explosive atmospheres under ATEX and IECEx directives.
- Aerospace:Turbine blade and airframe component qualification demands layer-by-line defect verification for titanium and nickel superalloys. German and U.S. primes now mandate ultrasonic array adoption for additive-manufactured parts.
- Automotive Manufacturing:Stamping, casting, and extrusion quality control relies on statistical process control sampling. High-volume production lines in Stuttgart and Wolfsburg integrate eddy current testing for surface crack detection on crankshafts and camshafts.
- Construction:Structural steel verification and weld quality assessment support infrastructure project certification. Bridge fabricators deploy portable hardness testers and magnetic particle inspection for field validation of heat-affected zones.
Automotive manufacturing anchors volume throughput. Oil and gas commands the steepest price premiums.
Technology:
Non-contact methods are displacing mechanical probing in surface-sensitive applications where specimen preservation matters.
- Non-Destructive Testing:Ultrasonic, radiographic, and electromagnetic methods evaluate material integrity without specimen consumption. Aerospace turbine blade inspection in Germany and the United States drives eddy current adoption for detecting subsurface cracks in single-crystal superalloys.
- Eddy Current Testing:Electromagnetic induction detects surface and near-surface defects through conductivity perturbations. The technology climbs fastest in heat exchanger tube inspection and aircraft wheel bolt hole evaluation where probe access is constrained.
- Destructive Testing:Tensile, impact, and fatigue tests consume specimens to characterize mechanical performance limits. Commodity metal producers in India and Brazil prioritize destructive throughput for batch release certification.
- X-Ray Fluorescence:Energy-dispersive and wavelength-dispersive systems determine elemental composition through characteristic X-ray emission. Scrap processors deploy handheld units at receiving docks to avoid melting contaminated batches.
Destructive testing retains volume dominance in commodity metals. Eddy current testing gains share fastest in precision aerospace workflows.
End User:
Procurement autonomy fragments as manufacturers internalize quality functions previously outsourced to independent laboratories.
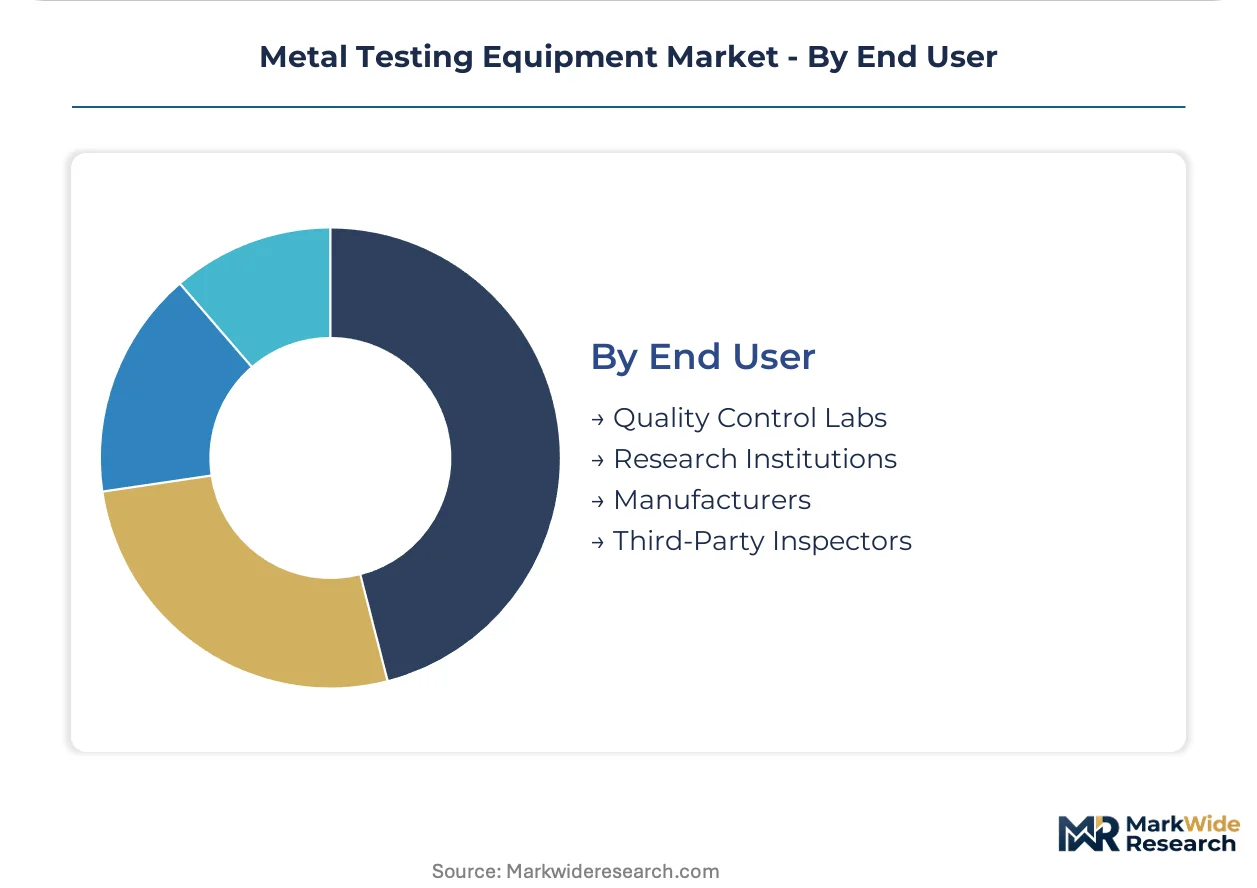
- Quality Control Labs:Captive and independent facilities execute incoming inspection, in-process monitoring, and final certification testing. European automotive quality labs in Stuttgart and Wolfsburg now unbundle equipment purchase from service contracts, negotiating calibration separately through third-party metrology providers.
- Manufacturers:Steel mills, foundries, and fabrication shops embed testing directly within production lines. EU Green Deal embodied carbon tracking forces European mills to upgrade from periodic batch testing to continuous in-line spectrometry.
- Third-Party Inspectors:TÜV, SGS, and Bureau Veritas affiliates provide independent certification for regulatory compliance and customer assurance. German TÜV-affiliated competitors undercut manufacturer-direct service rates, pressuring OEM-captive service organizations.
- Research Institutions:Universities and national laboratories advance test method development and material characterization standards. ASTM protocol revision committees depend on institutional research to validate new additive manufacturing test methods.
Quality control labs retain the deepest instrument installed base. Manufacturers drive near-term expansion as production-integrated metrology spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel and Corpus Christi LNG export terminals anchor United States demand for ultrasonic thickness gauges and radiographic inspection systems serving pipeline integrity mandates.
United States
Offshore platform operators in the Gulf of Mexico specify ATEX-rated equipment for explosive atmosphere certification, while automotive stampers in Michigan and Ohio face forced retooling under pending ASTM E8/E8M revisions. The FAA collaborates with aerospace primes on additive manufacturing qualification protocols that accelerate ultrasonic array adoption for titanium components.
Germany
Steel mills along the Rhine-Ruhr corridor deploy continuous in-line spectrometry to satisfy EU Green Deal embodied carbon tracking requirements. TÜV-affiliated competitors undercut manufacturer-direct service rates in Stuttgart and Wolfsburg quality labs, pressuring OEM-captive calibration organizations. The KBA enforces automotive material certification standards that dictate tensile testing equipment specifications.
Japan
METI-administered JIS standards compel PMDA-aligned medical device manufacturers to validate implant-grade titanium through certified hardness testing workflows. The precision instrument corridor concentrated in Kanagawa and Tokyo prefectures sustains demand for Rockwell and Vickers systems. Osaka-based foundries integrate optical emission spectrometry at melt lines for chemistry verification.
South Korea
LNG carrier construction standards now mandate full-hull ultrasonic scanning across shipbuilding quality labs in Ulsan and Geoje. MFDS-aligned medical device exporters drive secondary demand for material validation equipment. Daegu-Gyeongbuk manufacturing clusters adopt eddy current testing for automotive component surface defect detection.
India
BIS mandatory hallmarking expansion for precious and non-precious metals creates distributor-channel openings for mid-range X-ray fluorescence units in Surat and Mumbai jewelry manufacturing centers. Steel Authority of India and JSW Steel integrate continuous testing at Durgapur and Vijayanagar mills. The PLI scheme for specialty steel attracts spectrometer deployment for alloy chemistry verification.
Metal Testing Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, load cells, and calibration standards. The vendor base stratifies across three layers: diversified instrumentation conglomerates with spectroscopy and metrology portfolios; captive testing machine builders serving automotive and aerospace certification chains; and regional fabricators concentrating on portable field units for construction and energy inspection. Consolidation pressure concentrates among mid-scale European and Japanese equipment builders seeking geographic coverage. Strategic moves center on unbundling after-sales revenue through subscription calibration services and backward integration into reference material production to secure supply against rare earth export licensing volatility.
Among diversified instrumentation conglomerates, Thermo Scientific and AMETEK Inc. occupy positions exemplifying the recurring consumables revenue model anchored to installed spectroscopy bases. ZwickRoell represents the European captive testing machine archetype with calibration-locked long-term contracts. Mitutoyo Corporation and Shimadzu Corporation anchor the precision metrology integration strategy extending dimensional gauge portfolios into hardness testing workflows. Tinius Olsen and Starrett sit within the heritage mechanical testing tier facing displacement pressure from servo-electric frame adoption. Illinois Tool Works Inc. exemplifies the industrial conglomerate structure with testing equipment as one vertical among diversified manufacturing technology holdings.
| Leading Market Players |
|---|
| Thermo Scientific |
| ZwickRoell |
| Illinois Tool Works Inc. |
| Mitutoyo Corporation |
| Shimadzu Corporation |
| Tinius Olsen |
| AMETEK Inc. |
| QATM |
| Starrett |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr freight corridor's logistics costs compress margins for European spectrometer shipments while simultaneously amplifying price differentiation between premium in-line systems and economy-grade portable units. Supply concentration in German and Japanese precision manufacturing clusters forces buyers in India and Southeast Asia to absorb elevated landed costs or accept extended lead times from distributor intermediaries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs equipment procurement. Premium tiers command certification-grade pricing for ATEX-rated spectrometers and FAA-aligned ultrasonic arrays, while economy tiers serve Indian jewelry hallmarking and Brazilian scrap metal sorting. Price differentiation rests on calibration traceability and embedded software analytics. Cost compression in the standard tier is intensifying because European automotive labs unbundle service contracts and source calibration through TÜV-affiliated competitors. Third-party inspection houses exhibit highest price sensitivity due to competitive bidding pressures, whereas aerospace primes prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration among German machine builders and Japanese precision instrument fabricators anchors capacity for tensile frames and hardness testers. Geographic supply concentrates in Germany, Japan, and the United States for high-end laboratory systems, with China and South Korea supplying mid-range portable units. Raw material dependencies span rare earth elements for optical emission spectrometers, helium isotopes for mass spectrometry leak detection, and high-purity reference standards subject to Chinese export licensing. Single-source vulnerability in certified reference material supply threatens calibration continuity. Distribution runs through hybrid models blending manufacturer-direct regional service centers with authorized distributor networks in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment vendors face substitution pressure from laser-induced breakdown spectroscopy handheld units displacing traditional spark OES in scrap metal processing. Defense requires preemptive moves to lock in recurring revenue streams before technology commoditization accelerates.
For Market Incumbents: Pre-empt LIBS displacement by bundling cloud-connected calibration subscriptions with legacy spectrometer installed bases. Backward integration into rare earth reference material production secures supply against Chinese export volatility. Channel control through captive service organizations in Stuttgart and Wolfsburg quality labs resists third-party metrology disintermediation.
For New Entrants and Emerging Players: Portable phased-array ultrasonic equipment for South Korean LNG carrier hull inspection represents the most penetrable entry point given unserved demand in Ulsan and Geoje clusters. Mid-range X-ray fluorescence units for Indian BIS hallmarking expansion offer distributor-channel leverage without competing against entrenched laboratory system vendors. Go-to-market through regional calibration service partnerships bypasses capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Modular sensor platform developers with software-decoupled architectures present attractive acquisition targets given recurring revenue potential from algorithm updates. Long-term viability hinges on transition from perpetual license sales to subscription monetization. Watch ASTM E8/E8M protocol adoption velocity as inflection indicator for servo-electric testing machine replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reference Materials | Captive supply of rare earth certified standards insulates against Chinese export licensing volatility. |
| Cloud-Connected Calibration Subscription | Remote drift correction services target North American aerospace subcontractors with distributed facilities. |
| Modular Sensor Platform Development | Hardware-software decoupling enables recurring algorithm update revenue beyond perpetual licenses. |
| Regional Service Center Expansion | Hybrid channel models blend direct support with digital procurement portals in East Asian manufacturing clusters. |
| LIBS Handheld Field Unit Migration | Laboratory-bound alloy verification shifts to scrap dock sorting, compressing spark OES addressable market. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quality control lab managers, OEM procurement directors, aftermarket service heads, and third-party inspection engineers. Secondary validation drew from ASTM International protocol documentation, EU Green Deal regulatory filings, Japanese METI JIS standards publications, and customs trade data for spectrometer and hardness tester shipments. Bottom-up equipment unit economics triangulated against top-down market sizing across product type, application, technology, and end-user segmentation dimensions.
Calibration against historical replacement cycles and regulatory compliance timelines anchored projection reliability across the analysis window. Segmentation modeling spanned product type, application technology, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from equipment shipment velocity correlated with industrial production indices and capital expenditure surveys. Industry-specific forecast inputs incorporated EU embodied carbon tracking mandate implementation pace and additive manufacturing qualification protocol adoption rates.
Practitioners should monitor helium supply disruptions from Qatar and United States sourcing concentration, ASTM protocol revision adoption lags, and Chinese rare earth export licensing volatility for early signals of forecast deviation. Quarterly review of equipment replacement cycle compression indicators and service contract unbundling rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Calibration Management Software Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market