
 Lead-To-Account Matching and Routing Software Market | 2026-2036
Lead-To-Account Matching and Routing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lead-To-Account Matching and Routing Software Market Foresight
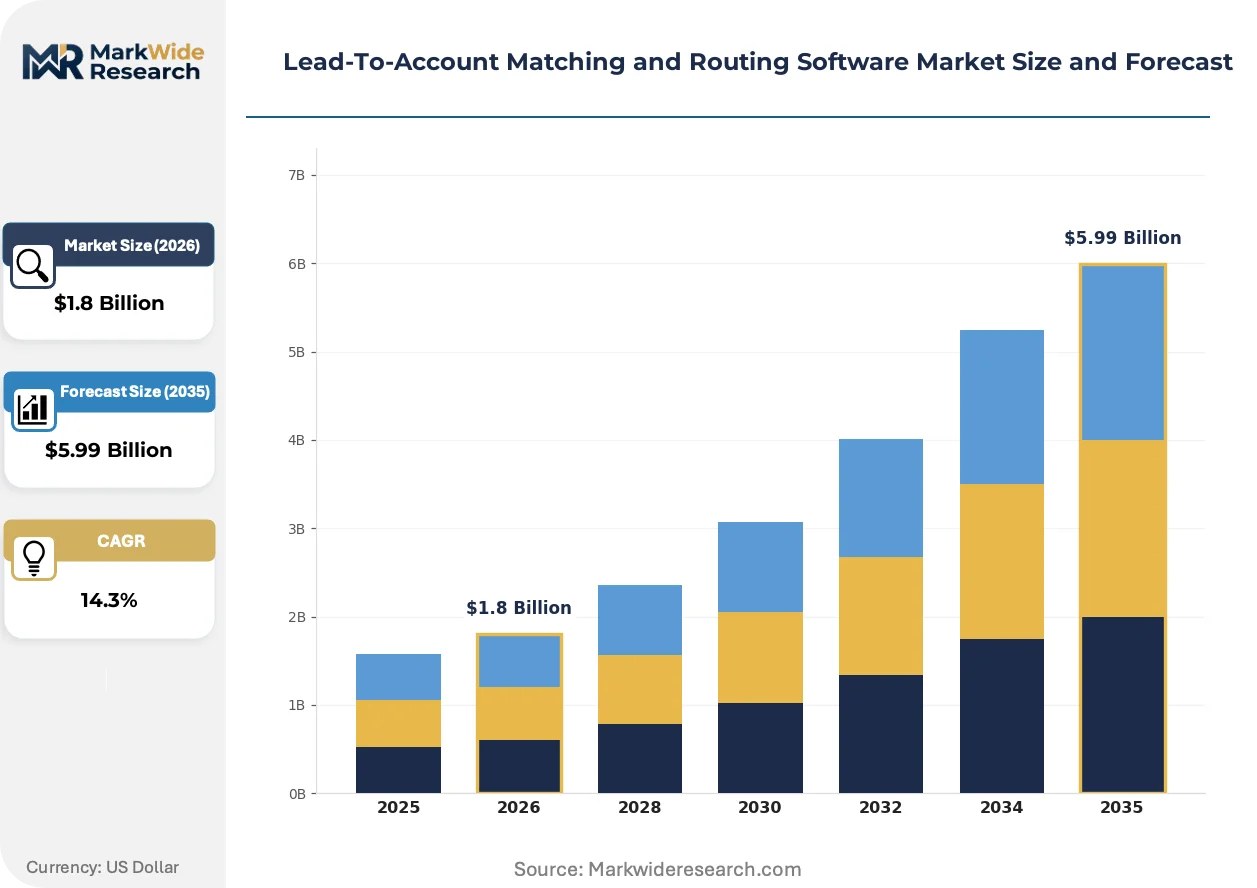
API-first architecture is rewriting how lead-to-account matching engines embed into CRM ecosystems. Openprise leverages native data orchestration layers to sustain competitive differentiation in enterprise deployments. LeanData anchors its position through deep Salesforce-native routing logic, while ZoomInfo extends its data asset into matching workflows through unified platform integration.
Lead-to-account matching and routing software applies deterministic and probabilistic algorithms to associate inbound leads with existing account records, then automatically distributes qualified opportunities to designated sales representatives based on territory, industry, or engagement scoring rules. Cloud-based solutions command the dominant deployment share as organizations prioritize elastic infrastructure and reduced maintenance overhead over on-premises installations. Among end users, large enterprises generate the deepest demand for integrated platforms combining real-time matching with analytics dashboards, whereas SMBs gravitate toward standalone software with faster implementation cycles.
The Federal Trade Commission and state-level privacy frameworks in the United States shape data handling requirements for vendors processing contact records across state lines, while the EU AI Act and GDPR impose algorithmic transparency and consent standards on matching engines operating in European jurisdictions. ISO 27001 certification has become a baseline procurement filter for financial institutions evaluating vendor security posture. Stakeholders must weigh the trade-off between routing speed and explainability as regulatory scrutiny of automated decision-making intensifies.
Market Dynamics
API-first architecture is concentrating matching-engine deployments inside CRM ecosystems, compressing implementation timelines from quarters to weeks while forcing vendors to abandon monolithic platform strategies.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic explainability requirements in European jurisdictions are accelerating investment in deterministic matching protocols that audit lead-to-account associations.
- Cloud infrastructure elasticity:Enterprise buyers prioritize SaaS routing solutions that scale compute resources during quarterly close periods without capital expenditure.
- Financial services procurement:ISO 27001 certification has become a non-negotiable filter for banks evaluating lead-routing vendors, consolidating demand around compliant platforms.
Market Restraints
- Data residency fragmentation:Divergent national cloud sovereignty laws in Germany, France, and Australia force vendors to maintain redundant regional infrastructure, elevating operational costs.
- Legacy CRM entrenchment:Deep customization of on-premises Salesforce instances creates technical debt that resists cloud-native routing migration.
- Talent scarcity in MLOps:Shortage of engineers capable of tuning probabilistic matching algorithms constrains vendor product development velocity.
Strategic Opportunities
- Mid-market underpenetration:Standalone routing tools with rapid deployment cycles remain underserved among SMBs relative to integrated enterprise suites.
- Real-time intent data fusion:Convergence of third-party intent signals with first-party CRM records enables predictive lead scoring before form submission.
- US state privacy patchwork:Fragmented compliance requirements across California, Virginia, and Colorado create demand for jurisdiction-aware routing logic.
Industry Challenges
- Cross-system identity resolution:Reconciling lead records across Marketo, HubSpot, and Salesforce instances demands specialized data engineering expertise that commands premium compensation.
- Algorithmic bias audit requirements:Demonstrating equitable territory assignment across demographic segments requires documentation infrastructure most vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead-To-Account Matching and Routing Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-Based Solutions, Integrated Platforms, Enterprise Applications Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: SMBs, Large Enterprises, Technology Firms, Financial Institutions Feature Set: Real-Time Matching, Automated Routing, Analytics Dashboard, Integration Capabilities |
| Companies Covered | Openprise, RingLead, Leadspace, LeanData, ZoomInfo, LeadAngel, Apollo.io, Traction Complete, Demandbase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead-To-Account Matching and Routing Software Market Shifts & Advancements
Matching engines are virtualizing their deployment topology, embedding directly inside customer data platforms rather than operating as standalone routing layers.
Deterministic graph-matching technology is virtualizing the core association layer between inbound leads and account records. Mid-market SaaS vendors are adopting these engines at twice the pace of enterprise buyers, compressing sales cycle attribution from weeks to hours. The structural consequence is collapsing demand for manual lead-review queues inside sales operations teams.
The EU AI Act's algorithmic transparency requirements are forcing vendors to document decision pathways for territory-assignment logic. This regulatory pressure is elevating procurement scrutiny of black-box probabilistic models in favor of auditable deterministic rules. European financial services deployments are responding by mandating vendor-provided explanation interfaces before contract execution.
Buyer procurement patterns are compressing vendor evaluation cycles from multi-quarter RFP processes to pilot-first engagements with 30-day proof-of-concept milestones. This behavioral shift is displacing traditional enterprise sales methodologies with product-led growth tactics. The United States technology sector exhibits the most acute acceleration, with revenue operations leaders demanding functional demonstrations before security review completion.
Lead-To-Account Matching and Routing Software Market Segmentation
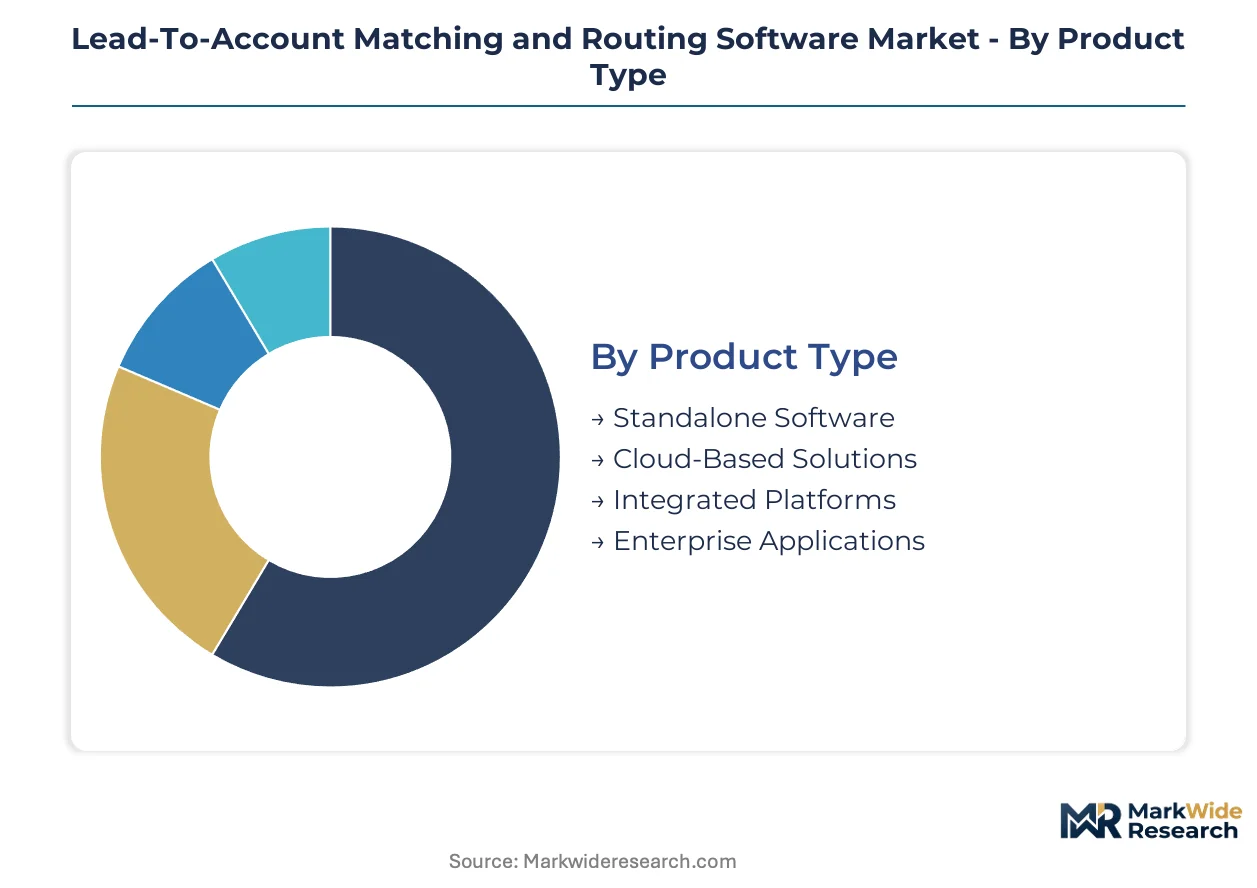
Lead-to-account matching and routing software exhibits divergent sales cycles across deployment configurations and buyer profiles. Segment-level cycle times range from weeks for cloud-native SMB tools to quarters for enterprise-integrated suites. Understanding these velocity differences shapes vendor resource allocation and partnership strategies.
Product Type:
Cycle times compress most dramatically for API-native offerings while enterprise applications demand extended procurement runway.
- Cloud-Based Solutions:Elastic infrastructure enables rapid scaling during quarterly close periods without capital expenditure. United States technology firms drive concentration here, prioritizing reduced maintenance overhead and seamless CRM embedding over customization depth.
- Integrated Platforms:Unified data orchestration layers combine matching engines with customer data platforms and analytics stacks. Large enterprises in financial services generate deepest demand, compelled by ISO 27001 procurement mandates and cross-system identity resolution requirements.
- Standalone Software:Purpose-built routing tools with faster implementation cycles attract SMB buyers seeking immediate deployment without platform lock-in.
- Enterprise Applications:Comprehensive suites with deep customization capabilities serve complex multi-territory sales organizations with legacy system dependencies.
Cloud-based solutions anchor the volume base while integrated platforms gain share at the steepest rate.
Deployment Model:
Cost tier stratification separates capital-light subscriptions from infrastructure-heavy private installations.
- Public Cloud:Shared infrastructure delivers lowest total cost of ownership with automatic updates and elastic compute. North American SaaS vendors concentrate demand here, exploiting mature hyperscaler ecosystems in the United States.
- Hybrid Cloud:Split workloads balance sensitive data residency with scalable processing. European financial institutions under GDPR and EU AI Act mandates drive adoption, requiring algorithmic transparency for territory-assignment logic.
- Private Cloud:Dedicated single-tenant environments satisfy stringent data sovereignty requirements in Germany, France, and Australia.
- On-Premises:Legacy installations persist where deep Salesforce customization creates technical debt resistant to cloud migration.
Public cloud deployments dominate current revenue while hybrid configurations climb the fastest as regulatory fragmentation intensifies.
End User:
Customer type determines pricing tolerance and implementation complexity tolerance in inverse proportion.
- Large Enterprises:Multi-division sales operations require real-time matching with analytics dashboards and cross-territory visibility. United States enterprise hubs generate deepest demand, driven by sales-tech stack complexity and revenue operations maturity.
- SMBs:Lean sales teams prioritize standalone tools with 30-day proof-of-concept milestones over integrated suites. Technology sector startups in California and New York exhibit acute pilot-first procurement patterns.
- Technology Firms:High-velocity sales environments demand API-first embedding into existing CRM ecosystems with minimal implementation friction.
- Financial Institutions:Banks and insurers mandate ISO 27001 certification and jurisdiction-aware routing logic for cross-state compliance.
Large enterprises anchor the volume base while SMBs expand most quickly as vendor product-led growth tactics mature.
Feature Set:
Application criticality separates table-stakes functionality from competitive differentiators in procurement evaluations.
- Real-Time Matching:Sub-second lead-to-account association using deterministic graph algorithms eliminates manual review queues. Technology firms in the United States demand this capability to compress attribution windows from weeks to hours.
- Automated Routing:Territory, industry, and engagement-scoring rules distribute qualified opportunities without human intervention. Financial institutions require auditable decision pathways under EU AI Act transparency mandates.
- Analytics Dashboard:Visualization layers track match accuracy, routing speed, and conversion outcomes for revenue operations teams.
- Integration Capabilities:Native connectors to Marketo, HubSpot, and Salesforce instances reduce specialized data engineering requirements.
Real-time matching anchors the volume base while automated routing gains share at the steepest rate as algorithmic audit requirements spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based SaaS vendors export lead-to-account matching platforms to enterprise buyers across Germany, United Kingdom, and Japan, with cloud infrastructure enabling rapid cross-border deployment.
United States
Technology firms in California and New York drive concentrated demand for API-first routing solutions that compress sales cycles. The Federal Trade Commission enforces state-level privacy frameworks governing cross-border data handling. Revenue operations teams in Silicon Valley prioritize 30-day pilot engagements over traditional RFP processes.
Germany
Financial institutions in Frankfurt require jurisdiction-aware routing logic for multi-territory compliance. The country's national data protection regulator enforces strict cloud sovereignty standards under federal privacy law. Bavarian enterprise hubs are mandating vendor-provided explanation interfaces for algorithmic transparency.
United Kingdom
London-based SaaS vendors and enterprise buyers prioritize hybrid cloud deployments balancing elastic compute with data residency controls. UK financial regulators impose operational resilience requirements on automated decision-making systems. The Thames Valley technology corridor exhibits acute procurement acceleration toward pilot-first vendor selection.
Japan
Enterprise sales organizations in Tokyo demand deep Salesforce-native integration for complex multi-division routing. METI guidelines shape data handling standards for cross-border SaaS implementations. Osaka-based manufacturing conglomerates are consolidating legacy CRM instances onto cloud-native matching engines.
Australia
Sydney and Melbourne financial services firms mandate ISO 27001 certification as a baseline procurement filter. The country's national privacy regulator enforces consent standards for automated lead processing. Australian cloud sovereignty laws force vendors to maintain dedicated regional infrastructure, elevating operational costs for market entry.
Lead-To-Account Matching and Routing Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: data-asset platforms, CRM-native specialists, and standalone routing tools. Tier-one players leverage existing customer data platforms to embed matching engines. Tier-two vendors compete on Salesforce-native deployment speed. Tier-three challengers target mid-market buyers with rapid implementation cycles. Dominant competitive moves include API-first architecture development and strategic partnerships with hyperscaler cloud providers.
Among data-asset heavyweights, ZoomInfo occupies a position exemplifying unified platform integration, while Openprise and LeanData represent contrasting archetypes in enterprise deployment methodology. ZoomInfo exemplifies the data-centric approach extending proprietary contact databases into routing workflows. Openprise anchors the data orchestration specialist tier with native integration layers. LeanData sits within the CRM-native category through deep Salesforce embedding. These three companies collectively illustrate how vendor positioning fragments across data ownership, platform integration depth, and deployment velocity vectors.
| Leading Market Players |
|---|
| Openprise |
| RingLead |
| Leadspace |
| LeanData |
| ZoomInfo |
| LeadAngel |
| Apollo.io |
| Traction Complete |
| Demandbase |
| Others |
Supply & Pricing Matrix
Silicon Valley's hyperscaler infrastructure concentration anchors SaaS delivery economics for lead-to-account matching vendors, translating cloud capacity abundance into subscription pricing flexibility that compresses margins for pure-play routing specialists while rewarding integrated platform providers.
Pricing Analysis
Cloud-native API tiers command premium positioning over legacy on-premises licensing, with deterministic matching engines priced above probabilistic alternatives due to EU AI Act auditability requirements. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with Salesforce-native deployment carrying brand premium over standalone tools. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler economies of scale enable aggressive vendor discounting. SMB buyers exhibit acute price sensitivity, while financial institutions prioritize ISO 27001 certification over cost minimization.
Supply Chain Analysis
Amazon Web Services, Microsoft Azure, and Google Cloud Platform hold dominant contract-manufacturing capacity for routing software infrastructure, with regional data center expansion in Germany, Australia, and Japan addressing sovereignty mandates. Compute instances, identity verification APIs, and CRM connector libraries constitute critical input dependencies. Single-source vulnerability concentrates in Salesforce-native deployment channels, where platform dependency creates lock-in risk. Distribution runs through direct enterprise sales teams for large accounts and self-service portals for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architecture disruption is accelerating market consolidation, with EU AI Act transparency mandates creating regulatory moats that favor vendors with auditable deterministic matching protocols over black-box probabilistic alternatives.
For Market Incumbents: Pre-empt cloud-native challengers by embedding matching engines directly into customer data platforms rather than maintaining standalone routing layers. ISO 27001 certification investment defends financial services procurement position against emerging data-asset platforms. Backward integration into proprietary contact databases reduces dependency on third-party data suppliers. For New Entrants and Emerging Players: Establish a beachhead in mid-market technology firms seeking 30-day pilot engagements without platform lock-in. SMB sales operations remain the most penetrable segment, with standalone tools addressing implementation velocity demands that integrated suites cannot match. Product-led growth tactics with freemium API tiers outperform traditional enterprise sales methodologies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors data-orchestration specialists with native integration layers over CRM-native deployment tools facing platform dependency risk. Long-term viability hinges on jurisdiction-aware routing logic capabilities as data residency fragmentation intensifies. Watch EU AI Act enforcement patterns as the signal for algorithmic transparency premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding matching engines into CDPs reduces standalone routing layer demand from enterprise buyers. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure accelerate regional data center deployment for sovereignty compliance. |
| Acquisition of Specialist Firm | Deterministic graph-matching technology purchases compress sales cycle attribution windows for mid-market SaaS vendors. |
| Geographic Expansion | Frankfurt and Sydney infrastructure addresses German cloud sovereignty and Australian ISO 27001 procurement filters. |
| Product Launch | Explanation interfaces for algorithmic transparency satisfy Bavarian enterprise mandates under EU AI Act requirements. |
Research Methodology
A standing panel of revenue operations leaders, CRM integration specialists, SaaS procurement officers, and data engineering directors provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie enterprise software rankings, and EU regulatory transparency databases. Bottom-up deployment estimates triangulated against top-down SaaS spend projections.
Scenario-bracketing framed projections across the analysis window, modeling deployment model, organization size, vertical integration complexity, and regional adoption pattern dimensions. CAGRs derived from elasticity-adjusted subscription revenue trajectories, with algorithmic audit requirement penetration and cloud migration velocity as software-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in enterprise software budget cycles and interest rate sensitivity would shift the trajectory. Forecasts reflect assumptions about CRM consolidation patterns and regulatory enforcement intensity. Quarterly review of EU AI Act implementation guidance and US state privacy patchwork expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Continuous Testing Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Trading Software Market
Software & Services
Deck Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
3D Animation Production Software Market
Software & Services
Online Donation Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
G Suite Technology Services Market
Software & Services
Paraphrasing Tools Market
Software & Services
UI Design Software Market
Software & Services
Lead Mining Software Market
Software & Services
Interior Design Software Market
Software & Services
Nonconformance Management Software Market