
 Global Continuous Testing Market | 2026-2036
Global Continuous Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Testing Market Foresight
Subscription-based access to containerized test environments is broadening what vendors monetize beyond perpetual licenses. Tricentis leverages its model-based automation engine to anchor enterprise accounts across complex SAP and Salesforce landscapes. IBM Corporation sustains relevance through deep integration with Red Hat OpenShift pipelines. EPAM Systems differentiates via engineering-led consulting that embeds continuous validation into client DevOps workflows.
Continuous testing denotes the practice of executing automated tests throughout the software delivery pipeline to provide immediate feedback on business risks associated with a software release candidate. Functional parameters include test orchestration across unit, integration, system, and acceptance layers with feedback loops measured in minutes rather than days. Cloud-based deployment leads in new bookings as enterprises retire on-premises test grids for elastic Kubernetes-native infrastructure. API testing represents the fastest-expanding solution type, reflecting microservices architecture proliferation and the need to validate inter-service contracts at deployment velocity.
The EU AI Act imposes conformity assessment requirements on high-risk automated systems, directly expanding mandatory validation scope for European enterprises. FDA software-as-a-medical-device guidance and HIPAA security rule enforcement in the United States create parallel compliance-driven demand for documented, repeatable test evidence. ISO/IEC 25010 quality standards and IEC 62304 medical device software lifecycle requirements further shape product design priorities across regulated verticals. Stakeholders must weigh whether to build captive testing platforms or partner with specialized vendors as regulatory scope widens beyond traditional quality assurance boundaries.
Market Dynamics
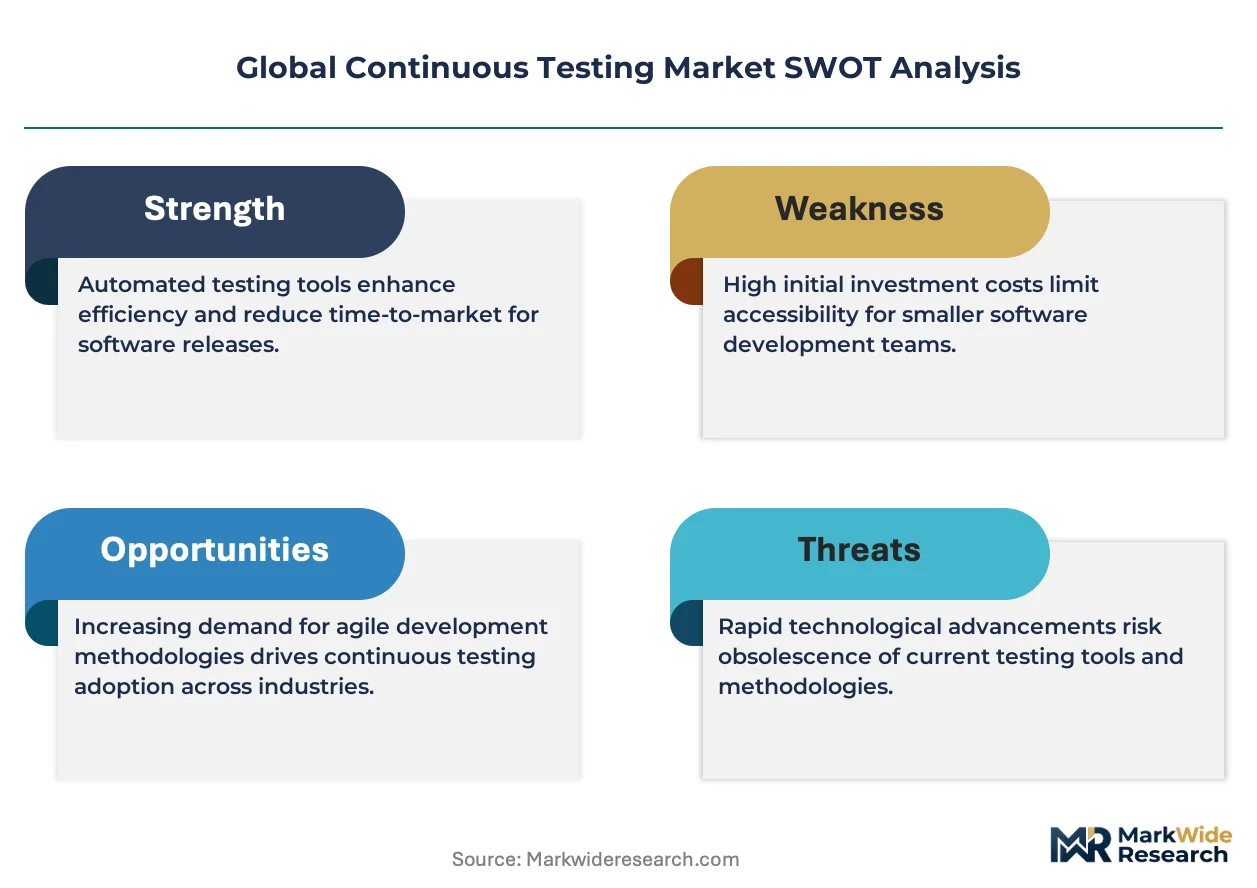
Regulatory mandates for algorithmic accountability are compressing validation cycles and forcing enterprises to embed automated quality gates directly into CI/CD pipelines rather than treating testing as a terminal phase.
Growth Catalysts
- EU AI Act conformity assessments:High-risk automated decision systems in European financial services and healthcare now require documented, repeatable test evidence before deployment authorization.
- Microservices architecture proliferation:API contract validation at deployment velocity has become non-negotiable for cloud-native application teams managing hundreds of interdependent services.
- DevSecOps maturity in the United States:Enterprise software engineering teams are mandating security and quality gates at every pipeline stage, expanding automated test coverage requirements.
Market Restraints
- Specialized engineering talent scarcity:Shortage of professionals capable of designing model-based test automation frameworks for complex enterprise landscapes limits implementation velocity.
- Legacy system integration friction:Mainframe and monolithic core systems in banking and insurance resist containerized test environment deployment, fragmenting toolchain standardization.
- Elastic infrastructure cost volatility:Cloud-native test grid scaling introduces unpredictable compute expenditure patterns that conflict with fixed IT budget cycles in regulated industries.
Strategic Opportunities
- Medical device software lifecycle gaps:IEC 62304 compliance requirements for SaMD manufacturers create demand for continuous validation platforms that automate documentation traceability.
- India's software export sector:Engineering services providers serving North American and European clients are building captive testing capabilities to capture higher-margin validation work.
- Shift-left security convergence:Integration of SAST/DAST tooling with functional test orchestration platforms enables unified risk scoring that security teams will pay premium pricing to access.
Industry Challenges
- Test data management complexity:GDPR and HIPAA constraints on production data usage force synthetic data generation investments that delay pipeline implementation timelines.
- Toolchain fragmentation:Enterprises average seven distinct testing tools across unit, integration, performance, and security layers, creating orchestration overhead and reporting inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Testing Market |
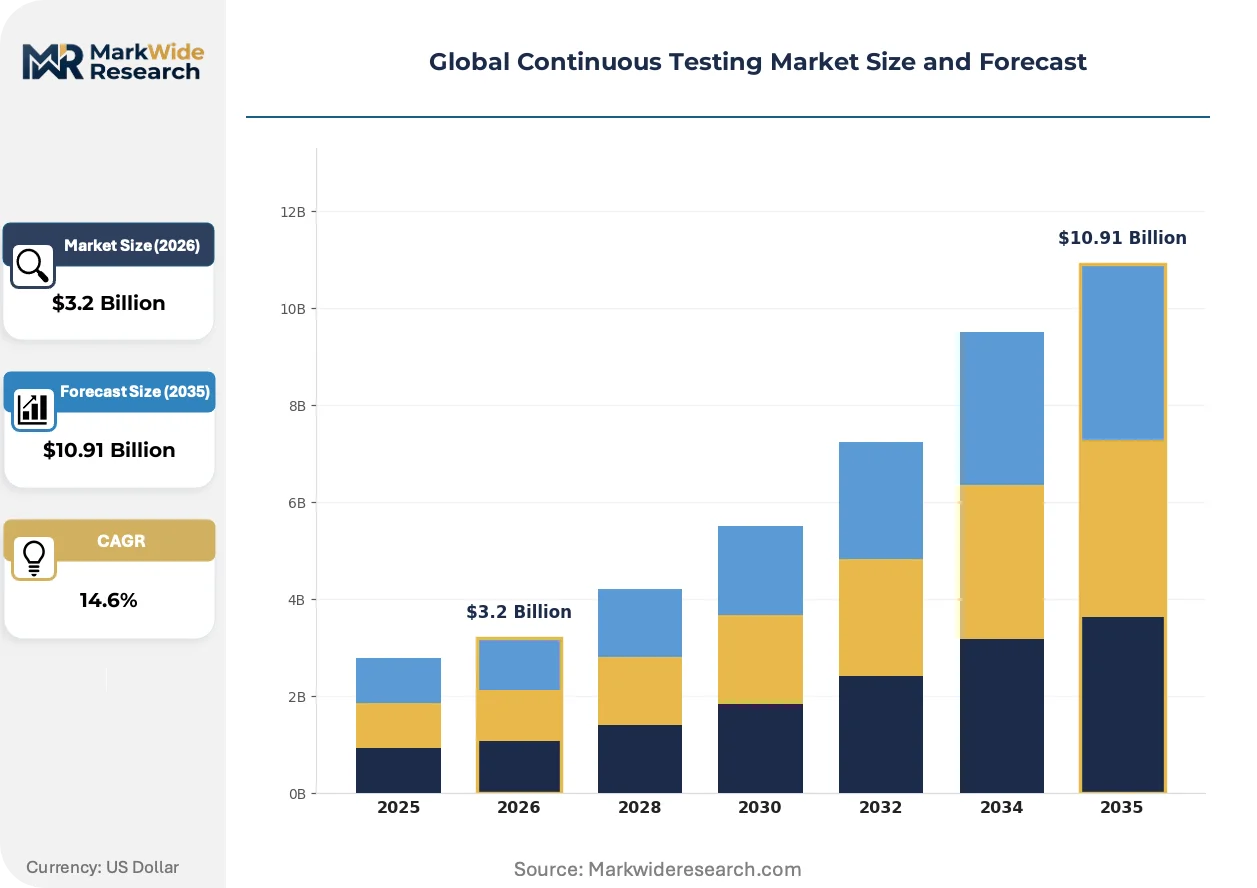
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $10.91 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Containerized Solution Type: Functional Testing, Performance Testing, Security Testing, API Testing, Usability Testing Application: Web Applications, Mobile Applications, Enterprise Software, Embedded Systems, IoT Platforms Industry Vertical: Banking & Financial Services, Telecommunications, Education, Government, Manufacturing |
| Companies Covered | IBM Corporation, Tricentis, Micro Focus, Accenture, HCL Technologies, Capgemini, EPAM Systems, Tech Mahindra, Infosys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Testing Market Shifts & Advancements
Artificial intelligence is transforming how test cases are generated, prioritized, and maintained, compressing the labor intensity of quality assurance while raising the bar for what constitutes adequate coverage.
Model-based test automation is integrating machine learning algorithms to auto-generate test scenarios from application behavior patterns. Financial services institutions with complex SAP and Salesforce deployments are adopting these engines to reduce script maintenance overhead. The technology is integrating predictive defect analysis that shifts testing resources toward highest-risk code changes.
The EU AI Act's risk classification framework is mandating conformity assessments for automated credit scoring and insurance pricing algorithms. European enterprises must now maintain versioned test evidence demonstrating bias detection and performance stability across demographic segments. Medical device manufacturers are extending these requirements to clinical decision support software under parallel MDR obligations.
Enterprise buyers are consolidating vendor relationships around platforms that unify functional, performance, and security testing within single orchestration layers. Procurement committees in United States healthcare and banking are disqualifying point solutions that require separate integration effort. This preference shift favors vendors with pre-built connectors to Red Hat OpenShift and native Kubernetes pipelines.
Global Continuous Testing Market Segmentation
Segmentation in continuous testing reveals how capital allocation, compliance burdens, and architectural complexity concentrate demand across deployment modes, solution types, and industry verticals. Vendors calibrate pricing and service models against these fault lines to capture expansion in cloud-native pipelines while defending legacy maintenance revenue.
Deployment:
Capital intensity varies sharply across deployment modes, with containerized and hybrid configurations demanding the heaviest upfront infrastructure investment.
- Cloud-Based:Elastic Kubernetes-native test grids eliminate fixed hardware depreciation while enabling burst scaling for release cycles. United States healthcare systems and financial services firms in New York and Chicago are retiring on-premises grids fastest, driven by HIPAA and SEC compliance documentation requirements that cloud vendors now bundle as attested controls.
- Containerized:Docker and Kubernetes-orchestrated test environments standardize reproducibility across dev, staging, and production. European banks under ECB supervision are prioritizing this mode to satisfy EU AI Act conformity assessment requirements for algorithmic credit decisions, despite higher initial platform engineering costs.
- Hybrid:Split workloads between captive data centers and public cloud for regulated data residency. German automotive manufacturers use this mode to keep proprietary design data on-premises while bursting compute to Frankfurt cloud regions.
- SaaS:Subscription access to vendor-managed test infrastructure with minimal client-side capital. Indian software export houses serving North American clients favor this mode for rapid client onboarding without infrastructure procurement cycles.
- On-Premises:Legacy perpetual-license deployments in air-gapped environments. Japanese pharmaceutical manufacturers under PMDA inspection protocols maintain this mode for clinical trial software validation.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Containerized.
Solution Type:
Solution specialization tracks the architectural evolution from monolithic applications toward microservices and API-first design.
- API Testing:Contract validation across interdependent microservices at deployment velocity. Financial services institutions in London and Singapore are expanding API test coverage fastest, compelled by open banking mandates and real-time payment settlement risks.
- Security Testing:SAST, DAST, and IAST integration into CI/CD pipelines for shift-left compliance. United States federal contractors under FedRAMP and CMMC requirements are driving premium pricing for unified security-quality orchestration platforms.
- Functional Testing:End-to-end validation of business logic across unit, integration, and acceptance layers. German insurance core system migrations sustain demand for SAP and mainframe test automation.
- Performance Testing:Load, stress, and soak validation for scalability guarantees. Brazilian e-commerce platforms preparing for seasonal traffic surges invest heavily here.
- Usability Testing:Accessibility and user experience validation, often manual or semi-automated. Canadian healthcare portals under AODA and ACA compliance requirements are expanding this coverage.
API Testing commands the steepest expansion trajectory. Security Testing captures the highest contract values per seat.
Application:
Application architecture determines test environment complexity and the granularity of feedback loops required.
- Enterprise Software:Packaged and custom business applications with complex integration surfaces. Salesforce and SAP landscapes in Australian mining and energy sectors demand model-based automation to reduce script maintenance overhead across quarterly release cycles.
- Mobile Applications:iOS and Android validation across device fragmentation and OS version matrices. South Korean consumer electronics manufacturers test mobile companion apps for smart appliances under MFDS interoperability requirements.
- Web Applications:Browser-based validation across responsive design and cross-platform compatibility. Dutch logistics platforms serving pan-European supply chains prioritize this for customer-facing booking interfaces.
- Embedded Systems:Firmware and hardware-software integration testing. Swiss medical device manufacturers under Swissmedic and MDR obligations extend continuous validation to clinical decision support software.
- IoT Platforms:Sensor-to-cloud pipeline validation at scale. Saudi smart city initiatives under MOHAP and SDAIA oversight are building captive testing capabilities for connected healthcare infrastructure.
Enterprise Software absorbs the largest absolute testing spend. Mobile Applications are climbing fastest in test automation penetration.
Industry Vertical:
Regulatory density and software criticality create divergent willingness-to-pay across vertical markets.
- Banking & Financial Services:Algorithmic trading, credit scoring, and insurance pricing systems under strict validation mandates. EU AI Act conformity assessments and SEC model risk management guidance in the United States are expanding mandatory test evidence scope fastest here.
- Government:Citizen-facing digital services and defense systems with security clearance requirements. United Kingdom GDS and United States 18F standards are mandating automated accessibility and performance testing for all new digital services.
- Telecommunications:5G network function virtualization and OSS/BSS transformation. South Korean operators under MSIT spectrum obligations are validating network slicing configurations through continuous test pipelines.
- Manufacturing:Industrial IoT, predictive maintenance, and digital twin validation. German Industrie 4.0 initiatives under BMWi funding prioritize IEC 62551 conformance for safety-critical control systems.
- Education:Learning management systems and credential verification platforms. Australian universities under TESQA quality standards are expanding automated testing for online assessment integrity.
Banking & Financial Services channels the deepest testing budgets. Government verticals are gaining share fastest as digital service mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the deepest continuous testing budgets while Germany channels the most regulatory-driven procurement acceleration. Cloud-native DevSecOps maturity separates American enterprise adoption curves from European compliance-first implementations. India's engineering services sector is capturing higher-margin validation work through captive capability building.
United States
Financial services firms in New York and Chicago are retiring on-premises test grids fastest for elastic Kubernetes-native infrastructure. SEC model risk management guidance and FDA software-as-a-medical-device enforcement mandate documented, repeatable test evidence. Healthcare systems across the Boston-Cambridge corridor are expanding automated validation pipelines for HIPAA-compliant cloud migrations.
Germany
Automotive manufacturers under BMWi Industrie 4.0 funding prioritize IEC 62551 conformance for safety-critical control systems. EU AI Act conformity assessments for algorithmic credit decisions are forcing ECB-supervised banks into containerized test environment investments. Bavarian industrial software clusters around Munich are building predictive defect analysis capabilities for complex SAP landscapes.
United Kingdom
Government Digital Service standards mandate automated accessibility and performance testing for all new citizen-facing digital services. London-based open banking platforms are expanding API contract validation fastest among European financial centers. Scottish fintech clusters are embedding continuous validation into DevOps workflows for regulatory technology exports.
India
Engineering services providers in Bengaluru and Hyderabad are building captive testing capabilities to capture higher-margin validation work from North American clients. RBI guidelines on digital lending algorithms are expanding domestic demand for automated bias detection pipelines. Pune-based IT services clusters are standardizing Kubernetes-native test grids for pharmaceutical client exports.
Japan
Pharmaceutical manufacturers under PMDA inspection protocols maintain air-gapped on-premises deployments for clinical trial software validation. METI standards for medical device software lifecycle management are extending continuous validation requirements to clinical decision support systems. Osaka-based electronics manufacturers are testing mobile companion apps for smart appliances under MFDS interoperability requirements.
Global Continuous Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform vendors capturing premium pricing in regulated verticals while services-heavy players compete on implementation velocity. The vendor base organizes into three tiers: enterprise automation platforms with pre-built SAP and Salesforce connectors, engineering-led consultancies embedding validation into client DevOps workflows, and scale-driven IT services firms competing on offshore delivery capacity. Dominant competitive moves include strategic partnerships with Red Hat OpenShift and cloud hyperscalers, plus portfolio diversification into shift-left security convergence.
Within the enterprise automation tier, IBM Corporation and Tricentis anchor platform strategies through deep CI/CD pipeline integration. EPAM Systems exemplifies the engineering-led consultancy archetype, embedding continuous validation into complex client workflows. These three occupy positions across the pricing spectrum from premium platform licensing to value-oriented services bundling.
| Leading Market Players |
|---|
| IBM Corporation |
| Tricentis |
| Micro Focus |
| Accenture |
| HCL Technologies |
| Capgemini |
| EPAM Systems |
| Tech Mahindra |
| Infosys |
| Others |
Supply & Pricing Matrix
Cloud compute consumption in containerized test grids flows through subscription tiers that stratify by orchestration depth and compliance documentation bundled, with elastic scaling premiums compressing margins for vendors serving fixed-budget regulated buyers.
Pricing Analysis
Capacity additions in India's engineering services corridor are reshaping price floors for implementation-heavy validation engagements. Three-tier pricing structure across premium, standard, and economy levels segments by automation engine sophistication and pre-built SAP connector availability. Price differentiation rests on ISO 25010 certification tier and EU AI Act conformity assessment pre-configuration. Cost compression in the economy tier intensifies because offshore delivery capacity expansion outpaces demand growth in North American mid-market accounts. Healthcare systems under HIPAA enforcement show least price sensitivity; Indian software export houses serving multiple clients exhibit highest.
Supply Chain Analysis
Specialized engineering talent supply rests on university pipelines in Bengaluru, Warsaw, and Mexico City feeding implementation services. Raw material inputs span open-source automation frameworks, hyperscaler compute credits, and synthetic data generation tooling. Supply chain risk centers on single-source vulnerability for Red Hat OpenShift-certified integration specialists. Distribution runs through direct enterprise sales for platform vendors and systems integrator partnerships for services-heavy players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in continuous testing hinges on cloud-native infrastructure cost curves flattening while compliance documentation premiums harden in EU-regulated verticals.
For Market Incumbents: Deploy model-based automation engines as defensive moats against scriptless AI-native challengers. Anchor enterprise accounts through pre-built SAP and Salesforce connectors that increase switching costs. Capture EU AI Act conformity assessment workflows to lock in multi-year documentation retainers. For New Entrants and Emerging Players: Begin with API-first testing modules targeting mid-market fintechs in London and Singapore where open banking mandates outpace incumbent platform complexity. Build Kubernetes-native orchestration layers that bypass legacy mainframe integration friction. Position through DevSecOps consultancies as implementation partners rather than direct platform competition. For Investors and Strategic Acquirers: Consolidation pressure builds where engineering-led consultancies with captive testing capabilities trade at implementation-margin premiums versus pure-platform vendors. Target acquisition archetypes: vertical specialists with IEC 62304 medical device validation expertise. Watch containerized deployment penetration in ECB-supervised banks as inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying functional, performance, and security testing within Red Hat OpenShift pipelines captures premium pricing from United States federal contractors. |
| Acquisition of Specialist Firm | Vertical expertise in IEC 62304 medical device validation commands implementation-margin premiums in Boston-Cambridge healthcare clusters. |
| Geographic Expansion | Captive testing capabilities in Bengaluru and Hyderabad capture higher-margin validation work from North American pharmaceutical exports. |
| Strategic Partnership | Red Hat OpenShift certification partnerships differentiate platform vendors in United States healthcare and banking procurement committees. |
| Product Launch | AI-powered predictive defect analysis shifts testing resources toward highest-risk code changes in complex SAP landscapes. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down vendor booking tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists combined with secondary validation against SEC filings, hyperscaler capex disclosures, and DevOps tooling adoption surveys. Triangulation across stakeholder inputs and documentary sources anchors segmentation integrity.
Input-output matrices map test environment provisioning costs against compliance documentation premiums across deployment modes, solution types, and vertical applications. Segmentation dimensions span cloud-native versus legacy infrastructure, API versus functional testing specialization, and regulated versus non-regulated industry exposure. CAGRs derive from elasticity-adjusted capacity expansion curves and regulatory mandate implementation timelines. Forecast inputs include EU AI Act enforcement pacing and Kubernetes adoption saturation thresholds.
Several conditions sit outside the modeled scope, including black-swan regulatory reversals, hyperscaler pricing architecture overhauls, and generative AI code generation displacement of traditional test automation. Forecasts reflect documented assumptions about compliance burden trajectory and cloud infrastructure cost curves. A small set of named triggers warrants ongoing watch: ECB supervision intensity for algorithmic credit decisions, FDA SaMD enforcement pacing, and Red Hat OpenShift market share inflections in financial services.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Social Collaboration Software Market
Software & Services
Collaboration Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Recruitment Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Computer Backup Software Market
Software & Services
Non-Profit Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
App Creation Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Hydraulic Modeling Software Market