
 Lead Mining Software Market | 2026-2036
Lead Mining Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Mining Software Market Foresight
Enterprise-grade accuracy tiers is rotating toward the center of vendor competition. Apollo leverages proprietary data verification layers to sustain platform stickiness among high-velocity sales organizations. ZoomInfo Technologies LLC anchors its position through deep business-contact graph coverage. Cognism Limited differentiates via GDPR-aligned compliance architecture across European deployments.
Lead mining software comprises systems that extract, enrich, and score prospect contact and firmographic data from public databases, web domains, and social signals, typically processing millions of records through real-time API pipelines or batch ingestion workflows. The primary commercial purpose is to reduce customer acquisition cost by automating top-of-funnel identification and prioritization. Cloud-based deployment now captures the largest revenue pool as buyers trade capital expenditure for elastic scaling. Sales intelligence use cases expand fastest, fueled by demand for intent signals and technographic overlays. CRM integration represents the stickiest integration tier, with API support becoming table stakes for mid-market and enterprise procurement.
GDPR in Europe, the EU AI Act, and state-level privacy statutes in the United States impose strict boundaries on data sourcing, consent documentation, and algorithmic scoring transparency. Vendors must architect audit trails and opt-out mechanisms into core workflows, or risk exclusion from regulated buyer segments. Stakeholders should monitor evolving cross-border data-transfer agreements and emerging AI disclosure mandates that could redefine competitive moats in prospecting technology.
Market Dynamics
Cloud-native API architectures are compressing deployment cycles for lead mining platforms, while GDPR enforcement and the EU AI Act impose compliance costs that favor vendors with pre-built audit infrastructure over point-solution newcomers.
Growth Catalysts
- Intent Signal Layering:Real-time technographic and behavioral data overlays enable sales teams to prioritize accounts showing active research patterns, compressing sales cycles for mid-market SaaS buyers.
- GDPR-Aligned Certification:European procurement teams now mandate documented consent chains and algorithmic transparency, creating preference pull for vendors with native compliance architecture.
- CRM Integration Depth:Native connectors to Salesforce, HubSpot, and Microsoft Dynamics reduce implementation friction, accelerating time-to-value for revenue operations teams.
Market Restraints
- Data Source Concentration:Quality business contact graphs depend on limited verified sources, creating supply vulnerability when primary aggregators restrict API access or raise licensing fees.
- Cross-Border Transfer Friction:Schrems II rulings and evolving EU-US data adequacy decisions force vendors to maintain redundant infrastructure, elevating operational complexity.
- Algorithmic Scoring Opacity:Black-box lead scoring models face scrutiny under AI Act transparency mandates, limiting deployment in regulated European financial services.
Strategic Opportunities
- APAC Expansion:Japan's METI guidelines on data utilization and South Korea's MFDS framework create openings for compliant prospecting platforms in manufacturing and life sciences verticals.
- Vertical-Specific Models:Pre-trained industry graphs for healthcare, legal, and financial services reduce cold-start data quality problems and command premium positioning.
- Privacy-Preserving Computation:Federated learning and differential privacy techniques enable cross-enterprise signal sharing without raw data exposure, addressing consent limitations.
Industry Challenges
- Data Engineering Talent Scarcity:Pipeline architecture for real-time enrichment at scale requires specialized skills in distributed systems and entity resolution, constraining vendor expansion velocity.
- Legacy CRM Migration Friction:Enterprises with heavily customized on-premise installations face integration complexity that extends implementation timelines and elevates professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Mining Software Market |
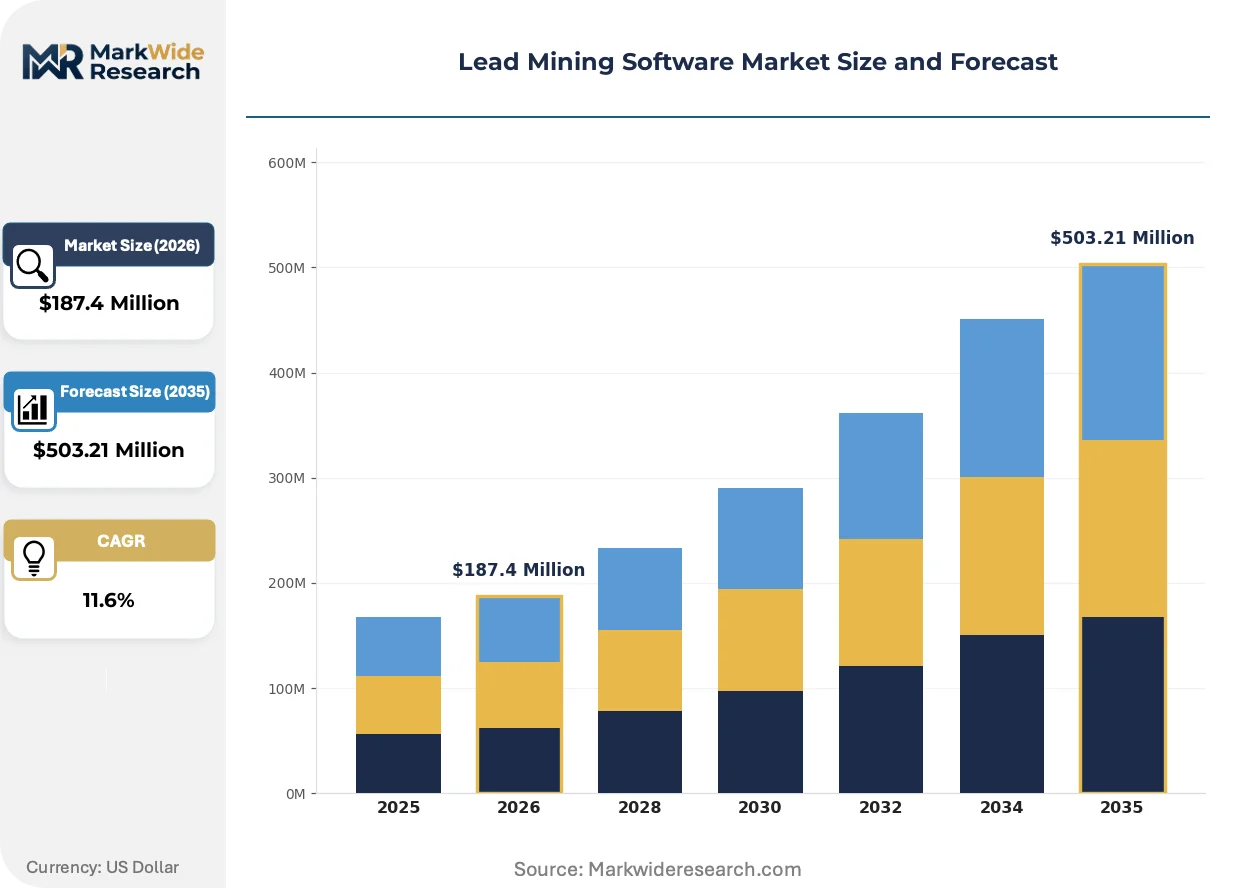
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Use Case: Sales Intelligence, Market Research, Lead Generation, Prospecting End User: SMBs, Enterprises, Marketing Agencies, Tech Startups Integration Level: CRM Integration, API Support, Data Export, Third-Party Tools |
| Companies Covered | Apollo, Cognism Limited, ZoomInfo Technologies LLC, Lusha Systems Inc, BuiltWith Pty Ltd, HubSpot Inc., LeadIQ Inc., AeroLeads Inc., Salesforce Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Mining Software Market Shifts & Advancements
Real-time data pipelines and algorithmic transparency mandates are restructuring how vendors build competitive moats, shifting differentiation from raw data volume to verified quality and explainable scoring.
Graph neural networks for entity resolution are decomposing traditional deterministic matching approaches, enabling probabilistic linkage across fragmented data sources. High-velocity sales organizations in technology and business services are adopting these systems fastest. The technology is decomposing legacy batch-processing architectures and compressing the value capture window for vendors without native AI infrastructure.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on automated decision systems used for lead scoring. Vendors must now maintain model cards, bias audit trails, and opt-out mechanisms as core product features. European financial services and healthcare technology buyers are demanding these capabilities pre-contract, reshaping RFP evaluation criteria.
Revenue operations teams are unbundling point-solution procurement, preferring consolidated platforms with native enrichment, scoring, and engagement orchestration. Mid-market buyers previously stitching together three to four tools now evaluate end-to-end alternatives. This consolidation pressure is most visible in North American SaaS and technology verticals, where procurement cycles have compressed from twelve to six months.
Lead Mining Software Market Segmentation
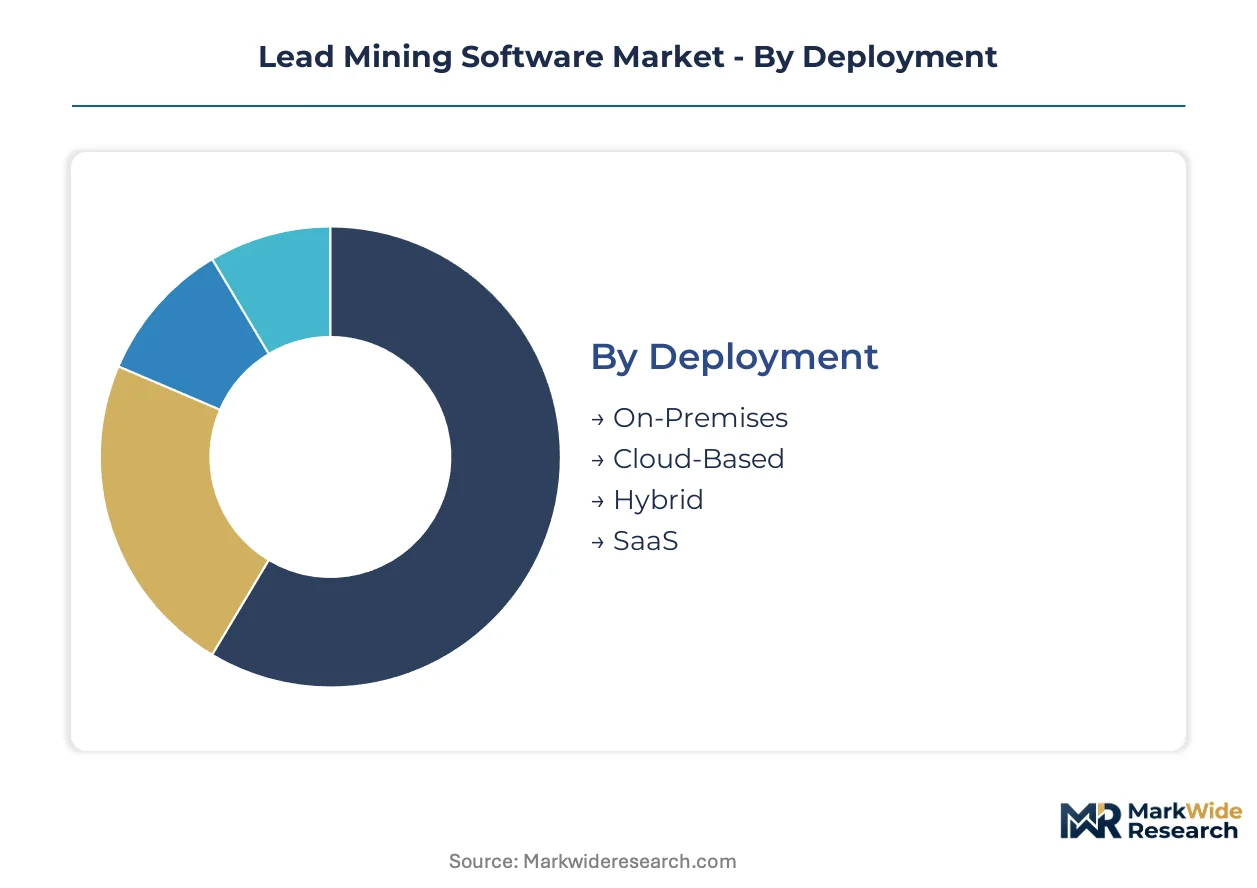
Lead mining software procurement diverges sharply across deployment models and integration requirements. GDPR enforcement in Europe and state-level privacy statutes in the United States create compliance-driven segmentation that reshapes vendor selection criteria and pricing architecture.
Deployment:
GDPR's data-localization mandates and the EU AI Act's audit requirements favor architectures with jurisdictional control and transparency documentation.
- Cloud-Based:Elastic infrastructure enables real-time enrichment pipelines without capital expenditure. European buyers prioritize vendors with EU-based data centers to satisfy GDPR localization requirements and Schrems II transfer restrictions. This segment commands the largest revenue pool as mid-market SaaS buyers trade ownership for operational agility.
- SaaS:Subscription pricing aligns procurement with revenue operations budgets rather than IT capital cycles. United States technology startups and business services firms drive fastest adoption, compressing implementation timelines from quarters to weeks. Native compliance dashboards differentiate European-facing offerings.
- On-Premises:Air-gapped installations serve financial services and defense contractors with classified data handling requirements.
- Hybrid:Split architectures process sensitive records locally while leveraging cloud APIs for public data enrichment.
Established volume favors Cloud-Based; emerging adoption favors SaaS.
Use Case:
Functional specialization determines integration depth and data freshness requirements across buyer workflows.
- Sales Intelligence:Intent signal layering and technographic overlays prioritize accounts showing active research patterns. United States high-velocity sales organizations in software and business services compress cycles through real-time behavioral scoring. API latency below 200 milliseconds separates competitive tiers.
- Lead Generation:Automated contact extraction from web domains and social platforms reduces customer acquisition cost. Marketing agencies in North America and Western Europe scale top-of-funnel volume without proportional headcount expansion. Quality verification layers determine platform stickiness.
- Market Research:Firmographic aggregation supports competitive positioning and total addressable market sizing.
- Prospecting:Prioritized outreach lists integrate directly with engagement orchestration tools.
Revenue concentration sits with Sales Intelligence; steepest expansion trajectory belongs to Lead Generation.
End User:
Organizational scale dictates feature complexity, compliance burden tolerance, and contract negotiation leverage.
- Enterprises:Custom data residency requirements and SSO integration demands dominate procurement. GDPR documentation and EU AI Act risk classification drive RFP evaluation in European financial services and healthcare technology. Procurement cycles extend to accommodate security review and legal negotiation.
- Tech Startups:Speed-to-value prioritization favors pre-built connectors and self-service onboarding. United States venture-backed companies scale prospecting operations without dedicated revenue operations engineering. Monthly billing and usage-based tiers align with cash flow constraints.
- SMBs:Price-sensitive buyers consolidate point solutions into bundled productivity suites.
- Marketing Agencies:Multi-tenant requirements and white-label capabilities support client-specific data segmentation.
Contract value concentration favors Enterprises; user growth velocity favors Tech Startups.
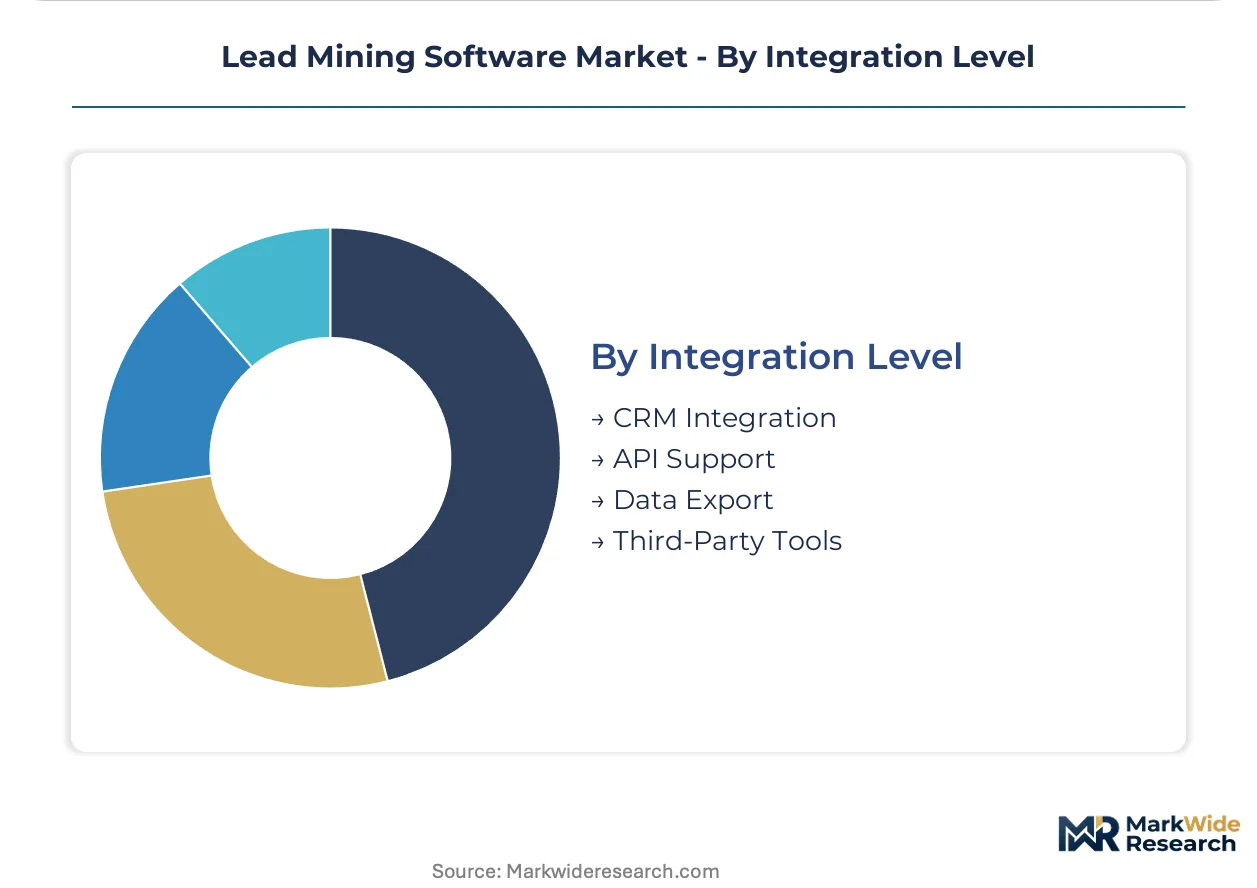
Integration Level:
Connectivity depth determines platform stickiness and switching cost architecture for revenue operations teams.
- CRM Integration:Native connectors to Salesforce, HubSpot, and Microsoft Dynamics embed enrichment directly into seller workflows. European enterprises mandate field-level audit trails for GDPR compliance. Bidirectional sync eliminates manual data entry friction.
- API Support:REST and GraphQL endpoints enable custom pipeline construction for sophisticated data engineering teams. United States mid-market SaaS buyers build proprietary scoring models atop vendor data layers. Documentation completeness and rate limit transparency influence vendor selection.
- Data Export:Bulk extraction capabilities support offline analysis and regulatory data portability requests.
- Third-Party Tools:Pre-built connectors to engagement platforms and business intelligence suites extend workflow coverage.
Retention stickiness concentrates in CRM Integration; technical buyer preference flows toward API Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure concentrates disproportionately in the United States, where venture capital availability and cloud hyperscaler proximity accelerate platform development cycles. GDPR enforcement in Europe and emerging data-localization mandates in Asia-Pacific reshape regional deployment architectures.
United States
High-velocity SaaS sales organizations in San Francisco and New York Metro drive fastest adoption of intent-signal layering platforms. State-level privacy statutes in California and Virginia impose consent documentation requirements that vendors must architect into core workflows. Austin and Seattle clusters host emerging challengers focused on API-first enrichment pipelines.
Germany
Industrial manufacturing and automotive sales teams in Baden-Württemberg demand GDPR-aligned compliance architecture with audit trail transparency. The KBA and BSI frameworks influence procurement evaluation criteria for automated decision systems. Munich-based enterprises prioritize vendors with EU-based data residency and Schrems II-compliant transfer mechanisms.
United Kingdom
Financial services prospecting in London requires algorithmic scoring explainability under FCA guidance and emerging AI disclosure mandates. The Information Commissioner's Office enforcement patterns shape vendor certification priorities. Manchester and Edinburgh clusters show expanding adoption among mid-market business services firms.
Japan
Manufacturing and life sciences verticals in Tokyo and Osaka adopt compliant prospecting platforms under METI data utilization guidelines. The PMDA framework influences healthcare technology buyer requirements for consent documentation. Nagoya-based automotive suppliers integrate enrichment tools into existing CRM deployments.
India
Technology services firms in Bangalore and Hyderabad scale outbound sales operations using cloud-based enrichment platforms. The Digital Personal Data Protection Act imposes emerging consent and localization requirements that vendors must address. Mumbai-based financial services buyers evaluate API latency and integration depth as primary selection criteria.
Lead Mining Software Market Competitive Landscape
Concentration sits with cloud-native platforms possessing proprietary data graphs and native compliance infrastructure. The vendor base stratifies across three tiers: established data aggregators with deep business-contact coverage, vertical specialists with GDPR-aligned architectures, and API-first challengers targeting mid-market SaaS buyers. Dominant competitive moves include strategic partnerships with CRM platforms and geographic expansion into APAC markets with localized compliance frameworks.
Within the established data aggregator tier, ZoomInfo Technologies LLC and Apollo occupy positions defined by scale and verification depth. Cognism Limited exemplifies the GDPR-specialist archetype, anchoring European-facing procurement evaluations. These three companies represent distinct strategic postures: scale-driven graph coverage, high-velocity sales workflow integration, and compliance-first regional positioning.
| Leading Market Players |
|---|
| Apollo |
| Cognism Limited |
| ZoomInfo Technologies LLC |
| Lusha Systems Inc |
| BuiltWith Pty Ltd |
| HubSpot Inc. |
| LeadIQ Inc. |
| AeroLeads Inc. |
| Salesforce Inc. |
| Others |
Supply & Pricing Matrix
Real-time API latency requirements below 200 milliseconds compress vendor engineering cycles to 45-60 days for feature releases, concentrating pricing power with cloud-native platforms possessing proprietary data verification layers and native GDPR compliance infrastructure. This lead-time compression favors established aggregators over point-solution newcomers, embedding cost advantages into subscription tiers that scale with enrichment volume and integration depth.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure across the lead mining software landscape. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade platforms with audit trail transparency from mid-market SaaS offerings and basic contact extraction tools. Price differentiation rests on certification level — GDPR-aligned vendors command 15-25% subscription premiums in European procurement evaluations — and integration complexity with native CRM connectors. Cost compression in the economy tier intensifies because venture-backed challengers subsidize user acquisition with usage-based pricing. Tech startups exhibit highest price sensitivity due to cash flow constraints, while financial services enterprises prioritize compliance documentation over unit cost.
Supply Chain Analysis
Engineering talent pipelines extending 90-120 days for distributed systems specialists constrain vendor expansion velocity, concentrating platform development in the United States, United Kingdom, and Germany where cloud hyperscaler proximity accelerates iteration cycles. Raw material dependencies center on proprietary business contact graphs, real-time behavioral signal feeds, and third-party firmographic databases. Single-source vulnerability runs through dominant data aggregators controlling verified contact coverage. Distribution runs through direct sales teams for enterprise accounts and self-service onboarding portals for mid-market buyers, with API documentation completeness influencing technical buyer conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated revenue operations teams unbundling point-solution procurement, with procurement cycle compression from twelve to six months in North American SaaS verticals fragmenting vendor negotiation leverage.
For Market Incumbents: Compound platform stickiness through native compliance architecture investments that preempt EU AI Act enforcement and Schrems II data localization mandates. Deepen proprietary data graph coverage in healthcare and financial services verticals where consent documentation requirements create switching cost barriers. Prioritize API latency optimization below 150 milliseconds to defend against API-first challengers targeting high-velocity sales organizations. For New Entrants and Emerging Players: Anchor in APAC manufacturing and life sciences verticals where Japan's METI guidelines and South Korea's MFDS framework create compliant prospecting openings with limited incumbent saturation. Target mid-market business services firms in Manchester and Edinburgh clusters where GDPR-aligned certification gaps persist among established vendors. Pursue federated learning partnerships that enable cross-enterprise signal sharing without raw data exposure. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy data aggregators with deep contact graphs but lacking native AI infrastructure for real-time enrichment pipelines. Long-term viability over the next decade hinges on algorithmic transparency capabilities becoming table stakes for European financial services procurement. Watch for Schrems III rulings and evolving EU-US data adequacy decisions as inflection indicators for infrastructure redundancy requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CRM connectors to Salesforce and HubSpot reduce implementation friction for revenue operations teams. |
| Geographic Expansion | EU-based data centers satisfy GDPR localization requirements and Schrems II transfer restrictions for European buyers. |
| Acquisition of Specialist Firm | Vertical-specific data graphs for healthcare and legal reduce cold-start quality problems in regulated segments. |
| Strategic Partnership | Federated learning alliances enable privacy-preserving signal sharing across enterprise boundaries without consent violations. |
| Product Launch | Compliance dashboards with algorithmic transparency documentation address EU AI Act risk classification mandates. |
Research Methodology
The analysis maps cloud-native API architectures, GDPR-aligned compliance infrastructure, and vertical-specific data graphs, each validated through primary interviews with revenue operations leaders, CTOs at high-velocity sales organizations, data engineering directors, and European procurement officers. Secondary sources include SEC filings from publicly traded vendors, hyperscaler capex disclosures, GDPR enforcement patterns from national data protection authorities, and EU AI Act implementation guidance. Bottom-up sizing of deployment models and use cases triangulates against top-down market aggregation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework models deployment architecture, organizational scale, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs derive from elasticity-adjusted demand curves and vendor pricing trajectory analysis. Forecast inputs incorporate cloud infrastructure cost curves and data engineering salary inflation patterns.
Material uncertainties — Schrems II ruling evolution, EU AI Act enforcement intensity, and cross-border data transfer agreement renegotiation — sit outside the modeled envelope. Forecasts reflect assumptions about compliance cost trajectories and buyer consolidation behavior. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sales Enablement Platform Market
Software & Services
Mining Software Market
Software & Services
Sales Coaching Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Event Management Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Global Landscape Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Runtime Software Market
Software & Services
Global MSP Software Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Global ERP Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Global Automation Software Market
Software & Services
User Experience (UX) Research Software Market