
 G Suite Technology Services Market | 2026-2036
G Suite Technology Services Market Size, Share, and Industry Trends Forecast 2026-2036
G Suite Technology Services Market Analysis
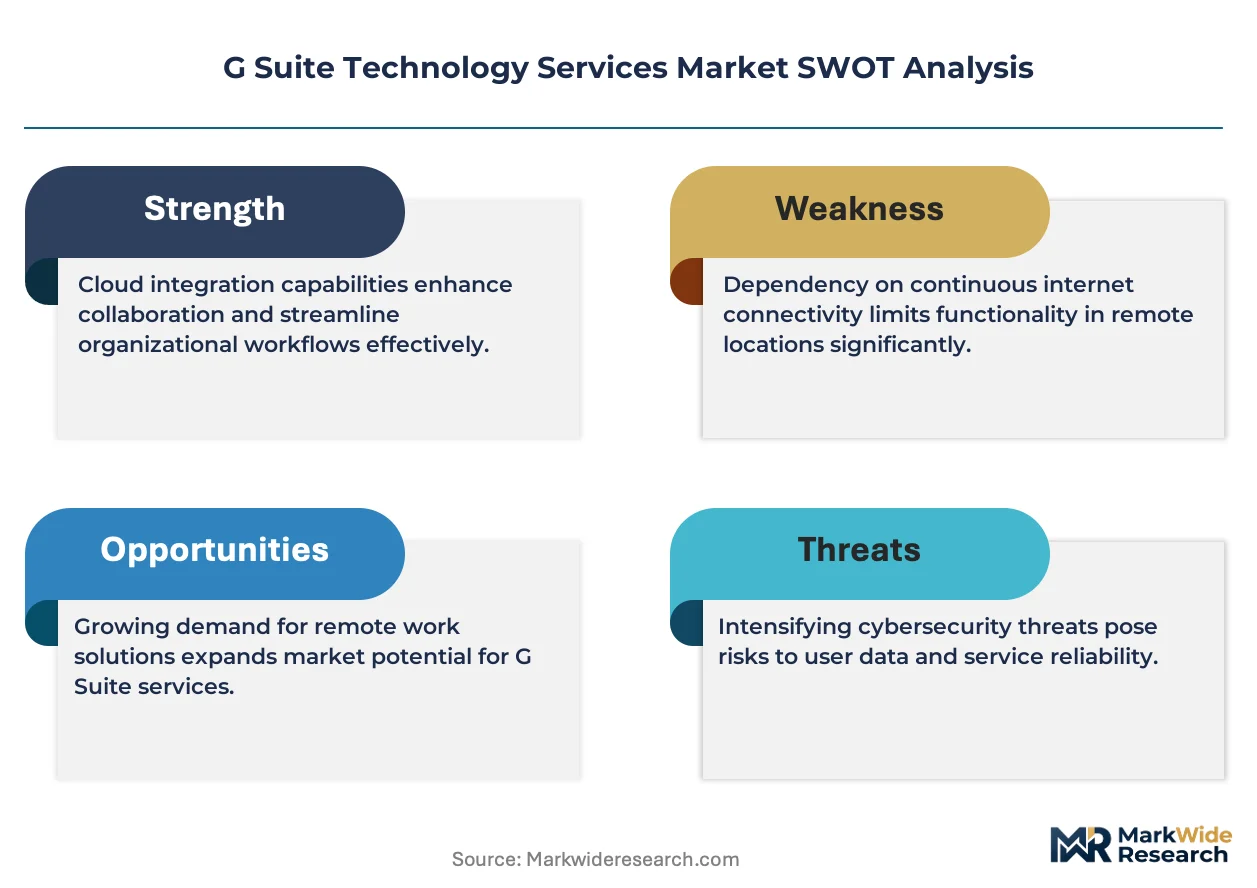
Serverless computing architectures and API-first design is rewriting how enterprise productivity platforms integrate with legacy systems. Google leverages its hyperscale infrastructure to dominate cloud-native workspace delivery. SADA Systems anchors its competitive position through deep Google Cloud specialization and certified deployment expertise. Zoho Corporation differentiates by competing on price-performance for mid-market buyers seeking alternatives to dominant ecosystems.
G Suite Technology Services encompass cloud-hosted software enabling document creation, real-time collaboration, secure storage, and unified communication through browser-based and mobile interfaces with 99.9% uptime SLAs. These services eliminate on-premises server maintenance while enabling distributed workforce coordination across geographies. Deployment through cloud-based models leads volume as enterprises abandon capital-intensive infrastructure, though hybrid configurations capture margin pools from regulated industries requiring data residency controls. Small businesses represent the fastest-growing end-user segment as self-service onboarding reduces implementation barriers. Managed services concentrate revenue among buyers lacking internal IT capacity for security configuration and compliance monitoring.
GDPR in Europe, HIPAA in the United States, and the EU AI Act collectively shape product roadmaps by mandating data localization, audit trails, and algorithmic transparency in automated workflow tools. Enterprise procurement teams now require SOC 2 Type II certification and region-specific data processing agreements as baseline vendor qualifications. Stakeholders must monitor evolving cross-border data transfer mechanisms and emerging sector-specific AI governance frameworks to anticipate compliance-driven purchasing decisions.
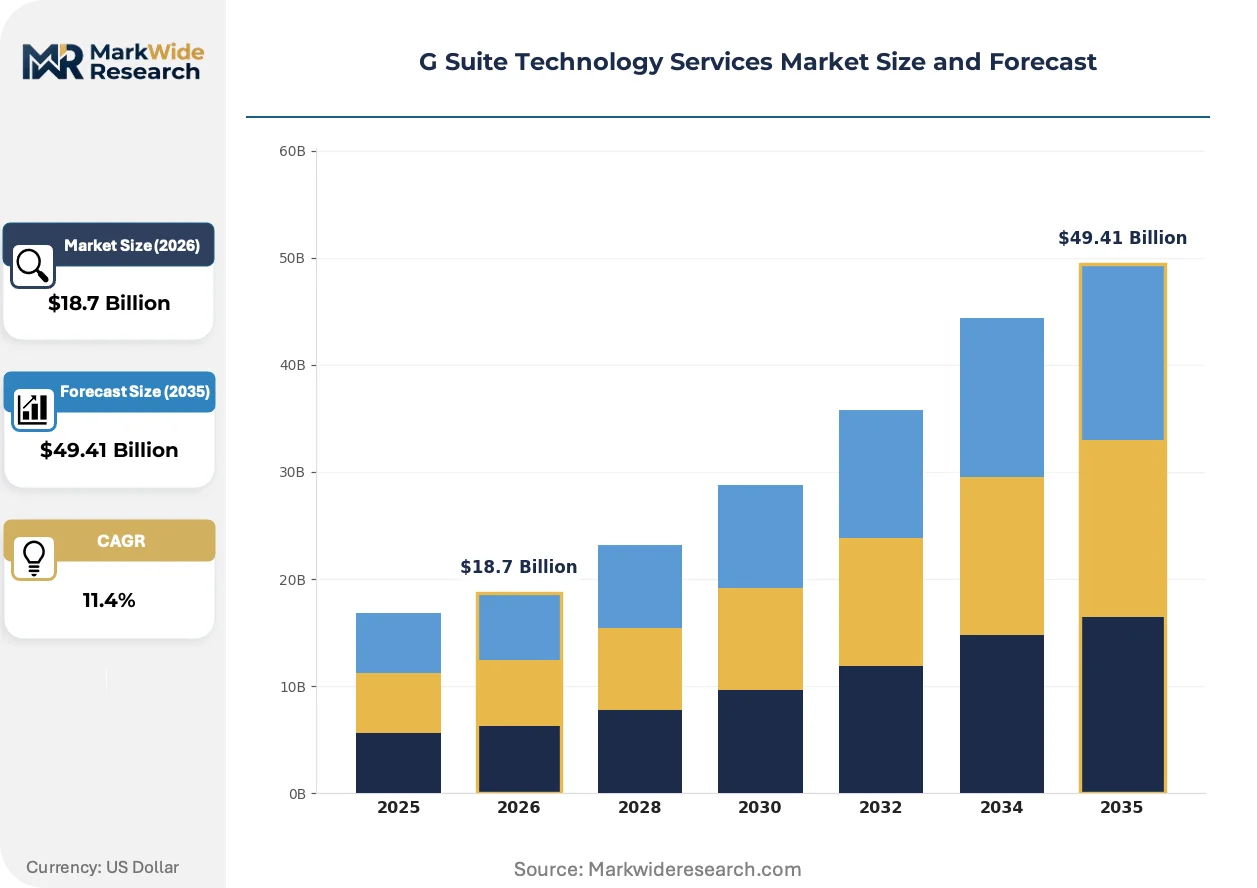
Market Dynamics
Enterprise migration from on-premises productivity infrastructure to cloud-native collaboration suites is compressing deployment cycles and reshaping vendor selection criteria. The EU AI Act and GDPR compliance mandates are forcing procurement teams to prioritize managed service providers with certified data residency controls.
Growth Catalysts
- HIPAA-compliant cloud migration:Healthcare providers in the United States are abandoning legacy on-premises email and document systems for cloud-hosted alternatives with built-in audit trails and encryption.
- Serverless architecture adoption:API-first design patterns enable real-time synchronization between G Suite applications and enterprise ERP systems without middleware maintenance.
- Educational procurement expansion:K-12 districts and universities across Germany, France, and the United Kingdom are standardizing on browser-based productivity suites to reduce device management overhead.
Market Restraints
- Cross-border data transfer friction:Schrems II rulings and evolving EU-U.S. Data Privacy Framework uncertainties create legal exposure for enterprises with distributed workforces.
- Legacy system integration costs:Mainframe-dependent financial services institutions face substantial middleware development expenses to connect cloud suites with core banking platforms.
- Hyperscale vendor concentration:Dependency on Google Cloud infrastructure for 99.9% uptime SLAs limits negotiating leverage and creates single-supplier risk for critical business functions.
Strategic Opportunities
- Mid-market managed services gap:Small businesses in India and Southeast Asia lack internal IT capacity for security configuration, creating demand for white-glove onboarding and compliance monitoring.
- AI-powered workflow automation:Convergence of generative AI with document creation tools enables automated contract drafting and approval routing in legal and procurement departments.
- EU AI Act compliance services:Algorithmic transparency requirements for automated decision-making tools create specialized consulting revenue streams around audit trail implementation.
Industry Challenges
- SOC 2 Type II certification timelines:Six-to-twelve-month audit cycles delay market entry for regional managed service providers seeking enterprise procurement qualification.
- Multi-cloud orchestration complexity:Enterprises maintaining hybrid deployments across Google Cloud, Microsoft Azure, and AWS struggle with identity federation and consistent policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | G Suite Technology Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collaboration Tools, Storage Solutions, Productivity Applications, Communication Services Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Small Businesses, Large Enterprises, Educational Institutions, Non-Profits Solution: Doc Management, Email Hosting, Calendar Services, Project Management |
| Companies Covered | Google, SADA Systems, Cloudypedia, Zoho Corporation, Salesforce, Bespin Global, Box, Slack Technologies, Smartsheet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
G Suite Technology Services Market Emerging Trajectories
Zero-trust security architectures and edge-computing integration are redefining how distributed teams access centralized productivity platforms. These shifts compress the boundary between endpoint devices and cloud infrastructure.
Serverless computing is collapsing the distinction between application logic and infrastructure management in enterprise productivity deployments. Mid-market manufacturers with limited DevOps resources are adopting function-as-a-service patterns for custom workflow automation. This compression eliminates server provisioning overhead and accelerates time-to-deployment for line-of-business applications.
The EU AI Act mandates algorithmic transparency for automated workflow tools processing personal data in employment contexts. European enterprises must now document decision logic in AI-powered document classification and routing systems. German automotive suppliers and French pharmaceutical firms are prioritizing vendors with pre-built audit trail modules to accelerate compliance certification.
Enterprise buying committees now require consumption-based pricing models with granular usage visibility rather than per-seat licensing. Channel partners are displacing direct sales motions in regulated industries by bundling compliance consulting with platform subscriptions. This pattern is most visible in United States healthcare and financial services verticals where procurement teams lack internal cloud security expertise.
G Suite Technology Services Market Segmentation
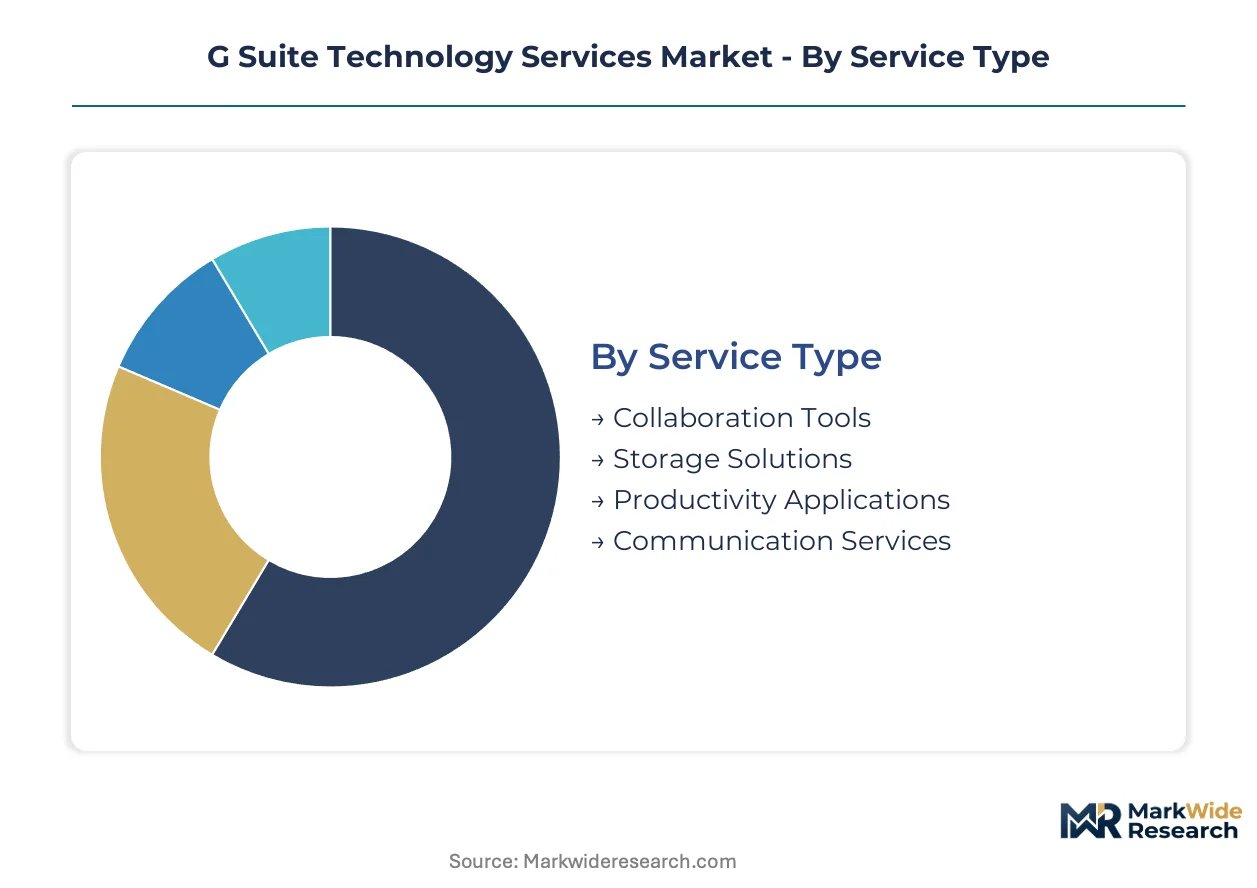
G Suite Technology Services segment along four intersecting dimensions that determine procurement velocity and margin structure. Deployment models and end-user scale create the most pronounced cycle-time differentials, with cloud-native configurations turning over in weeks while hybrid implementations stretch across quarters.
Service Type:
Collaboration Tools refresh fastest as feature releases drive continuous upgrade cycles, while Storage Solutions lock in longer-term commitments through data gravity effects.
- Collaboration Tools:Real-time document editing, shared workspaces, and synchronous commenting capabilities form the engagement layer. Healthcare systems in the United States prioritize HIPAA-compliant shared drives with granular permission controls to replace legacy file servers.
- Storage Solutions:Object storage with tiered retrieval policies and encryption-at-rest for archival compliance. German automotive suppliers demand EU-sovereign data residency to satisfy GDPR Article 44 transfer restrictions.
- Productivity Applications:Spreadsheet, presentation, and word processing suites with offline synchronization.
- Communication Services:VoIP telephony, video conferencing, and unified messaging with calendar integration.
Productivity Applications dominate installed base. Collaboration Tools is where expansion concentrates.
Deployment:
Cloud-based deployments compress procurement cycles through self-service provisioning, while hybrid configurations extend sales timelines through security review phases.
- Cloud-Based:Fully hosted multi-tenant infrastructure with automatic patch management and elastic scaling. Southeast Asian small businesses adopt this model fastest due to minimal upfront capital requirements and rapid onboarding workflows.
- Hybrid:Sensitive data remains on-premises while collaboration layers operate in cloud. French pharmaceutical firms select this architecture to maintain local custody of clinical trial documentation under ANSM guidance.
- On-Premises:Self-managed server infrastructure with full administrative control over update cadence.
- Managed Services:Third-party oversight of security configuration, compliance monitoring, and user lifecycle management.
Cloud-Based deployments dominate installed base. Managed Services is climbing the fastest as IT capacity constraints spread.
End User:
Small Businesses move through evaluation cycles in days, whereas Large Enterprises require multi-stakeholder alignment across security, procurement, and legal functions.
- Small Businesses:Organizations under 500 employees with limited dedicated IT staff and high price sensitivity. Indian professional services firms represent expanding demand as self-service onboarding eliminates implementation friction.
- Large Enterprises:Multi-divisional organizations with complex identity federation requirements and custom integration needs. United Kingdom financial institutions mandate SOC 2 Type II certification as baseline vendor qualification.
- Educational Institutions:K-12 districts and universities with seasonal procurement patterns and device management complexity.
- Non-Profits:Grant-funded organizations with constrained budgets and volunteer-driven technology adoption.
Large Enterprises dominate installed base. Small Businesses is gaining share fastest as barrier reduction accelerates.
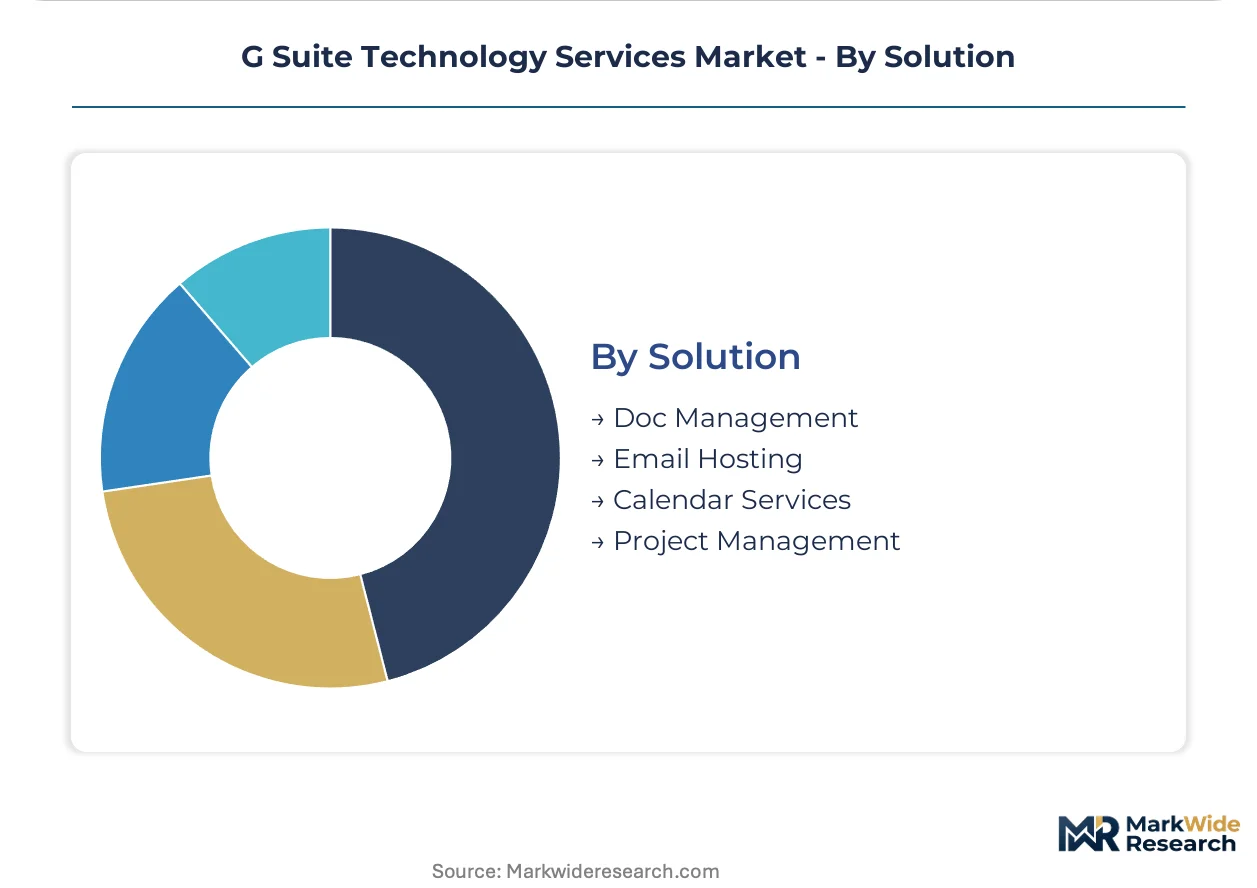
Solution:
Email Hosting carries the longest replacement cycles due to migration complexity, while Project Management tools turn over rapidly as teams test competing methodologies.
- Doc Management:Version control, metadata tagging, and retention policy enforcement for unstructured content. Legal departments in the United States deploy AI-powered classification to automate privilege review and discovery preparation.
- Email Hosting:Message routing, spam filtering, and eDiscovery archiving with litigation hold capabilities. Healthcare providers abandon legacy on-premises Exchange installations for cloud alternatives with built-in audit trails.
- Calendar Services:Resource booking, availability sharing, and meeting intelligence analytics.
- Project Management:Task tracking, Gantt visualization, and portfolio dashboards with time recording.
Email Hosting dominates installed base. Doc Management is where expansion concentrates as AI augmentation proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian IT services exporters supply managed G Suite deployment expertise to healthcare systems and educational institutions across the United States and United Kingdom. These cross-border service flows concentrate in Hyderabad and Bangalore delivery centers.
United States
Healthcare providers abandon legacy on-premises Exchange installations for cloud-hosted alternatives with built-in HIPAA audit trails and encryption. FDA guidance on software-as-a-medical-device shapes procurement requirements for clinical workflow tools. Texas Medical Center in Houston drives demand for compliant document management systems serving pharmaceutical research consortia.
Germany
Automotive suppliers prioritize EU-sovereign data residency to satisfy GDPR Article 44 transfer restrictions in multi-national engineering collaborations. KBA oversight of connected vehicle data influences enterprise cloud architecture decisions. Stuttgart manufacturing cluster adopts hybrid deployments maintaining local custody of powertrain development documentation.
United Kingdom
Financial institutions mandate SOC 2 Type II certification as baseline vendor qualification for productivity platform procurement. FCA operational resilience requirements accelerate migration from self-managed infrastructure to managed service deployments. London banking district concentrates demand for compliance-integrated collaboration tools among asset management firms.
France
Pharmaceutical firms select hybrid architectures to maintain local custody of clinical trial documentation under ANSM guidance. CNIL enforcement actions on cross-border data transfers reshape vendor selection criteria for workforce productivity platforms. Lyon biotech corridor drives specialized demand for audit trail modules in automated document classification systems.
India
Professional services firms under 500 employees adopt self-service onboarding to eliminate implementation friction in productivity suite deployment. RBI data localization guidelines for financial services influence hybrid cloud architecture preferences. Bangalore IT services cluster exports certified deployment expertise to North American healthcare and education verticals.
G Suite Technology Services Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deployment, integration, and managed service segments. Hyperscale infrastructure providers anchor the consolidated upper tier while regional system integrators populate a fragmented middle layer. Two strategic archetypes dominate: Google Cloud-specialized deployment partners and price-competitive mid-market suite vendors. Competitive moves concentrate on certified expertise accumulation and geographic service expansion.
Within the Google Cloud specialization tier, SADA Systems and Cloudypedia occupy positions as certified deployment partners. Zoho Corporation sits within the price-competitive alternative ecosystem targeting mid-market buyers. These three entities exemplify the bifurcation between ecosystem-anchored specialists and independent suite providers challenging dominant platforms.
| Leading Market Players |
|---|
| SADA Systems |
| Cloudypedia |
| Zoho Corporation |
| Salesforce |
| Bespin Global |
| Box |
| Slack Technologies |
| Smartsheet |
| Others |
Supply Flow & Price Mechanics
Google Cloud infrastructure concentration in the United States anchors margin capture for hyperscale deployment partners, while downstream pricing power fragments across managed service tiers serving compliance-heavy verticals.
Pricing Analysis
Current-generation serverless deployment commands premium positioning against prior-generation VM-based hosting and emerging edge-computing configurations. Three-tier pricing structure across enterprise, mid-market, and self-service levels stratifies by SOC 2 certification tier and white-glove onboarding intensity. Cost compression in mid-market segments intensifies as Zoho Corporation and regional specialists compete on price-performance. Small businesses in India exhibit highest price sensitivity, while United Kingdom financial institutions accept premium positioning for ANSM-aligned audit trail modules.
Supply Chain Analysis
Tariff exposure between United States and China in semiconductor components for data center infrastructure dominates supply risk planning for hyperscale deployment partners. Primary supply concentration rests in United States, Ireland, and Singapore for Google Cloud region infrastructure. Raw material dependencies span silicon wafers, specialized cooling systems, and subsea cable capacity. Single-source vulnerability in custom AI accelerator chips creates contingency pressure. Distribution runs through certified deployment partners and direct hyperscaler channels in regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
G Suite Technology Services sits in early-cycle expansion as HIPAA-compliant cloud migration accelerates among United States healthcare providers abandoning legacy Exchange infrastructure.
For Market Incumbents: Harden defensive positioning through vertical integration into EU-sovereign data residency infrastructure and accelerated SOC 2 Type II certification pipelines. SADA Systems and Cloudypedia face margin pressure from price-competitive mid-market entrants. Certification investment in EU AI Act audit trail modules secures procurement qualification among German automotive suppliers. For New Entrants and Emerging Players: Pursue white-space capture in Southeast Asian small business segments lacking internal IT capacity for security configuration. Indian professional services firms under 500 employees represent the most penetrable end-user archetype. Channel partnership with Google Cloud deployment specialists accelerates market access without direct certification burden. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed managed service providers holding certified Google Cloud specialization and healthcare vertical concentration. Long-term viability hinges on compliance service attach rates rather than pure subscription resale. Watch FDA guidance evolution on software-as-a-medical-device as inflection signal for clinical workflow tool procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Module Development | Pre-built audit trail capabilities accelerate ANSM-aligned certification for French pharmaceutical firms. |
| Healthcare Vertical Specialization | HIPAA-compliant deployment expertise captures Texas Medical Center pharmaceutical research consortium demand. |
| Hybrid Cloud Architecture Partnership | Local data residency integration satisfies GDPR Article 44 restrictions for Stuttgart manufacturing cluster. |
| Mid-Market Self-Service Onboarding | Frictionless implementation reduces customer acquisition cost for Indian professional services segments. |
| Serverless Workflow Automation Platform | API-first design patterns enable real-time ERP synchronization for manufacturing DevOps teams. |
Methodological Framework
Desk research of hyperscaler capex disclosures, SEC filings, and EU regulatory guidance databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and compliance specialists. Primary fieldwork across United States, Germany, United Kingdom, France, and India validated secondary estimates of deployment velocity and procurement criteria. Bottom-up segmentation modeling triangulated against top-down market sizing from cloud infrastructure spend data.
Assumptions around HIPAA migration timelines, EU AI Act implementation phases, and serverless adoption curves remained fixed across the projection horizon while competitive dynamics and tariff exposure varied in sensitivity testing. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from cohort-based adoption curves and replacement cycle analysis, with inputs from educational procurement patterns and healthcare compliance expenditure trends.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting enterprise software capex or cross-border data transfer policy stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and hyperscaler infrastructure expansion plans. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Movie Editing Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Estate Management Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Torque Software Market
Software & Services
Global Application Development Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Human Identification Analysis Software Market