
 Nonconformance Management Software Market | 2026-2036
Nonconformance Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Nonconformance Management Software Market Analytics
EU MDR is restructuring how medical device and pharmaceutical firms document quality deviations, forcing legacy paper-based systems into digital replacement cycles. MasterControl Inc. leverages deep validation protocols for FDA-regulated environments. ETQ Reliance anchors its position through configurable workflows across discrete manufacturing verticals. Sparta Systems differentiates via integrated quality intelligence that connects nonconformance data to corrective action tracking.
Nonconformance management software comprises digital platforms that capture, classify, route, and resolve product or process deviations against predefined quality standards, typically incorporating electronic signatures, audit trails, and CAPA linkage to satisfy 21 CFR Part 11. Cloud-based deployment leads current investment as organizations eliminate server maintenance overhead and accelerate multi-site rollouts. Quality Assurance solutions within the software stack command the deepest enterprise commitment because they directly interface with regulatory submission packages and supplier scorecards. Manufacturing end users generate the largest volume of nonconformance records, though Healthcare adoption is accelerating as hospital networks extend quality systems into clinical supplier management.
FDA enforces electronic records integrity through 21 CFR Part 11, while EU MDR mandates systematic post-market surveillance documentation that nonconformance platforms must structure. ISO 9001 and ISO 13485 certification audits increasingly expect closed-loop digital traceability from deviation detection through root-cause closure. Stakeholders should evaluate how platform architectures accommodate simultaneous multi-jurisdiction compliance rather than sequential regional customization.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from months to weeks, forcing incumbent vendors to rebuild validation frameworks around containerized infrastructure while medical device manufacturers demand FDA 21 CFR Part 11 compliance in serverless environments.
Growth Catalysts
- FDA 21 CFR Part 820:Medical device manufacturers in the United States must maintain electronic quality system records, mandating digital nonconformance platforms for design control and production documentation.
- EU MDR post-market surveillance:European medical device firms face systematic vigilance reporting requirements that paper-based deviation tracking cannot satisfy, accelerating replacement cycles.
- Remote audit protocols:Quality teams now require real-time supplier visibility across distributed manufacturing networks, pulling cloud-based deployment models into critical infrastructure status.
Market Restraints
- Validation cost structure:FDA-regulated environments require documented software validation under 21 CFR Part 11, adding 40-60% implementation overhead versus standard enterprise software.
- Legacy system entrenchment:Discrete manufacturing verticals operate decades-old ERP integrations that resist API-based connectivity, creating technical debt barriers.
- Substitution by modular QMS suites:Integrated quality management platforms from adjacent software categories absorb nonconformance functionality, threatening standalone positioning.
Strategic Opportunities
- Clinical supplier management:Hospital networks in the United States are extending quality systems into vendor credentialing and device tracking, opening healthcare vertical expansion.
- ISO 13485 convergence:Medical device suppliers seeking dual FDA-CE marking must harmonize deviation documentation, creating demand for multi-jurisdiction workflow engines.
- AI-assisted root-cause analysis:Machine learning classification of nonconformance patterns converges with predictive CAPA triggering, enabling closed-loop automation.
Industry Challenges
- CSV talent scarcity:Computer system validation specialists with FDA-regulated software experience command premium compensation, constraining implementation velocity.
- Legacy ERP integration complexity:SAP and Oracle manufacturing modules require custom middleware development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonconformance Management Software Market |
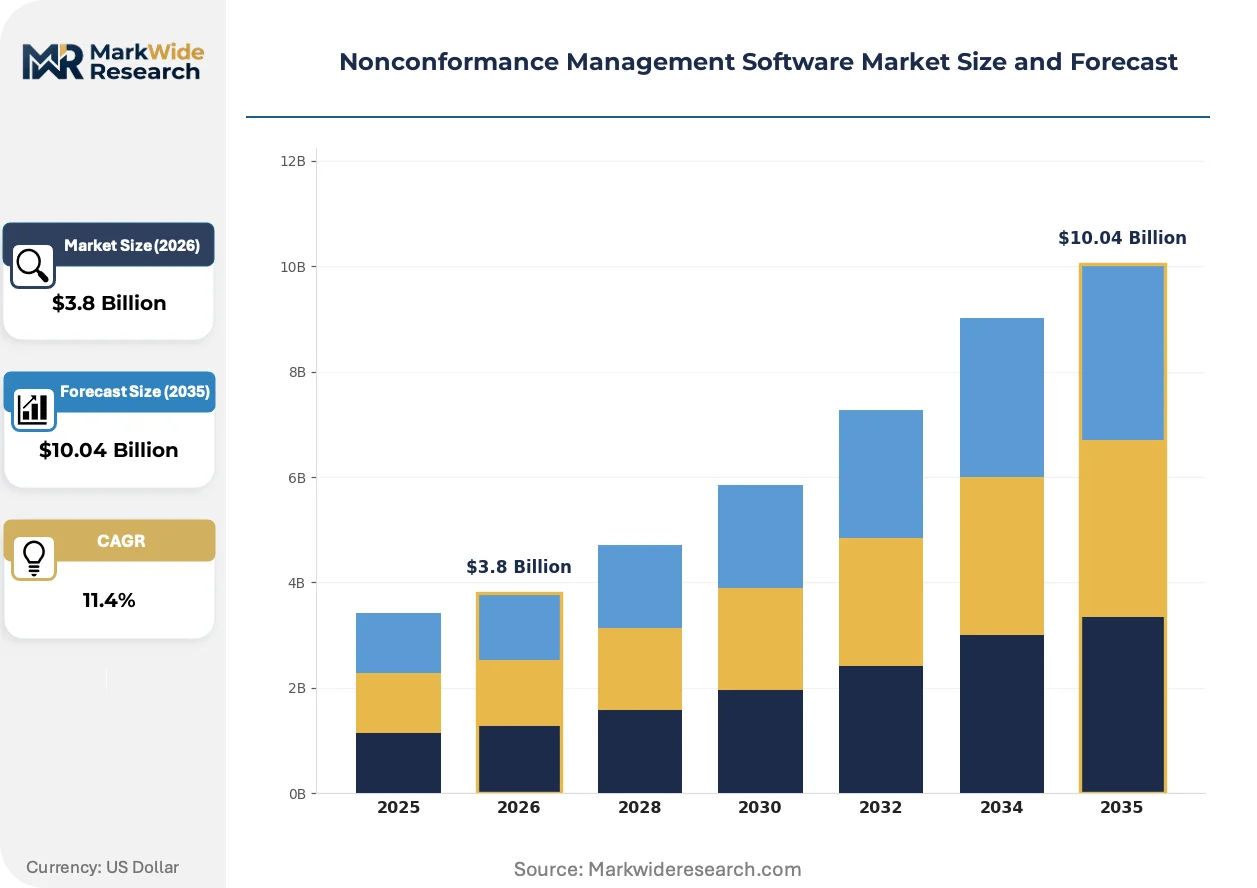
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Retail, Healthcare, Aerospace Solution: Quality Assurance, Compliance Management, Risk Management, Auditing Functionality: Reporting, Tracking, Analytics, Documentation |
| Companies Covered | MasterControl Inc., ETQ Reliance, Sparta Systems, Intelex Technologies, AssurX, ComplianceQuest, TrackWise Digital, Greenlight Guru, MetricStream, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonconformance Management Software Market Evolving Landscape
Artificial intelligence and API-first architectures are rewriting how deviation data flows from shop-floor sensors through regulatory submissions, collapsing the latency between detection and corrective action initiation.
Machine learning classification engines are rewriting nonconformance triage by automatically categorizing deviation severity against ISO 13485 risk matrices. Medical device quality teams in Germany and Switzerland are piloting these systems for supplier scorecard automation. The technology is rewriting the economics of multi-site quality operations by reducing manual classification labor.
EU MDR's systematic post-market surveillance documentation mandate is forcing medical device manufacturers to restructure deviation workflows around EUDAMED-compatible data formats. Firms seeking CE marking must now demonstrate closed-loop traceability from complaint through CAPA closure. European notified bodies are rejecting paper-based evidence packages, compressing digital transformation timelines.
Hospital procurement departments are consolidating vendor quality requirements into unified scorecards that demand real-time nonconformance visibility. United States health systems now require suppliers to expose API endpoints for deviation alerts as a contract precondition. This behavior shift is most visible in orthopedic and cardiovascular device categories where supply base concentration amplifies buyer leverage.
Nonconformance Management Software Market Segmentation
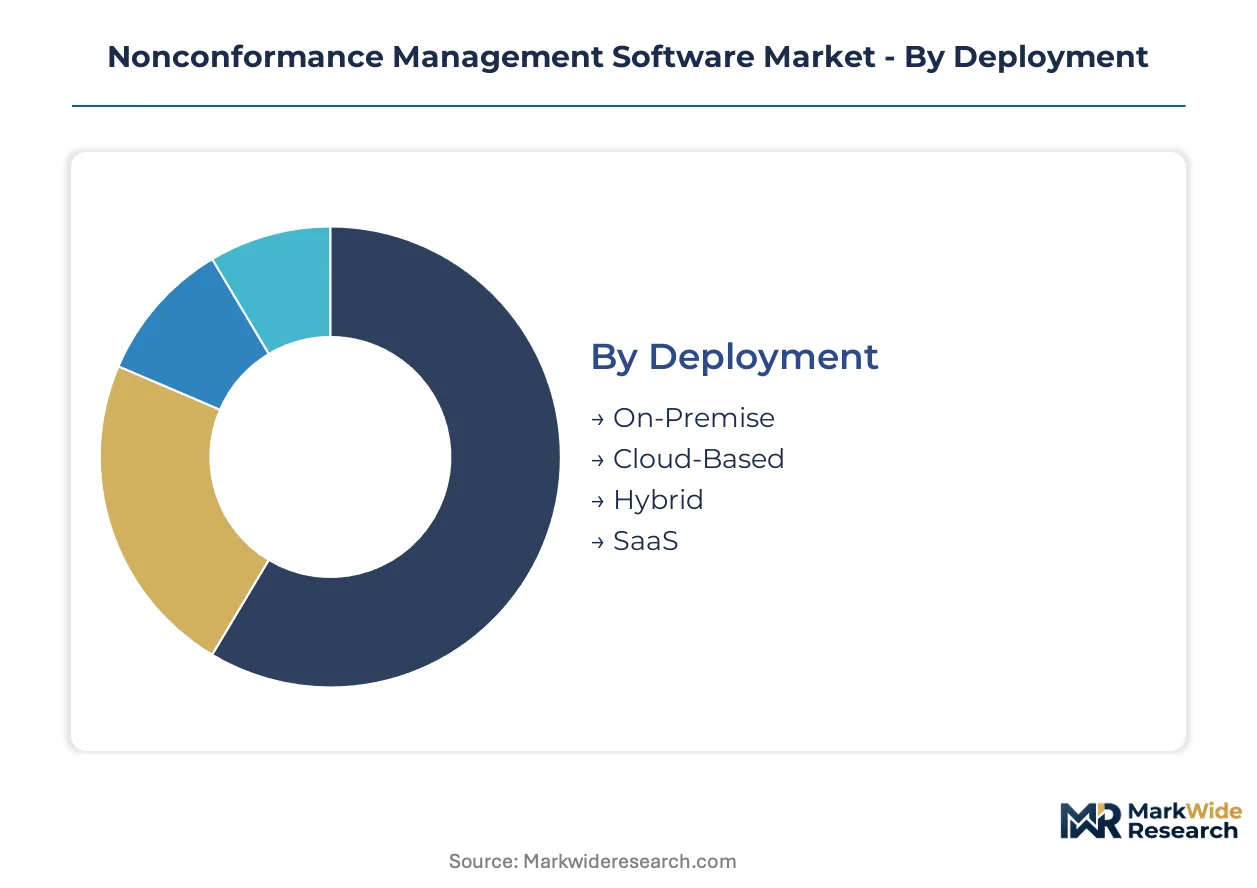
Segmentation in nonconformance management software reveals how regulatory intensity and infrastructure maturity shape purchasing decisions. Deployment models diverge sharply between FDA-validated environments and lighter compliance contexts, while solution types map directly to audit preparation burdens.
Deployment:
Cloud-based and SaaS offerings carry lighter 21 CFR Part 11 validation overhead than on-premise equivalents, though hybrid architectures dominate where ERP integration complexity demands local data residency.
- On-Premise:Installed within client data centers with full hardware control. Medical device manufacturers in Germany and Switzerland retain this model where Swissmedic and BfArM audits require physical server access for inspection protocols.
- Cloud-Based:Vendor-managed infrastructure with subscription pricing. Quality teams across US orthopedic device clusters prioritize this model for multi-site supplier visibility without server maintenance overhead.
- Hybrid:Sensitive deviation records remain on-premise while analytics and reporting shift to cloud tiers. FDA-regulated manufacturers in Massachusetts and Minnesota deploy this architecture to partition CAPA data from operational dashboards.
- SaaS:Fully managed software with continuous validation updates. Mid-tier medical device suppliers in Ireland and the Netherlands adopt this model to compress implementation timelines for EU MDR readiness.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
End-user concentration reflects where deviation documentation carries the steepest regulatory penalties, with manufacturing and healthcare commanding premium pricing for validated workflows.
- Manufacturing:Discrete production environments generate the highest nonconformance record volumes. Automotive suppliers in Stuttgart and medical device contract manufacturers in Tijuana deploy these platforms for ISO 13485 traceability across multi-tier supply chains.
- Healthcare:Hospital networks and clinical suppliers extend quality systems into vendor credentialing. US health systems in Texas and Florida now mandate real-time deviation APIs from orthopedic and cardiovascular device vendors as contract preconditions.
- Retail:Product quality teams track supplier deviations against private-label specifications. European grocery chains in France and the United Kingdom use these platforms for food safety documentation aligned with EFSA traceability requirements.
- Aerospace:AS9100-certified suppliers manage nonconformances across complex assemblies. Tier-1 manufacturers in Toulouse and Seattle require closed-loop documentation for FAA and EASA dual-certification maintenance.
Manufacturing retains the deepest enterprise commitment, while Healthcare expands most quickly as procurement departments consolidate vendor quality requirements.
Solution:
Solution purchasing correlates with audit frequency, where quality assurance modules command the longest contract terms due to direct regulatory submission dependencies.
- Quality Assurance:Core deviation capture, classification, and resolution workflows. FDA-regulated medical device firms in California and Minnesota treat this as infrastructure for 21 CFR Part 820 design control documentation.
- Compliance Management:Structured regulatory mapping and submission package assembly. EU MDR-bound manufacturers in Ireland and Denmark prioritize this solution for EUDAMED-compatible vigilance reporting.
- Risk Management:ISO 14971-aligned hazard analysis and risk control traceability. Swiss and German device suppliers integrate this with post-market surveillance for notified body inspection readiness.
- Auditing:Scheduled and ad-hoc audit execution with electronic signature capture. Remote audit protocols adopted during 2020-2021 have entrenched this solution across distributed manufacturing networks.
Quality Assurance dominates current deployment value, with Compliance Management gaining share fastest as EU MDR deadlines compress replacement cycles.
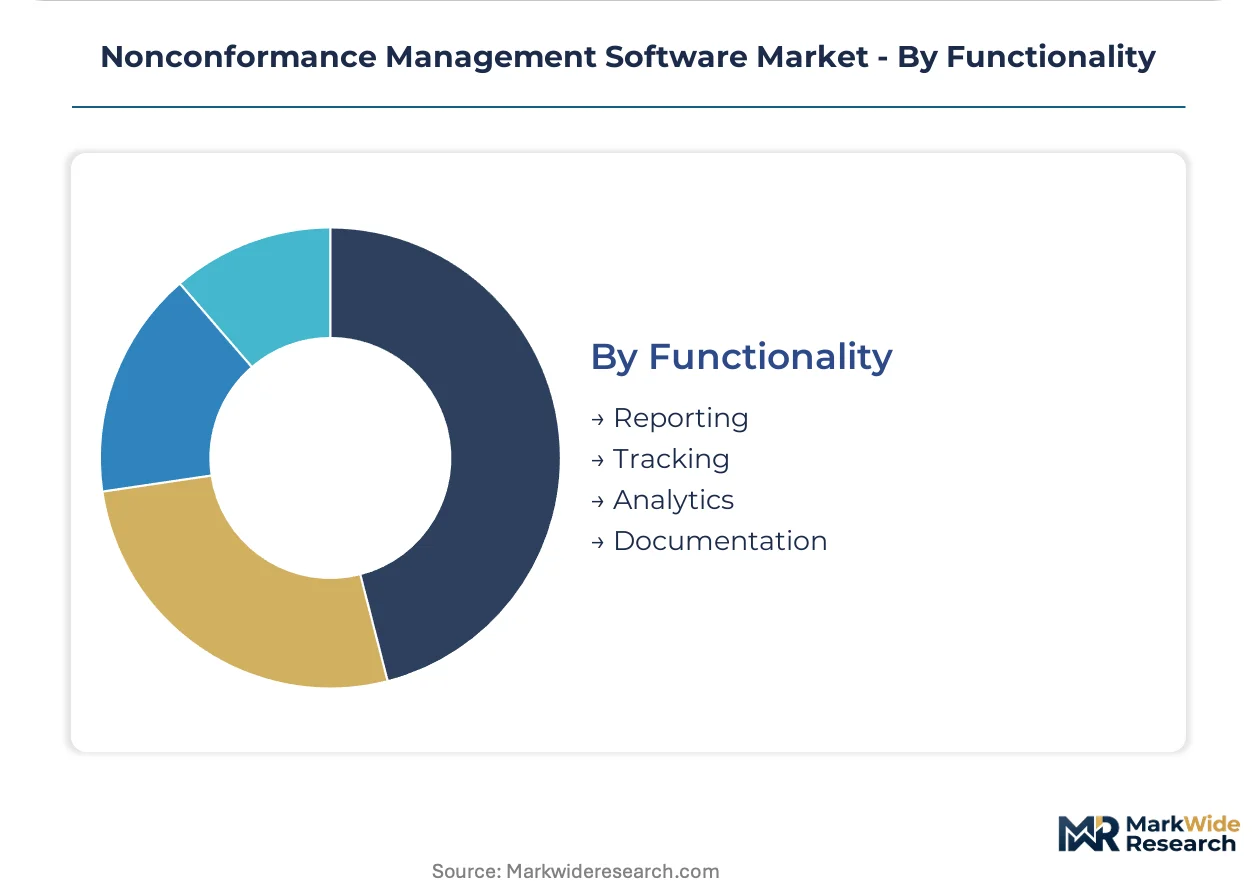
Functionality:
Functionality adoption follows the data latency requirements from shop-floor detection through regulatory submission, with tracking and documentation commanding the tightest integration specifications.
- Reporting:Configurable dashboards and regulatory submission formatting. FDA 483 response preparation drives demand among US-based device manufacturers facing inspection frequency increases.
- Tracking:Real-time deviation status and escalation routing. Multi-site medical device suppliers in Singapore and Costa Rica deploy this for 24-hour handoff across time zones.
- Analytics:Trend analysis and predictive pattern recognition. Machine learning classification pilots in Germany and Switzerland automate severity scoring against ISO 13485 risk matrices.
- Documentation:Electronic signatures, audit trails, and 21 CFR Part 11 record integrity. This functionality underpins every validated deployment regardless of other module selection.
Documentation anchors every implementation, with Analytics showing the steepest expansion trajectory as AI-assisted root-cause analysis matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nonconformance management software originated in the United States during the 1990s as FDA electronic record mandates forced medical device manufacturers toward digital quality systems. European and Asia-Pacific markets subsequently developed distinct regulatory-driven adoption patterns.
United States
FDA 21 CFR Part 820 quality system regulations and 21 CFR Part 11 electronic records requirements drive enterprise procurement among medical device manufacturers. The FDA's inspection enforcement intensity in Massachusetts and Minnesota clusters accelerates replacement of legacy paper systems. Boston-area orthopedic device firms deploy cloud-native platforms for multi-site supplier visibility.
Germany
EU MDR post-market surveillance mandates and BfArM inspection protocols compel digital transformation among Mittelstand medical device suppliers. ISO 13485 certification audits in Baden-Württemberg and Bavaria increasingly demand closed-loop deviation traceability. Stuttgart automotive suppliers extend these platforms into AS9100 aerospace documentation.
Switzerland
Swissmedic inspection requirements and dual FDA-CE marking strategies concentrate demand among precision instrument manufacturers. ISO 14971 risk management integration with post-market surveillance drives platform selection in Basel and Zurich clusters. German-speaking cantons pilot AI-assisted root-cause classification for supplier scorecard automation.
Ireland
EU MDR readiness deadlines and EUDAMED-compatible vigilance reporting compress implementation timelines for pharmaceutical and device contract manufacturers. IDA Ireland investment incentives attract quality system digitization among American multinational subsidiaries. Cork and Galway medical technology parks prioritize SaaS deployment models.
Singapore
HSA regulatory alignment with FDA and EU standards positions the city-state as Asia-Pacific quality system hub. Multi-site medical device suppliers deploy real-time tracking functionality for 24-hour handoff across time zones. Jurong biomedical manufacturing clusters demand API-first architectures for supplier network integration.
Nonconformance Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth and regulatory specialization. The vendor base organizes into three tiers: incumbent enterprise suites with decades-long FDA validation frameworks, cloud-native challengers compressing implementation cycles, and integrated QMS platforms absorbing nonconformance functionality. Consolidation pressure intensifies as mid-tier suppliers seek scale for multi-jurisdiction compliance engineering. Strategic moves center on M&A for validation asset acquisition and API-first architecture rebuilds.
Within the incumbent validation tier, MasterControl Inc. and Sparta Systems anchor positions through deep FDA-regulated environment expertise. ETQ Reliance exemplifies the configurable workflow approach across discrete manufacturing verticals. These three represent distinct archetypes: MasterControl Inc. occupies the historical validation depth position, Sparta Systems sits within integrated quality intelligence, and ETQ Reliance anchors configurable vertical specialization.
| Leading Market Players |
|---|
| MasterControl Inc. |
| ETQ Reliance |
| Sparta Systems |
| Intelex Technologies |
| AssurX |
| ComplianceQuest |
| TrackWise Digital |
| Greenlight Guru |
| MetricStream |
| Others |
Value Network & Pricing Analysis
Validation-depth bifurcation between FDA 21 CFR Part 11-certified platforms and lighter compliance tools manifests in both pricing power and supply chain configuration. Premium-tier vendors command sustained margins through computer system validation documentation and audit-ready infrastructure, while commodity SaaS providers compete on compressed implementation timelines.
Pricing Analysis
Subscription-based tiering across enterprise, professional, and starter levels anchors the dominant pricing structure. Price differentiation hinges on validation documentation depth and multi-jurisdiction compliance engine coverage. Cost compression in the mid-market tier intensifies as integrated QMS suites absorb standalone nonconformance functionality. Hospital procurement departments exhibit highest price sensitivity due to budget consolidation pressures, whereas FDA-regulated medical device manufacturers prioritize audit readiness over license cost.
Supply Chain Analysis
Cloud infrastructure provision rests on hyperscaler data centers concentrated in the United States, Ireland, and Singapore. Software development labor pools, validation documentation services, and API integration middleware constitute critical input dependencies. Single-source vulnerability in specialized computer system validation talent constrains implementation velocity for complex deployments. Distribution runs through direct enterprise sales teams supplemented by quality consulting channel partners serving discrete manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in nonconformance management software stems from automation of validation documentation and tiered premium positioning around multi-jurisdiction compliance engines.
For Market Incumbents: Hedge against modular QMS suite substitution by deepening vertical integration into computer system validation services and API-first architecture rebuilds. Prioritize M&A targeting cloud-native challengers with containerized infrastructure expertise to compress deployment cycles without sacrificing FDA compliance depth. For New Entrants and Emerging Players: AI-assisted root-cause classification engines offer a technology-first wedge into the supplier scorecard automation segment. Target mid-tier medical device suppliers in Ireland and the Netherlands seeking rapid EU MDR readiness through SaaS deployment models with pre-configured EUDAMED-compatible workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms possessing validated FDA frameworks but sub-scale geographic footprint. Long-term viability centers on multi-jurisdiction compliance engineering capabilities. Watch AI-assisted classification adoption rates in German-speaking cantons as inflection indicator for platform differentiation sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Rebuild | Containerized infrastructure enables serverless FDA 21 CFR Part 11 compliance for medical device manufacturers. |
| Acquisition of Validation Specialists | Computer system validation talent scarcity constrains implementation velocity across cloud-native deployments. |
| EU MDR Workflow Pre-Configuration | EUDAMED-compatible vigilance reporting compresses replacement cycles for European device suppliers. |
| AI-Assisted Classification Integration | Machine learning severity scoring against ISO 13485 risk matrices automates supplier scorecard generation. |
| Healthcare Vertical Expansion | Hospital network procurement consolidation demands real-time deviation APIs as contract preconditions. |
Research Methodology
Bottom-up quality assurance deployment modeling reconciled against top-down cloud infrastructure tracking forms the analytical core. Primary interviews with quality directors at medical device manufacturers, computer system validation consultants, hospital procurement officers, and regulatory affairs leads combined with secondary validation from FDA 483 observation databases, EU MDR technical documentation guidance, ISO 13485 certification audit records, and hyperscaler compliance disclosure filings. Triangulation between stakeholder-reported implementation timelines and vendor-reported subscription metrics ensures cross-verified volume estimation.
Historical trendline analysis of validation documentation automation adoption and cloud deployment penetration informed projection parameters. Segmentation dimensions span deployment architecture, end-user vertical intensity, solution module bundling, and geographic regulatory cluster complexity. CAGRs derive from fitted growth curves applied to validated base-year estimates, with medical device manufacturer capital expenditure cycles and EU MDR deadline compression serving as industry-specific forecast inputs across the modeling period.
The model holds under sustained FDA inspection enforcement intensity and EU MDR post-market surveillance mandate adherence; deviation in regulatory delay or hyperscaler compliance framework changes would shift trajectory. A small set of named triggers warrants ongoing watch: AI classification regulatory acceptance, legacy ERP API accessibility improvements, and hospital procurement budget consolidation severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Expense Management Software Market
Software & Services
Movie Editing Software Market
Software & Services
Sales Training Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Product Optimization Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Cemetery Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
E-Clinical Solution Software Market
Software & Services
Global Human Capital Management Software Market