
 Deck Software Market | 2026-2036
Deck Software Market Size, Share, and Industry Trends Forecast 2026-2036
Deck Software Market Analytics
Multi-source procurement of deck design and project management tools is broadening across mid-sized construction firms. Microsoft anchors the enterprise tier through deep integration with Office ecosystems and Azure infrastructure. Canva competes aggressively on visual template libraries that lower design barriers for non-specialist users. Atlassian sustains developer-centric workflows that extend into cross-functional project coordination.
Deck software encompasses digital platforms that enable structural design visualization, material quantification, and client presentation for outdoor living construction projects, typically rendering three-dimensional models with load-bearing calculations and automated code compliance checks. The primary commercial purpose centers on compressing sales cycles for contractors while reducing estimation errors that erode project margins. Cloud-Based deployment leads current uptake trajectories as field crews require real-time synchronization between tablet-based site measurements and office estimating systems. Presentation Tools retain the largest installed base among product types, though Analytics Solutions are capturing disproportionate investment as firms seek to optimize material yield and labor scheduling.
The National Association of Home Builders influences voluntary software certification protocols that shape contractor purchasing criteria in the United States. State-level licensing boards in California, Florida, and Texas increasingly reference digital plan submission standards that favor platforms with integrated engineering validation. Stakeholders must weigh interoperability commitments against the risk of vendor lock-in as platform ecosystems consolidate around adjacent construction technology categories.
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing residential construction contractors to replace manual takeoff methods with integrated digital platforms that synchronize field measurements with back-office estimating systems.
Growth Catalysts
- EU AI Act Cloud Mandates:European contractors face procurement deadlines that accelerate platform upgrades, compressing sales cycles for vendors with compliant infrastructure.
- Material Yield Analytics:Automated code compliance checks embedded in deck design software reduce estimation errors that erode project margins for mid-sized builders.
- United States Home Improvement Retail:National builders and large retailers drive platform standardization through volume procurement agreements that favor integrated engineering validation.
Market Restraints
- Interoperability Lock-in Risk:Consolidation around adjacent construction technology categories creates switching costs that trap contractors in vendor ecosystems with limited API flexibility.
- State-Level Licensing Variability:California, Florida, and Texas maintain divergent digital plan submission standards that fragment development roadmaps and inflate certification overhead.
- Labor Scheduling Complexity:Real-time synchronization demands between tablet-based site crews and office systems expose bandwidth limitations in rural construction zones.
Strategic Opportunities
- Analytics Solutions Investment:Firms seek disproportionate allocation toward material yield optimization and labor scheduling modules that extend beyond presentation tools.
- Mid-Sized Firm Multi-Source Procurement:Construction companies below national scale increasingly evaluate best-of-breed combinations rather than single-vendor suites.
- National Association of Home Builders Certification:Voluntary software protocols shape contractor purchasing criteria and create preferred vendor status for compliant platforms.
Industry Challenges
- Legacy System Integration Friction:Field crews using established estimating spreadsheets resist migration to cloud-based workflows despite synchronization benefits.
- Cross-Functional Coordination Gaps:Developer-centric project management tools require adaptation for contractor sales teams unfamiliar with agile methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deck Software Market |
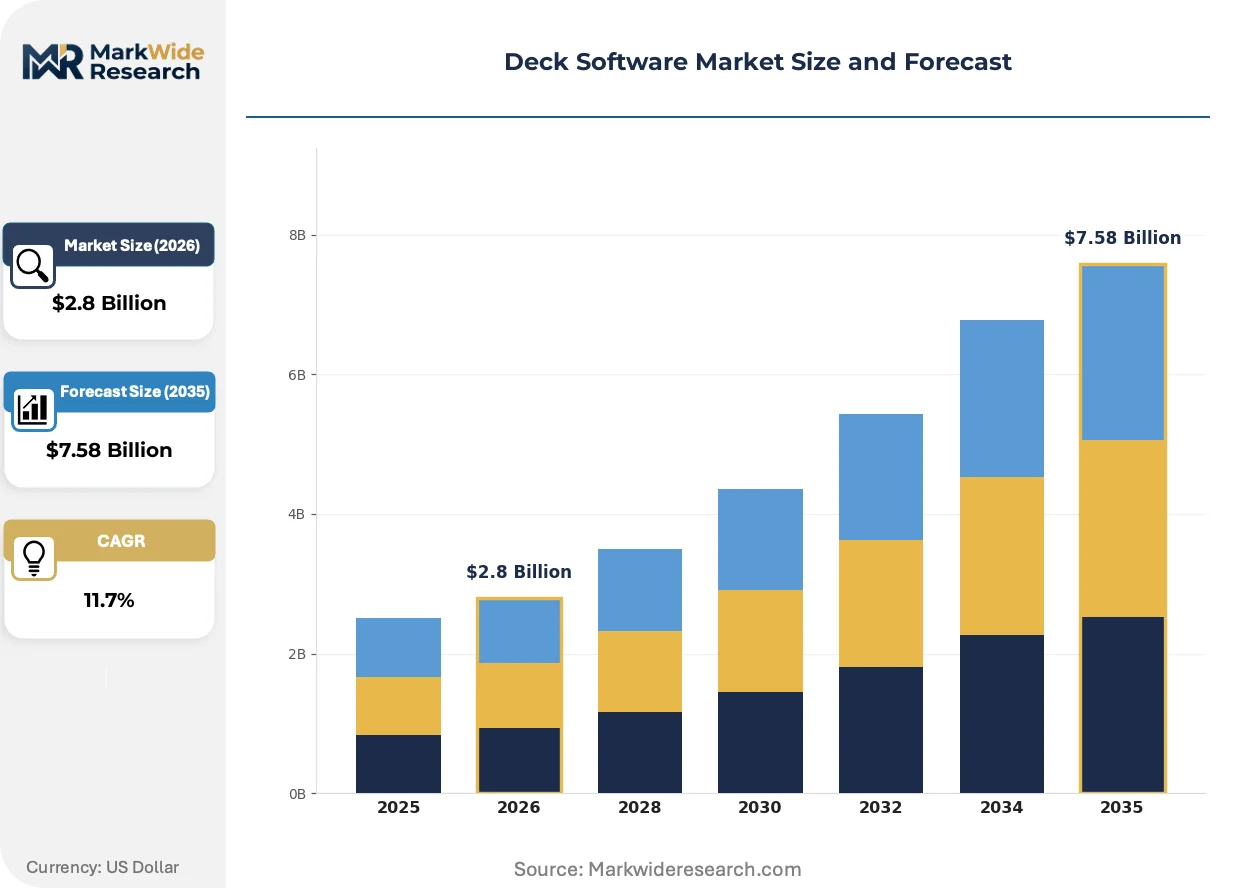
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Presentation Tools, Collaboration Platforms, Design Software, Analytics Solutions Deployment: On-Premises, Cloud-Based, Hybrid, Open Source End User: Education, Corporate, Non-Profit, Freelancers Application: Marketing, Sales, Training, Project Management |
| Companies Covered | Asana, monday.com, Canva, Semrush, Hootsuite, Microsoft, ClickUp, Atlassian, Slack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deck Software Market Evolving Landscape
Three-dimensional modeling capabilities are extending from visualization into structural engineering validation, compressing the traditional handoff between design and permitting phases.
Parametric design automation is expanding into load-bearing calculation workflows. Regional builders in the United States adopt these tools at accelerating pace as state licensing boards mandate digital submission formats. The technology is expanding into permit-ready documentation that eliminates manual engineering review delays.
The EU AI Act establishes algorithmic transparency requirements for construction software processing structural safety data. European contractors must demonstrate audit trails for automated code compliance checks. Deck design platforms with embedded engineering validation face the steepest compliance curves in Germany and France.
Subscription-based access models displace perpetual licenses among mid-sized construction firms. National home improvement retailers negotiate enterprise terms that bundle training and priority support. This shift concentrates most visibly in the United States where platform standardization agreements lock in multi-year commitments.
Deck Software Market Segmentation
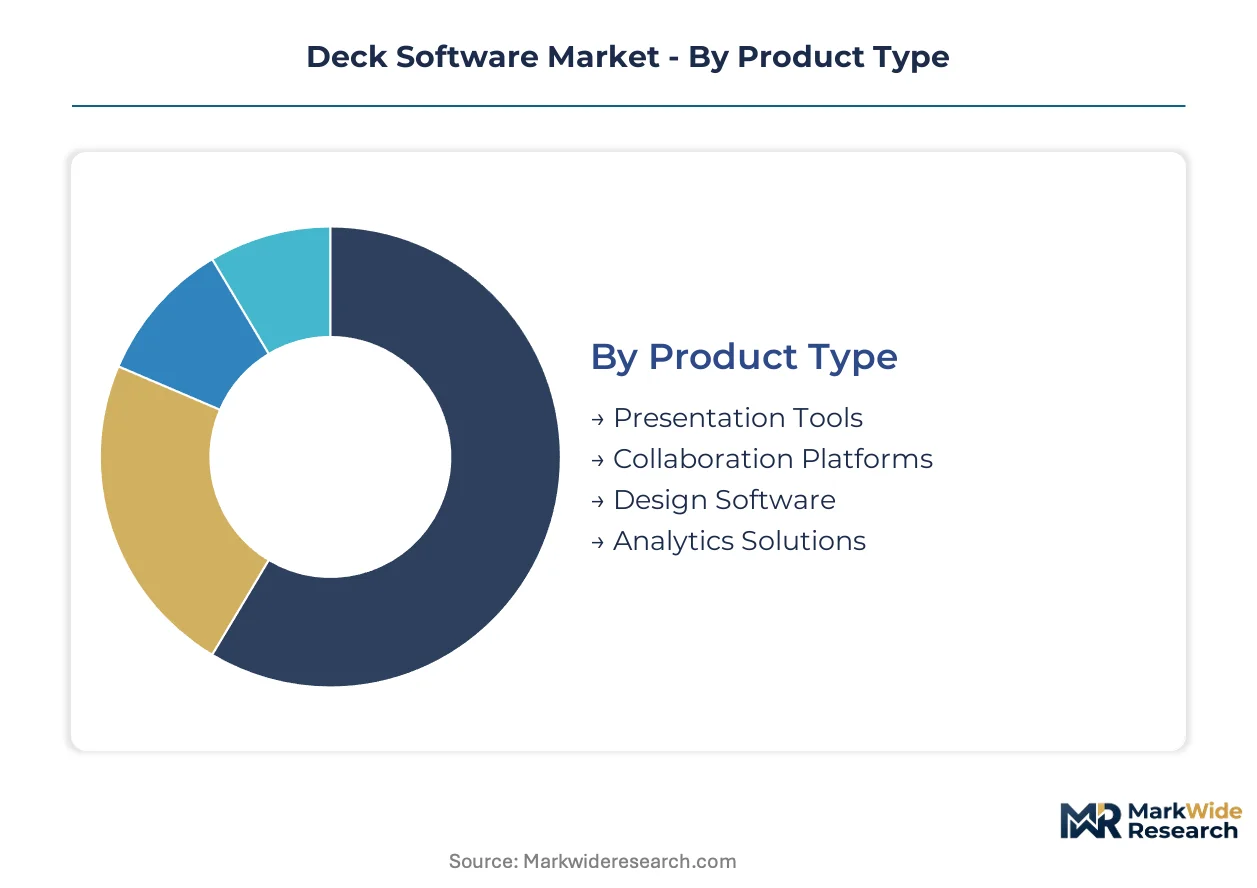
Deck software purchasing decisions pivot on deployment flexibility and end-user technical sophistication. Contractors prioritize synchronization capabilities between field and office systems. Corporate procurement teams weigh integration overhead against per-seat licensing economics.
Product Type:
Pricing tolerance varies sharply by functional depth — visualization commands premium rates while analytics modules justify subscription upgrades through measurable ROI.
- Presentation Tools:Template-driven platforms dominate current installed bases through drag-and-drop interfaces and rapid client-ready output generation. Demand concentrates among residential construction contractors in the United States where sales cycle compression drives procurement decisions; the National Association of Home Builders certification protocols favor platforms with integrated code compliance visualization.
- Analytics Solutions:Embedded material yield calculators and labor scheduling algorithms extend platform value beyond design into operational optimization. Growth tilts toward mid-sized builders in Germany and France facing EU AI Act audit trail mandates for automated structural safety checks.
- Collaboration Platforms:Real-time markup and version control tools synchronize distributed project teams across hybrid work environments.
- Design Software:Parametric modeling engines with load-bearing calculation modules serve specialist engineering workflows requiring permit-ready documentation output.
Volume sits with Presentation Tools; growth tilts toward Analytics Solutions.
Deployment:
Connectivity infrastructure maturity determines feasible architecture choices for field-based workforces.
- Cloud-Based:Tablet-to-office synchronization enables real-time measurement upload and estimate revision without local server dependency. Demand concentrates in United States suburban construction corridors where national home improvement retailers mandate platform standardization across contractor networks; bandwidth limitations in rural zones create deployment friction.
- Hybrid:Local processing of sensitive structural calculations combined with cloud-based collaboration features addresses data residency requirements. Adoption accelerates among European contractors navigating EU AI Act algorithmic transparency obligations while maintaining field crew autonomy.
- On-Premises:Legacy estimating system integration preserves established workflows for risk-averse operations.
- Open Source:Customizable frameworks attract developer-heavy organizations with internal IT capacity for platform extension.
Deployment gravity favors Cloud-Based for new procurement; Hybrid architectures gain share fastest among compliance-sensitive buyers.
End User:
Budget authority and procurement cycle length segment buyer behavior across organizational types.
- Corporate:Enterprise licensing agreements bundle training and priority support through volume procurement. Demand concentrates in United States national builder headquarters where platform standardization reduces vendor management overhead.
- Education:Discounted academic licensing builds future professional familiarity with specific platform ecosystems.
- Non-Profit:Grant-funded project budgets prioritize perpetual licenses over recurring subscription commitments.
- Freelancers:Per-project pricing tolerance limits feature depth but drives template library breadth requirements.
Revenue concentration rests with Corporate buyers; Freelancers represent the steepest expansion trajectory as independent contractor registration grows.
Application:
Functional use case determines integration requirements and success metrics for platform selection.
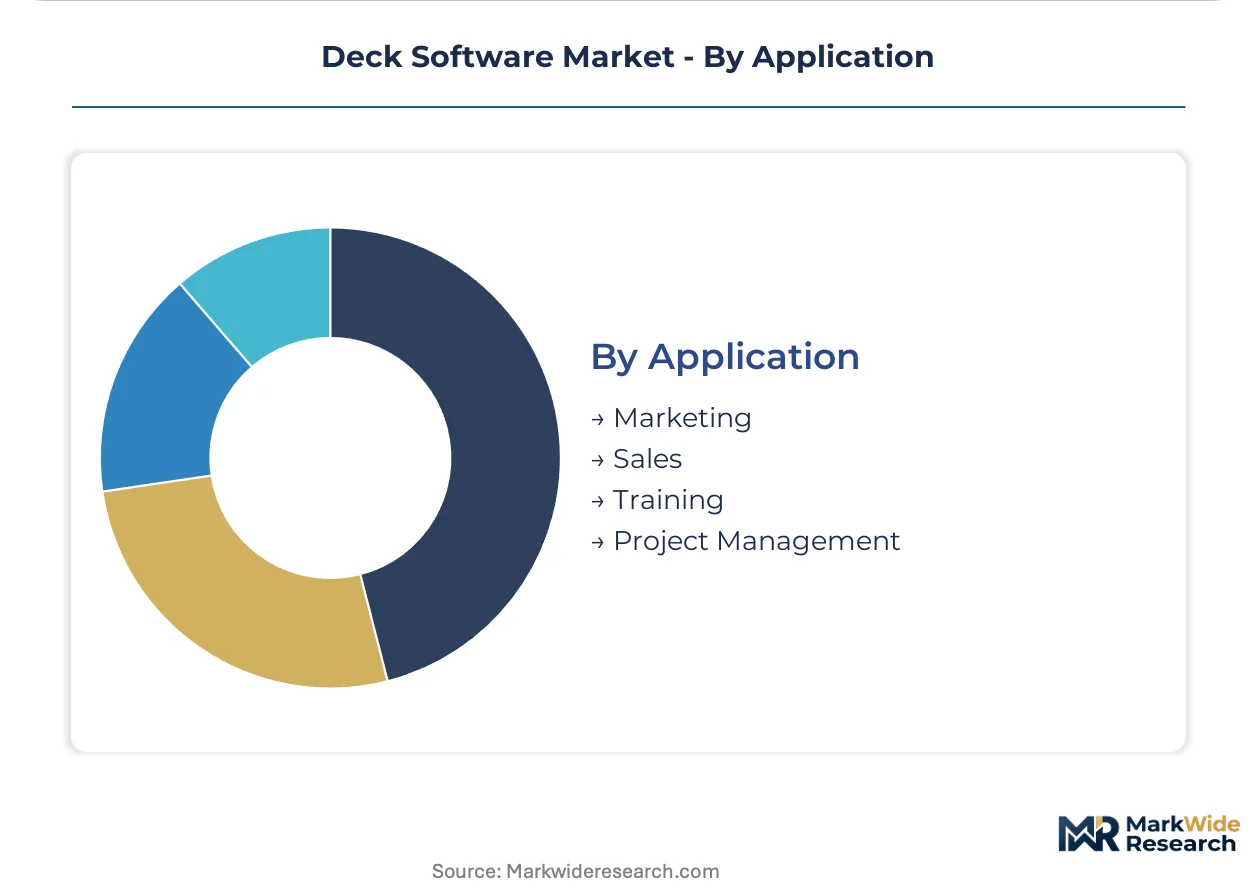
- Sales:Rapid proposal generation with 3D visualization compresses client decision timelines and reduces estimation error rates. Demand concentrates among United States residential contractors where material yield accuracy directly protects project margins.
- Project Management:Cross-functional coordination tools adapt developer-centric workflows for construction crew scheduling and subcontractor milestone tracking.
- Marketing:Portfolio presentation capabilities support contractor brand differentiation in competitive bidding environments.
- Training:Onboarding modules reduce platform adoption friction for field crews transitioning from manual estimation methods.
Commercial intensity clusters around Sales applications; Project Management functionality is climbing the fastest as contractor operations digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Timber processing clusters in the Pacific Northwest anchor North American deck material supply chains, while EU regulatory mandates reshape software procurement patterns across member states.
United States
National home improvement retailers and large builders drive platform standardization through volume procurement agreements. State-level licensing boards in California, Florida, and Texas increasingly reference digital plan submission standards that favor platforms with integrated engineering validation. The National Association of Home Builders influences voluntary certification protocols that shape contractor purchasing criteria nationwide.
Germany
EU AI Act algorithmic transparency requirements impose steep compliance curves on deck design platforms processing structural safety data. German contractors must demonstrate audit trails for automated code compliance checks embedded in three-dimensional modeling software. Industrial concentration in Bavaria and North Rhine-Westphalia accelerates adoption of parametric design automation with load-bearing calculation capabilities.
France
Cloud migration mandates under EU digital governance frameworks force residential construction contractors to replace manual takeoff methods with integrated platforms. French state-level digital plan submission standards fragment development roadmaps for vendors seeking cross-border certification. The Île-de-France region concentrates demand for hybrid deployment architectures that combine local structural calculation processing with cloud-based collaboration features.
United Kingdom
Mid-sized construction firms increasingly evaluate best-of-breed combinations rather than single-vendor suites for deck design and project management. Subscription-based access models displace perpetual licenses as procurement teams weigh integration overhead against per-seat licensing economics. Greater London anchors corporate buyer concentration where enterprise licensing agreements bundle training and priority support.
Canada
Field crews in rural construction zones face bandwidth limitations that create deployment friction for cloud-based synchronization between tablet-based site measurements and office estimating systems. Ontario and British Columbia lead provincial adoption of digital takeoff tools as contractors seek to compress sales cycles and reduce estimation errors. Provincial licensing authorities reference NAHB-influenced certification protocols when evaluating platform compliance.
Deck Software Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and template library depth, producing a tiered structure where enterprise ecosystems anchor the high end and specialized visualization tools capture mid-market share. The vendor base clusters around three strategic archetypes: productivity-suite incumbents with deep Office integration, design-centric platforms competing on visual template breadth, and developer-oriented workflow specialists extending into cross-functional coordination. Competitive moves concentrate on M&A for adjacent construction technology capabilities and strategic partnerships with national home improvement retailers.
Among productivity-suite incumbents, Microsoft anchors enterprise-tier positioning through Azure infrastructure and Office ecosystem integration. Canva exemplifies the design-centric archetype with aggressive competition on visual template libraries that lower barriers for non-specialist users. Atlassian occupies a position within the developer-oriented tier, sustaining workflows that extend into cross-functional project coordination for contractor operations.
| Leading Market Players |
|---|
| Asana |
| monday.com |
| Canva |
| Semrush |
| Hootsuite |
| Microsoft |
| ClickUp |
| Atlassian |
| Slack |
| Others |
Value Network & Pricing Analysis
Cloud migration mandates under the EU AI Act are compressing development timelines for deck software vendors while simultaneously concentrating procurement power among national home improvement retailers in the United States who negotiate volume-based standardization agreements. This regulatory-technology intersection elevates compliance costs for smaller developers while rewarding platforms with pre-certified engineering validation modules.
Pricing Analysis
Warranty and priority support bundling separates enterprise-tier agreements from standard SaaS subscriptions, with national builders in the United States demanding multi-year contracts that include training and dedicated account management. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, integration depth, and certification status. Pricing pressure stems from mid-sized construction firms evaluating best-of-breed combinations rather than single-vendor suites, compressing margins for platforms lacking differentiated analytics modules. Freelancers and independent contractors exhibit highest price sensitivity, while corporate procurement teams prioritize total cost of ownership over per-seat licensing.
Supply Chain Analysis
Freight and data residency costs are tilting European contractors toward hybrid deployment architectures that process structural calculations locally while synchronizing collaboration features through cloud infrastructure. Software development concentrates in the United States, Germany, and United Kingdom, with specialized engineering validation modules drawing from timber processing clusters in the Pacific Northwest and Bavaria. Supply chain risk centers on single-source vulnerability for integrated code compliance engines that must satisfy divergent state-level licensing standards in California, Florida, and Texas. Distribution runs through national home improvement retailer procurement networks and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deck software market functions as a cost-of-compliance story where EU AI Act algorithmic transparency requirements erect barrier-to-entry moats favoring platforms with pre-built audit trail capabilities and certified engineering validation modules.
For Market Incumbents: Hedge against interoperability lock-in risk by deepening API flexibility and pursuing strategic partnerships with adjacent construction technology vendors rather than defensive acquisition strategies. Microsoft and Atlassian face emerging threats from specialized visualization platforms competing on template library breadth. Prioritize certification investment with the National Association of Home Builders to secure preferred vendor status in United States procurement cycles. For New Entrants and Emerging Players: National home improvement retailer procurement teams represent the most penetrable channel partner type for mid-market positioning, offering volume pathways that bypass direct enterprise sales complexity. White-space targets include rural construction zones in Canada and hybrid deployment architectures for EU compliance-sensitive buyers. A focused go-to-market angle centers on material yield analytics modules that demonstrate measurable ROI through labor scheduling optimization. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by productivity-suite incumbents seeking adjacent construction technology capabilities and cross-functional workflow extension. Long-term viability favors platforms with embedded engineering validation and multi-source procurement flexibility rather than point solutions dependent on single-vendor ecosystem lock-in. The signal to watch is state-level digital plan submission standardization momentum in Texas and Florida as inflection indicator for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and Office ecosystem anchoring secures enterprise-tier positioning against specialized competitors. |
| Strategic Partnership | National home improvement retailer agreements lock in multi-year standardization commitments across contractor networks. |
| Acquisition of Specialist Firm | Engineering validation module targets compress permitting phase handoffs for residential builders. |
| Geographic Expansion | EU AI Act compliance investment opens procurement pathways in Germany and France for audit-ready platforms. |
| Product Launch | Material yield analytics modules capture disproportionate investment as firms seek operational optimization beyond visualization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with residential construction contractors, enterprise software procurement officers, platform engineering leads, and National Association of Home Builders certification directors. Secondary sources included EU AI Act implementation guidance, state-level licensing board digital submission standards, and hyperscaler infrastructure deployment disclosures. Bottom-up segment sizing triangulated against top-down market value estimates derived from volume procurement agreement reporting.
Reconciliation of deployment model adoption curves, organization size penetration rates, and regional regulatory compliance timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type functional depth, cloud-hybrid-on-premises architecture preference, and end-user budget authority tier. CAGRs were derived from installation base growth trajectories and subscription revenue scaling patterns, with specific weighting applied to field crew synchronization demand and automated code compliance check adoption.
Caveats apply where bandwidth infrastructure deployment in rural construction zones or divergent state-level licensing standardization could materially shift the outlook for cloud-based platform adoption. Forecasts reflect assumptions regarding EU AI Act enforcement consistency and United States home improvement retailer procurement consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
MES Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Logistics Services Software Market
Software & Services
Global Call Center Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
3D Animation Production Software Market
Software & Services
Estate Management Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Diagram Software Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Website Translation Software Market