
 Online Donation Software Market | 2026-2036
Online Donation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Online Donation Software Market Outlook
North American SaaS infrastructure capacity is decoupling from legacy payment processor dependencies as dedicated nonprofit technology stacks mature. Bloomerang leverages donor retention algorithms to sustain above-average lifetime value metrics across mid-sized charities. Donorbox anchors the small-shop segment with simplified embeddable donation forms that reduce technical onboarding friction. Funraise competes on event-based fundraising workflows that integrate auction management with mobile bidding.
Online donation software comprises cloud-native payment orchestration platforms purpose-built for tax-exempt entities, incorporating recurring billing engines, donor relationship databases, and automated gift acknowledgment systems compliant with IRS Publication 1771. The primary commercial purpose centers on reducing donor abandonment rates while ensuring charitable contribution documentation meets audit standards. Recurring donations generate the most predictable revenue streams for platform operators, while peer-to-peer fundraising exhibits the steepest user acquisition efficiency as individual donors become volunteer solicitors. Cloud-based deployment dominates new implementations though hybrid solutions retain footholds among institutions with legacy accounting system dependencies.
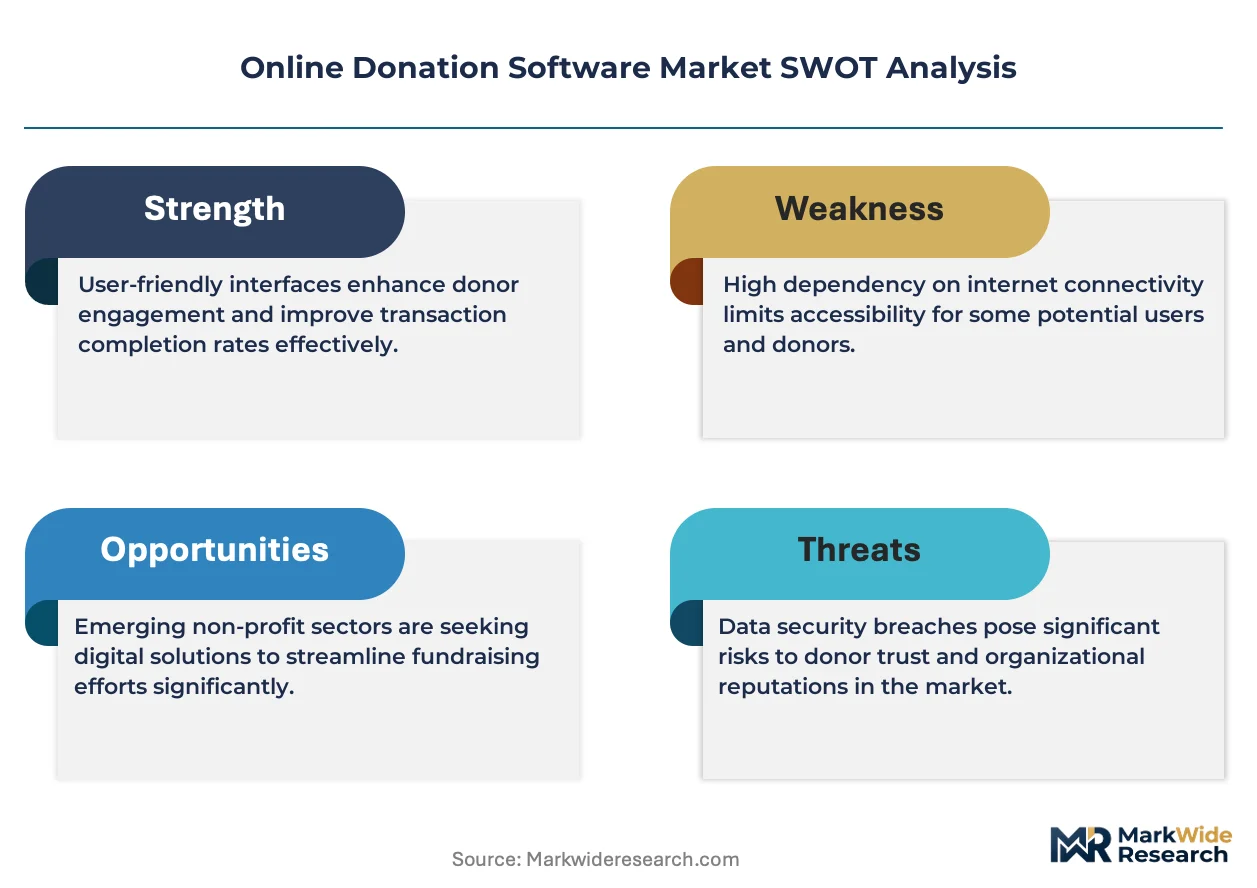
PCI DSS Level 1 certification shapes vendor viability by mandating encrypted cardholder data environments and annual third-party security audits. State charitable solicitation regulators in New York and California impose registration requirements that filter out non-compliant software providers. GDPR cross-border data transfer rules affect platforms serving European donors from US servers. Stakeholders must weigh payment method diversification against compliance fragmentation as digital wallets and ACH transfers gain share against card-dependent architectures.
Market Dynamics
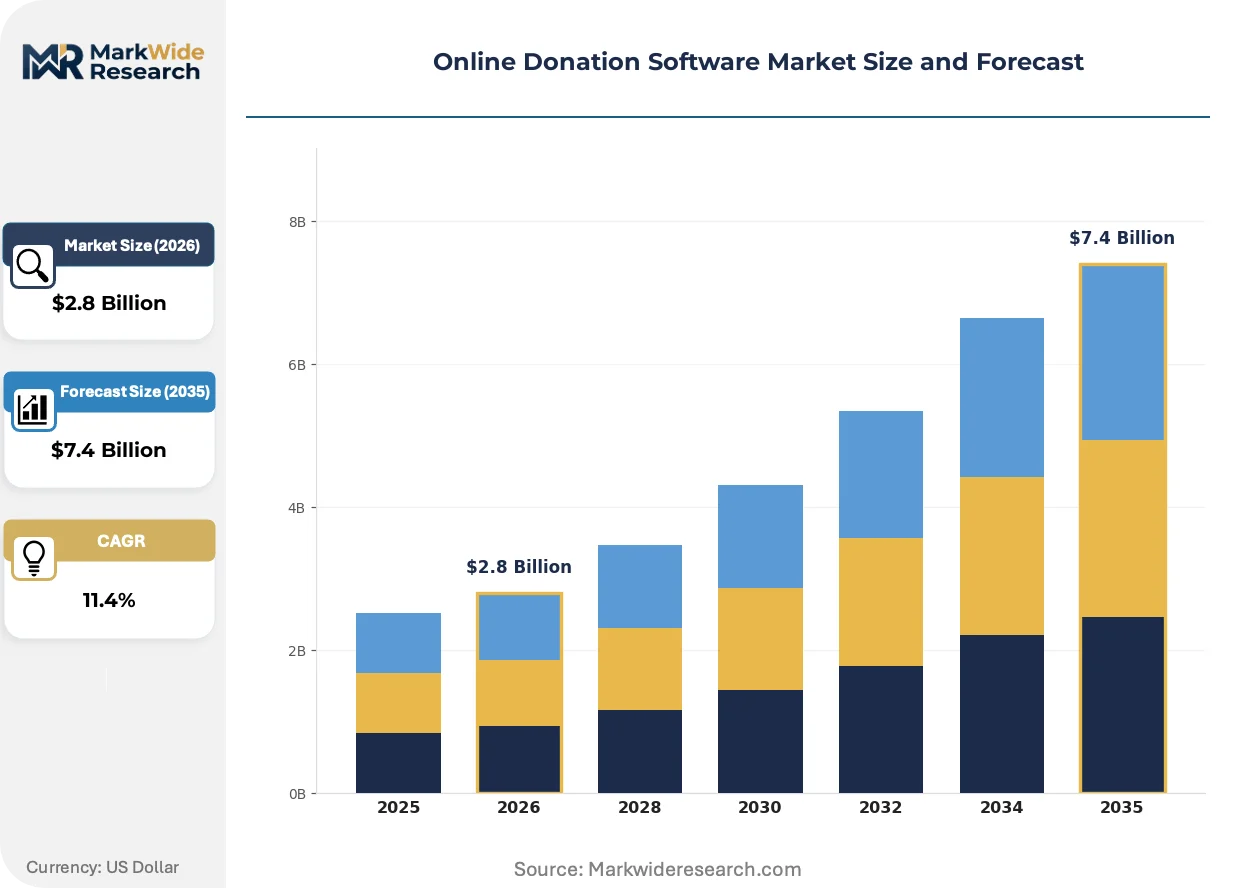
The transition from cash-based to digital-first giving is compressing vendor margins while expanding addressable donor pools. PCI DSS Level 1 certification requirements now function as a structural gatekeeper, filtering out undercapitalized entrants and consolidating procurement authority among compliant platforms.
Growth Catalysts
- UPI-enabled micro-donation rails:India's unified payments interface is electrifying giving behavior in tier-2 and tier-3 cities, reducing per-transaction costs below card-network thresholds.
- IRS Publication 1771 automation:Automated gift acknowledgment systems are eliminating manual compliance overhead for mid-sized charities, reducing audit preparation cycles.
- Faith-based digital tithing:Congregations are replacing physical collection plates with recurring billing engines, creating predictable revenue streams for platform operators.
Market Restraints
- State charitable solicitation fragmentation:New York and California impose non-uniform registration requirements that multiply compliance costs for multi-state nonprofits.
- Payment processor concentration:Legacy card-network dependencies in North America limit pricing negotiation leverage for emerging SaaS vendors.
- GDPR cross-border data friction:European donor data hosted on US servers triggers transfer mechanism complexity, delaying platform deployment timelines.
Strategic Opportunities
- ACH and digital wallet convergence:Platforms integrating automated clearing house rails with Apple Pay and Google Pay are capturing card-averse donor segments.
- Hybrid deployment for legacy accounting systems:Institutions with entrenched financial software represent underserved demand for API bridges rather than full cloud migration.
- Peer-to-peer fundraising automation:Individual donors acting as volunteer solicitors create viral acquisition loops with minimal platform marketing spend.
Industry Challenges
- Embedded form customization talent scarcity:Technical onboarding friction persists as small-shop charities lack in-house JavaScript expertise for white-label configurations.
- Annual third-party security audit timelines:PCI DSS recertification cycles compress product development roadmaps for resource-constrained vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Donation Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recurring Donations, One-Time Donations, Crowdfunding, Peer-to-Peer Fundraising Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Solutions End User: Nonprofits, Charitable Organizations, Educational Institutions, Religious Organizations Payment Method: Credit Card, Debit Card, ACH Transfer, Digital Wallets |
| Companies Covered | Zeffy, Bloomerang, Givebutter, Donately, GoFundMe Pro, Donorbox, Funraise, GiveSmart, GalaBid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Donation Software Market Strategic Shifts
Payment orchestration architectures are fragmenting as specialized nonprofit stacks decouple from general-purpose processors. Three distinct vectors are reshaping competitive positioning: embedded finance integration, compliance automation, and donor experience personalization.
Recurring billing engines with machine learning-based churn prediction are electrifying donor retention workflows. Mid-sized charities are adopting these tools fastest, replacing static monthly giving programs with dynamic amount-adjustment prompts. The technology is compressing donor lifetime value variance across customer cohorts.
GDPR Article 44 transfer impact assessments are forcing US-based platforms to localize European donor data. The regulation is mandating EU-region server deployments or standard contractual clause renegotiations. Faith-based organizations with international missionary networks are most affected, accelerating hybrid infrastructure investments.
Mobile-first giving behaviors are displacing desktop-centric donation flows among younger donor demographics. Text-to-give and QR-code activated forms are capturing event-based fundraising moments previously served by paper pledge cards. India and Brazil exhibit the steepest mobile share expansion, driven by super-app payment integration.
Online Donation Software Market Segmentation
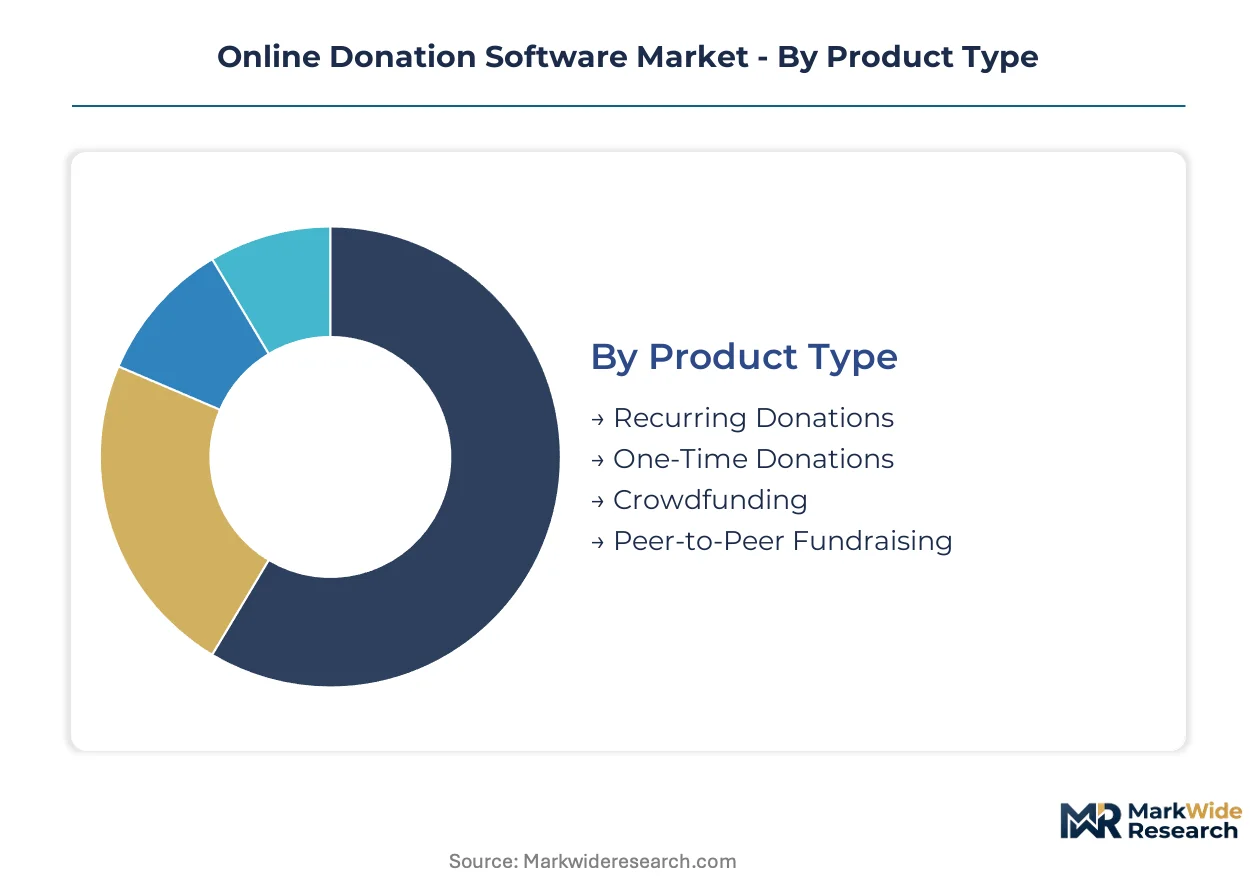
Segmentation in online donation software determines which compliance frameworks apply to each deployment. PCI DSS Level 1 certification requirements, state charitable solicitation registrations, and GDPR data localization rules create divergent cost structures across product architectures.
Product Type:
PCI DSS Level 1 certification burdens recurring donation platforms most heavily due to stored payment credential requirements, while one-time donation flows face lighter SAQ-A validation paths.
- Recurring Donations:Subscription billing engines with tokenized card-on-file storage dominate platform revenue predictability. Faith-based organizations in the United States drive concentrated demand as congregations abandon physical collection plates for automated tithing workflows.
- Peer-to-Peer Fundraising:Individual donors function as volunteer solicitors through personalized campaign pages, creating viral acquisition loops with minimal platform marketing expenditure. Mid-sized charities in India deploy these tools fastest as UPI-enabled micro-donation rails reduce per-transaction costs below card-network thresholds.
- One-Time Donations:Single-transaction flows with simplified checkout abandonment reduction.
- Crowdfunding:Project-specific fundraising with milestone-based fund release mechanisms.
Recurring Donations sits at the top of the volume ranking, with Peer-to-Peer Fundraising climbing the fastest.
Deployment:
Cost tier stratification separates cloud-native implementations from legacy-dependent hybrid architectures requiring API bridge investments.
- Cloud-Based:Multi-tenant SaaS architectures with automatic PCI DSS compliance updates and elastic infrastructure scaling. New nonprofit formations in Brazil and India select these deployments exclusively as mobile-first giving behaviors displace desktop-centric workflows.
- Hybrid Solutions:API-connected configurations bridging cloud donation front-ends with on-premise accounting system back-ends. Large educational institutions in the United States with entrenched financial software represent the primary demand concentration.
- On-Premise:Self-hosted installations with full data sovereignty for high-security requirements.
- Mobile Solutions:Native application or progressive web app delivery optimized for super-app payment integration.
Cloud-Based deployments hold the dominant revenue share, though Hybrid Solutions are expanding most quickly among established institutions.
End User:
Application-specific compliance requirements vary sharply across tax-exempt entity classifications.
- Religious Organizations:Congregation management systems with recurring tithing automation and missionary network donor databases. These entities face acute GDPR Article 44 pressure as international missionary activities trigger cross-border data transfer assessments.
- Nonprofits:General-purpose charitable entities requiring IRS Publication 1771 automated gift acknowledgment. State charitable solicitation registration fragmentation in New York and California multiplies compliance costs for multi-state operations.
- Charitable Organizations:Public charity structures with event-based fundraising and auction management needs.
- Educational Institutions:Alumni relations platforms with advancement office CRM integration and pledge tracking.
Nonprofits constitute the largest addressable base, while Religious Organizations are gaining share fastest through digital tithing conversion.
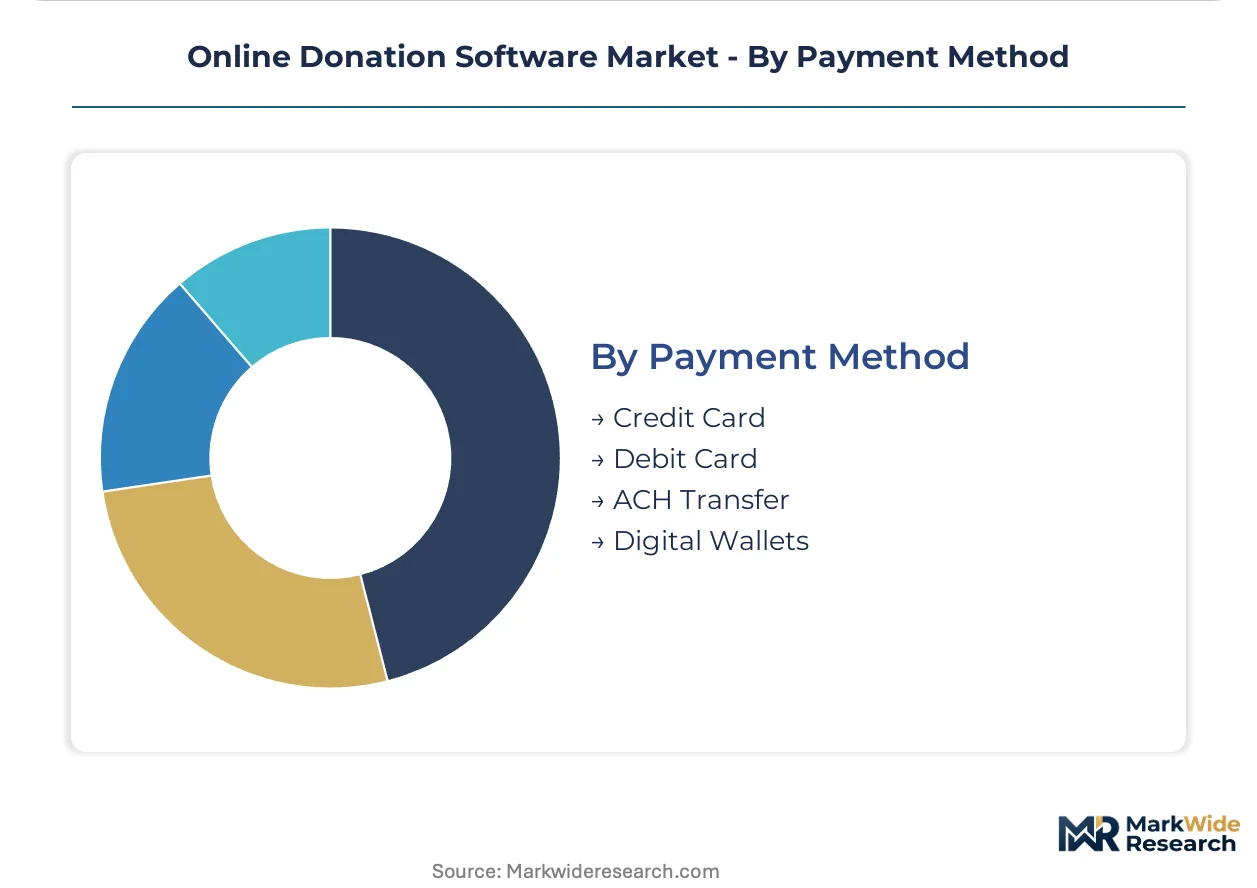
Payment Method:
Margin structure diverges significantly between card-network dependent methods and direct bank rails.
- ACH Transfer:Automated clearing house rails with sub-card interchange cost structures and bank account verification workflows. Card-averse donor segments in the United States migrate toward these methods as platforms integrate Plaid-style account authentication.
- Digital Wallets:Apple Pay, Google Pay, and super-app embedded payment flows with tokenized security and one-touch authentication. India exhibits the steepest adoption trajectory as UPI infrastructure enables wallet-agnostic micro-donation acceptance.
- Credit Card:Card-network processed transactions with PCI DSS scope implications.
- Debit Card:Bank-issued card products with lower interchange rates than credit instruments.
Credit Card processing retains the dominant transaction volume, though Digital Wallets are climbing the fastest among younger donor demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI-enabled micro-donation platforms scale faster than United States faith-based digital tithing workflows, though both markets compress per-transaction costs below legacy card-network thresholds.
United States
Congregations in Texas and Florida replace physical collection plates with automated recurring billing engines, driving platform revenue predictability. State charitable solicitation regulators in New York and California impose non-uniform registration requirements that multiply compliance costs for multi-state nonprofits. The Greater Boston corridor hosts established SaaS vendors bridging cloud donation front-ends with legacy accounting systems for educational institutions.
India
Tier-2 and tier-3 cities in Maharashtra and Karnataka electrify giving behavior through UPI infrastructure, reducing per-transaction costs below card-network thresholds. The Reserve Bank of India oversees payment system stability as super-app embedded finance penetrates donor wallets. Bangalore's technology cluster anchors domestic platform development for mobile-first donation workflows.
Brazil
Super-app payment integration captures event-based fundraising moments previously served by paper pledge cards among younger donor demographics. The country's national financial regulator monitors digital wallet proliferation as mobile share expands fastest across Latin America. São Paulo's fintech corridor concentrates platform localization efforts for Portuguese-language donor experiences.
Germany
GDPR Article 44 transfer impact assessments force US-based platforms to localize European donor data or renegotiate standard contractual clauses. Faith-based organizations with international missionary networks accelerate hybrid infrastructure investments to comply with cross-border data transfer rules. Berlin-Brandenburg hosts compliance-focused vendors serving GDPR-sensitive charitable entities.
United Kingdom
Alumni relations platforms with advancement office CRM integration drive demand among educational institutions with entrenched financial software dependencies. The Information Commissioner's Office enforces data protection standards for donor databases spanning international missionary networks. London's SaaS corridor anchors European headquarters for North American platform expansion.
Online Donation Software Market Competitive Environment
United States vendors anchor one tier; India-based specialists hold emerging-market adaptation capabilities. The vendor base stratifies across PCI DSS Level 1 certified incumbents, simplified onboarding specialists, and event-based workflow innovators. Three archetypes dominate: retention-algorithm platforms, embeddable-form providers, and mobile-bidding auction managers. Consolidation pressure intensifies through strategic partnerships between payment orchestrators and compliance automation vendors, while geographic expansion into UPI-enabled markets accelerates.
Within the retention-focused tier, Bloomerang exemplifies donor lifetime value optimization through machine learning-based churn prediction. Donorbox occupies a position among embeddable-form specialists reducing technical onboarding friction for small-shop charities. Funraise anchors the event-based workflow segment, representing integration between auction management and mobile bidding capabilities. These three vendors collectively illustrate competitive positioning across the platform maturity spectrum.
| Leading Market Players |
|---|
| Zeffy |
| Bloomerang |
| Givebutter |
| Donately |
| GoFundMe Pro |
| Donorbox |
| Funraise |
| GiveSmart |
| GalaBid |
| Others |
Value Chain & Pricing Dynamics
PCI DSS Level 1 certification requirements gate both qualified platform supply and premium-tier pricing access, as only capitalized vendors absorb annual third-party security audit costs while passing compliance premiums to mid-sized charities with multi-state operations.
Pricing Analysis
Capacity additions in India's UPI infrastructure are reshaping price floors for micro-donation processing below legacy card-network thresholds. The dominant pricing structure stratifies across PCI DSS certification tiers, with Level 1 platforms commanding premiums against SAQ-A validated alternatives. Price differentiation hinges on compliance grade and embedded finance integration depth. Cost compression in the small-shop segment intensifies as simplified embeddable forms reduce technical onboarding friction. Faith-based organizations with recurring tithing volumes exhibit lowest price sensitivity, while one-time crowdfunding campaigns face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from multi-state nonprofits mandate multi-supplier qualification across payment orchestration and compliance automation vendors. Platform development concentrates in the United States, India, and Brazil, with Bangalore's technology cluster feeding mobile-first donation workflows. The supply chain draws from cloud infrastructure providers, tokenized payment credential services, and donor database specialists. Single-source vulnerability persists in PCI DSS audit provider concentration. Distribution runs through direct SaaS sales channels and nonprofit technology consultants serving institutional advancement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as congregations abandon cash collection plates for automated recurring billing engines with churn prediction capabilities.
For Market Incumbents: Anchor retention-algorithm leadership by deepening machine learning investment for donor lifetime value optimization. Defend against UPI-enabled entrants by accelerating API bridge development for hybrid deployment demand among legacy-dependent educational institutions. Prioritize PCI DSS recertification automation to compress product roadmap disruption. For New Entrants and Emerging Players: Mobile-first embeddable forms offer the most penetrable white-space target for small-shop charities lacking JavaScript expertise. India's tier-2 and tier-3 cities present geographic expansion opportunity as UPI rails electrify giving behavior. Pursue super-app payment integration as the primary go-to-market angle for event-based fundraising workflows. For Investors and Strategic Acquirers: Roll-up economics work for compliance-automation specialists because state charitable solicitation fragmentation multiplies vendor procurement authority among certified platforms. Five-to-ten year viability favors platforms with embedded finance integration and GDPR-localized infrastructure. Monitor ACH-digital wallet convergence velocity as the critical signal for payment method diversification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PCI DSS Level 1 Recertification Automation | Annual third-party audit compression preserves product development velocity for resource-constrained vendors competing on compliance. |
| UPI Infrastructure Localization | Reserve Bank of India oversight enables sub-card-network transaction economics across Maharashtra and Karnataka tier-2 cities. |
| Hybrid Deployment API Bridge Development | Greater Boston corridor educational institutions with entrenched financial software generate recurring integration revenue. |
| GDPR Article 44 Transfer Impact Assessment | Faith-based missionary networks accelerate EU-region server investment to satisfy cross-border data localization mandates. |
| Peer-to-Peer Fundraising Viral Loop Engineering | Individual donor volunteer solicitation reduces platform marketing expenditure while capturing acquisition efficiency in Indian micro-donation markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nonprofit CTOs, advancement office CRM directors, faith-based congregation technology coordinators, and state charitable solicitation compliance officers with secondary validation from SEC SaaS vendor filings, IRS Publication 1771 documentation, and Reserve Bank of India payment system reports. Bottom-up platform deployment counts and top-down addressable nonprofit universe estimates were triangulated.
Segment-weighting approaches applied differential growth assumptions across recurring donation, peer-to-peer fundraising, and one-time donation product architectures throughout the projection horizon. Deployment models, end-user classifications, and payment method diversification patterns structured the analytical framework. CAGRs derived from elasticity-adjusted adoption curves incorporating UPI penetration rates and faith-based digital tithing conversion velocity.
The model assumes a particular technology adoption path; alternative pathways for ACH-digital wallet convergence would alter the outlook. Forecasts reflect assumptions regarding PCI DSS certification timeline compression and GDPR localization investment pacing. Deviation in state charitable solicitation regulatory harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Referral Marketing Software Market
Software & Services
Online Project Management Software Market
Software & Services
Device Tracking Software Market
Software & Services
Global Directory Software Market
Software & Services
Telecom IT Services Market
Software & Services
Marketing Automation Software Market
Software & Services
Design Engineering Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Call Center Software Market
Software & Services
Global Open Source Services Market
Software & Services
Global Quoting Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Global Survey Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Movie Editing Software Market
Software & Services
Aviation Software Market