
 Global Meeting Room Booking System Software Market | 2026-2036
Global Meeting Room Booking System Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Meeting Room Booking System Software Market Foresight
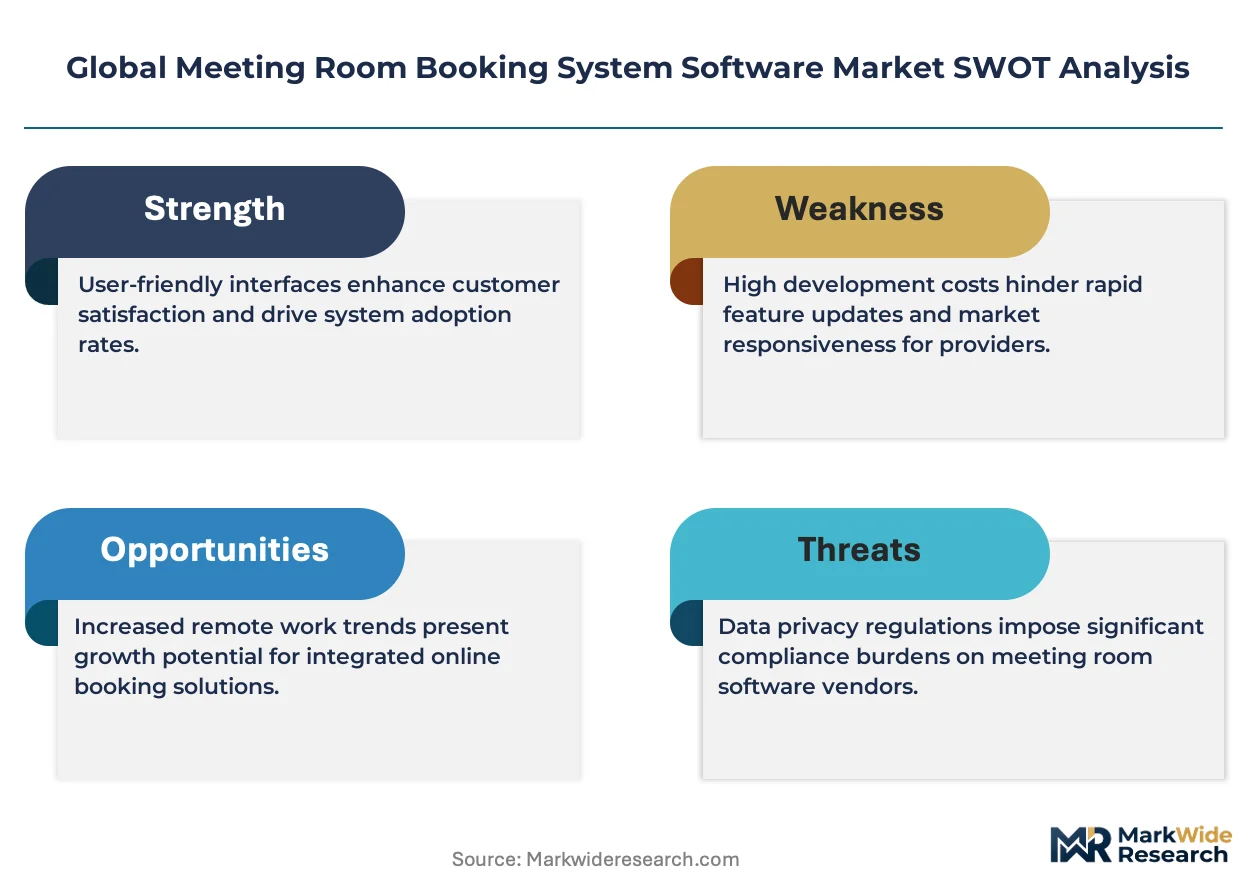
API-first architecture is realigning product economics as cloud-native integration layers replace legacy on-premises middleware. Robin leverages deep calendar-system connectivity to anchor enterprise accounts across North America. Envoy competes through visitor-management convergence with access control, while Skedda specializes in mid-market co-working deployments across the United Kingdom and Australia.
Meeting room booking system software comprises cloud-based, on-premises, hybrid, and hosted platforms that synchronize real-time availability data across calendar servers, IoT occupancy sensors, and digital signage endpoints to automate workspace reservation and utilization analytics. The primary commercial purpose centers on eliminating scheduling conflicts, reducing real estate overhead, and generating occupancy intelligence for facilities teams. Cloud-based deployment leads in new contract value as enterprises abandon server maintenance, while room scheduling and desk booking solutions capture the fastest expansion as hybrid work policies normalize shared-desk models across corporate offices and co-working spaces.
The EU AI Act and GDPR shape algorithmic transparency requirements for automated room allocation systems processing employee location data, while the U.S. FCC and state-level biometric privacy laws in Illinois and Texas constrain facial-recognition check-in features. Japan's METI workplace digitization guidelines and ISO 55000 asset management standards further elevate software procurement criteria for multinational facilities teams. Stakeholders must monitor whether emerging building-energy disclosure mandates in California and the EU Green Deal transform utilization analytics from operational convenience into regulatory compliance infrastructure.
Market Dynamics
API-first architecture is consolidating vendor economics as cloud-native integration layers displace legacy on-premises middleware across enterprise facilities stacks. This structural shift compresses implementation timelines while elevating interoperability requirements for procurement teams.
Growth Catalysts
- EU AI Act compliance mandates:Automated room allocation systems processing employee location data now require algorithmic transparency documentation. Facilities teams in Germany and France are upgrading legacy platforms to satisfy these requirements.
- Hybrid work policy institutionalization:Corporate real estate teams in the United States and Japan are deploying shared-desk reservation infrastructure to support rotational office attendance models.
- IoT sensor convergence:Occupancy detection hardware from Nordic semiconductor vendors is integrating directly with calendar servers, eliminating manual check-in friction and generating real-time utilization telemetry.
Market Restraints
- Biometric privacy law fragmentation:Illinois BIPA and Texas biometric statutes constrain facial-recognition check-in feature deployment, forcing vendors to maintain parallel authentication stacks.
- Cloud data residency requirements:German works councils and Japanese METI guidelines mandate local server presence, inflating operational complexity for SaaS providers.
- Legacy calendar system entrenchment:Microsoft Exchange and Google Workspace dominance creates switching friction for enterprises with decade-old directory configurations.
Strategic Opportunities
- Underpenetrated Australian co-working segment:Mid-market flexible office operators in Sydney and Melbourne lack purpose-built reservation platforms, presenting white-space for specialized vendors.
- EU Green Deal building-energy disclosure:Utilization analytics are transitioning from operational convenience to compliance infrastructure as France and the Netherlands implement mandatory consumption reporting.
- Digital signage convergence:Room display hardware from Samsung and LG is merging with booking software, creating bundled procurement opportunities for facilities departments.
Industry Challenges
- Multi-protocol integration complexity:Facilities teams struggle to synchronize Zigbee, LoRaWAN, and Wi-Fi occupancy sensors with heterogeneous calendar backends.
- ISO 55000 asset management certification timelines:Multinational corporations require 18-24 month compliance windows for procurement approval, elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Meeting Room Booking System Software Market |
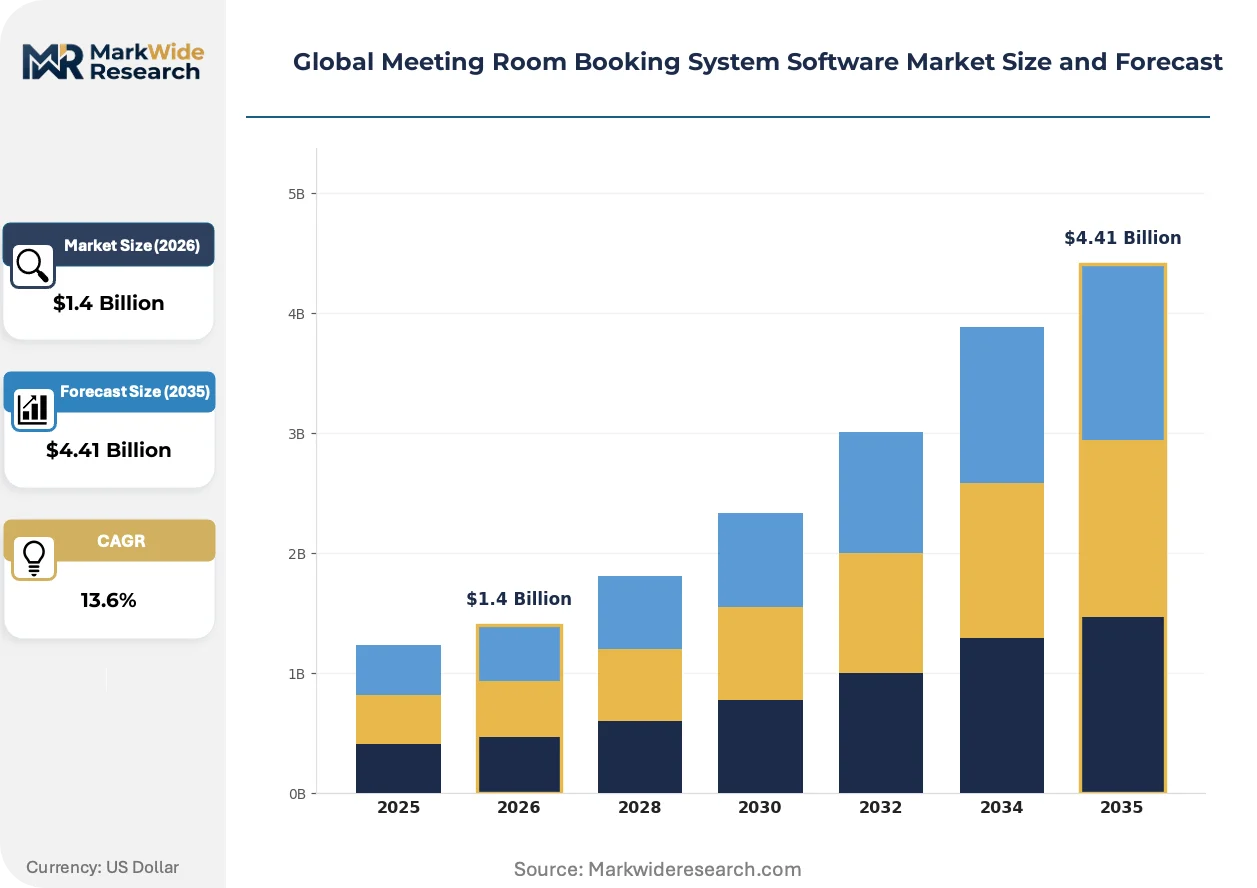
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Desk Booking, Room Scheduling, Visitor Management, Resource Allocation, Event Management Application: Corporate Offices, Co-Working Spaces, Educational Institutions, Government Agencies, Financial Services End User: Small Enterprises, Medium Enterprises, Large Corporations, Non-Profit Organizations, Startups |
| Companies Covered | Robin, Roomzilla, Anolla, Envoy, Tidaro, Joan, Skedda, Archie, DeskFlex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Meeting Room Booking System Software Market Shifts & Advancements
Edge computing architectures are redistributing data processing from centralized cloud instances to on-premise gateways, reshaping latency requirements and vendor deployment models across the facilities technology stack.
Computer vision occupancy verification is expanding into high-security corporate campuses and government facilities where badge-swipe data alone proves insufficient for audit trails. Financial services firms in London and Singapore are piloting these systems to satisfy internal risk committees. The technology is compressing the addressable market for standalone infrared beam counters while elevating hardware cost floors.
The EU AI Act's algorithmic transparency requirements are forcing vendors to document automated room allocation logic for employee location data processing. German works councils are now demanding explainability dashboards before contract approval. Cloud-native platforms with built-in audit trails are capturing procurement preference over legacy systems lacking compliance instrumentation.
Enterprise buying committees are consolidating software procurement under centralized IT governance rather than facilities-led point solutions. Real estate teams in the United States and United Kingdom are losing autonomy as CIOs mandate unified SaaS contracts. This behavioral shift favors vendors with enterprise-grade security certifications and native Microsoft 365 integration over specialized point solutions.
Global Meeting Room Booking System Software Market Segmentation
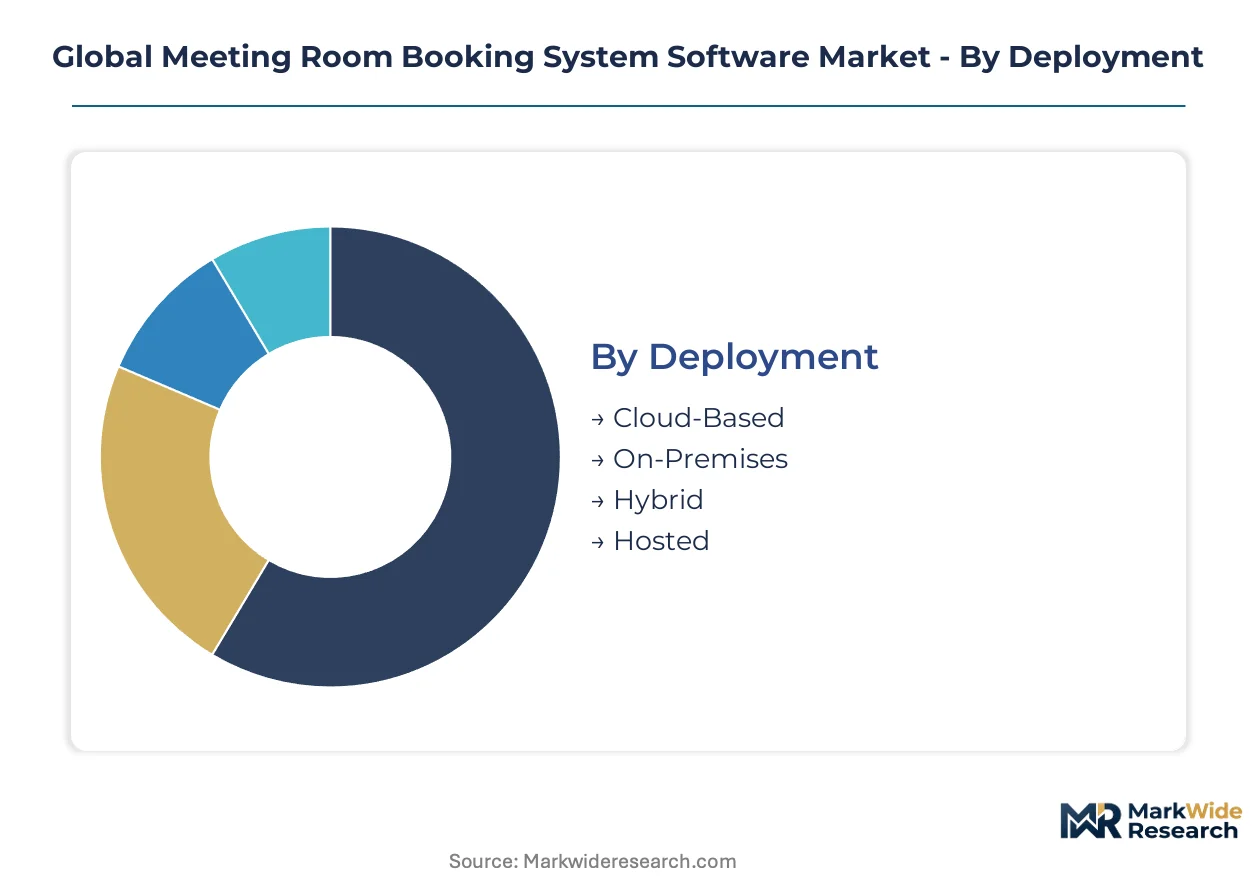
Segmentation reveals how procurement priorities diverge across deployment models, solution architectures, and organizational scale. Facilities teams select platforms based on data residency constraints, integration complexity, and real estate portfolio structure rather than feature checklists alone.
Deployment:
Upgrade cycles accelerate where legacy server infrastructure nears end-of-life, pushing facilities teams toward consumption-based alternatives that eliminate capital expenditure approval chains.
- Cloud-Based:Multi-tenant architectures synchronize calendar servers with IoT occupancy sensors through REST APIs, eliminating on-site maintenance overhead. Demand concentrates in United States and German corporate offices where IT governance mandates centralized SaaS procurement under CIO authority rather than facilities-led point solutions.
- On-Premises:Single-tenant installations persist in Japanese financial services and German manufacturing where METI guidelines and works council agreements mandate local data sovereignty. These deployments require dedicated infrastructure teams and elongate implementation timelines.
- Hybrid:Edge-gateway architectures process occupancy verification locally while pushing analytics to cloud instances, satisfying split compliance requirements.
- Hosted:Managed private cloud deployments offer dedicated server instances without capital ownership, appealing to mid-market Australian co-working operators.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Solution Type:
Application depth determines pricing tiers, with bundled platforms commanding premium contracts over standalone modules.
- Desk Booking:Hot-desking algorithms allocate shared workstations based on team proximity preferences and amenity requirements. United States technology firms and United Kingdom professional services deploy these systems to support three-day rotational office policies.
- Room Scheduling:Calendar-integrated reservation interfaces with digital signage endpoints remain the foundational use case across all geographies.
- Visitor Management:Pre-registration workflows with access control integration address security-audit requirements in Singapore financial services and London corporate headquarters.
- Resource Allocation:Equipment and catering procurement modules extend booking systems into facilities operations management.
- Event Management:Multi-room coordination for all-hands meetings and external conferences targets large campus environments.
Desk Booking captures the steepest expansion trajectory as hybrid work policies institutionalize shared-space models.
Application:
End-use environment shapes sensor density requirements and authentication protocols.
- Corporate Offices:Enterprise campuses in the United States and Germany deploy floor-wide sensor grids with Microsoft 365 directory integration.
- Co-Working Spaces:Flexible office operators in Sydney and Melbourne require white-label booking interfaces with member-billing integration.
- Educational Institutions:University IT departments prioritize free scheduling for academic use with fee-based external event management.
- Government Agencies:Federal facilities in the United States and prefectural offices in Japan mandate FedRAMP or equivalent security certifications.
- Financial Services:Trading floors and back-office locations in London and Singapore pilot computer vision occupancy verification for audit compliance.
Corporate Offices dominate current installations; Financial Services shows the fastest uptake of advanced verification features.
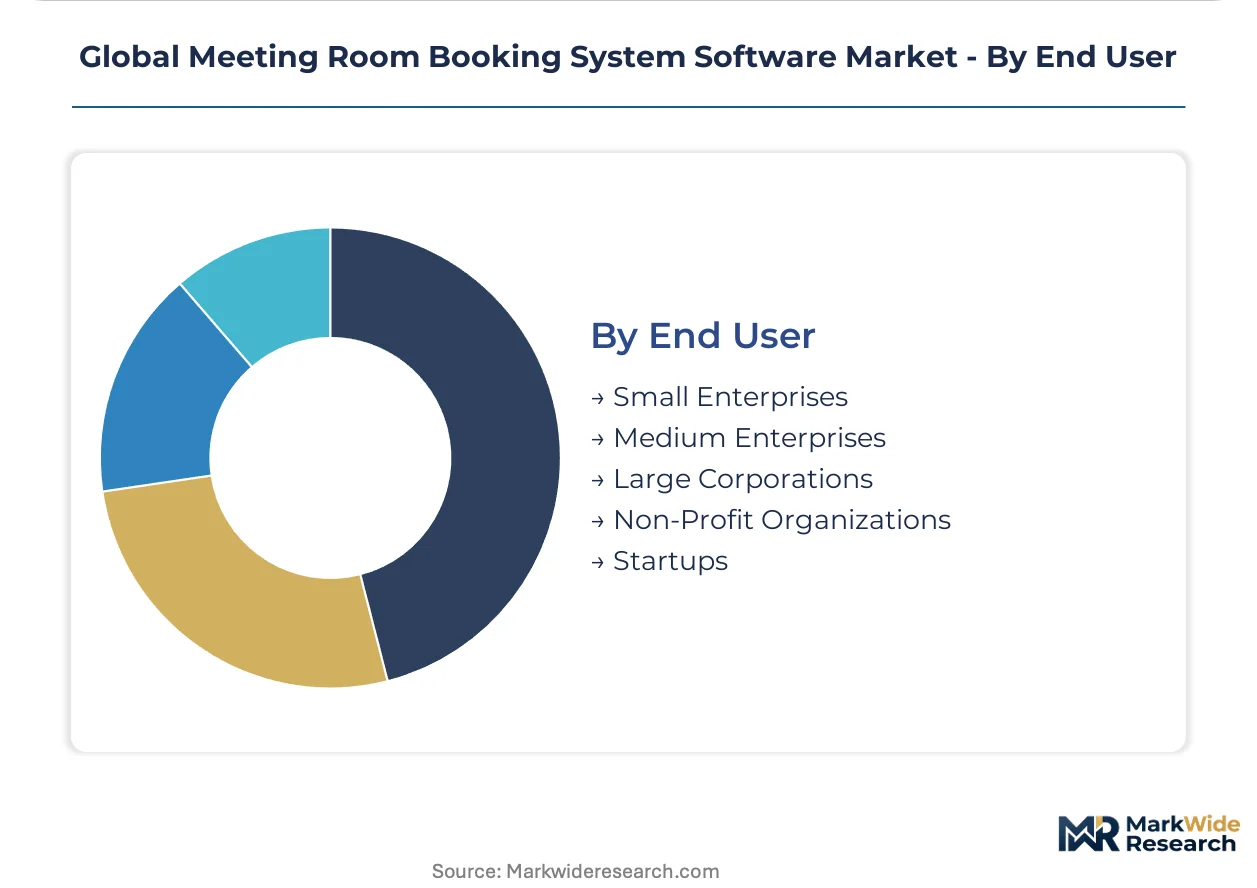
End User:
Organizational scale determines procurement autonomy and integration complexity tolerance.
- Small Enterprises:Sub-100 employee organizations adopt browser-based solutions without dedicated facilities staff.
- Medium Enterprises:Regional headquarters with 500-2,000 employees drive mid-market growth through standardized platform rollouts.
- Large Corporations:Multinational facilities teams require ISO 55000 asset management certification and 18-24 month procurement cycles.
- Non-Profit Organizations:Budget-constrained operators prioritize donated or subsidized software licenses.
- Startups:Venture-backed firms in technology clusters select platforms based on API extensibility rather than feature breadth.
Large Corporations anchor contract value; Startups expand most quickly as venture funding flows into workplace technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in corporate offices across the United States, Germany, and Japan as hybrid work policies institutionalize room reservation infrastructure. Cloud-based platforms capture dominant contract value in North American and European markets, while data residency requirements sustain on-premises installations in select Asian jurisdictions.
United States
Technology firms and financial services operators in New York and San Francisco drive cloud-native platform procurement. FCC guidelines and state-level biometric privacy laws in Illinois and Texas constrain facial-recognition check-in feature deployment. Corporate campuses in Silicon Valley and Manhattan are consolidating software procurement under centralized IT governance mandates.
Germany
Manufacturing headquarters and automotive R&D centers in Munich and Stuttgart require algorithmic transparency documentation for automated room allocation. Works council agreements and GDPR frameworks mandate local data sovereignty, sustaining hybrid deployment architectures. The EU AI Act accelerates compliance-driven upgrades across industrial facilities in Bavaria and North Rhine-Westphalia.
Japan
METI workplace digitization guidelines shape procurement criteria for financial services and electronics manufacturers. Trading floors in Tokyo and Osaka pilot computer vision occupancy verification for audit compliance. Prefectural offices mandate FedRAMP-equivalent security certifications, elongating vendor approval timelines.
United Kingdom
Professional services firms in London deploy desk booking algorithms to support three-day rotational office policies. CSRD disclosure requirements and ISO 55000 asset management standards elevate software procurement criteria for multinational facilities teams. Flexible office operators in the City and Canary Wharf seek white-label booking interfaces with member-billing integration.
Australia
Mid-market co-working operators in Sydney and Melbourne lack purpose-built reservation platforms, presenting white-space for specialized vendors. TGA-equivalent data governance expectations and building-energy disclosure mandates in New South Wales transform utilization analytics into compliance infrastructure. Tech clusters in Melbourne's Docklands and Sydney's Barangaroo drive API-first platform adoption.
Global Meeting Room Booking System Software Market Competitive Landscape
API-first architecture consolidation dominates the current landscape as cloud-native integration layers displace legacy on-premises middleware. The vendor base organizes around three strategic archetypes: enterprise-grade platforms with deep calendar-system connectivity, mid-market specialists emphasizing visitor-management convergence, and regional co-working focused operators with white-label capabilities. M&A activity and strategic partnerships represent the primary competitive vectors as facilities departments consolidate procurement under CIO authority.
Within the enterprise-grade tier, Robin and Envoy exemplify contrasting positioning strategies—Robin anchors North American accounts through Microsoft 365 directory integration, while Envoy converges visitor management with access control for security-audit environments. Skedda occupies a specialized position among mid-market flexible office operators across the United Kingdom and Australia, where white-label interfaces and member-billing integration distinguish procurement decisions.
| Leading Market Players |
|---|
| Robin |
| Roomzilla |
| Anolla |
| Envoy |
| Tidaro |
| Joan |
| Skedda |
| Archie |
| DeskFlex |
| Others |
Supply & Pricing Matrix
Large corporate procurement committees concentrated in United States technology campuses and German automotive headquarters command volume-based SaaS contracts that compress per-seat pricing while elevating integration requirements. This buyer concentration forces vendors to absorb upfront implementation costs in exchange for multi-year subscription commitments.
Pricing Analysis
Volume commitments from enterprise facilities teams dominate contract economics while margin capture concentrates in premium tiers with ISO 55000 certification and FedRAMP-equivalent security attestations. Price differentiation rests on API extensibility and native Microsoft 365 directory integration versus limited connector libraries. Pricing pressure stems from CIO-led procurement consolidation that treats room booking as commoditized infrastructure rather than strategic investment. Mid-market co-working operators in Australia and the United Kingdom exhibit highest price sensitivity, while financial services firms in London and Singapore accept premium tiers for audit-trail compliance.
Supply Chain Analysis
Regional distribution centers for IoT occupancy sensors cluster in Taiwan for Nordic semiconductor components, South Korea for display hardware, and China for edge-computing gateways. Software development draws from engineering talent pools in the United States, Germany, and India, with cloud infrastructure tethered to AWS, Azure, and Google Cloud regions. Single-source vulnerability concentrates in Nordic Semiconductor for ultra-low-power radio chipsets. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meeting room booking system software is becoming a vertical-integration race as vendors capture sensor hardware margins and edge-computing infrastructure to escape pure-SaaS commoditization.
For Market Incumbents: Deploy API-first platform consolidation to absorb adjacent workspace management categories before point solutions establish beachheads. Incumbents must deepen calendar-system connectivity against emerging entrants offering free-forever tiers with limited Exchange and Google Workspace integration. Backward integration into IoT sensor manufacturing protects margin compression from Nordic Semiconductor supply constraints. For New Entrants and Emerging Players: Capture white-space in Australian mid-market co-working through white-label booking interfaces with native member-billing integration. Sydney and Melbourne operators lack purpose-built platforms and prioritize brand customization over enterprise security certifications. A channel partnership strategy with flexible office real estate developers accelerates footprint without direct enterprise sales overhead. For Investors and Strategic Acquirers: The window for entry favors platforms with built-in EU AI Act compliance instrumentation and explainable allocation algorithms. Long-term viability requires defensible data moats from utilization analytics rather than transactional booking volume. Watch for German works council contract approvals as the inflection signal for enterprise procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Microsoft 365 connectivity anchors enterprise renewal rates against point-solution displacement. |
| Acquisition of Specialist Firm | Computer vision occupancy verification targets financial services audit requirements in London and Singapore. |
| Geographic Expansion | Australian co-working white-label penetration captures underserved mid-market demand in Sydney and Melbourne. |
| Strategic Partnership | Samsung and LG display hardware bundling creates procurement consolidation opportunities for facilities departments. |
| Product Launch | Edge-gateway hybrid architectures satisfy German works council data residency mandates without full on-premise burden. |
Research Methodology
Document review covered SEC filings from cloud infrastructure providers, EU regulatory guidance on algorithmic transparency, and ISO 55000 asset management standards, complemented by interviews with facilities directors, IT procurement officers, and integration specialists at enterprise campuses and co-working operators. Secondary sources included hyperscaler partnership announcements, METI workplace digitization guidelines, and building-energy disclosure mandates from California and the EU Green Deal. Bottom-up deployment estimates triangulated against top-down SaaS spending projections across corporate real estate categories.
Cross-referencing historical implementation timelines with panel input from vendor sales cycles established the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, end-use environment, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating hybrid work policy institutionalization rates and IoT sensor price decline trajectories. Industry-specific inputs captured works council negotiation timelines and FedRAMP-equivalent certification approval windows.
The model holds under stable hybrid work policy continuity and sustained cloud infrastructure investment; deviation in biometric privacy law fragmentation or EU AI Act enforcement intensity would shift enterprise procurement timelines. Forecasts reflect documented assumptions about CIO governance consolidation and calendar-system integration friction. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Gym Management Software Market
Software & Services
Driver Updater Software Market
Software & Services
ITSM Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Mind Mapping Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Optical Design Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
PCB Layout Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Automotive Hypervisor Market
Software & Services
Jobsite Management Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Software Repository Market
Software & Services
Optical Coatings Design Software Market