
 Paraphrasing Tools Market | 2026-2036
Paraphrasing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Paraphrasing Tools Market Intelligence
Platform licensing revenue is reconfiguring competitive economics in the paraphrasing tools space, pulling margin pools away from standalone consumer subscriptions toward API-accessible enterprise deployments. Grammarly sustains brand dominance through browser-native distribution and workplace productivity integrations. QuillBot leverages freemium-to-paid conversion mechanics that anchor its position among student demographics. Jasper AI differentiates through vertical specialization in marketing copy workflows, commanding higher per-seat pricing than generalist alternatives.
Paraphrasing tools are software applications that apply natural language processing algorithms—specifically transformer-based neural networks with attention mechanisms—to restructure source text while preserving semantic meaning, operating across latency thresholds measured in milliseconds per sentence. Their primary commercial purpose centers on enabling scalable content variation for digital publishing, academic integrity compliance, and multilingual localization pipelines. AI-based technology segments now capture the fastest expansion as large language model inference costs decline and output quality thresholds rise. Subscription pricing models retain the dominant share of recurring revenue, though freemium tiers serve as critical user acquisition funnels that feed enterprise conversion cycles. Cloud-based delivery architectures increasingly displace on-premise rule-based installations, particularly among mid-market professional services firms.
The European Union's GDPR and the EU AI Act impose transparency and data governance requirements on automated text generation systems, compelling vendors to document training data provenance and offer human oversight mechanisms. The United States lacks unified federal AI regulation, though the FTC applies existing consumer protection statutes to deceptive automation claims and the SEC scrutinizes AI-generated financial communications. Stakeholders must monitor evolving jurisdictional fragmentation in algorithmic accountability standards, as compliance architecture choices made today will determine market access breadth across the next regulatory cycle.
Market Dynamics
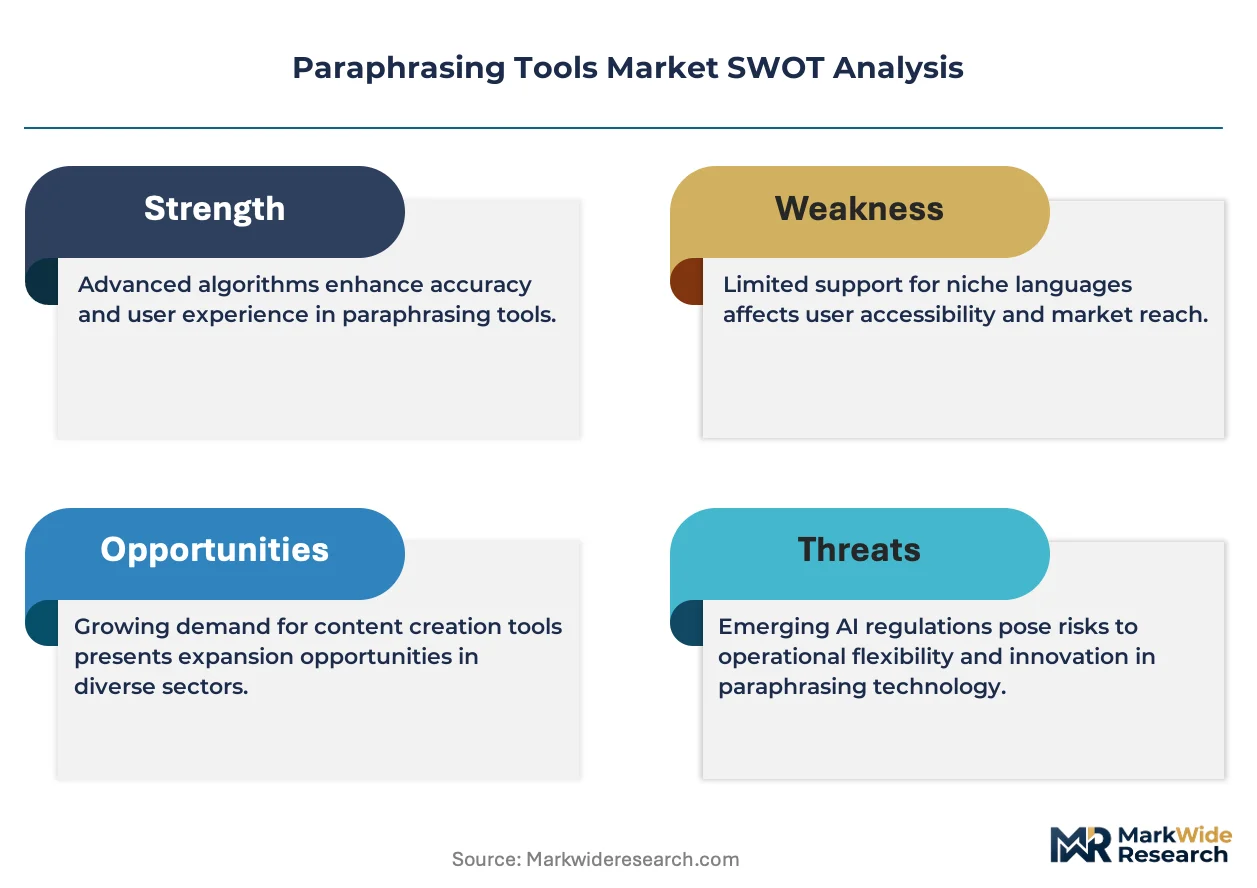
Transformer architecture improvements and declining LLM inference costs are compressing quality-latency tradeoffs, forcing vendors to restructure pricing tiers around API throughput rather than seat-based subscriptions.
Growth Catalysts
- GDPR Article 22 mandates:EU enterprises deploying automated text generation must implement human oversight mechanisms, creating procurement pull for paraphrasing tools with audit trails and explainability features.
- Academic integrity compliance:North American universities now embed paraphrasing software directly into Learning Management Systems, institutionalizing recurring subscription revenue at scale.
- Multilingual localization pipelines:Transformer-based neural networks with attention mechanisms enable real-time content variation across 50+ languages, opening enterprise translation workflows previously served by human agencies.
Market Restraints
- Compute cost volatility:GPU cluster pricing fluctuations directly squeeze margins for cloud-native vendors operating on thin freemium-to-paid conversion economics.
- Training data provenance risk:The EU AI Act requires documented consent chains for text corpora used in model training, exposing vendors to retroactive compliance liabilities.
- Human editor substitution ceiling:Enterprise buyers in legal and medical verticals maintain hard requirements for professional linguist sign-off, capping automation penetration.
Strategic Opportunities
- India's PLI scheme for AI:Domestic cloud infrastructure subsidies enable localized inference deployment, reducing latency for South Asian language pairs and bypassing data residency restrictions.
- Marketing copy workflow convergence:Paraphrasing APIs are integrating with creative asset management platforms, capturing budget previously allocated to separate copywriting SaaS tools.
- CE marking pathway for AI systems:Early compliance with emerging EU conformity assessment frameworks creates preferential procurement status for enterprise RFPs.
Industry Challenges
- NLP engineer scarcity:Vendors compete for talent capable of fine-tuning transformer architectures on domain-specific corpora, inflating compensation costs.
- Legacy plagiarism detection integration:Turnitin and similar incumbents resist API interoperability, forcing paraphrasing vendors to build costly custom connectors for institutional clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraphrasing Tools Market |
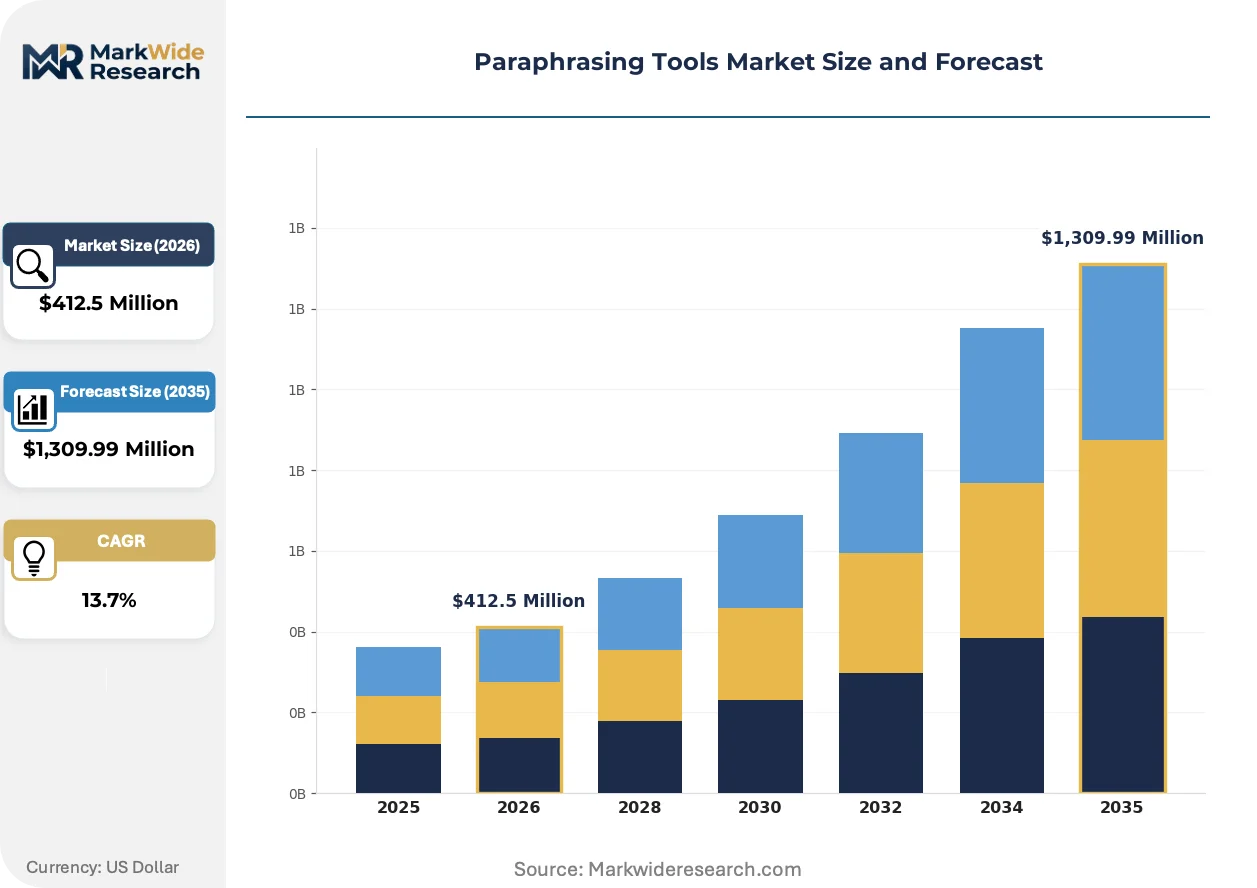
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
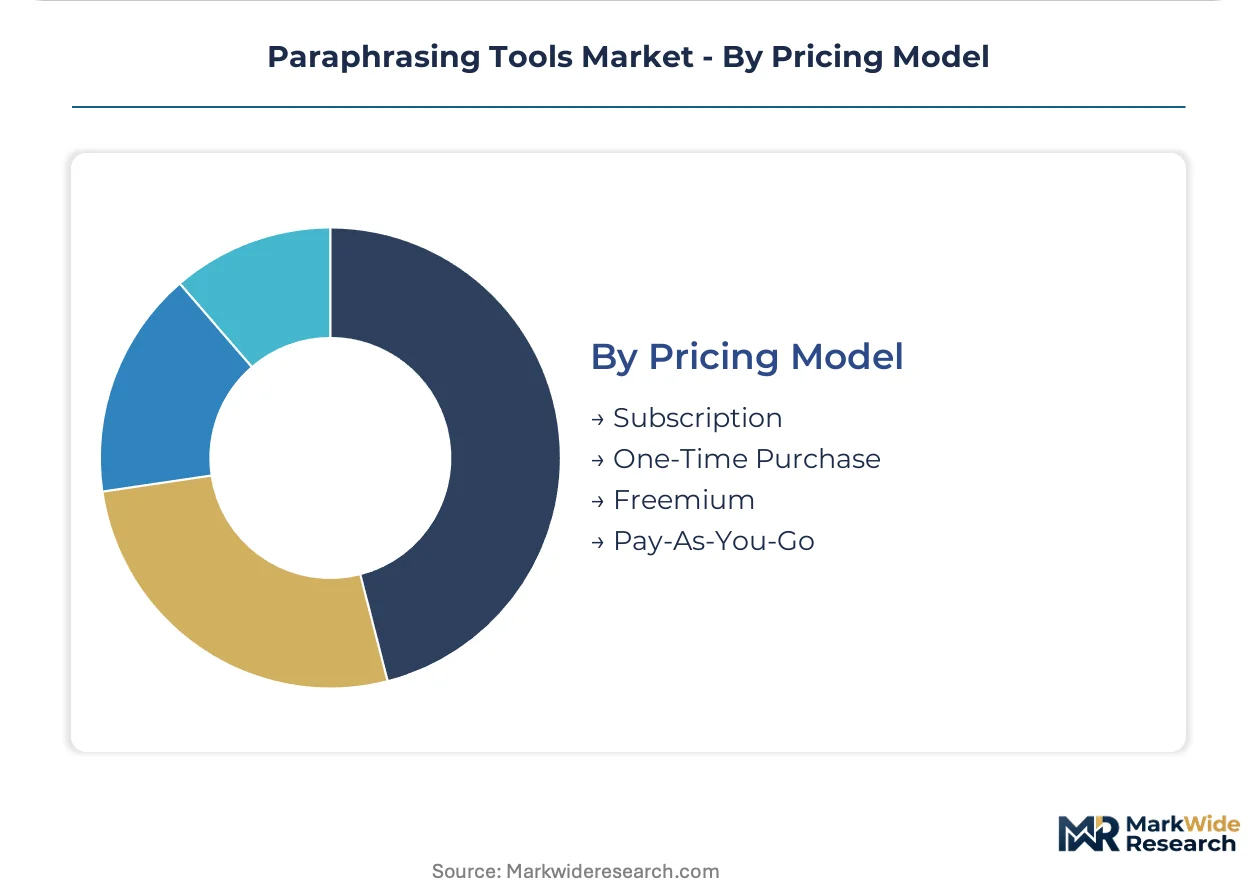
| Segmentation | Product Type: Online Tools, Software Applications, Plugins, Mobile Apps User Type: Students, Professionals, Content Creators, Educators Technology: AI-Based, Rule-Based, Hybrid, Cloud-Based Pricing Model: Subscription, One-Time Purchase, Freemium, Pay-As-You-Go |
| Companies Covered | Jasper AI, Semrush, QuillBot, HumanizeAI, Copy AI, Grammarly, Writesonic, Ahrefs, Wordtune, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraphrasing Tools Market Strategic Shifts & Innovations
Product roadmaps increasingly prioritize real-time collaborative editing environments over standalone document processing, embedding paraphrasing into synchronous content workflows rather than asynchronous batch operations.
Retrieval-augmented generation is hybridizing with pure transformer inference, enabling paraphrasing tools to ground outputs in client-specific document repositories rather than generic training corpora. Enterprise legal departments are piloting these systems for contract variation tasks, compressing turnaround times from days to minutes. This architecture shift is forcing vendors to reengineer infrastructure around vector database latency rather than model parameter scale.
The EU AI Act's transparency obligations are compelling vendors to deploy watermarking and provenance tracking layers on all generated text. German publishers and French media conglomerates now require cryptographic signatures embedded in machine-paraphrased content, creating compliance differentiation between vendors with and without native provenance stacks. Implementation timelines vary, with Q2 2025 emerging as the operational deadline for most continental European deployments.
University procurement offices are consolidating vendor relationships under single-platform agreements, displacing the previous pattern of departmental software autonomy. Campus-wide licensing deals with centralized IT procurement are capturing volume discounts that individual colleges cannot match. This concentration is most visible in the United States, where state university systems are standardizing on common paraphrasing tool stacks to simplify compliance auditing and reduce administrative overhead.
Paraphrasing Tools Market Segmentation
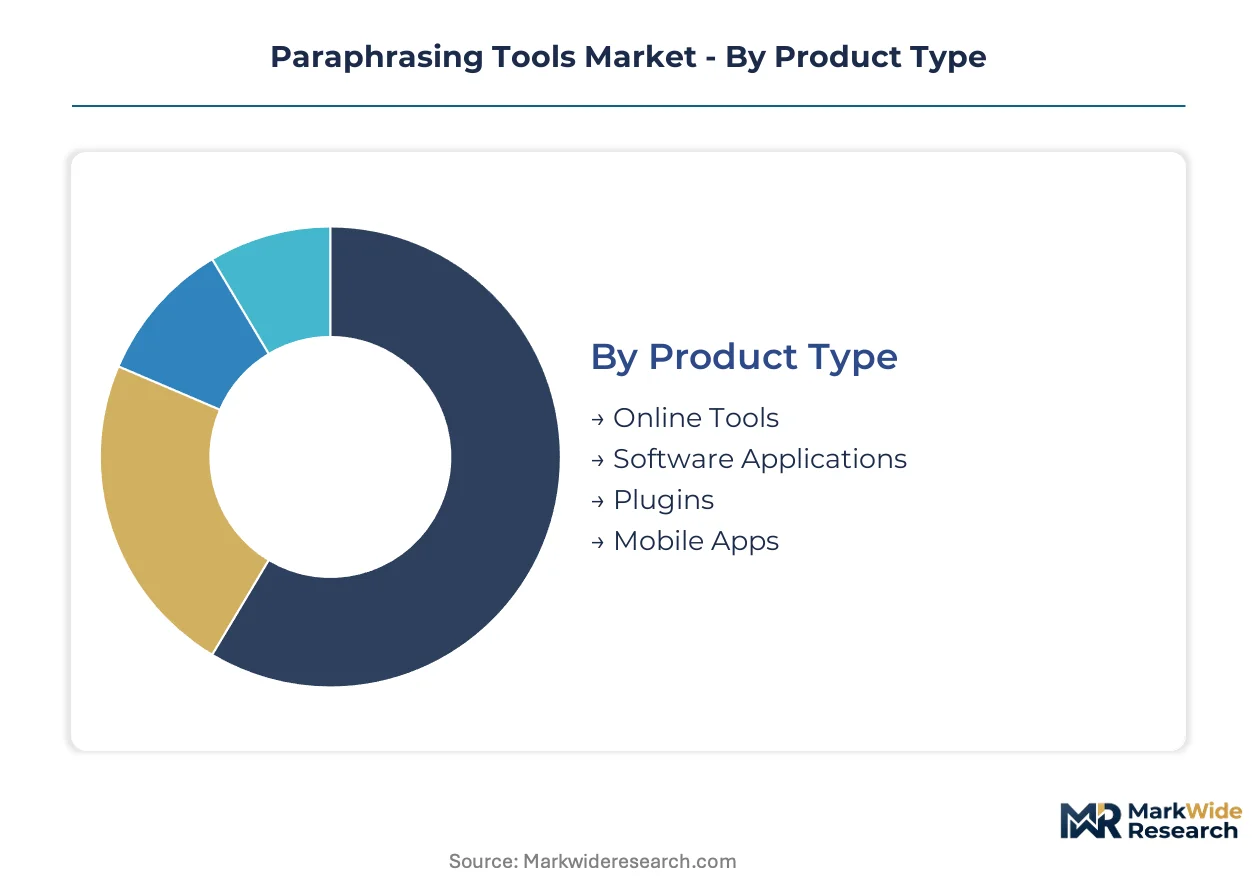
Segmentation in the paraphrasing tools market reveals how vendor architectures align with distinct procurement budgets and workflow integration requirements. Each dimension—product format, user profile, underlying technology, and commercial terms—creates separate competitive battlegrounds with divergent margin structures and customer lifetime values.
Product Type:
Product format determines distribution economics and user acquisition costs, with browser-native delivery commanding lower friction than installable software.
- Online Tools:Web-based interfaces process text through remote API calls, eliminating local compute requirements. North American university procurement offices favor these for LMS embedding, driven by zero-install deployment and centralized license management.
- Software Applications:Desktop installations offer offline processing and local data retention. Enterprise legal departments in Germany specify these for GDPR-sensitive document workflows, prioritizing air-gapped operation over cloud convenience.
- Plugins:Browser extensions and word processor add-ins embed paraphrasing directly into content creation surfaces. These capture professional writer workflows through minimal context-switching friction.
- Mobile Apps:Smartphone-native applications target on-the-go content revision. South Asian markets show concentration here, with India's PLI-subsidized cloud infrastructure enabling low-latency inference for regional language pairs.
Online tools hold installed capacity. Mobile apps are rotating up the share rankings.
User Type:
Customer profile segmentation maps directly to pricing elasticity and feature depth requirements, with institutional buyers exhibiting fundamentally different procurement patterns than individual subscribers.
- Students:Price-sensitive users with high volume needs and low willingness to pay. Freemium tiers with daily word limits dominate acquisition, with conversion concentrated in final-year thesis preparation periods.
- Professionals:Corporate writers and knowledge workers requiring brand voice consistency. Marketing agencies in the United States drive premium subscription uptake, prioritizing API access for bulk content variation.
- Content Creators:Independent publishers and social media operators needing rapid output scaling. These users exhibit the highest churn rates but also the strongest viral referral potential.
- Educators:Academic staff integrating paraphrasing into curriculum design and plagiarism instruction. Campus-wide licensing deals in California and Texas state university systems anchor recurring revenue for this segment.
Students dominate user counts. Professionals are climbing the fastest in revenue contribution.
Technology:
Underlying architecture choices determine inference quality, latency profiles, and compliance posture, with transformer-based systems displacing legacy rule engines across most commercial contexts.
- AI-Based:Transformer neural networks with attention mechanisms generate semantically coherent rephrasings. These systems capture the steepest expansion trajectory as LLM inference costs decline and output quality thresholds rise.
- Rule-Based:Template substitution and syntactic transformation engines without machine learning. Financial services compliance teams in Switzerland retain these for fully auditable, deterministic output.
- Hybrid:Combined statistical and neural approaches balancing quality with computational efficiency. Mid-market professional services firms in the United Kingdom deploy these for cost-controlled enterprise scaling.
- Cloud-Based:Remote inference architectures eliminating local hardware requirements. These dominate new vendor entrants, leveraging AWS and Azure GPU clusters for elastic capacity.
AI-Based systems hold installed capacity. Cloud-Based deployment is rotating up the share rankings.
Pricing Model:
Commercial structure shapes customer acquisition economics and lifetime value profiles, with recurring revenue models commanding premium valuations from investors.
- Subscription:Monthly or annual recurring payments for unlimited or tiered usage. This structure retains dominant share of vendor revenue, though annual contracts show higher retention than monthly.
- One-Time Purchase:Perpetual licenses with optional maintenance fees. Rule-based software vendors in Japan favor this model for conservative enterprise procurement practices.
- Freemium:Basic functionality at no cost with premium feature gates. Student demographic acquisition depends entirely on this funnel, with sub-five-percent conversion rates typical.
- Pay-As-You-Go:Per-word or per-request metering without fixed commitments. API-first vendors targeting developer integrations and automated content pipelines deploy this structure.
Subscription holds installed capacity. Pay-As-You-Go is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraphrasing tool consumption patterns diverge sharply by geography: United States enterprise buyers prioritize API throughput for content operations, while European procurement emphasizes GDPR-compliant audit trails, and South Asian markets favor mobile-first deployment for regional language processing.
United States
Enterprise content operations and university procurement budgets sustain premium subscription tiers. The FTC applies consumer protection statutes to deceptive automation claims, while the SEC scrutinizes AI-generated financial communications. California and Texas state university systems anchor campus-wide licensing concentration.
Germany
Enterprise legal departments specify air-gapped desktop installations for GDPR-sensitive document workflows. The EU AI Act imposes transparency obligations requiring documented training data provenance. Berlin-Brandenburg clusters host compliance-focused vendor development for cryptographic signature embedding.
United Kingdom
Mid-market professional services firms deploy hybrid architectures for cost-controlled enterprise scaling. The Information Commissioner's Office enforces GDPR Article 22 mandates for human oversight mechanisms. London's financial services corridor drives procurement for contract variation automation.
India
Domestic cloud infrastructure subsidies under the PLI scheme enable localized inference deployment for South Asian language pairs. The Ministry of Electronics and Information Technology oversees data residency compliance frameworks. Bengaluru and Hyderabad clusters concentrate mobile-native application development for on-the-go content revision.
Japan
Conservative enterprise procurement practices favor perpetual license models for rule-based software vendors. METI coordinates national AI strategy alignment with industrial standardization. Tokyo's publishing conglomerates pilot watermarking and provenance tracking layers for machine-paraphrased content.
Paraphrasing Tools Market Key Industry Players
Capability concentration sits with specialized AI-native vendors; scale advantage sits with browser-distributed productivity platforms. The market exhibits tiered structure with three distinct strategic archetypes: horizontal productivity suites, vertical marketing copy specialists, and API-first infrastructure providers. Dominant competitive moves include workplace productivity integrations and freemium-to-paid conversion mechanics.
Within the horizontal productivity tier, Grammarly and QuillBot exemplify distribution-first positioning through browser-native embedding and freemium user acquisition funnels. Jasper AI occupies a specialist position in vertical marketing copy workflows. These three anchors demonstrate how brand recognition, demographic targeting, and workflow integration respectively command differentiated pricing power across student, professional, and enterprise segments.
| Leading Market Players |
|---|
| Jasper AI |
| Semrush |
| QuillBot |
| HumanizeAI |
| Copy AI |
| Grammarly |
| Writesonic |
| Ahrefs |
| Wordtune |
| Others |
Cost & Logistics Intelligence
Bengaluru's GPU cluster concentration anchors inference cost structures for API-first vendors, translating cloud infrastructure density into pricing power over student and enterprise segments. North American university procurement offices leverage this capacity concentration to negotiate volume discounts on subscription tiers, while European buyers absorb compliance premiums for GDPR-auditable deployments.
Pricing Analysis
Long-term campus-wide licensing agreements dominate institutional procurement, with annual contracts commanding higher retention than monthly SaaS tiers. Price differentiation rests on API throughput thresholds and explainability feature depth, with GDPR-compliant audit trails extracting premiums from German legal departments. Cost compression in freemium tiers intensifies as GPU pricing volatility squeezes vendor margins. Students exhibit highest price sensitivity, while marketing agencies in the United States show lowest elasticity for vertical-specialized tools.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for on-premise hardware vendors serving air-gapped installations. Taiwan, South Korea, and the United States concentrate advanced GPU manufacturing for cloud inference clusters. Raw material dependencies center on NVIDIA H100 accelerators, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability in transformer architecture licensing from OpenAI and Anthropic creates procurement concentration. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transformer fine-tuning talent gap constrains vendor roadmaps, with NLP engineers capable of domain-specific corpus optimization commanding compensation premiums that reshape hiring economics.
For Market Incumbents: Entrench browser-native distribution through deeper LMS embedding partnerships, neutralizing emerging API-first challengers. Pursue backward integration into vector database infrastructure to reduce latency dependencies on Pinecone and Weaviate. The EU AI Act's training data provenance mandates threaten margin structures for vendors lacking documented consent chains. For New Entrants and Emerging Players: Mid-market professional services firms in the United Kingdom represent the most penetrable entry point, underserved by Grammarly's consumer tilt and Jasper's marketing vertical lock. India's PLI-subsidized cloud infrastructure enables localized inference deployment for South Asian language pairs with minimal capital intensity. Developer-first API documentation and usage-based metering accelerate technical buyer acquisition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid architecture vendors bridging rule-based determinism with neural quality, capturing financial services compliance budgets. Long-term viability hinges on provenance stack ownership as EU watermarking mandates harden. Acquisition target archetype: specialized legal or medical vertical tools with institutional customer concentration. The signal to watch is campus-wide licensing consolidation velocity in United States state university systems.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedding paraphrasing into creative asset management platforms captures copywriting SaaS budgets. |
| CE Marking Pathway for AI Systems | Early EU conformity assessment compliance creates preferential procurement status in German RFPs. |
| Backward Integration into Vector Databases | Controlling retrieval-augmented generation latency differentiates enterprise legal contract variation offerings. |
| Strategic Partnership with LMS Providers | Canvas and Blackboard embedding institutionalizes recurring revenue in California university systems. |
| Geographic Expansion via PLI Subsidies | India's domestic cloud infrastructure subsidies enable low-latency inference for Hindi-Tamil language pairs. |
Research Approach
A standing panel of NLP engineering leads, university procurement officers, enterprise legal department heads, and cloud infrastructure architects provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings from Grammarly and Jasper AI, hyperscaler capex disclosures from AWS and Azure, and EU regulatory documentation from the AI Act drafting process. Bottom-up vendor revenue triangulation against top-down education technology spending estimates anchored market size construction.
Scenario-bracketing around GPU pricing volatility and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, user type, pricing model, and regional compliance cluster. CAGRs derived from fitted growth curves against historical SaaS adoption patterns in adjacent text automation markets. Transformer inference cost decline curves and academic integrity policy diffusion rates served as key forecast inputs.
Practitioners should monitor EU AI Act enforcement intensity and NVIDIA supply allocation shifts for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
HPC Software Market
Software & Services
Online Project Management Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Global ITSM Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
North America Equity Management Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Tag Management Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Data Visualization Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Advanced Process Control Software Market