
 Global Paper Towels Market | 2026-2036
Global Paper Towels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Towels Market Foresight
E-commerce platforms for janitorial supplies is tilting toward subscription and bulk-order models as facility managers seek predictable replenishment. Procter & Gamble leverages its North American retail network to sustain shelf dominance in supermarkets and wholesale clubs. Kimberly-Clark anchors the healthcare sanitation channel with specialized dispensing systems. Georgia-Pacific competes aggressively on manufacturing scale across the commercial facilities segment.
Paper towels are absorbent disposable sheets manufactured from wood pulp or recycled fiber, typically ranging from single-ply to quilted multi-ply constructions, designed for wiping, drying, and surface sanitation in residential and professional settings. Double-ply and quilted variants command margin pools in premium household cleaning and hospitality services where perceived softness and absorbency drive replacement cycles. Recycled fiber grades face structural constraints in food preparation centers due to FDA and EU food-contact compliance thresholds, while embossed textures lead in janitorial services where bulk throughput and dispenser compatibility outweigh unit softness.
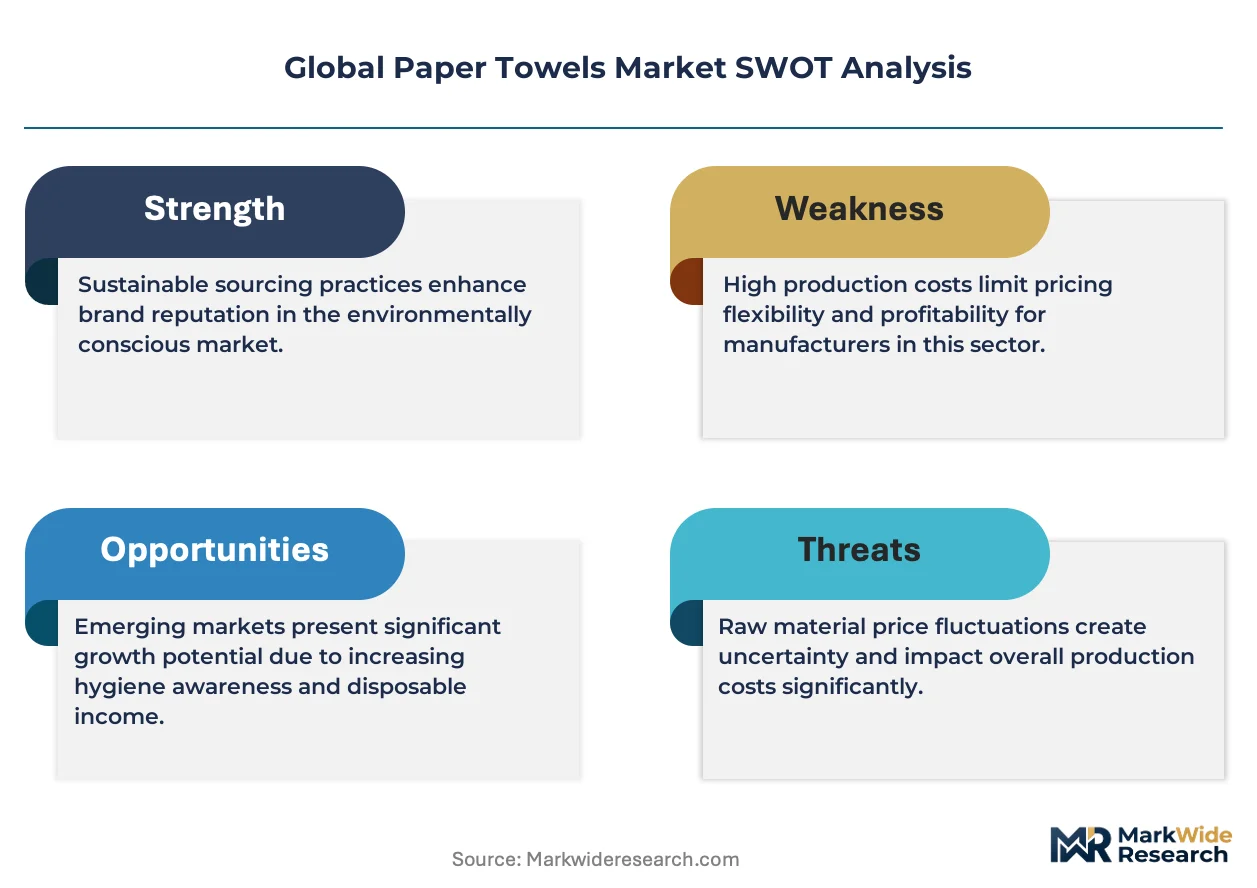
The EPA's Safer Choice program and the EU Ecolabel framework shape fiber sourcing requirements and bleaching chemistry across North American and European supply chains. China's GB standards and MEE environmental compliance rules are tightening wastewater discharge thresholds for pulp mills serving domestic paper towel production. ISO 14001 certification pressure is spreading through private-label contracts from corporate offices and educational institutions. Stakeholders must monitor how diverging regional sustainability mandates reshape cross-border sourcing economics and private-label qualification timelines.
Market Dynamics
Commercial hygiene infrastructure upgrades across airports, hospitals, and foodservice facilities are compressing replacement cycles and forcing dispenser compatibility standardization across bulk procurement contracts.
Growth Catalysts
- EU Green Deal fiber mandates:Bleaching chemistry restrictions and recycled content thresholds are accelerating capital upgrades at European mills, creating first-mover certification advantages for compliant suppliers.
- Quick-service restaurant expansion:Chain operators in the United States and China are standardizing touchless dispensing systems, locking in multi-year towel supply agreements with embedded volume commitments.
- Healthcare sanitation protocols:Post-pandemic infection control standards at German and Japanese hospitals are specifying embossed, high-throughput grades for clinical environments.
Market Restraints
- Pulp input cost volatility:Northern bleached softwood kraft prices swing with energy and freight costs, squeezing margin pools for non-integrated converters.
- Recycled fiber compliance barriers:FDA food-contact thresholds and EU Ecolabel purity standards structurally exclude post-consumer grades from commercial kitchen applications.
- Plastic hand dryer substitution:Energy-efficient blade dryers in European airports and corporate campuses capture share in washroom specification decisions.
Strategic Opportunities
- Subscription janitorial platforms:E-commerce replenishment models for facility managers in the United States bypass traditional distribution markups and capture lifetime value data.
- India sanitation infrastructure:Government cleanliness campaigns and airport modernization are creating first-time demand for commercial-grade dispensing systems.
- ISO 14001 certification bundling:Corporate office and university private-label contracts increasingly require environmental management system documentation as a qualifying gate.
Industry Challenges
- Cross-border compliance synchronization:Diverging EPA Safer Choice, EU Ecolabel, and China GB standards force parallel product line maintenance and extended qualification timelines.
- Dispenser interoperability fragmentation:Proprietary roll core dimensions and sensor calibrations across major system manufacturers complicate second-source qualification for facility managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Towels Market |
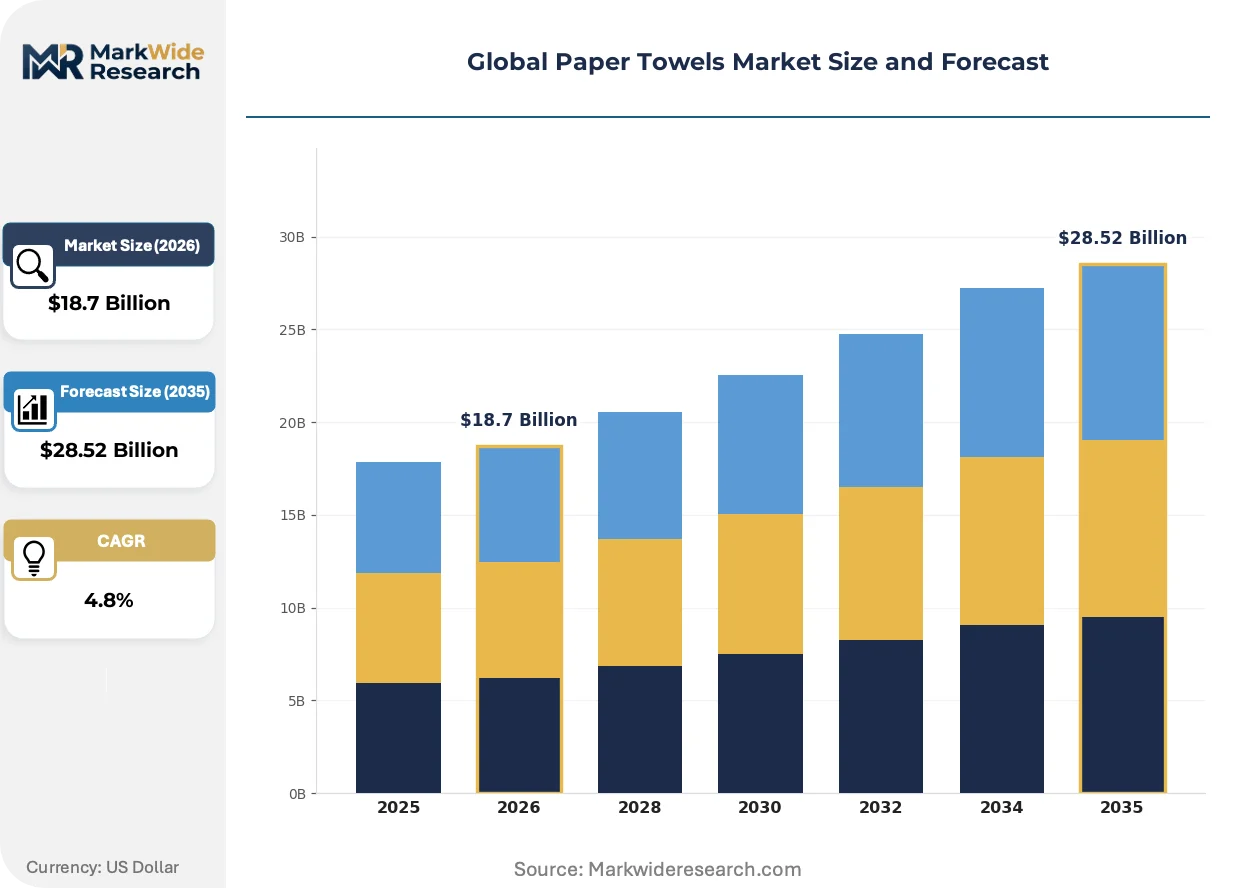
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Ply, Double-Ply, Quilted, Recycled Fiber, Embossed Application: Household Cleaning, Commercial Facilities, Food Service, Healthcare Sanitation, Hospitality Services Distribution Channel: Supermarkets, E-Commerce Platforms, Wholesale Clubs, Convenience Stores, Office Suppliers End User: Residential Consumers, Janitorial Services, Corporate Offices, Educational Institutions, Food Preparation Centers |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Georgia-Pacific, Essity, Kruger, Cascades, WEPA Hygieneprodukte, Metsä Tissue, Solaris Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Towels Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to redefine absorbency performance benchmarks and sourcing transparency requirements across consumer and commercial segments.
Bamboo-pulp fiber blends are penetrating premium household and hospitality segments with lower water-intensity cultivation profiles and softer hand-feel characteristics. Boutique hotel chains and eco-certified restaurants in Germany and California are specifying these grades for guest-facing applications. The technology is hybridizing virgin and alternative fiber supply chains, forcing traditional wood-pulp suppliers to develop parallel certification tracks or cede margin-rich positioning.
China's MEE wastewater discharge rules are tightening COD and AOX thresholds for pulp mills serving domestic paper towel production, accelerating closed-loop bleaching investments. Mills in Shandong and Guangdong provinces face retrofit deadlines that favor capital-rich integrated producers. Export-oriented manufacturers are diverting compliant output toward private-label contracts for Japanese and Australian buyers seeking supply chain documentation.
Facility managers at US airports and hospital systems are consolidating SKU portfolios around standardized roll formats to reduce inventory complexity and dispenser maintenance costs. Distributor sales representatives are repositioning around technical specification support rather than price negotiation. This consolidation is most visible in Texas and Florida healthcare networks where procurement centralization has compressed supplier rosters from eight to three approved vendors per category.
Global Paper Towels Market Segmentation
Paper towel segmentation reflects divergent performance requirements across hygiene-sensitive environments. Product construction, application setting, and procurement channel each reshape margin structures and supplier qualification barriers.
Product Type:
Use-case spectrum spans from economy bulk throughput to premium tactile experience in guest-facing environments.
- Single-Ply:Thin, lightweight sheets engineered for high-volume dispensers in transit hubs and stadium concourses. Airport authorities in the United States and Germany specify these grades for passenger throughput optimization where unit cost dominates softness metrics.
- Double-Ply:Laminated two-layer construction delivering elevated absorbency for household kitchens and mid-tier hospitality. Quick-service restaurants in China standardize this grade for dine-in areas where hand-drying satisfaction influences repeat visitation.
- Quilted:Embossed air-pocket patterns targeting premium residential and boutique hotel segments. California eco-lodges specify these for guest bathroom amenities.
- Recycled Fiber:Post-consumer pulp blends constrained by FDA food-contact thresholds in commercial kitchens. German municipal procurement favors these for office building washrooms.
- Embossed:Textured surfaces engineered for clinical throughput in hospital sanitation protocols. Japanese healthcare networks specify high-emboss grades for infection control compliance.
The dominant share belongs to Double-Ply, while Recycled Fiber is closing the gap fastest as EU Ecolabel procurement mandates expand.
Application:
Cost tier stratification separates commodity replenishment from specification-driven contract supply.
- Household Cleaning:Consumer-packaged goods sold through retail shelf space competition. Procter & Gamble's North American supermarket network sustains placement dominance.
- Commercial Facilities:Bulk dispensing systems for airports, corporate campuses, and logistics centers. Texas healthcare networks consolidated supplier rosters from eight to three approved vendors.
- Food Service:FDA and EU food-contact compliance requirements exclude recycled grades from kitchen deployment. Chain operators lock in multi-year supply agreements with embedded volume commitments.
- Healthcare Sanitation:Post-pandemic infection control standards specify embossed, high-throughput grades. German and Japanese hospitals drive clinical-grade procurement.
- Hospitality Services:Guest-facing amenities where perceived softness influences brand positioning. Boutique hotel chains in Germany specify bamboo-pulp blends.
Commercial Facilities command the largest procurement volumes, though Healthcare Sanitation shows the steepest expansion trajectory as clinical protocols tighten.
Distribution Channel:
Customer type determines whether procurement emphasizes price negotiation or technical specification support.
- Supermarkets:Mass-market retail shelf competition with brand recognition driving placement. Kimberly-Clark and Georgia-Pacific contest dominant positioning.
- E-Commerce Platforms:Subscription and bulk-order models bypass traditional distribution markups. Facility managers in the United States capture lifetime value data through predictable replenishment.
- Wholesale Clubs:Volume-tiered pricing for residential stock-up and small commercial accounts. Procter & Gamble leverages scale economics here.
- Convenience Stores:Emergency replenishment with limited SKU breadth. Single-ply and travel-format dominance.
- Office Suppliers:Corporate procurement contracts bundling janitorial supplies with environmental certification requirements. ISO 14001 documentation increasingly gates qualification.
E-Commerce Platforms are gaining share fastest as procurement centralization shifts toward data-driven replenishment, while Supermarkets retain the dominant position in consumer volumes.
End User:
Volume concentration varies dramatically between fragmented residential demand and consolidated institutional procurement.
- Residential Consumers:Brand-loyal households purchasing through retail and e-commerce channels. Softness and price-per-roll drive switching behavior.
- Janitorial Services:Contract cleaners standardizing roll formats to reduce inventory complexity. Distributor sales representatives reposition around technical support.
- Corporate Offices:Centralized procurement with sustainability documentation requirements. EU Green Deal fiber mandates accelerate compliant supplier selection.
- Educational Institutions:University private-label contracts requiring environmental management system certification. ISO 14001 pressure spreads through campus sustainability offices.
- Food Preparation Centers:Commercial kitchens with strict FDA purity thresholds excluding recycled fiber grades. Quick-service restaurant expansion locks in compliant supply.
Janitorial Services represent the largest addressable base by facility count, yet Corporate Offices are expanding contract value fastest as sustainability procurement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where bulk procurement consolidation squeezes converter margins, while German buyers leverage EU Green Deal mandates to extract sustainability premiums from certified suppliers.
United States
Texas and Florida healthcare networks drive procurement centralization, compressing supplier rosters from eight to three approved vendors per category. FDA food-contact regulations lock recycled fiber grades out of commercial kitchen specifications. Atlanta-based Georgia-Pacific anchors manufacturing scale across the Southeast commercial facilities corridor.
Germany
Boutique hotel chains in Bavaria specify bamboo-pulp blends for guest-facing amenities, extracting softness premiums from alternative fiber suppliers. EU Ecolabel bleaching chemistry restrictions accelerate capital upgrades at North Rhine-Westphalia mills. Essity's Tork brand dominates healthcare sanitation contracts through specialized dispensing system integration.
China
Quick-service restaurant chains in Shanghai and Beijing standardize touchless dispensing systems with embedded multi-year volume commitments. MEE wastewater discharge rules tighten COD thresholds for Shandong and Guangdong pulp mills. Export-oriented manufacturers divert compliant output toward private-label contracts for Japanese buyers demanding supply chain documentation.
Japan
Post-pandemic infection control standards at Tokyo and Osaka hospital networks specify embossed, high-throughput grades for clinical environments. METI procurement guidelines favor domestic suppliers with ISO 14001 environmental management certification. Kansai-region distributors consolidate technical specification support roles as SKU portfolios narrow.
India
Government cleanliness campaigns and Mumbai-Delhi airport modernization create first-time demand for commercial-grade dispensing systems. BIS fiber purity standards lag EU thresholds, allowing faster qualification timelines for virgin pulp imports. Maharashtra-based janitorial service contractors standardize roll formats to reduce inventory complexity across fragmented facility bases.
Global Paper Towels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying fiber and converting capacity. The vendor base stratifies across three tiers: multinational hygiene platforms with dispenser ecosystem lock-in, regional converters competing on mill-scale economics, and private-label specialists bundling ISO 14001 certification for corporate procurement. Dominant competitive moves include backward integration into pulp supply and strategic partnerships with sensor-enabled dispenser manufacturers.
Among North American hygiene platforms, Procter & Gamble and Kimberly-Clark exemplify divergent archetypes: the former leverages retail network density for household shelf dominance, while the latter anchors healthcare and commercial sanitation channels through technical specification depth. Georgia-Pacific occupies a position at the scale-driven end, competing aggressively on manufacturing throughput across bulk commercial contracts. European specialists including Essity and Metsä Tissue represent the sustainability-certification tier, extracting margin premiums from EU Ecolabel-compliant supply chains.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Georgia-Pacific |
| Essity |
| Kruger |
| Cascades |
| WEPA Hygieneprodukte |
| Metsä Tissue |
| Solaris Paper |
| Others |
Supply & Pricing Matrix
Overcapacity in European bleached pulp mills is compressing spot prices for northern softwood kraft while tightening contract premiums for EU Ecolabel-certified grades, forcing converters to arbitrage between compliant inventory and standard bulk supply.
Pricing Analysis
The customization-premium spread between standard bulk rolls and dispenser-configured formats runs wide across institutional procurement. Three-tier pricing structure across premium bamboo-pulp blends, standard double-ply household grades, and economy single-ply commercial tiers captures divergent buyer willingness-to-pay. Cost compression in the economy tier intensifies because Texas and Florida healthcare networks consolidated supplier rosters, squeezing converter margins. Janitorial services exhibit highest price sensitivity due to inventory complexity pressures, while German boutique hospitality buyers absorb softness premiums for alternative fiber certification.
Supply Chain Analysis
Extended payment terms from US airport authorities and corporate campus facility managers are forcing working-capital strain onto mid-tier converters without captive pulp supply. Fiber supply concentrates in the United States, China, and Germany, with converting capacity clustering around major metropolitan distribution hubs. Raw material dependencies center on northern bleached softwood kraft, recycled post-consumer pulp, and emerging bamboo-pulp blends. Single-source vulnerability runs through proprietary dispenser core dimensions that lock facilities into sole-source relationships. Distribution runs through janitorial supply distributors repositioning around technical specification support rather than price negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where dispenser ecosystem lock-in creates high switching costs that protect incumbent share against price-based competition.
For Market Incumbents: Pre-empt emerging bamboo-pulp specialists by securing exclusive dispensing system partnerships with sensor-enabled manufacturers before alternative fiber certification becomes table stakes. Backward integration into closed-loop bleaching capacity at Shandong and Guangdong mills hedges against China's MEE wastewater discharge rule tightening. Channel control through subscription janitorial platforms captures lifetime value data that raises rival customer acquisition costs.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's first-time commercial dispensing demand generated by Mumbai-Delhi airport modernization and government cleanliness campaigns. Underpenetrated janitorial service contractors in Maharashtra offer faster qualification timelines than saturated US healthcare networks. Go-to-market angle should bundle ISO 14001 certification documentation with technical dispenser specification support to bypass price-driven procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated hygiene platforms with captive dispenser ecosystem lock-in, positioning these archetypes for superior cash-flow stability. Long-term viability hinges on regulatory entrenchment through EU Ecolabel and FDA food-contact compliance rather than commodity scale economics. Acquisition targets should display backward integration into pulp supply or exclusive sensor-dispenser partnerships. Watch for inflection when China's MEE rules force mill consolidation that eliminates marginal non-integrated converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber sourcing hedges against northern bleached softwood kraft price volatility at European mills. |
| Dispenser Ecosystem Partnership | Exclusive sensor-calibration agreements with touchless system manufacturers create facility lock-in against second-source qualification. |
| EU Ecolabel Certification Investment | Bleaching chemistry compliance extracts sustainability premiums from German municipal and corporate procurement mandates. |
| Subscription Platform Launch | Predictable replenishment models for US facility managers bypass traditional distribution markups and capture usage data. |
| Alternative Fiber Supply Development | Bamboo-pulp blend capacity addresses California and German boutique hospitality demand for lower water-intensity grades. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with mill procurement directors, facility management executives at US hospital networks, janitorial supply distributors, and sustainability officers at German corporate campuses; alongside secondary validation through customs trade records, EPA Safer Choice product listings, EU Ecolabel certified product databases, and pulp mill environmental disclosure filings. Bottom-up volume triangulation across product type, application setting, and distribution channel converged with top-down macroeconomic sanity checks.
Forecast inputs considered capacity utilization at North American and European pulp mills, dispenser installation rates at Chinese quick-service restaurant chains, and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions modeled include product construction tier, end-use environment sensitivity, procurement channel structure, and regional certification requirement intensity. CAGRs derived from slope analysis of historical volume trajectories adjusted for structural break points around pandemic-era hygiene protocol changes and subsequent procurement centralization trends.
Sensitivities concentrate around pulp input cost volatility, dispenser interoperability standardization outcomes, and divergent regional sustainability mandate enforcement intensity. Forecasts reflect assumptions about continued procurement centralization at US healthcare networks and MEE rule implementation timelines at Chinese mills. Macroeconomic contraction, regulatory delay, or breakthrough plastic hand dryer efficiency gains would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Drinkware Accessories Market
Household Items
Countertop Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Air Humidifier Market
Household Items
Netherlands Cookware Market
Household Items
Sorting Hampers Market
Household Items
Coffin and Cremation Urn Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Portable Showers Market
Household Items
Japan Cookware Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Commercial Lawnmower Market
Household Items
Thermos Bottle Market
Household Items
Smart Air Purifier Market
Household Items
Electric Blankets Market