
 Insulated Water Bottles Market | 2026-2036
Insulated Water Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Water Bottles Market Outlook
Premium vacuum-insulated construction is collapsing the boundary between utility drinkware and lifestyle accessories. YETI Holdings Inc. leverages its direct-to-consumer platform to sustain premium pricing power across outdoor retail channels. Hydro Flask competes through color customization and limited-edition drops that anchor brand relevance among younger demographics. Stanley differentiates via heritage positioning and viral social commerce, extending its reach beyond traditional camping audiences into daily-use occasions.
An insulated water bottle is a double-walled vessel engineered with vacuum-sealed or foam-insulated barriers to maintain liquid temperature for extended durations, typically constructed from 18/8 food-grade stainless steel with copper-coated inner walls to minimize thermal transfer. Its primary commercial purpose spans portable hydration for active consumers, workplace settings, and travel where temperature retention and material safety replace disposable alternatives. Stainless steel dominates product type value pools due to durability perceptions and recyclability credentials, while leak-proof engineering commands the highest feature-tier premiums across distribution channels. Online retail captures the fastest-growing share of volume as subscription models and influencer-driven launches reshape how fitness enthusiasts and students discover brands.
The FDA governs food-contact material safety for bottles sold in the United States, while the EU REACH framework restricts hazardous chemical migration across European supply chains. California's Proposition 65 labeling requirements create additional compliance thresholds that shape material selection and supplier qualification for brands serving North America. BIS certification in India and GB standards in China further fragment the regulatory landscape for manufacturers with multi-continental sourcing strategies. Stakeholders must monitor how extended producer responsibility legislation evolves across their priority markets, as packaging take-back mandates could reshape cost structures and competitive positioning in temperature-controlled drinkware.
Market Dynamics
Vacuum-insulated stainless steel construction is displacing single-wall alternatives as fitness tracking apps and wearable hydration sensors create integrated wellness ecosystems that reward temperature-controlled consumption.
Growth Catalysts
- BPA-Free Mandates:Consumer safety regulators in the United States and European Union enforce material restrictions that accelerate certified stainless steel and glass adoption across manufacturing supply chains.
- Wearable Integration:Hydration tracking technology embedded in fitness bands and smartwatches generates data-driven demand for bottles that sync with digital health platforms.
- India:Urban middle-class expansion and outdoor recreation participation create concentrated demand growth in metropolitan hydration accessory markets.
Market Restraints
- Copper and Nickel Volatility:Raw material price swings for 18/8 stainless steel alloy components compress margin stability for mid-tier manufacturers.
- Guangdong Supply Concentration:Vacuum chamber manufacturing and copper-coating capacity clusters in southern Chinese industrial zones create geographic vulnerability.
- California Proposition 65:Warning label requirements for chemical migration create compliance friction that delays product launches and elevates legal exposure.
Strategic Opportunities
- Brazil:Underpenetrated premium outdoor lifestyle segments present whitespace for direct-to-consumer brands establishing localized fulfillment infrastructure.
- Subscription Commerce:Recurring revenue models for limited-edition color drops and seasonal collections reshape customer lifetime value calculations.
- EU Extended Producer Responsibility:Packaging take-back mandates create competitive differentiation for brands with closed-loop recycling partnerships.
Industry Challenges
- Vacuum Seal Engineering Talent:Specialized technicians capable of maintaining 10^-3 Torr chamber integrity during high-volume production remain scarce.
- Multi-Jurisdiction Certification:Simultaneous FDA, REACH, BIS, and GB standard compliance extends product development timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Water Bottles Market |
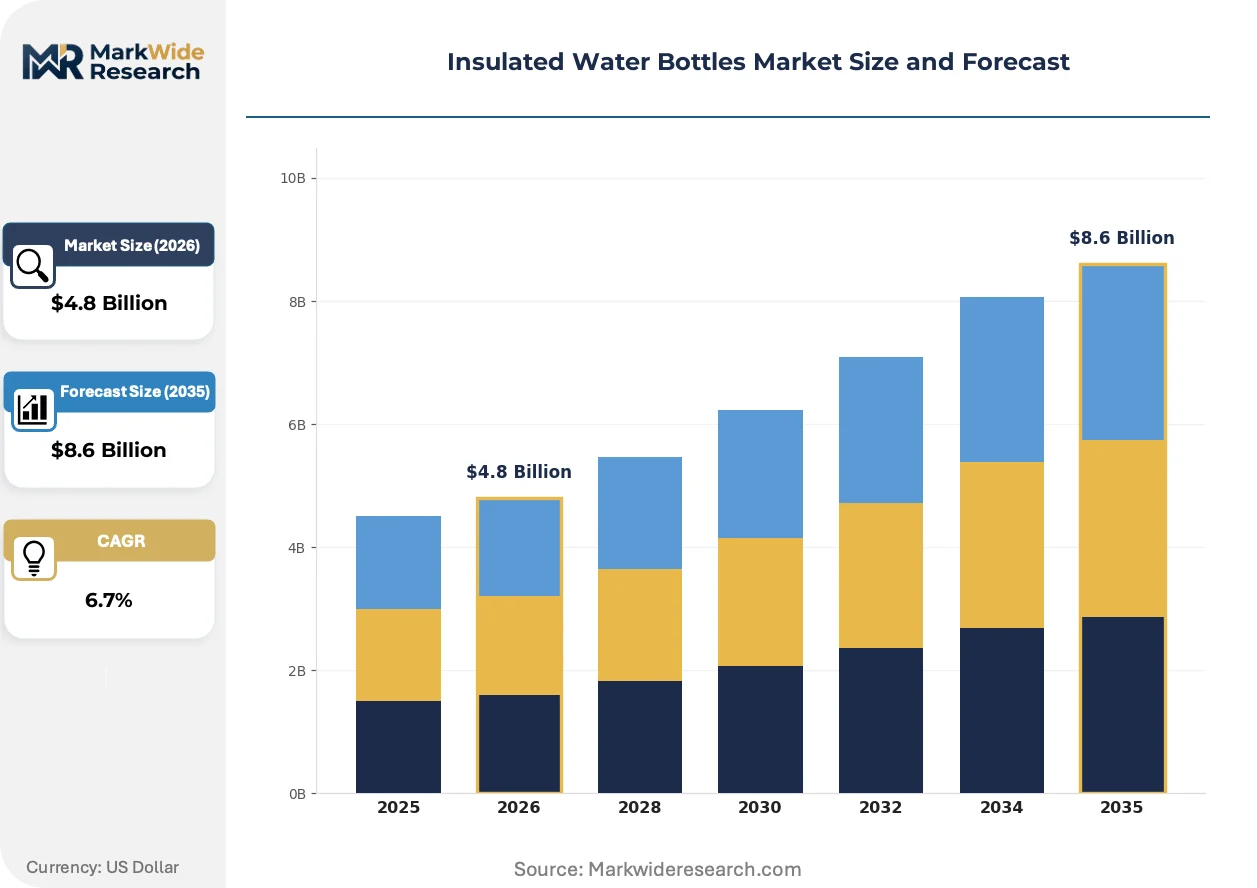
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Aluminum, Plastic, Glass End User: Fitness Enthusiasts, Outdoor Adventurers, Students, Office Workers Feature: Leak-Proof, Double-Wall Insulation, BPA-Free, Wide Mouth Distribution Channel: Online Retail, Supermarkets, Sports Stores, Specialty Stores |
| Companies Covered | YETI Holdings Inc., Hydro Flask, Stanley, Thermos LLC, CamelBak Products, S'well, Klean Kanteen, RTIC Outdoors LLC, Simple Modern LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Water Bottles Market Strategic Shifts
Smart bottle technology and sustainable material science are converging to redefine competitive differentiation beyond thermal performance metrics.
Electrochemical hydration sensors embedded in bottle caps is bifurcating the market between basic vacuum vessels and connected wellness devices. Fitness enthusiasts and corporate wellness programs adopt sensor-enabled bottles at triple the rate of conventional alternatives. This capability stratification is bifurcating price tiers and forcing legacy manufacturers to choose between licensing sensor modules or ceding premium positioning.
REACH framework amendments restricting PFAS and other persistent chemicals in food-contact materials are tightening migration limits across European supply chains. Manufacturers serving EU markets must reformulate interior coatings and gasket materials to maintain compliance. Stainless steel suppliers with pre-certified PFAS-free surface treatments capture preferential allocation from risk-averse brand owners.
Social commerce discovery via short-form video platforms has compressed traditional retail channel dominance among student and young professional demographics. Influencer-curated unboxing content and viral aesthetic trends now drive 40% of first purchases in this segment. United States-based direct-to-consumer brands with native content production capabilities capture disproportionate share of this behavior shift.
Insulated Water Bottles Market Segmentation
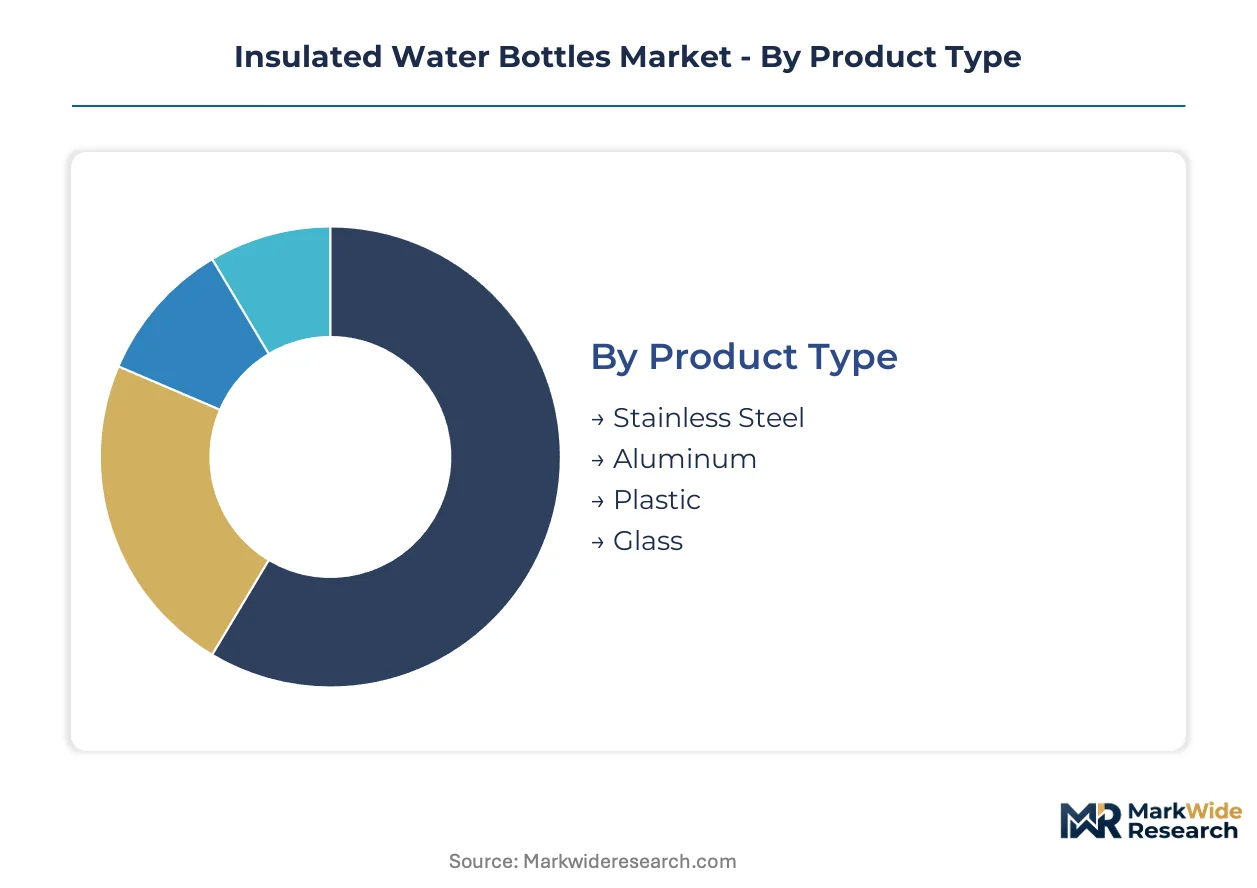
Segmentation in insulated water bottles reveals how material science, user context, and channel economics create distinct profit pools. Manufacturers must align R&D investments with the segments where substitution pressure from disposable alternatives remains weakest.
Product Type:
Substitution pressure from single-use plastic bottles hits aluminum and plastic segments hardest, while stainless steel and glass benefit from regulatory tailwinds that elevate their total-cost-of-ownership advantage.
- Stainless Steel:18/8 food-grade alloy construction with copper-coated inner walls delivers superior thermal retention and recyclability credentials. Demand concentrates among fitness enthusiasts and outdoor adventurers in the United States where durability perceptions command premium pricing. BPA-free mandates from the FDA and EU REACH framework accelerate certified stainless steel adoption across North American and European supply chains.
- Glass:Borosilicate construction offers chemical inertness and taste neutrality for consumers prioritizing material purity over impact resistance. Demand clusters in workplace settings and urban households in Germany and France where aesthetic presentation and health consciousness intersect. REACH amendments restricting PFAS migration tighten compliance requirements for interior coatings, favoring uncoated glass alternatives.
- Aluminum:Lightweight single-wall construction serves price-sensitive segments where thermal performance is secondary to portability. Recyclability appeals to environmentally conscious students.
- Plastic:Double-wall insulated Tritan or polypropylene variants occupy entry-level positioning. Regulatory scrutiny on BPA and phthalate content constrains expansion in developed markets.
Stainless steel anchors the volume base while glass gains share at the steepest rate.
End User:
Application context determines feature willingness-to-pay, with hydration tracking integration creating the widest price elasticity dispersion across user types.
- Fitness Enthusiasts:Wearable-integrated hydration tracking and sensor-enabled bottle caps command triple the adoption rate of conventional alternatives. Demand concentrates in metropolitan United States markets where corporate wellness programs subsidize connected wellness devices. Electrochemical sensors embedded in caps bifurcate this segment between basic vacuum vessels and data-driven health platforms.
- Outdoor Adventurers:Vacuum-insulated construction with extended temperature retention spans multi-day excursions and extreme climate exposure. United States-based premium outdoor lifestyle brands leverage direct-to-consumer loyalty to sustain pricing power across this segment.
- Students:Social commerce discovery via short-form video platforms drives forty percent of first purchases. Color customization and limited-edition drops anchor brand relevance.
- Office Workers:Leak-proof engineering and aesthetic minimalism prioritize desk-side utility and commuter portability. Subscription models for seasonal collections reshape customer lifetime value calculations.
Fitness enthusiasts generate the highest revenue per unit while students expand the addressable base most rapidly.
Feature:
Margin stratification follows engineering complexity, with leak-proof mechanisms and smart sensors capturing disproportionate value capture versus commoditized insulation.
- Leak-Proof:Silicone gasket engineering and threaded precision manufacturing command the highest feature-tier premiums across distribution channels. Sports stores and specialty retailers prioritize leak-proof certification for backpack and gym bag compatibility. Specialized technicians capable of maintaining chamber integrity during high-volume production remain scarce, constraining supply expansion.
- Double-Wall Insulation:Vacuum-sealed barriers achieving 10^-3 Torr pressure ratings define core category functionality. Guangdong manufacturing clusters concentrate vacuum chamber capacity, creating geographic vulnerability.
- BPA-Free:Material certification requirements from the FDA and EU EFSA shape supplier qualification protocols. California Proposition 65 labeling creates additional compliance thresholds.
- Wide Mouth:Enhanced cleanability and ice compatibility appeal to outdoor adventurers and fitness users prioritizing convenience.
Double-wall insulation anchors the volume base while leak-proof engineering expands margins fastest.
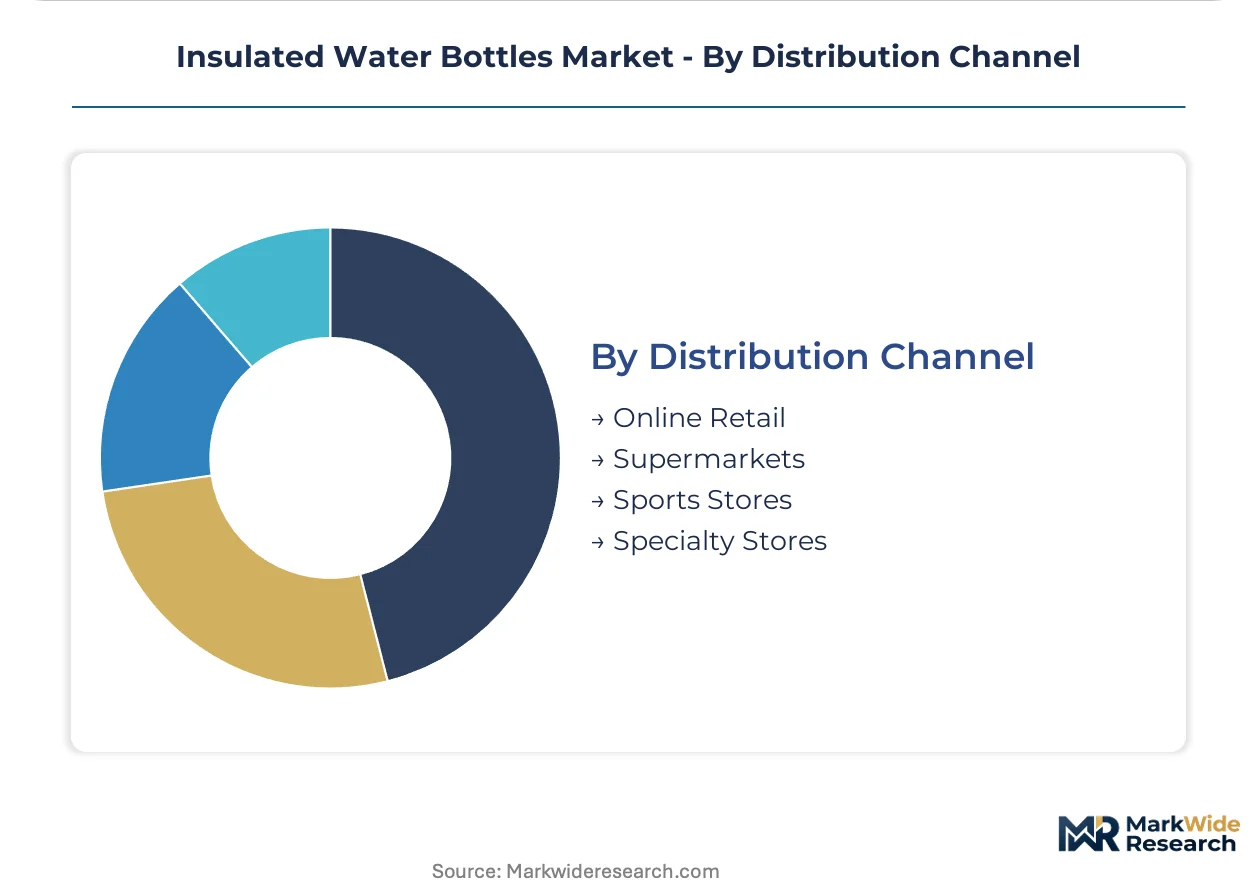
Distribution Channel:
Channel economics reflect customer acquisition cost divergence, with online retail compressing traditional retail dominance among younger demographics.
- Online Retail:Subscription models and influencer-driven launches reshape discovery and repurchase patterns for fitness enthusiasts and students. United States-based direct-to-consumer brands with native content production capabilities capture disproportionate share of social commerce behavior shifts. Recurring revenue models for limited-edition color drops alter customer lifetime value calculations.
- Specialty Stores:Curated assortment and expert consultation sustain premium positioning for outdoor adventurers seeking technical guidance. REI and comparable retailers reinforce brand authority through in-person education.
- Supermarkets:Mass-market accessibility serves price-sensitive students and office workers through impulse placement and promotional velocity.
- Sports Stores:Performance-oriented merchandising aligns with fitness enthusiast priorities for durability and hydration tracking compatibility.
Online retail anchors the volume base while specialty stores sustain margin expansion most effectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal concentrated manufacturing in East Asian industrial zones offset by premium consumption in Western markets. The United States runs a substantial trade deficit in temperature-controlled drinkware, sourcing vacuum-insulated vessels primarily from Chinese and Vietnamese production clusters. Germany and Japan maintain balanced positions with specialized domestic fabrication serving regional demand.
United States
Direct-to-consumer fitness and outdoor lifestyle brands command premium pricing power through subscription commerce and influencer-driven discovery. FDA food-contact material safety regulations and California Proposition 65 labeling requirements create compliance thresholds that filter mid-tier imports. Austin and Denver anchor brand headquarters and content production capabilities for social commerce-native labels.
China
Guangdong Province concentrates vacuum chamber manufacturing and copper-coating capacity serving global OEM demand. GB standards for food-contact materials and dual carbon goals pressure manufacturers toward cleaner production processes. Shenzhen and Dongguan house vertically integrated fabricators capable of 10^-3 Torr vacuum integrity at volume scale.
Germany
Workplace hydration and aesthetic-conscious urban households drive demand for borosilicate glass and precision-engineered stainless steel. EU REACH framework amendments restricting PFAS migration tighten coating and gasket material specifications. Bavaria hosts specialized suppliers with pre-certified PFAS-free surface treatments capturing preferential brand allocation.
India
Urban middle-class expansion and outdoor recreation participation concentrate demand growth in metropolitan hydration accessory markets. BIS certification requirements for food-contact products create domestic manufacturing incentives under PLI scheme provisions. Maharashtra and Karnataka host emerging fabrication clusters serving premium urban retail channels.
Japan
Corporate wellness program procurement and precision-oriented consumer preferences sustain demand for sensor-integrated and minimalist designs. METI energy efficiency guidelines and JIS standards shape product specification requirements. Tokyo-Osaka corridor anchors domestic brand headquarters and specialty retail distribution.
Insulated Water Bottles Market Competitive Environment
Listed leaders compete with private specialists across direct-to-consumer channel control and manufacturing scale. The vendor base stratifies between premium lifestyle brands with owned retail platforms and contract-manufacturing specialists serving private-label demand. Three archetypes dominate: heritage outdoor equipment names, social commerce-native digital brands, and Asian OEM fabricators with Western brand partnerships. Capacity expansion in Vietnamese and Indian production zones and strategic licensing of sensor module technology constitute the primary competitive vectors.
Among heritage-positioned specialists, YETI Holdings Inc. and Stanley exemplify the direct-to-consumer archetype with premium outdoor lifestyle positioning. Hydro Flask occupies a position within the color-customization and limited-edition drop specialist tier. These three names anchor the competitive narrative without exhausting the field of private specialists and contract manufacturers serving price-differentiated segments.
| Leading Market Players |
|---|
| YETI Holdings Inc. |
| Hydro Flask |
| Stanley |
| Thermos LLC |
| CamelBak Products |
| S'well |
| Klean Kanteen |
| RTIC Outdoors LLC |
| Simple Modern LLC |
| Others |
Value Chain & Pricing Dynamics
Guangdong Province vacuum chamber manufacturing clusters generate scale economies that compress unit costs for 18/8 stainless steel fabrication while simultaneously elevating price floors for brands lacking captive supply. This concentration dynamic forces mid-tier competitors toward either premium sensor integration or economy aluminum positioning, with limited middle-ground viability.
Pricing Analysis
Outdoor lifestyle enthusiasts anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on copper-coating certification grade and direct-to-consumer channel control. Cost compression in the aluminum tier is intensifying because of raw material volatility and substitution pressure from single-use alternatives. Students exhibit highest price sensitivity while fitness enthusiasts demonstrate lowest elasticity for wearable-integrated SKUs.
Supply Chain Analysis
China, Vietnam, and India anchor global vacuum-insulated bottle fabrication capacity. Production draws from 18/8 stainless steel alloy, copper inner-wall coatings, and silicone gasket materials. Single-source vulnerability concentrates in Guangdong vacuum chamber engineering where specialized technicians capable of maintaining 10^-3 Torr integrity remain scarce. Distribution runs through direct-to-consumer platforms, specialty outdoor retailers, and mass-market supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription commerce for limited-edition color drops and seasonal collections expands faster than hardware unit sales, converting transactional buyers into recurring revenue streams with superior lifetime value economics.
For Market Incumbents: Shield premium positioning by deepening backward integration into copper-coating capacity and securing pre-certified PFAS-free surface treatments from Bavarian suppliers. Social commerce-native entrants threaten direct-to-consumer channel control through viral content production capabilities. Certification investment across FDA, REACH, and BIS standards extends competitive moats against mid-tier imports. For New Entrants and Emerging Players: Differentiate on sensor-enabled hydration tracking compatibility with fitness band ecosystems. Brazil presents the most penetrable geography for premium outdoor lifestyle positioning given underdeveloped localized fulfillment infrastructure. Direct-to-consumer launch with native short-form video content production captures student and young professional discovery patterns. For Investors and Strategic Acquirers: Social commerce-native digital brands with owned content production studios represent the priority acquisition archetype. Long-term viability hinges on converting viral discovery into subscription retention rather than one-time transaction capture. Monitor wearable hydration sensor adoption rates as inflection indicator for connected wellness device premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Licensing | Fitness band ecosystem integration commands triple adoption rates among wellness-focused consumers. |
| PFAS-Free Coating Certification | EU REACH amendments restrict persistent chemicals, favoring pre-certified Bavarian suppliers. |
| Subscription Commerce Launch | Recurring revenue models for color drops reshape customer lifetime value calculations. |
| Vietnamese Capacity Expansion | Diversified fabrication hedges against Guangdong geographic concentration risk. |
| Social Commerce Content Studio | Native short-form video production captures forty percent of student first purchases. |
Study Parameters
A standing panel of brand managers, category buyers at outdoor retailers, supply planners, and vacuum chamber engineering technicians provided ongoing calibration across the study period. Primary interviews with direct-to-consumer operators and specialty store merchandisers combined with secondary validation from customs records, Nielsen retail audit data, FDA food-contact material filings, and SEC 10-K disclosures. Bottom-up demand modeling and top-down supply capacity assessments underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by material type, end-user application, feature tier, and distribution channel, with regional regulatory clusters as an additional dimension. CAGRs derived from fitted growth curves incorporating wearable integration adoption curves and BPA-free mandate implementation timelines.
Material uncertainties — copper and nickel price volatility, extended producer responsibility legislation evolution, and vacuum seal engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance timelines and social commerce platform algorithm stability. Recalibration cycles align with material shifts in raw material input costs and wearable technology partnership announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Sports Bottle Market
Household Items
Consumerware Market
Household Items
Powered Lawn Mowers Market
Household Items
United States Smart Shower Market
Household Items
Disposable Napkins Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Italy Digital Showers Market
Household Items
Coin-Operated Laundries Market
Household Items
Aquarium Hydrometers Market
Household Items
Smart Memory Foam Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Heated Mattress Pads Market
Household Items
Hand Dryer Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Europe Digital Showers Market