
 Toilet Hygiene Products Market | 2026-2036
Toilet Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Hygiene Products Market Analytics
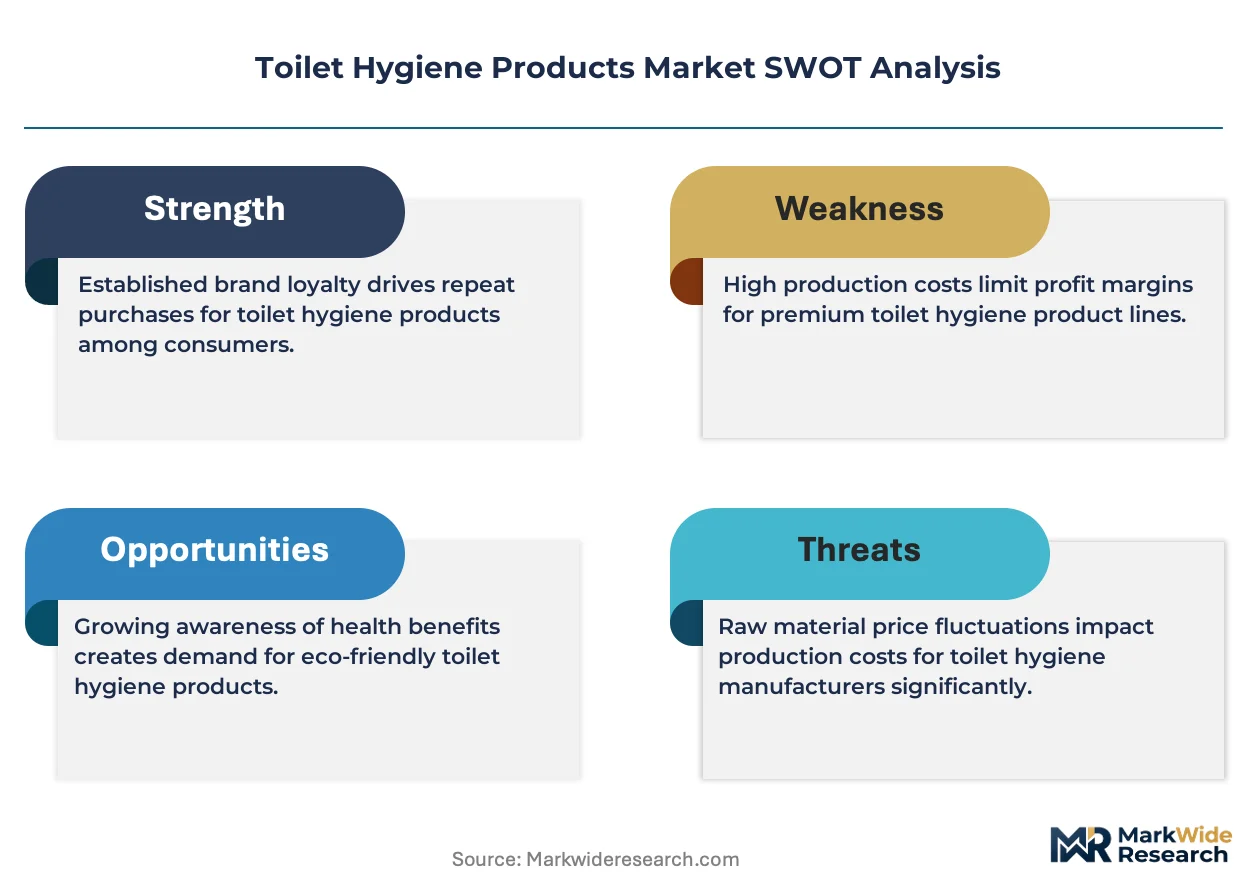
REACH is realigning the cost-of-entry calculus for surfactant suppliers entering European retail channels. Reckitt Benckiser leverages its Lysol manufacturing footprint to sustain dual-hemisphere compliance without third-party tolling. Procter & Gamble anchors its North American position through captive bleach supply and Kroger-Walmart shelf-space agreements. Henkel AG & Co. KGaA differentiates via enzyme-based toilet tablet formulations that bypass traditional chlorine chemistry.
Toilet hygiene products encompass chemical and mechanical formulations engineered to sanitize ceramic fixtures, eliminate biofilm accumulation, and neutralize malodorous compounds through oxidative or enzymatic action; active ingredients typically range from sodium hypochlorite concentrations of 0.5–5% to quaternary ammonium compounds dosed at 400–1500 ppm for institutional applications. Toilet cleaners dominate absolute revenue due to replenishment frequency, while disinfectant wipes represent the fastest-expanding margin pool as healthcare facilities upgrade from general-purpose to sporicidal claims. Automatic air fresheners command premium shelf positioning in online retail channels where subscription bundling with toilet bowl tablets reduces customer acquisition costs.
The EPA's Design for the Environment program and the EU Ecolabel framework constrain permissible volatile organic compound thresholds, compelling reformulation investments that favor multi-national R&D budgets over regional private-label competitors. India's BIS certification requirements for antimicrobial efficacy claims create additional testing-layer costs for imported finished goods. Stakeholders must monitor regulatory divergence between OECD-aligned biodegradability standards and emerging economy enforcement gaps that could fragment sourcing strategies.
Market Dynamics
Post-pandemic institutional sanitation mandates have permanently elevated sporicidal efficacy standards, forcing reformulation investments that favor suppliers with captive R&D infrastructure over toll-dependent competitors.
Growth Catalysts
- Healthcare procurement upgrades:Hospital systems in the United States are mandating EPA-registered disinfectant wipes with C. difficile kill claims, expanding addressable volume for high-concentration quaternary ammonium formulations.
- REACH biodegradability mandates:The EU Green Deal's surfactant reformulation deadlines are compressing supply bases, advantaging European manufacturers with in-house fermentation capacity for biosourced alternatives.
- Enzymatic chemistry maturation:Protease-lipase blends for biofilm disruption now achieve parity with chlorine on malodor control, opening premium positioning in Nordic markets with stringent VOC ceilings.
Market Restraints
- Chlor-alkali supply concentration:Sodium hypochlorite precursor availability clusters around Gulf Coast petrochemical corridors, exposing formulators to hurricane-season input volatility.
- BIS testing-layer costs:India's antimicrobial efficacy certification requires 90-day local stability trials, extending time-to-market for imported finished goods by two fiscal quarters.
- Quat resistance documentation:Institutional buyers now demand longitudinal efficacy studies against emerging resistant strains, raising qualification barriers for regional private-label entrants.
Strategic Opportunities
- Subscription bundling models:Direct-to-consumer platforms in Germany are combining automatic toilet bowl dispensers with refill tablets, capturing lifetime value through locked-in consumable replenishment.
- MEA hospitality expansion:Luxury hotel construction in Dubai and Riyadh is specifying touchless sanitation fixtures, creating specification-grade demand for integrated cleaning-dispensing systems.
- EPA Safer Choice penetration:The Design for the Environment label is becoming a procurement filter for US federal facilities, rewarding early reformulators with sole-source contract eligibility.
Industry Challenges
- Surfactant toxicology expertise scarcity:Formulation chemists with biodegradability testing experience command 40% compensation premiums, constraining mid-tier R&D expansion.
- Legacy dispenser retrofit complexity:Automatic toilet cleaning hardware from the 2010s lacks IoT connectivity, complicating predictive maintenance rollouts in aging commercial building stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Hygiene Products Market |
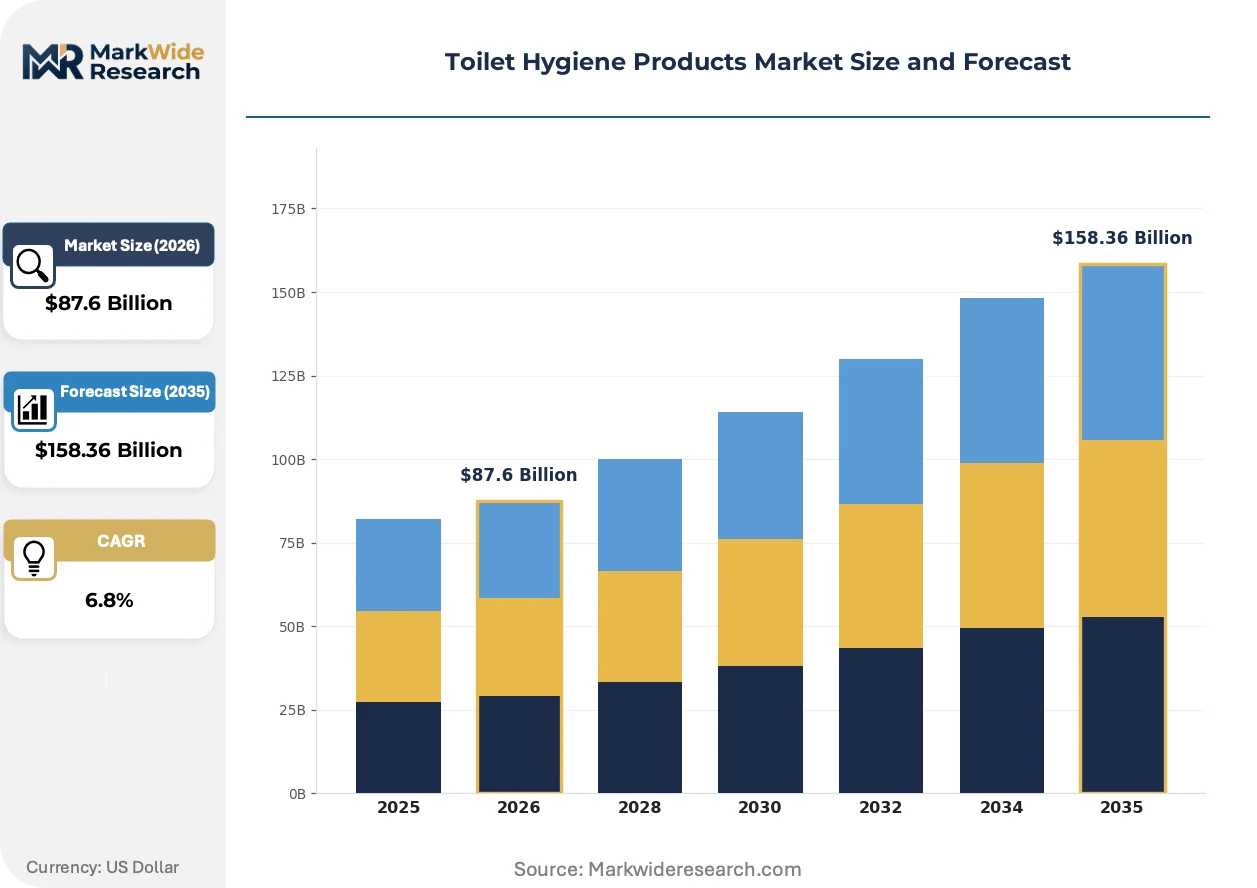
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilet Cleaners, Disinfectant Wipes, Toilet Bowl Tablets, Automatic Air Fresheners Packaging Type: Bottles, Tubes, Pouches, Cans End User: Households, Businesses, Educational Institutions, Healthcare Facilities Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Reckitt Benckiser, Unilever PLC, Procter & Gamble, The Clorox Company, S. C. Johnson & Son Inc., Henkel AG & Co. KGaA, Church & Dwight Co., Inc., Kimberly-Clark, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Hygiene Products Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing simultaneous transformation, with enzymatic alternatives gaining specification share and procurement platforms disintermediating traditional janitorial supply hierarchies.
Solid-form toilet bowl tablets with sustained-release enzyme matrices are consolidating category share in European retail. German and French mass-market buyers are adopting these formats at rates exceeding liquid alternatives. The technology is consolidating shelf space previously fragmented across gel, liquid, and aerosol segments, compressing SKU counts at major grocers.
REACH Annex XVII restrictions on nonylphenol ethoxylates are forcing surfactant substitution across European supply chains. Formulators are pivoting toward alcohol ethoxylates and alkyl polyglucosides despite 15-20% raw material cost premiums. Institutional contract manufacturers serving Dutch and Belgian healthcare networks face the most compressed reformulation timelines.
Healthcare procurement departments are consolidating vendor lists around full-line sanitation suppliers capable of dual chemical-mechanical system integration. Traditional janitorial distributors are losing specification influence to direct manufacturer relationships with infection control committees. This concentration is most visible in United States acute care networks exceeding 500 beds.
Toilet Hygiene Products Market Segmentation
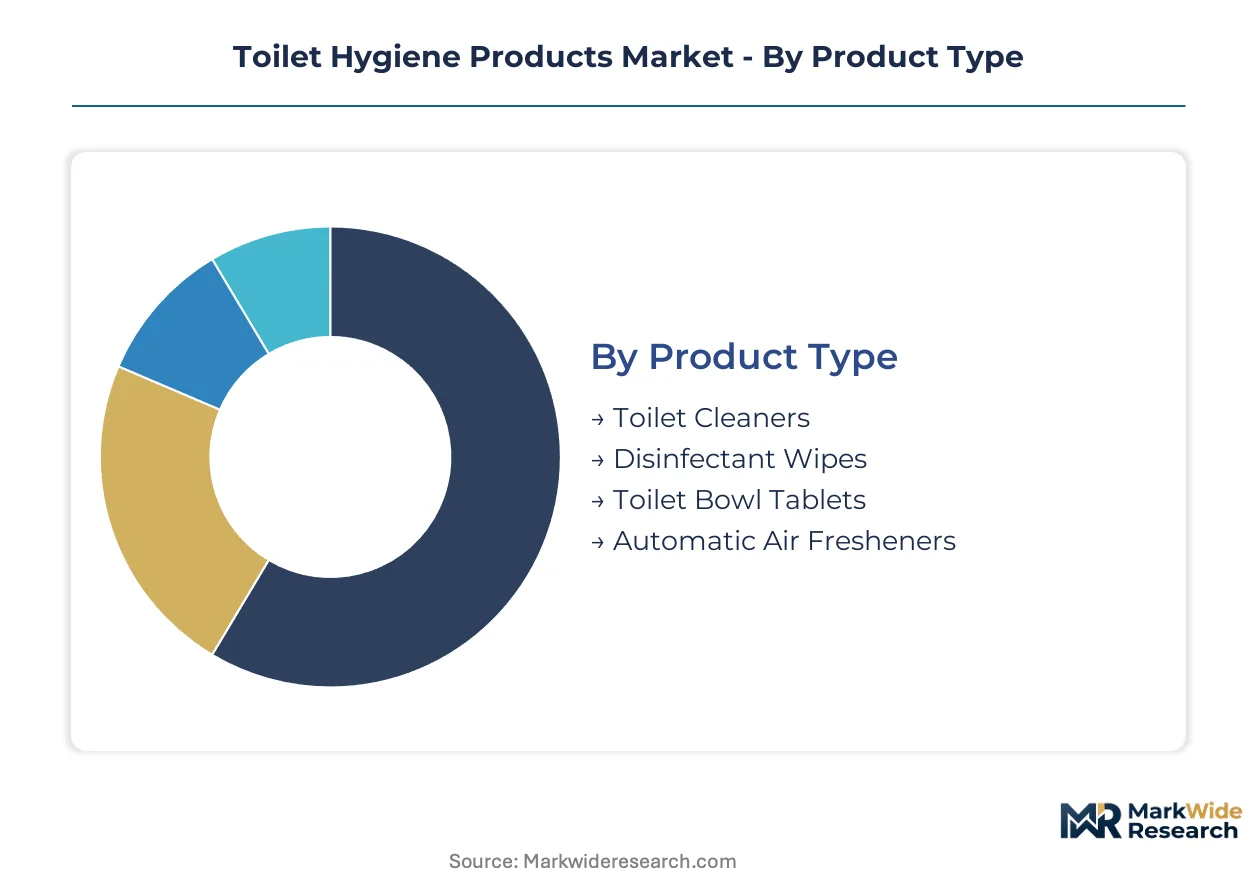
Toilet hygiene procurement splits across formulation chemistry, delivery hardware, and institutional compliance tiers. Understanding these divisions exposes where margin pools concentrate and where regulatory pressure reshapes supplier viability.
Product Type:
Formulation chemistry determines efficacy claims, replenishment frequency, and regulatory qualification burden.
- Toilet Cleaners:Liquid and gel formulations carrying sodium hypochlorite or quaternary ammonium concentrations dominate absolute volume through weekly household replenishment cycles. United States mass-market buyers prioritize EPA-registered disinfectant claims over fragrance differentiation, compressing premium pricing power.
- Disinfectant Wipes:Sporicidal formulations with C. difficile kill claims command the steepest expansion trajectory as United States hospital systems mandate single-use protocols over reusable microfiber. Healthcare procurement consolidation around full-line suppliers favors manufacturers with captive wipe substrate production.
- Toilet Bowl Tablets:Sustained-release enzyme matrices and chlorine-based alternatives serve automatic dispenser systems. Nordic markets specify low-VOC enzymatic chemistry under REACH volatile organic compound ceilings.
- Automatic Air Fresheners:Integrated dispensing hardware with IoT connectivity enables predictive refill scheduling. Subscription bundling with toilet bowl tablets reduces customer acquisition costs in German direct-to-consumer channels.
Mature deployment sits with toilet cleaners. Newer deployment is concentrated in disinfectant wipes.
Packaging Type:
Packaging selection trades shelf stability, shipping economics, and sustainability credentials against regulatory labeling requirements.
- Bottles:High-density polyethylene containers dominate liquid toilet cleaner distribution through United States supermarket channels. Post-consumer recycled content mandates in California and New York are forcing resin specification changes.
- Pouches:Flexible film formats reduce freight cube and support concentrated refill economics. European retail buyers specify recyclable mono-material structures under Extended Producer Responsibility frameworks.
- Tubes:Collapsible aluminum and laminate structures serve gel and cream formulations. Slower throughput limits adoption outside premium positioning.
- Cans:Aerosol formats persist in automatic air freshener segments despite volatile organic compound scrutiny. EPA Safer Choice qualification requires propellant reformulation investments.
Established infrastructure favors bottles. Emerging sustainability compliance is accelerating pouch specification.
End User:
Procurement authority and efficacy standards diverge sharply between residential and institutional buyers.
- Healthcare Facilities:Infection control committees mandate EPA-registered sporicidal claims with documented efficacy against emerging resistant strains. United States acute care networks exceeding 500 beds consolidate vendor lists around full-line sanitation suppliers.
- Businesses:Corporate facility managers balance cost containment against occupant complaint reduction. Touchless fixture specification in Dubai and Riyadh hospitality construction creates demand for integrated cleaning-dispensing systems.
- Households:Mass-market buyers respond to subscription bundling and fragrance differentiation more than disinfectant registration tier. German direct-to-consumer platforms capture lifetime value through locked-in consumable replenishment.
- Educational Institutions:K-12 and university procurement departments prioritize bulk pricing and storage safety over premium efficacy claims. Budget constraints limit adoption of healthcare-grade formulations.
Compliance complexity peaks with healthcare facilities. Volume scale concentrates in households.
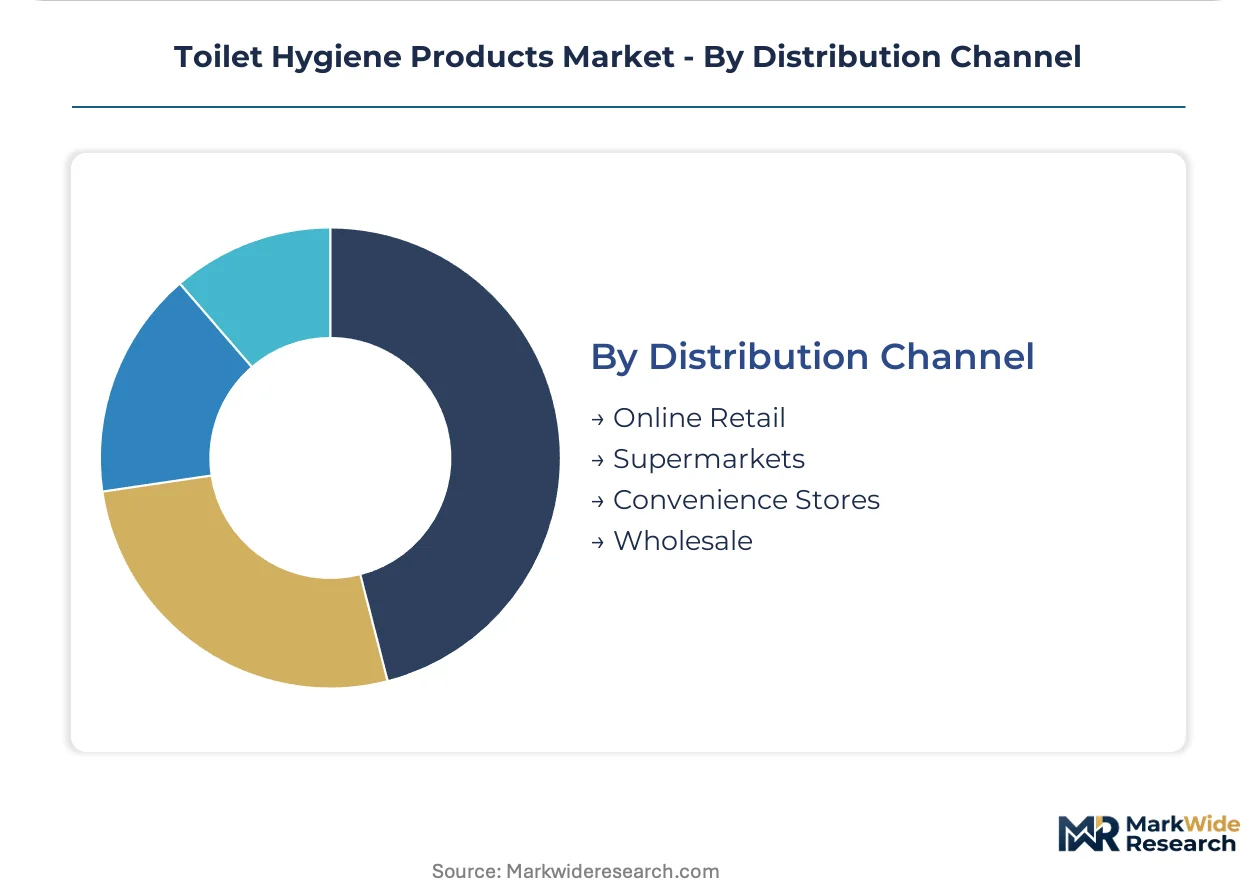
Distribution Channel:
Channel selection determines margin capture, customer data access, and regulatory traceability obligations.
- Supermarkets:Kroger-Walmart shelf-space agreements anchor North American mass-market penetration. Slotting fees and promotional calendars favor multi-national marketing budgets over regional private-label competitors.
- Online Retail:Direct-to-consumer platforms enable subscription bundling and predictive replenishment algorithms. German markets show highest automatic toilet bowl dispenser adoption through this channel.
- Wholesale:Institutional contract manufacturers serve Dutch and Belgian healthcare networks through consolidated procurement platforms. Traditional janitorial distributors lose specification influence to direct manufacturer relationships.
- Convenience Stores:Emergency replenishment and travel-size formats generate impulse volume. Limited shelf space restricts SKU breadth to top-moving chlorine and bleach variants.
Procurement digitization is advancing fastest through online retail. Legacy infrastructure remains entrenched in supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Dahej Special Economic Zone draws surfactant manufacturers with duty exemptions on imported ethylene oxide derivatives, concentrating toilet hygiene chemical production along India's western industrial corridor.
United States
Hospital systems exceeding 500 beds mandate EPA-registered sporicidal disinfectant wipes with C. difficile kill claims. The EPA's Design for the Environment program filters federal facility procurement toward safer chemistry formulations. Gulf Coast chlor-alkali corridors around Houston supply sodium hypochlorite precursors to formulators, though hurricane exposure creates seasonal input volatility.
Germany
REACH Annex XVII deadlines on nonylphenol ethoxylates compress surfactant reformulation timelines for contract manufacturers. The EU Green Deal accelerates biosourced alcohol ethoxylate adoption despite 15-20% raw material premiums. Direct-to-consumer platforms in Berlin and Hamburg capture automatic toilet bowl dispenser subscriptions through predictive replenishment algorithms.
India
BIS certification requires 90-day local stability trials for antimicrobial efficacy claims, extending time-to-market for imported finished goods. Maharashtra's Mumbai-Pune industrial belt hosts private-label formulators serving domestic retail chains. Gujarat's Dahej SEZ concentrates surfactant production with ethylene oxide derivative duty exemptions.
China
GB standards for volatile organic compounds constrain aerosol propellant formulations in automatic air fresheners. The Yangtze River Delta around Shanghai anchors wipe substrate manufacturing for export markets. Dual carbon goals pressure petrochemical-based surfactant producers toward fermentation-derived alternatives.
UAE
Luxury hospitality construction in Dubai and Riyadh specifies touchless sanitation fixtures with integrated cleaning-dispensing systems. MOHAP antimicrobial efficacy guidelines align with Gulf Cooperation Council harmonization efforts. Jebel Ali Free Zone clusters import-distribution operations for MENA regional supply.
Toilet Hygiene Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and delivery hardware segments. The vendor base organizes around three strategic archetypes: multi-national consumer goods houses with captive bleach supply, regional contract manufacturers with fermentation-based surfactant capacity, and specialty chemical firms with enzyme formulation expertise. Competitive moves concentrate on M&A for full-line sanitation capabilities and strategic partnerships for IoT-enabled dispenser ecosystems.
Among diversified consumer goods conglomerates, Reckitt Benckiser and Procter & Gamble occupy positions reflecting dual-hemisphere manufacturing scale and retail shelf-space anchoring. Henkel AG & Co. KGaA exemplifies the enzyme-based chemistry specialist archetype, representing reformulation investments that bypass traditional chlorine pathways. These three entities sit within distinct competitive tiers—global mass-market penetration, North American retail dominance, and European premium positioning—without overlapping strategic postures.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Unilever PLC |
| Procter & Gamble |
| The Clorox Company |
| S. C. Johnson & Son Inc. |
| Henkel AG & Co. KGaA |
| Church & Dwight Co., Inc. |
| Kimberly-Clark |
| Kao Corporation |
| Others |
Value Network & Pricing Analysis
Captive bleach supply integration anchors both cost position and pricing power for North American formulators, insulating them from Gulf Coast chlor-alkali volatility while compressing margins for toll-dependent competitors sourcing sodium hypochlorite on spot markets.
Pricing Analysis
Short lead-time premiums concentrate in healthcare procurement, where United States hospital systems pay contract premiums for EPA-registered sporicidal wipes with documented C. difficile efficacy delivered within 48 hours. Pricing stratifies across premium enzymatic formulations, standard chlorine chemistry, and economy private-label bleach variants, with differentiation driven by certification tier and captive substrate production. Cost compression in economy tiers intensifies because of polyethylene resin volatility and recycled-content mandates in California and New York. Educational institutions exhibit highest price sensitivity, while acute care networks prioritize kill-claim documentation over unit cost.
Supply Chain Analysis
India's BIS domestic-content mandates reshape sourcing for antimicrobial finished goods, compelling importers to establish local stability-testing infrastructure or cede share to Maharashtra-based private-label formulators. Surfactant production concentrates in India, China, and Germany, with ethylene oxide derivative availability tethered to petrochemical corridors in Gujarat's Dahej SEZ and the Yangtze River Delta. Single-source vulnerability sits with Gulf Coast chlor-alkali concentration exposed to hurricane-season disruption. Distribution runs through wholesale institutional platforms in Dutch and Belgian healthcare networks, bypassing traditional janitorial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around full-line sanitation capabilities, with REACH biodegradability deadlines and sporicidal efficacy documentation requirements forcing toll-dependent regional competitors toward exit or acquisition.
For Market Incumbents: Extend captive R&D infrastructure into biosourced surfactant fermentation capacity before REACH Annex XVII deadlines compress European supply bases. Secure direct infection control committee relationships in United States acute care networks exceeding 500 beds, displacing traditional janitorial distributors losing specification influence. Channel control through Kroger-Walmart shelf-space agreements anchors North American mass-market position against private-label encroachment. For New Entrants and Emerging Players: EPA Safer Choice qualification in the United States opens a window for sole-source federal facility contracts, bypassing crowded retail shelf-space competition. Target subscription bundling models in German direct-to-consumer channels, where predictive replenishment algorithms lock in lifetime consumable value. Pursue integrated cleaning-dispensing system specifications in Dubai and Riyadh luxury hospitality construction as the most penetrable institutional segment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multi-national consumer goods houses seeking full-line sanitation capabilities. Five-to-ten year viability favors contract manufacturers with in-house fermentation capacity for alcohol ethoxylate alternatives and captive wipe substrate production. Watch for EPA registration tier expansion into emerging resistant strain claims as the inflection signal for premium formulation valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Fermentation | REACH Annex XVII compliance secures European healthcare contract eligibility against reformulation-dependent competitors. |
| Direct-to-Consumer Subscription Launch | German platform predictive algorithms reduce customer acquisition costs for automatic toilet bowl dispenser refills. |
| EPA Safer Choice Certification Investment | Federal facility procurement filters reward early reformulators with sole-source contract eligibility in the United States. |
| Integrated Dispensing Hardware Partnership | Touchless fixture specifications in Dubai and Riyadh hospitality construction create specification-grade demand capture. |
| C. Difficile Kill Claim Registration Expansion | Hospital system vendor consolidation favors manufacturers with longitudinal efficacy documentation against emerging resistant strains. |
Research Methodology
Independent corroboration across infection control committee procurement officers, surfactant plant managers, and retail category buyers underwrites the qualitative findings, with secondary validation drawing from EPA registration databases, REACH Annex XVII regulatory filings, and Nielsen retail audit data. Bottom-up volume triangulation from formulation chemistry throughput and top-down value estimation from shelf-space velocity reconcile across the analysis window.
Comparable-period anchoring to post-pandemic institutional procurement baselines structures the projection horizon, with segmentation modeling across formulation chemistry, packaging format, end-user compliance tier, and distribution channel. CAGRs derive from surfactant raw material cost trajectory analysis and healthcare procurement upgrade cycle timing. Enzymatic chemistry maturation curves and IoT-enabled dispenser adoption rates inform alternative scenario boundaries.
The model assumes a particular technology adoption path; alternative pathways for solid-form enzyme matrix tablets would alter the outlook if Nordic low-VOC specifications accelerate beyond current REACH timelines. Forecasts reflect assumptions regarding chlor-alkali supply stability and BIS certification processing efficiency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Knife Set Market
Household Items
Heated Towel Rail Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Paper Towel Dispenser Market
Household Items
Umbrella Market
Household Items
Soap Dispenser Market
Household Items
Cups and Pots Market
Household Items
Japan Faucets Market
Household Items
MENA POU Water Purifiers Market
Household Items
Thermos Bottle Market
Household Items
Countertop Market
Household Items
Residential Water Purifier Market
Household Items
Multi-Door Fridges Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Europe Hand Dryers Market