
 Fan Market | 2026-2036
Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Fan Market Analysis
A capital-intensity divergence between integrated motor manufacturers and assembly-focused brands is reorganizing competitive tiers in the fan industry. Emerson Electric Co. leverages captive motor production to sustain margin control across industrial segments. Midea Group Co. Ltd. anchors volume leadership through manufacturing scale in Asia-Pacific supply chains. Havells India Limited differentiates via channel depth in domestic electrical retail networks.
A fan is a rotary bladed device driven by an electric motor, typically operating at rotational speeds between 200 and 350 RPM for ceiling configurations, designed to induce air circulation for thermal comfort, ventilation, or process cooling in residential, commercial, and industrial environments. Ceiling Fan installations dominate replacement cycles and new construction attach rates across tropical climates. DC Motor Fans command premium positioning as energy-efficiency regulations tighten motor-performance thresholds. Smart Fans represent the fastest-growing technology slice as connected-home ecosystems expand controller integration.
US DOE appliance standards, EU Ecodesign requirements, and India's BIS mandatory labeling program collectively elevate minimum-efficiency floors and restrict market access for non-compliant products. China's SAMR enforces GB standards that phase out single-phase induction motors below specified efficiency tiers. Stakeholders must monitor regulatory harmonization pressures between efficiency mandates and connected-device cybersecurity frameworks as product intelligence deepens.
Market Dynamics
DC motor technology is bifurcating the fan industry's cost structure, separating premium efficiency tiers from legacy induction motor portfolios as regulatory mandates tighten minimum performance thresholds across major economies.
Growth Catalysts
- India BIS mandatory labeling:The Bureau of Indian Standards energy-efficiency labeling program accelerates replacement demand in residential cooling across tier-two urban centers as electrification expands.
- Smart home ecosystem integration:Connected controller platforms in Southeast Asian urban centers pull demand toward WiFi-enabled ceiling configurations compatible with voice-activated automation systems.
- Industrial process cooling:Manufacturing facility ventilation upgrades in Vietnam and Indonesia drive specification-grade fan procurement for thermal management in assembly operations.
Market Restraints
- Copper and rare-earth magnet cost volatility:DC motor production depends on neodymium supply concentration in Chinese processing facilities, exposing margin compression risks.
- Single-phase induction motor phase-outs:China's SAMR enforcement of GB motor-efficiency standards eliminates low-tier production capacity before replacement supply chains mature.
- Ceiling fan replacement cycle extension:Improved bearing technologies and blade durability materials compress residential refresh demand in saturated urban markets.
Strategic Opportunities
- Philippines rural electrification gaps:Off-grid solar-powered DC fan configurations address cooling access in island communities beyond centralized grid infrastructure.
- EU Ecodesign regulatory tailwind:Minimum efficiency requirements for residential ventilation products create compliant-product premium positioning for Asian exporters.
- Agricultural livestock ventilation:Precision climate control in poultry and dairy operations in Brazil opens specification-grade demand for corrosion-resistant industrial configurations.
Industry Challenges
- Embedded systems engineering scarcity:Smart fan development requires firmware and IoT security expertise that competes with broader consumer electronics talent pools.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and BIS testing protocols extend product launch schedules for cross-border brands.
- Legacy HVAC integration complexity:Building management system compatibility demands proprietary protocol adaptation that fragments R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fan Market |
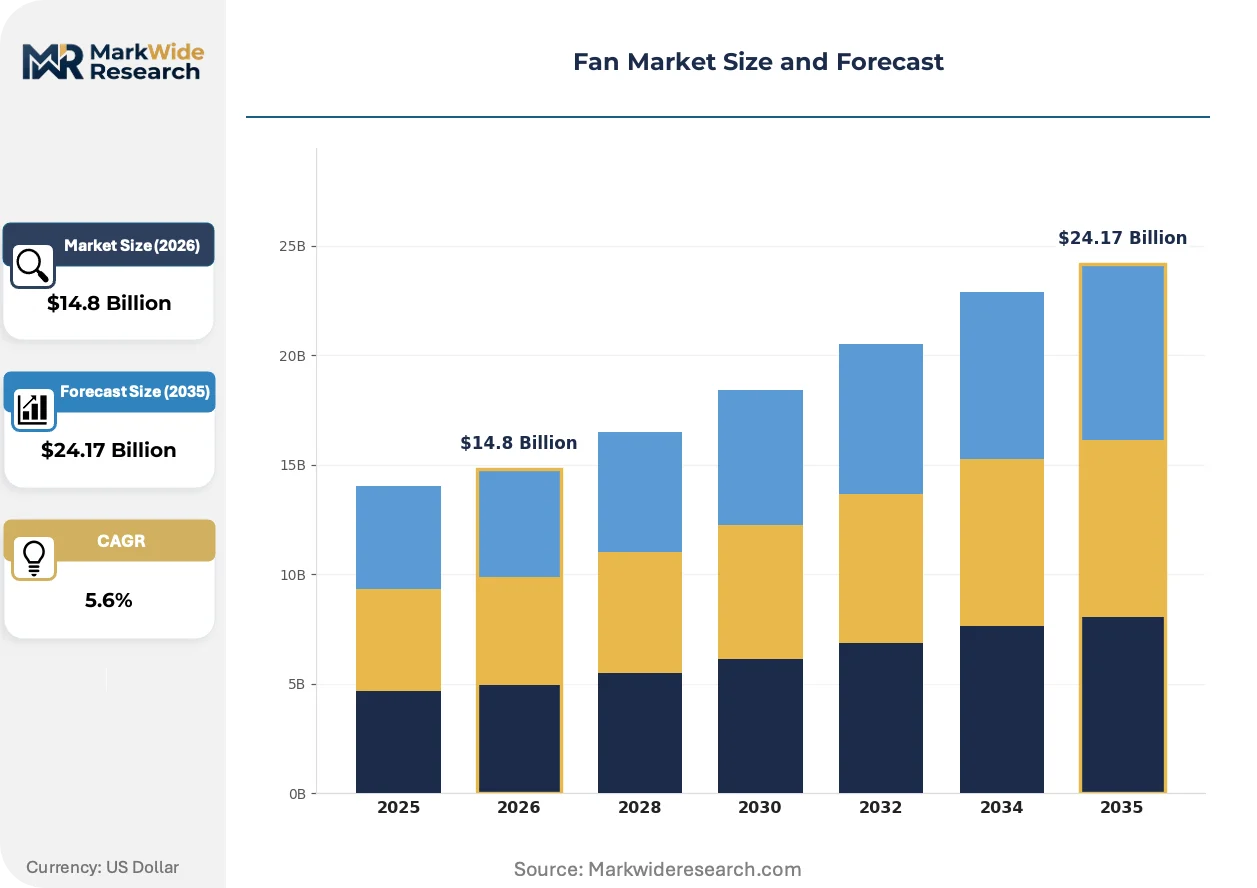
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Fan, Table Fan, Tower Fan, Exhaust Fan End User: Residential, Commercial, Industrial, OEM Technology: Smart Fans, Energy-Efficient Fans, Conventional Fans, DC Motor Fans Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Hunter Fan Company, Emerson Electric Co., Minka Aire, Crompton Greaves Consumer Electricals Limited, Westinghouse Lighting Corporation, Panasonic Corporation, Midea Group Co. Ltd., Havells India Limited, Monte Carlo Fans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fan Market Emerging Trajectories
Product intelligence and motor topology are reshaping competitive differentiation, with efficiency regulations and connectivity standards forcing portfolio restructuring across manufacturing bases.
Brushless DC motor architecture is bifurcating the residential ceiling fan segment into connected premium tiers and basic efficiency-compliant offerings. Southeast Asian property developers specify DC configurations for new condominium construction, while replacement markets in India and Indonesia lag adoption curves. This technology divide is compressing margins for single-speed induction motor portfolios while enabling price premiums for variable-speed, app-controlled systems.
China's SAMR enforcement of updated GB motor-efficiency standards phases out IE1 and IE2 induction motor classes from domestic production. Manufacturers must retool winding and lamination processes to meet IE3 minimums or exit volume residential segments. Export-oriented producers in Guangdong and Zhejiang provinces accelerate DC platform shifts to maintain access to European markets under concurrent Ecodesign requirements.
Channel consolidation in electrical wholesale is compressing distributor counts while expanding direct-to-contractor digital platforms. Industrial and commercial buyers in India's tier-one cities bypass traditional retail networks for manufacturer portals offering specification tools and project pricing. This disintermediation is most visible in Mumbai and Bangalore, where MEP contractors source directly for high-rise residential and IT campus installations.
Fan Market Segmentation
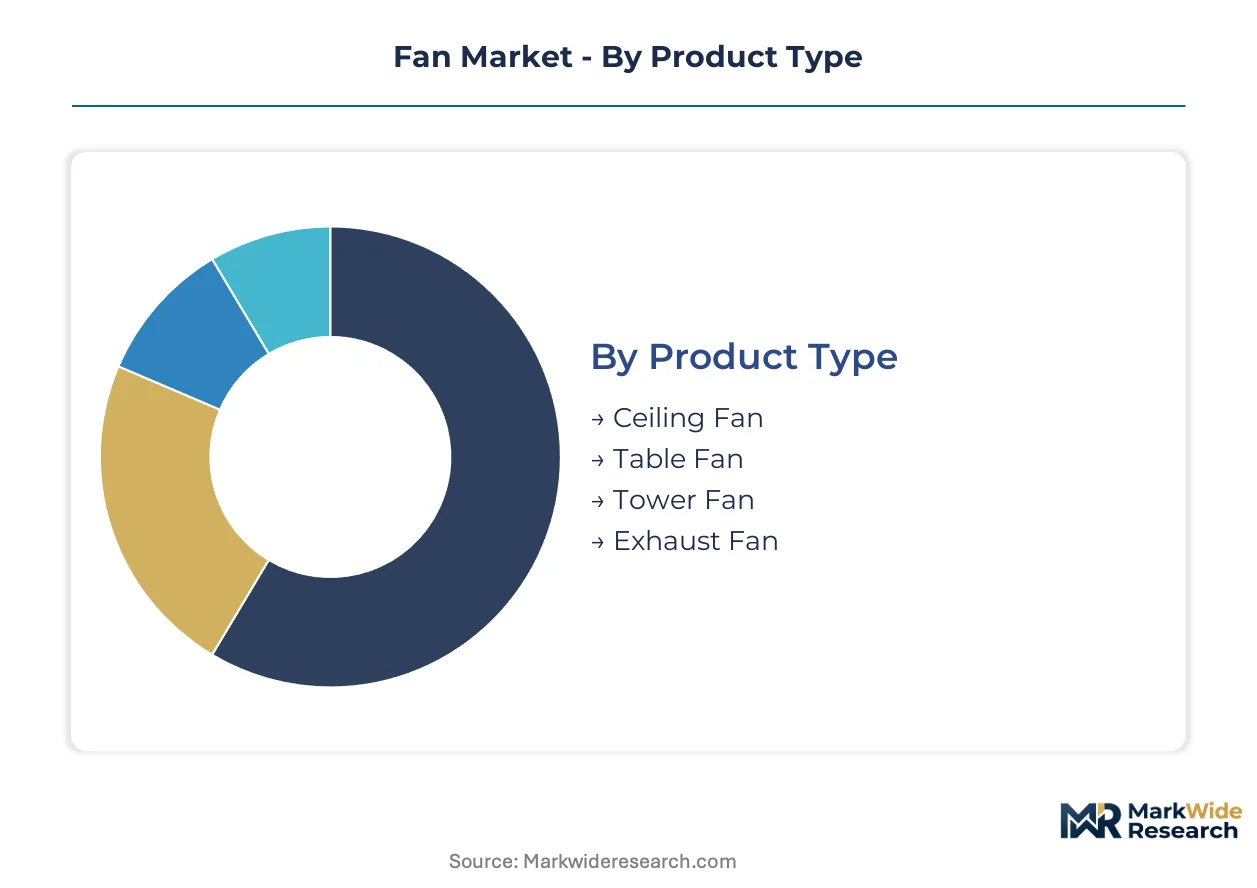
Fan market segmentation reveals how motor technology, distribution economics, and end-use specifications create distinct margin pools across product tiers. Understanding these divisions helps manufacturers allocate R&D resources and channel investments against regulatory and demand pressures.
Product Type:
Margin concentration follows installation permanence and motor complexity, with ceiling-mounted systems commanding sustained service revenue streams.
- Ceiling Fan:Permanent-mount rotary systems with 200-350 RPM operating envelopes dominate residential cooling infrastructure in tropical urban centers. India's tier-two cities and Vietnam's condominium developments drive specification-grade procurement as electrification expands and construction attach rates climb.
- Table Fan:Portable axial configurations serve supplemental cooling needs in cost-sensitive segments across Southeast Asian rental markets. Demand clusters in India's urban informal housing and Indonesia's student dormitory accommodations where permanent installation is impractical.
- Tower Fan:Vertical bladeless or cross-flow designs occupy premium positioning in developed Asian households seeking space-efficient aesthetics.
- Exhaust Fan:Ventilation-focused centrifugal and axial units address moisture and contaminant extraction in commercial kitchens and industrial process environments.
The dominant share belongs to Ceiling Fan, while Tower Fan is closing the gap fastest.
End User:
Application-driven specification requirements separate price-competitive residential volumes from engineering-intensive industrial procurements.
- Residential:Individual household cooling represents volume concentration across India's electrifying tier-two cities and Vietnam's emerging middle-class developments. BIS energy-labeling mandates accelerate replacement cycles as consumers upgrade from unlabeled legacy units to star-rated efficient configurations.
- Industrial:Process ventilation and thermal management in manufacturing facilities demand corrosion-resistant materials, explosion-proof ratings, and continuous-duty motor specifications. Vietnam and Indonesia assembly operations drive specification-grade procurement for worker safety compliance and equipment protection.
- Commercial:Retail, hospitality, and office installations balance aesthetic integration with energy-performance requirements under tightening Ecodesign thresholds.
- OEM:Embedded fan subsystems supplied to HVAC equipment manufacturers and appliance integrators face integration complexity and proprietary protocol demands.
Residential installations hold the volume base, though Industrial applications are expanding most quickly on manufacturing facility buildouts.
Technology:
Regulatory efficiency floors and connectivity premiums are bifurcating the cost structure between legacy induction portfolios and advanced motor platforms.
- DC Motor Fans:Brushless permanent-magnet systems with variable-speed electronic commutation deliver 50-70% energy savings over induction alternatives. China's GB motor-efficiency standards and India's BIS labeling collectively phase out low-tier competition, positioning DC platforms as the compliance-default for premium residential and commercial specification.
- Smart Fans:WiFi-enabled configurations with app-based control, voice assistant integration, and occupancy sensing represent the steepest expansion trajectory. Southeast Asian smart home ecosystem adoption pulls demand toward connected ceiling installations in Bangkok, Singapore, and Jakarta high-rise developments.
- Energy-Efficient Fans:IE3-compliant induction and early DC platforms meeting minimum regulatory thresholds without full connectivity feature sets.
- Conventional Fans:Single-speed induction motor configurations face phased elimination under China's SAMR enforcement and concurrent efficiency mandates across export markets.
DC Motor Fans capture the technology margin premium, while Smart Fans are gaining share fastest on connected-home penetration.
Distribution Channel:
Channel economics reflect customer procurement sophistication and project scale, with digital platforms compressing traditional wholesale margins.
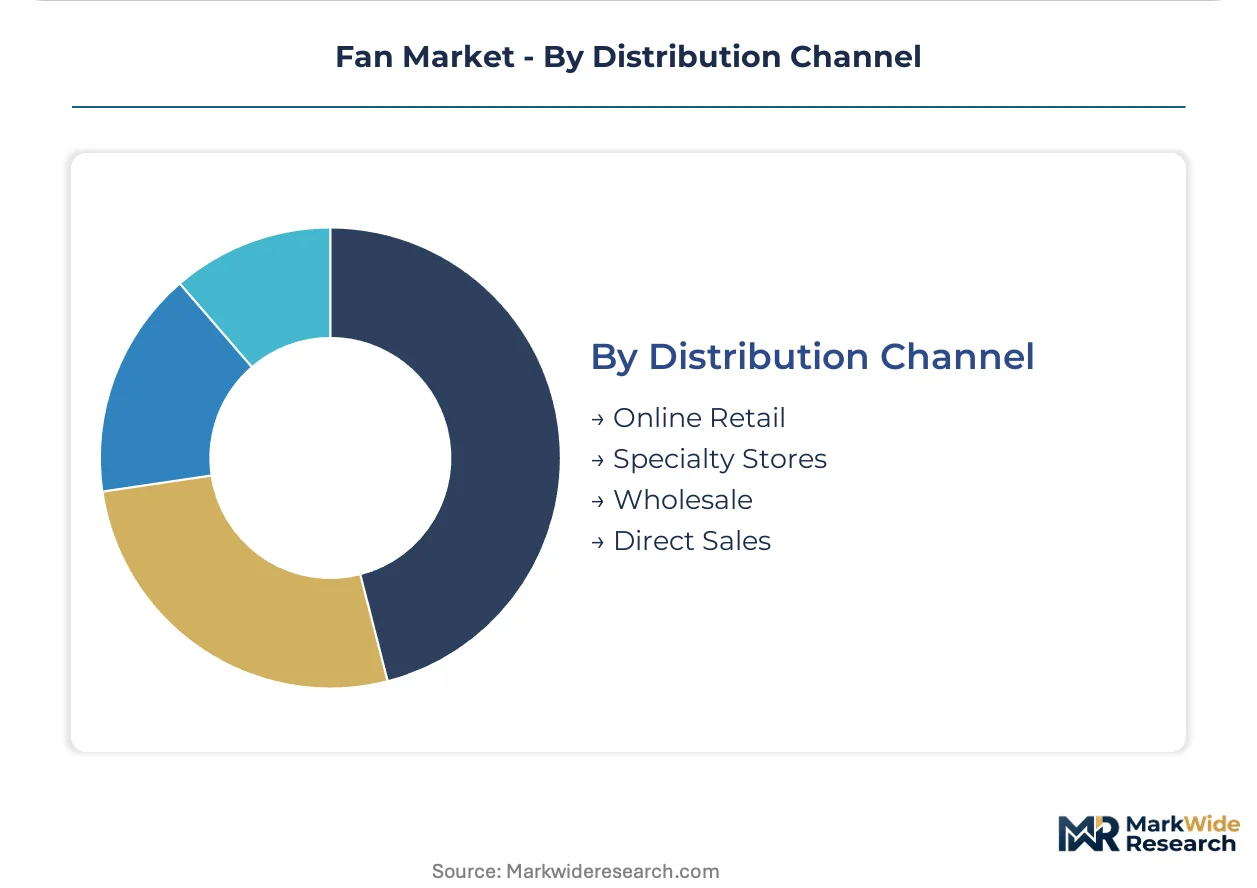
- Online Retail:E-commerce platforms capture growing share in India's tier-one cities and Southeast Asian urban centers where consumers research efficiency ratings and compare DC motor specifications before purchase. Direct-to-consumer logistics bypass traditional electrical wholesale markups while enabling manufacturer control over product education.
- Direct Sales:Manufacturer portals and specification teams serve MEP contractors and project developers in Mumbai, Bangalore, and Jakarta high-rise construction. Disintermediation is most visible in commercial and industrial segments where contractors source volume direct for campus and residential tower installations.
- Specialty Stores:Electrical retail networks maintain relevance in India's domestic market where Havells and comparable brands leverage channel depth for premium positioning.
- Wholesale:Traditional distributor networks face consolidation pressure as digital platforms and direct procurement erode volume throughput.
Specialty Stores retain the installed base, though Direct Sales are climbing the fastest on commercial project disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fan consumption patterns diverge sharply across geographies. Tropical urban centers prioritize ceiling-mounted residential cooling, while temperate industrial economies emphasize process ventilation and commercial HVAC integration.
India
Tier-two cities including Lucknow, Indore, and Coimbatore drive replacement demand as electrification expands beyond metropolitan cores. BIS mandatory energy-labeling accelerates upgrades from unlabeled legacy units to star-rated efficient configurations. Manufacturing clusters in Faridabad and Ghaziabad retool motor winding processes to meet IE3 compliance thresholds.
China
Guangdong and Zhejiang provinces anchor export-oriented production for European and Southeast Asian markets. SAMR enforcement of updated GB motor-efficiency standards phases out IE1 and IE2 induction classes from domestic manufacturing. Shenzhen and Dongguan facilities accelerate DC platform shifts to maintain Ecodesign-compliant export access.
United States
Replacement cycles dominate residential demand as improved bearing technologies extend product lifespans in saturated urban markets. DOE appliance standards elevate minimum-efficiency floors for ceiling fan configurations. Texas and Florida construction markets specify DC motor systems for new residential developments seeking ENERGY STAR certification.
Vietnam
Ho Chi Minh City and Hanoi condominium developments specify DC ceiling configurations for emerging middle-class housing stock. Industrial process cooling demand surges in Binh Duong and Dong Nai manufacturing zones for worker safety compliance. SAMR-aligned import standards shape procurement specifications for Chinese-supplied equipment.
Germany
EU Ecodesign requirements for residential ventilation products create premium positioning for compliant Asian exporters. Industrial facility upgrades in Bavaria and North Rhine-Westphalia drive specification-grade procurement for precision climate control. Munich and Stuttgart engineering consultancies specify connected fan systems with BMS integration protocols.
Fan Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the fan industry's competitive structure. Emerson Electric Co. leverages captive motor production to sustain margin control across industrial segments, while assembly-focused brands compete on channel reach and specification relationships. The market organizes around three archetypes: vertically integrated motor manufacturers, scale-driven Asian conglomerates, and domestic channel specialists. Consolidation pressures favor backward integration into core motor technologies and direct-to-contractor digital platform investments.
Within the integrated manufacturing tier, Emerson Electric Co. exemplifies captive supply chain control, while Midea Group Co. Ltd. occupies a position anchored in Asia-Pacific production scale. Havells India Limited represents the domestic channel specialist archetype, leveraging electrical retail network depth. These three entities collectively illustrate how motor technology access, manufacturing scale, and distribution infrastructure define competitive positioning across regulatory environments.
| Leading Market Players |
|---|
| Hunter Fan Company |
| Emerson Electric Co. |
| Minka Aire |
| Crompton Greaves Consumer Electricals Limited |
| Westinghouse Lighting Corporation |
| Panasonic Corporation |
| Midea Group Co. Ltd. |
| Havells India Limited |
| Monte Carlo Fans |
| Others |
Supply Flow & Price Mechanics
Sixty-day lamination steel inventories held by Guangdong motor manufacturers signal pricing power concentration among integrated producers with captive winding capacity, while spot-market buyers face margin compression from neodymium magnet cost volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one OEMs and Zhejiang motor suppliers, insulating volume buyers from rare-earth price spikes while spot purchasers absorb volatility. Pricing stratifies across IE3-compliant DC platforms, basic induction configurations, and connected smart systems with firmware bundles. Cost compression in entry-level induction tiers is intensifying because China's SAMR enforcement eliminates substandard production capacity before replacement supply chains mature. Residential replacement buyers in India's tier-two cities exhibit highest price sensitivity, while Southeast Asian property developers sourcing for condominium projects prioritize efficiency certification over unit cost.
Supply Chain Analysis
China anchors global motor manufacturing with Guangdong and Zhejiang provinces housing concentrated lamination stamping and winding operations, while India feeds from Faridabad and Ghaziabad assembly clusters serving domestic electrification demand. Neodymium permanent magnets, copper windings, and cold-rolled silicon steel constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare-earth processing facilities, exposing non-integrated brands to supply interruption. Distribution runs through electrical wholesale networks in India and direct-to-contractor digital platforms in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor adoption represents a high-growth disruption as BIS and GB regulatory mandates collectively eliminate legacy induction portfolios, compressing the transition window for manufacturing retooling.
For Market Incumbents: Fortify captive motor production capacity to sustain margin control against assembly-focused competitors dependent on spot-market magnet procurement. Accelerate IE3-compliant platform certification across BIS, CE, and UL testing protocols to preempt multi-jurisdiction launch delays. Channel control through direct-to-contractor digital platforms in Mumbai and Bangalore defends position against wholesale disintermediation.
For New Entrants and Emerging Players: Anchor in Philippines off-grid solar DC configurations where centralized grid infrastructure gaps create cooling access white space. Target tier-two Indian cities including Lucknow and Indore where electrification expansion outpaces established brand penetration. Specification-grade agricultural ventilation for Brazil's poultry and dairy operations offers engineering-intensive entry with lower volume-competition intensity.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because efficiency mandates across India, China, and EU markets structurally favor producers with integrated motor technology and certification bandwidth. Acquisition targets should screen for captive lamination and winding capacity, firmware development teams, and established BIS or Ecodesign compliance records. The signal to watch is SAMR enforcement acceleration phasing out IE2 induction classes ahead of announced timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Core Production | Captive lamination stamping insulates margin from Chinese silicon steel price volatility. |
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous BIS, CE, and UL testing compresses product launch schedules for cross-border brands. |
| Direct-to-Contractor Digital Platform Launch | Mumbai and Bangalore MEP contractors bypass wholesale markups for high-rise project sourcing. |
| Smart Home Ecosystem Partnership | WiFi-enabled ceiling configurations integrate with voice-activated automation systems in Bangkok and Jakarta. |
| Solar DC Configuration Development | Off-grid island communities in Philippines create specification demand beyond centralized grid infrastructure. |
Methodological Framework
A standing panel of motor manufacturing plant managers, electrical wholesale procurement leads, MEP contractor specification teams, and BIS certification officers provided ongoing calibration against secondary validation from customs trade data, Bureau of Energy Efficiency star-rating databases, SAMR GB standard filings, and SEC 10-K disclosures from listed electrical equipment manufacturers. Bottom-up unit shipment estimates triangulated with top-down market value reconstructions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled motor technology tier, end-use application, distribution channel structure, and regional regulatory cluster as primary segmentation dimensions. CAGRs derived from fitted growth curves applied to electrification penetration rates, construction attach rate assumptions, and replacement cycle dynamics informed by bearing technology lifespan improvements.
Material uncertainties — neodymium supply disruption, SAMR enforcement acceleration, and smart home ecosystem protocol fragmentation — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization timelines and motor-efficiency technology adoption curves. Recalibration cycles align with material shifts in BIS labeling enforcement intensity and GB standard phase-out announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
UV Sanitizer Travel Wand Market
Household Items
Pet Safe Cleaners Market
Household Items
Candle Air Fresheners Market
Household Items
Chest Freezers Market
Household Items
US Digital Showers Market
Household Items
Pet Fur Remover Market
Household Items
South Africa Cookware Market
Household Items
Robot Mops Market
Household Items
Domestic Sauna Heaters Market
Household Items
US Flashlights Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Leaf Blower Market
Household Items
Hydralight Lanterns Market
Household Items
Sleeping Pillow Market
Household Items
Portable Showers Market
Household Items
Disposable Napkins Market