
 India Non-Stick Cookware Market | 2026-2036
India Non-Stick Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
India Non-Stick Cookware Market Foresight
BIS certification for food-contact materials is expanding the compliance burden for new entrants. TTK Prestige leverages its in-house testing infrastructure to navigate these standards efficiently. Hawkins Cookers Limited anchors its market position through specialized hard-anodized product lines. Havells India Limited competes by extending its electrical appliance distribution network into cookware retail.
India non-stick cookware comprises kitchen vessels engineered with polytetrafluoroethylene or ceramic coatings applied to aluminum, stainless steel, or hard-anodized substrates, typically achieving friction coefficients below 0.1 for oil-free cooking performance. These products serve residential food preparation by reducing fat consumption and simplifying cleanup. Fry pans and cookware sets dominate volume throughput, while ceramic material formulations capture premium positioning as health concerns around traditional fluoropolymer coatings intensify. Online distribution channels are outpacing hypermarkets in growth velocity, though specialty stores retain margin concentration through experiential retail and assisted selling.
BIS standards for food-contact safety, FSSAI guidelines on chemical migration limits, and the Bureau of Indian Quality Control Orders collectively determine product legality and consumer trust in domestic cookware. CDSCO oversight of imported coating raw materials adds a secondary compliance layer for manufacturers reliant on foreign chemical suppliers. Stakeholders must monitor evolving BIS test protocol amendments and raw material import dependency to secure supply continuity and certification validity.
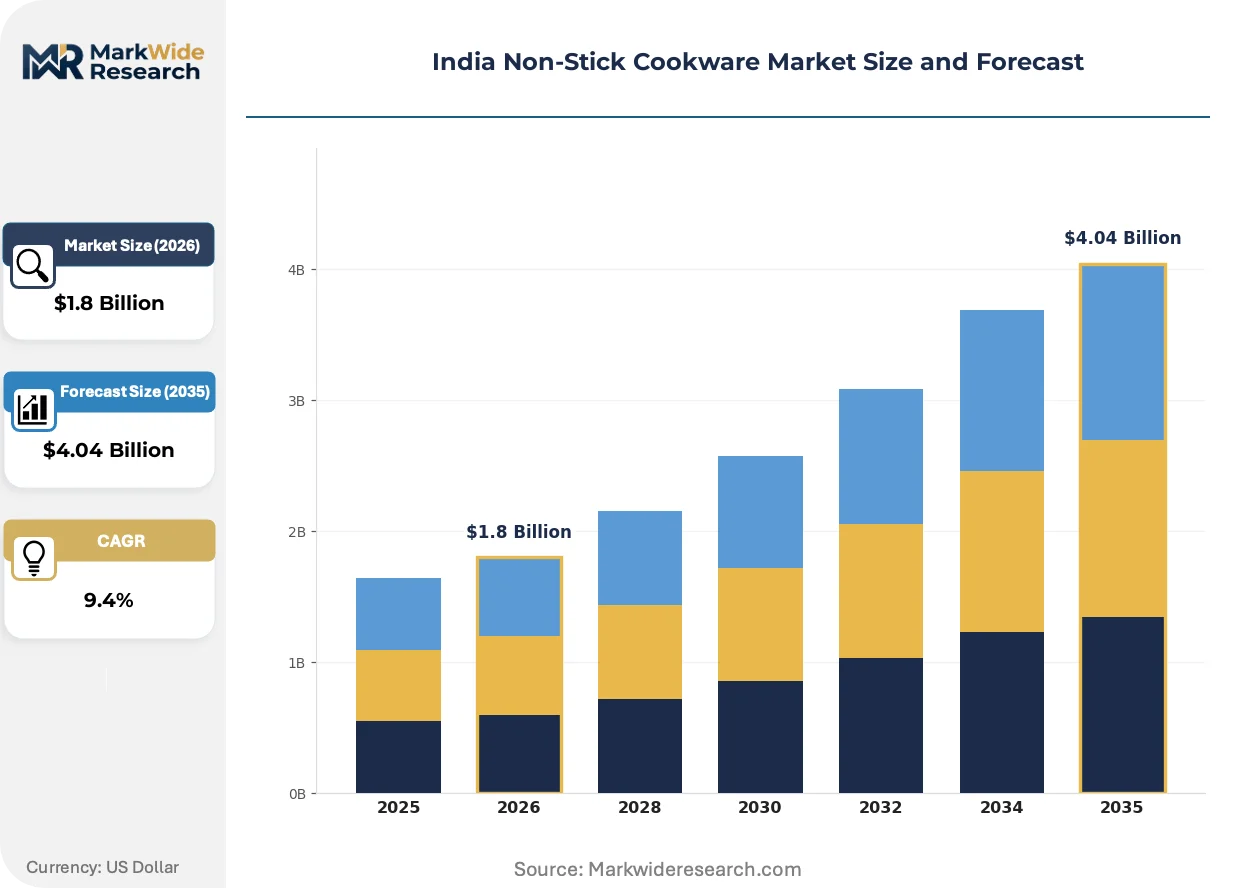
Market Dynamics
BIS certification tightening for food-contact materials is forcing domestic manufacturers to reconfigure testing infrastructure while imported coating raw materials face CDSCO scrutiny, compressing margins for non-compliant entrants.
Growth Catalysts
- Urban replacement cycles:Metropolitan households in Mumbai and Bangalore are upgrading legacy cookware as disposable incomes rise and health consciousness spreads through South Indian metropolitan clusters.
- FSSAI chemical migration limits:Stricter guidelines on coating safety are accelerating consumer trust in certified domestic brands over unorganized imports.
- Ceramic coating formulations:Health-conscious buyers are pivoting from traditional fluoropolymer surfaces toward aluminum substrates with ceramic finishes that promise reduced chemical exposure.
Market Restraints
- Import dependency for coating chemicals:CDSCO oversight of foreign-sourced polytetrafluoroethylene precursors creates supply continuity risks for manufacturers without captive chemical production.
- Aluminum substrate price volatility:Global metal commodity fluctuations compress margin predictability for mid-tier producers dependent on spot-market aluminum sourcing.
- Hard-anodized substitution:Specialized uncoated cookware lines from established domestic players capture safety-conscious consumers skeptical of any synthetic coating technology.
Strategic Opportunities
- Tier-II city penetration:Underpenetrated markets in Pune, Hyderabad, and Chennai offer volume expansion as organized retail and e-commerce logistics deepen reach beyond Delhi and Mumbai.
- Online channel acceleration:Direct-to-consumer platforms are outpacing hypermarket growth velocity, enabling margin capture through assisted selling and subscription-based cookware replacement programs.
- PLI scheme alignment:Domestic manufacturing incentives for consumer durables create capital subsidy pathways for producers investing in in-house coating application infrastructure.
Industry Challenges
- BIS test protocol amendments:Evolving certification standards require continuous laboratory reinvestment, stretching compliance timelines for smaller manufacturers without captive testing facilities.
- Coating-application talent scarcity:Specialized technicians for ceramic and fluoropolymer deposition remain concentrated in legacy industrial hubs, limiting geographic flexibility for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Non-Stick Cookware Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fry Pans, Griddles, Cookware Sets, Woks Material: Aluminum, Stainless Steel, Ceramic, Hard Anodized Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Hypermarkets, Specialty Stores, Department Stores |
| Companies Covered | Butterfly Gandhimathi Appliances Limited, Vinod Cookware India Private Limited, TTK Prestige, Usha Shriram Private Limited, Havells India Limited, Stovekraft Limited, Nirlep Appliances Private Ltd., Bhalaria Metal Craft Pvt. Ltd., Hawkins Cookers Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Non-Stick Cookware Market Shifts & Advancements
Material science advances and distribution digitization are compressing traditional product lifecycles while regulatory pressure on coating chemistry accelerates formulation diversity.
Ceramic-coated aluminum skillets are absorbing market attention from conventional polytetrafluoroethylene products as health narratives around fluoropolymer safety intensify. Premium urban households in Bangalore and Chennai are adopting these surfaces at twice the rate of replacement purchases for traditional coatings. This shift is absorbing margin concentration toward certified ceramic suppliers while compressing volume for legacy coating manufacturers.
BIS standards for food-contact safety are tightening test protocols for chemical migration from synthetic coatings into prepared food. Manufacturers must now document compliance across extended temperature cycling and acidic food exposure scenarios. Hard-anodized product lines and ceramic formulations are capturing disproportionate shelf space as retailers preempt liability exposure from non-compliant inventory.
Specialty stores are unbundling experiential retail from pure transaction efficiency, deploying assisted selling and live cooking demonstrations to justify premium positioning. This model is displacing price-competitive hypermarket placements for mid-tier brands. South Indian metropolitan clusters show the highest concentration of these experiential formats, correlating with elevated ceramic cookware penetration.
India Non-Stick Cookware Market Segmentation
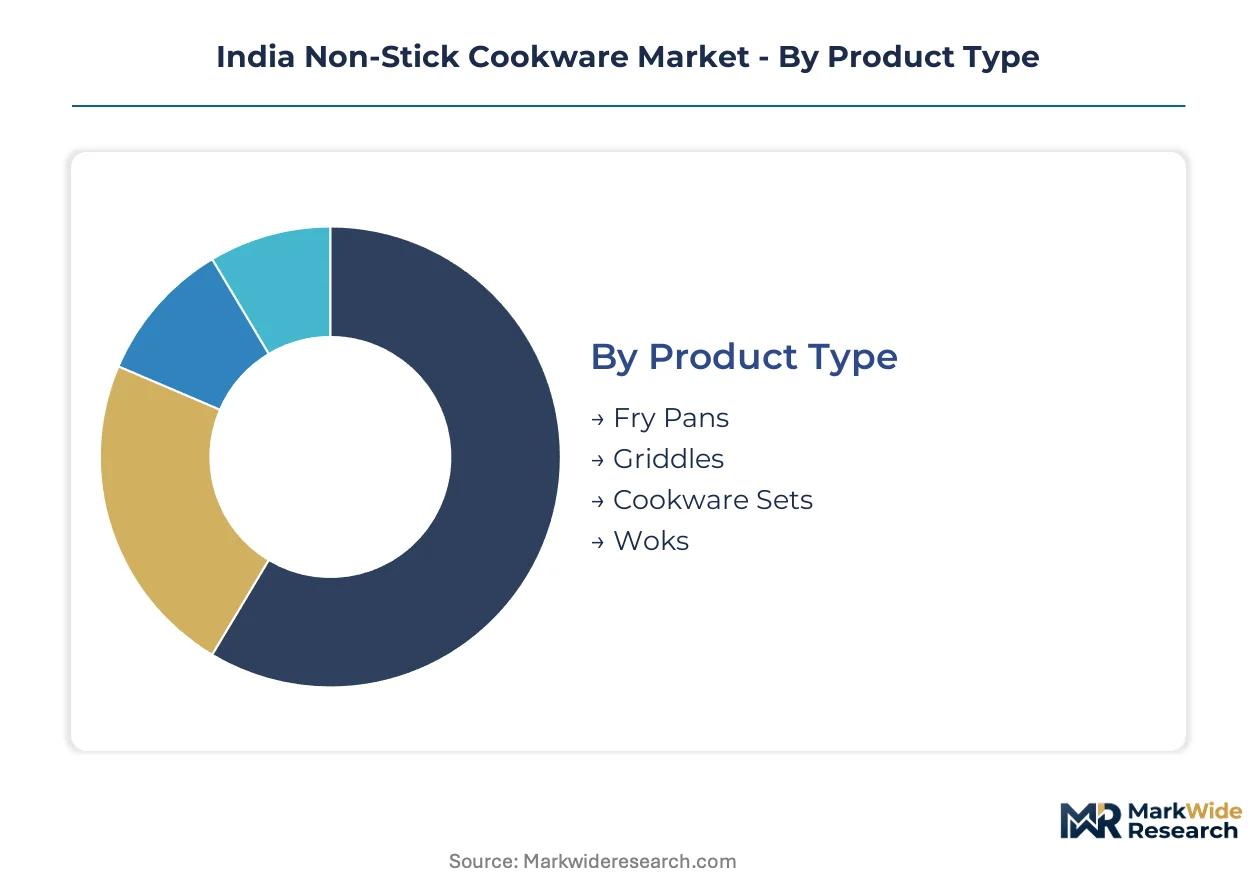
Segmentation in the India non-stick cookware market reveals distinct capital requirements and margin structures across product formats and material substrates. Manufacturers configure production lines differently for ceramic coating application versus hard-anodized processing, creating divergent competitive moats.
Product Type:
Fry pans and cookware sets demand the heaviest coating-application infrastructure investment, while griddles and woks require specialized thermal engineering for even heat distribution.
- Fry Pans:These vessels utilize aluminum substrates with polytetrafluoroethylene or ceramic coatings applied through spray deposition or roller coating processes. Mumbai and Bangalore households are replacing legacy fry pans at accelerated rates as BIS certification awareness spreads through urban clusters.
- Cookware Sets:Multi-piece configurations combine varied vessel geometries requiring flexible production tooling and coordinated coating batch consistency. South Indian metropolitan consumers favor certified sets from organized brands over unorganized imports given FSSAI chemical migration scrutiny.
- Griddles:Flat cooking surfaces with extended thermal mass require thicker aluminum substrates and reinforced coating adhesion protocols for sustained high-heat performance.
- Woks:Curved geometries with concentrated heat zones demand specialized spinning equipment and localized coating thickness control for oil-free stir-fry applications.
Fry pans absorb the bulk of installed capacity; cookware sets are expanding most quickly.
Material:
Material selection determines coating compatibility and thermal performance ceilings, with aluminum dominating volume throughput and ceramic capturing premium positioning.
- Aluminum:Lightweight substrates with excellent thermal conductivity serve as the foundation for most polytetrafluoroethylene and ceramic coatings. CDSCO oversight of imported coating precursors creates supply continuity risks for manufacturers dependent on foreign chemical sourcing.
- Ceramic:Sol-gel derived silica-based coatings promise reduced chemical exposure compared to fluoropolymer alternatives. Health-conscious buyers in Bangalore and Chennai are adopting ceramic-finished aluminum at twice the replacement rate of traditional coatings.
- Hard Anodized:Electrochemically thickened aluminum oxide layers create uncoated cooking surfaces that capture safety-conscious consumers skeptical of synthetic coatings.
- Stainless Steel:Corrosion-resistant substrates with lower thermal conductivity require clad aluminum cores or specialized coating formulations for non-stick performance.
Aluminum substrates command the greatest production volume; ceramic coatings are climbing the fastest.
Size:
Size segmentation reflects household composition patterns and cooking frequency variations across Indian urban and semi-urban markets.
- Medium:24-28cm diameter vessels balance portion flexibility with storage efficiency for nuclear families. These dimensions dominate replacement purchases in Mumbai and Bangalore apartment kitchens.
- Large:30-32cm configurations accommodate multi-generational households and batch cooking practices prevalent in South Indian metropolitan clusters.
- Small:18-22cm vessels target single-person households and supplementary cooking tasks with lower per-unit pricing.
- Extra Large:34cm+ diameters serve commercial kitchen requirements and large-family entertaining with specialized handling features.
Medium sizes anchor current production schedules; large formats are gaining share fastest.
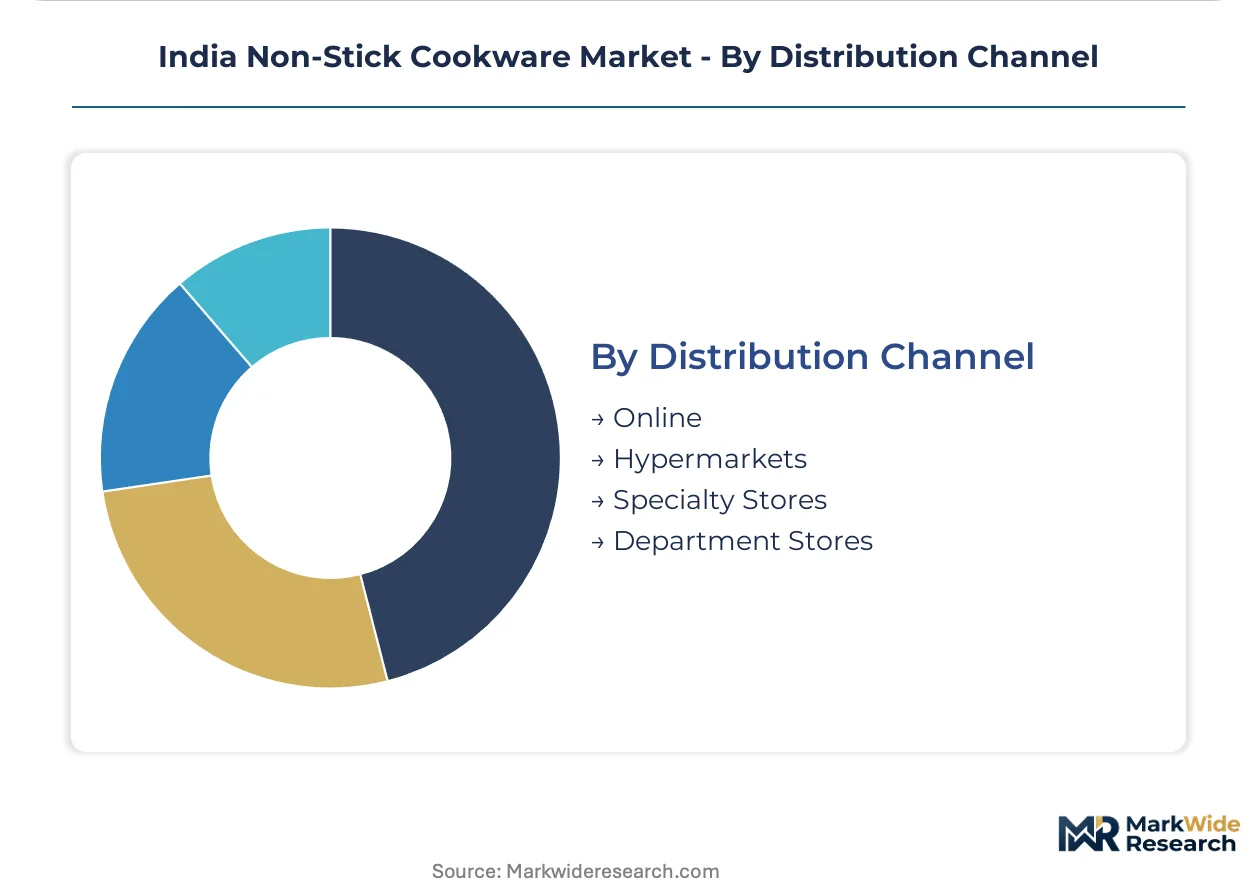
Distribution Channel:
Channel selection determines margin capture potential and customer education intensity, with digital platforms compressing traditional retail economics.
- Online:Direct-to-consumer platforms enable assisted selling through video demonstrations and subscription-based replacement programs. E-commerce logistics are deepening reach into Pune, Hyderabad, and Chennai beyond Delhi-Mumbai concentration.
- Specialty Stores:Experiential retail formats deploy live cooking demonstrations and trained staff to justify premium ceramic and hard-anodized positioning. South Indian metropolitan clusters show the highest concentration of these assisted-selling formats.
- Hypermarkets:High-volume self-service retail captures price-sensitive replacement demand with limited staff interaction and compressed margins for mid-tier brands.
- Department Stores:Curated cookware sections in urban retail formats blend transactional efficiency with moderate product education for gift purchases and upgrade occasions.
Hypermarkets currently move the greatest unit volume; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan households in Mumbai and Bangalore are driving replacement demand, while South Indian urban clusters accelerate ceramic cookware adoption. BIS certification tightening is redrawing competitive boundaries across state-level markets.
Maharashtra
Mumbai apartment kitchens favor medium-sized fry pans for nuclear family cooking. FSSAI chemical migration limits are accelerating organized brand preference over unorganized imports. Pune's deepening e-commerce logistics infrastructure is enabling direct-to-consumer ceramic cookware penetration beyond Mumbai's retail concentration.
Karnataka
Bangalore's health-conscious consumers adopt ceramic-coated aluminum at twice the replacement rate of traditional coatings. PLI scheme alignment for consumer durables is attracting capital subsidy applications for coating application infrastructure. Specialty stores with live cooking demonstrations cluster in Bangalore's urban retail corridors.
Tamil Nadu
Chennai households show elevated ceramic cookware penetration correlating with experiential retail format concentration. CDSCO oversight of imported coating precursors creates supply continuity risks for manufacturers without captive chemical sourcing. Large-format cookware sets serve multi-generational batch cooking practices prevalent in metropolitan Chennai.
Telangana
Hyderabad's underpenetrated market offers volume expansion as organized retail and e-commerce logistics deepen reach. BIS test protocol amendments require continuous laboratory reinvestment stretching compliance timelines. Hard-anodized product lines capture safety-conscious consumers skeptical of synthetic coating technology.
Delhi-NCR
Hypermarket channels currently move the greatest unit volume in the national capital region despite compressing margins for mid-tier brands. DGFT regulations on raw material imports intersect with CDSCO oversight of foreign-sourced polytetrafluoroethylene precursors. Specialty retail formats are displacing price-competitive placements through assisted selling and subscription-based replacement programs.
India Non-Stick Cookware Market Competitive Landscape
South Indian producers anchor one tier; North Indian specialists hold differentiated positions through hard-anodized and electrical appliance distribution networks. The vendor base concentrates around organized domestic brands with in-house testing infrastructure versus fragmented unorganized imports facing compliance compression. Three archetypes dominate: integrated kitchen appliance conglomerates, specialized cookware fabricators, and electrical appliance distributors extending into cookware retail. Competitive moves center on capacity expansion for ceramic coating application and strategic partnerships with e-commerce platforms for direct-to-consumer reach.
Within the integrated appliance tier, TTK Prestige leverages in-house testing infrastructure to navigate BIS standards efficiently. Hawkins Cookers Limited anchors market position through specialized hard-anodized product lines that capture safety-conscious consumers. Havells India Limited represents the electrical distribution extension archetype, competing by deploying its appliance retail network into cookware. These three exemplify how compliance capability, material specialization, and channel control define competitive positioning under tightening FSSAI and BIS frameworks.
| Leading Market Players |
|---|
| Butterfly Gandhimathi Appliances Limited |
| Vinod Cookware India Private Limited |
| TTK Prestige |
| Usha Shriram Private Limited |
| Havells India Limited |
| Stovekraft Limited |
| Nirlep Appliances Private Ltd. |
| Bhalaria Metal Craft Pvt. Ltd. |
| Hawkins Cookers Limited |
| Others |
Supply & Pricing Matrix
Captive in-house coating application infrastructure anchors both supply security and pricing power for organized domestic manufacturers navigating BIS certification tightening and CDSCO import scrutiny. This integration choice separates premium-positioned players from margin-compressed entrants dependent on foreign-sourced polytetrafluoroethylene precursors and spot-market aluminum procurement.
Pricing Analysis
Volume throughput concentrates in hypermarket channels with compressed margins, while specialty stores and online platforms capture premium pricing through assisted selling and experiential retail. Price differentiation rests on BIS certification tier and ceramic versus fluoropolymer coating grade, with certified ceramic formulations commanding substantial premiums over unorganized imports. Pricing pressure intensifies in mid-tier segments as hard-anodized uncoated alternatives capture safety-conscious defectors. Price-sensitive buyers cluster in hypermarket self-service formats, while least-sensitive consumers frequent South Indian specialty stores with live demonstration capabilities.
Supply Chain Analysis
Coating-application technician scarcity in legacy industrial hubs constrains geographic flexibility for new production facilities seeking to serve South Indian metropolitan clusters. Supply concentration centers on domestic aluminum substrate fabrication in Maharashtra and Gujarat, with ceramic sol-gel precursors and fluoropolymer chemicals drawing from China and Germany. Raw material dependencies encompass aluminum ingots, imported coating chemicals, and specialized spinning equipment for wok geometries. Single-source vulnerability pervades imported polytetrafluoroethylene precursor supply under CDSCO oversight. Distribution runs through direct-to-consumer platforms accelerating fastest, though specialty retail retains margin concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through coating-application talent scarcity and imported chemical dependency, with captive infrastructure investment propping pricing power for compliant incumbents.
For Market Incumbents: Lock in coating-application technician pipelines through apprenticeship partnerships with legacy industrial hub training institutes before geographic expansion into Pune and Hyderabad. Deepen backward integration into ceramic sol-gel formulation to reduce CDSCO import exposure. Defensive priority centers on pre-empting hard-anodized substitution through certified ceramic line extensions. For New Entrants and Emerging Players: Capture underpenetrated Tier-II city volume in Hyderabad and Chennai through e-commerce logistics partnerships before brick-and-mortar fixed-cost commitment. Most penetrable segment lies in medium-sized certified cookware sets for nuclear families replacing legacy unorganized imports. Go-to-market angle emphasizes FSSAI compliance documentation and subscription-based replacement programs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated kitchen appliance conglomerates seeking coating-application infrastructure and BIS-certified product portfolios. Long-term viability favors producers with captive chemical sourcing and in-house testing laboratories. Signal to watch: BIS test protocol amendments accelerating compliance timeline compression for non-integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | Captures health-conscious consumer pivot away from fluoropolymer surfaces in Bangalore and Chennai clusters. |
| Backward Integration into Sol-Gel Formulation | Reduces CDSCO import dependency and secures supply continuity for premium ceramic product lines. |
| Direct-to-Consumer Platform Launch | Enables margin capture through assisted selling and subscription-based replacement programs beyond hypermarket compression. |
| In-House BIS Testing Infrastructure Investment | Accelerates certification timelines and creates competitive moat against unorganized import competitors. |
| Experiential Retail Partnership in South India | Deploys live cooking demonstrations to justify premium positioning in highest ceramic penetration markets. |
Research Methodology
Multi-period observation of BIS certification timelines, coating formulation shifts, and channel mix evolution anchored the trend analysis, supplemented by interviews with product development heads at domestic cookware manufacturers, regulatory compliance officers navigating FSSAI chemical migration protocols, category buyers at organized retail chains, and procurement leads at aluminum substrate suppliers. Secondary validation drew from BIS notification records, CDSCO import clearance data, FSSAI guideline amendments, and e-commerce platform category growth disclosures. Bottom-up production capacity estimates and top-down consumption surveys were triangulated against channel shipment data.
Segment-weighting approaches modeled product type, material substrate, size configuration, and distribution channel dimensions across the analysis window. CAGRs were derived from fitted growth curves applied to replacement cycle acceleration in metropolitan clusters and ceramic formulation adoption trajectories. Industry-specific forecast inputs encompassed urban household disposable income projections and PLI scheme subsidy uptake rates for consumer durables manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS test protocol amendment timing and aluminum commodity price volatility. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and coating chemical import clearance velocity. Material deviation in BIS certification stringency or CDSCO import restriction scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Jet Hand Dryer Market
Household Items
Snow Blower Market
Household Items
Drain Cleaners Market
Household Items
Insulated Lunch Box Market
Household Items
Smart Spin Mop Market
Household Items
Steam Cleaners Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Heated Mattress Pads Market
Household Items
Car Air Freshener Market
Household Items
Global Rimless Toilets Market
Household Items
Garbage Disposals Market
Household Items
Fine Mist Sprayer Market
Household Items
Indoor Humidifier Market