
 Global Airport Snow Removal Vehicles and Equipment Market | 2026-2036
Global Airport Snow Removal Vehicles and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airport Snow Removal Vehicles and Equipment Market Foresight
Ground handling firms are rotating into the dominant buyer archetype as airport authorities outsource winter operations to specialized contractors. Oshkosh Corporation leverages its military-derived chassis expertise to anchor the high-capacity blower segment. Aebi Schmidt Holding AG sustains European market presence through integrated spreader-plow systems. Boschung Holding AG differentiates via autonomous runway condition monitoring tied to equipment dispatch.
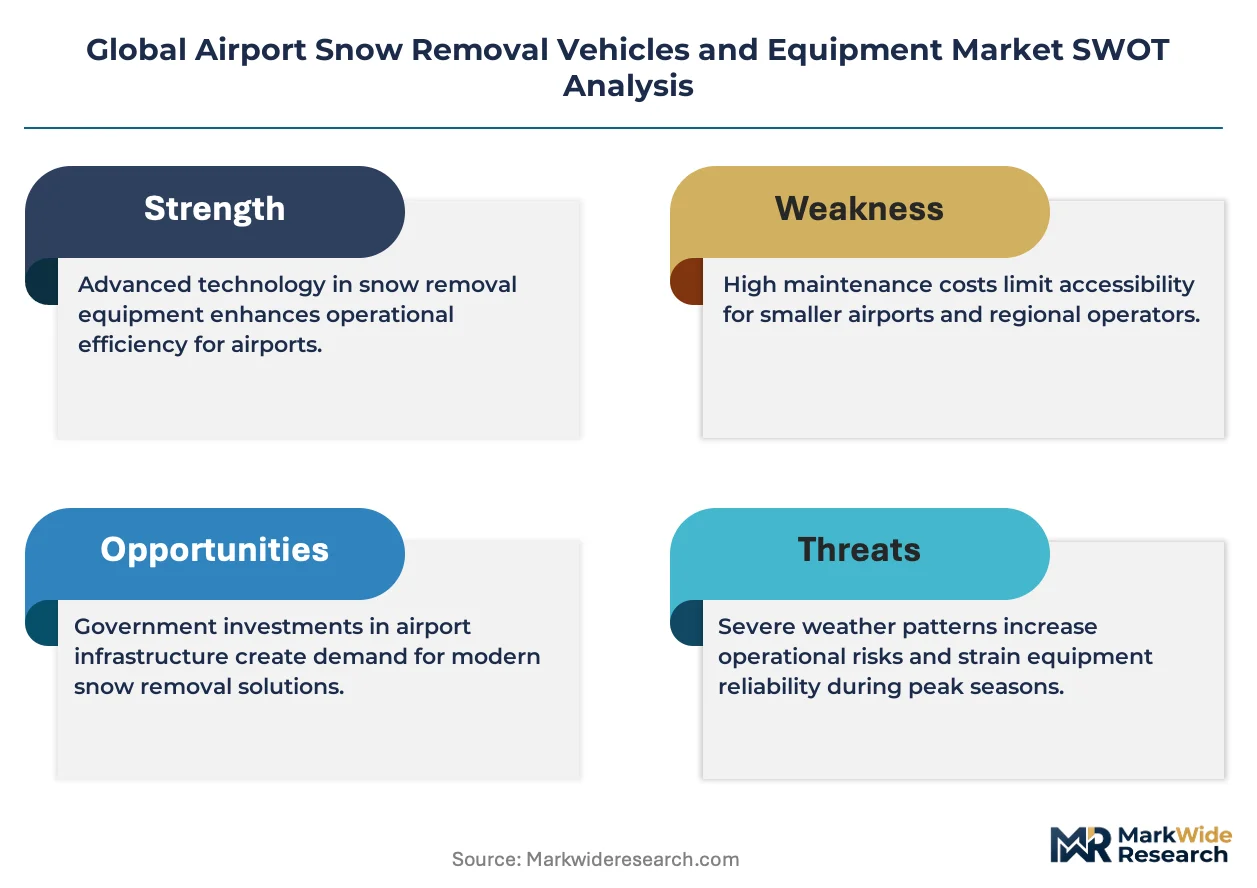
Airport snow removal vehicles and equipment encompasses purpose-built machines engineered to maintain airfield pavement friction coefficients above operational minimums, typically featuring high-horsepower diesel or hybrid drivetrains, corrosion-resistant alloys, and FAA-compliant lighting packages for 24-hour visibility. Rotary blowers and multi-functional loaders command premium positioning due to their throughput advantages on wide-body gate positions and crosswind runways. Deicing trucks represent a mature margin pool where fleet replacement cycles now favor electric and hybrid technology variants.
FAA airfield maintenance standards, EASA certification requirements for winter operations, and ISO 11001 surface condition reporting protocols collectively mandate documented equipment capability thresholds and operator training benchmarks. These frameworks shape procurement specifications and create compliance-driven replacement demand across regulated airports. Stakeholders must monitor evolving emissions standards and electrification readiness as regulatory timelines compress for ground support equipment.
Market Dynamics
Outsourced winter operations are compressing procurement authority into ground handling firms, who now specify integrated spreader-blower fleets rather than single-function units. This buyer consolidation is forcing OEMs to bundle training, telemetry, and maintenance into capital contracts.
Growth Catalysts
- FAA Runway Condition Assessment Matrix:Mandated friction coefficient documentation drives replacement of legacy plows with sensor-equipped blowers. US hub airports face certification deadlines that accelerate capital deployment.
- Hybrid-electric drivetrains:Airport authorities in Germany and Switzerland specify CO2-reduced ground support equipment. EASA emissions guidelines for apron vehicles extend to snow removal fleets.
- Crosswind runway throughput:High-capacity rotary blowers reduce closure duration during active precipitation. Ground handlers at Minneapolis-St. Paul and Denver International prioritize machines clearing 2,500+ tons per hour.
Market Restraints
- Specialized steel alloy costs:Corrosion-resistant chassis materials face price volatility from nickel and molybdenum supply concentration in Russia and Indonesia.
- Single-source component risk:Precision snow depth sensors rely on German and Japanese optical manufacturers, creating vulnerability to export control disruptions.
- Extended replacement cycles:Diesel-powered units from the 2010s remain serviceable, delaying fleet turnover despite efficiency gaps with hybrid alternatives.
Strategic Opportunities
- Nordic secondary airports:Norway and Finland maintain hundreds of regional strips with aging equipment. Procurement budgets are expanding under national climate adaptation funds.
- Autonomous runway patrol integration:Boschung and competitors converge LiDAR mapping with automated blower dispatch. This reduces labor costs for overnight surface monitoring.
- India's Greenfield airport construction:Noida International and Navi Mumbai specify modern winter capability despite mild climates, anticipating climate volatility and ICAO compliance.
Industry Challenges
- Certified operator scarcity:FAA-mandated airfield driver training programs face instructor bottlenecks. Ground handlers struggle to staff 24-hour winter operations.
- Legacy fleet telemetry incompatibility:Older blowers lack CAN bus interfaces for fleet management platforms. Retrofit costs erode ROI on connected maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airport Snow Removal Vehicles and Equipment Market |
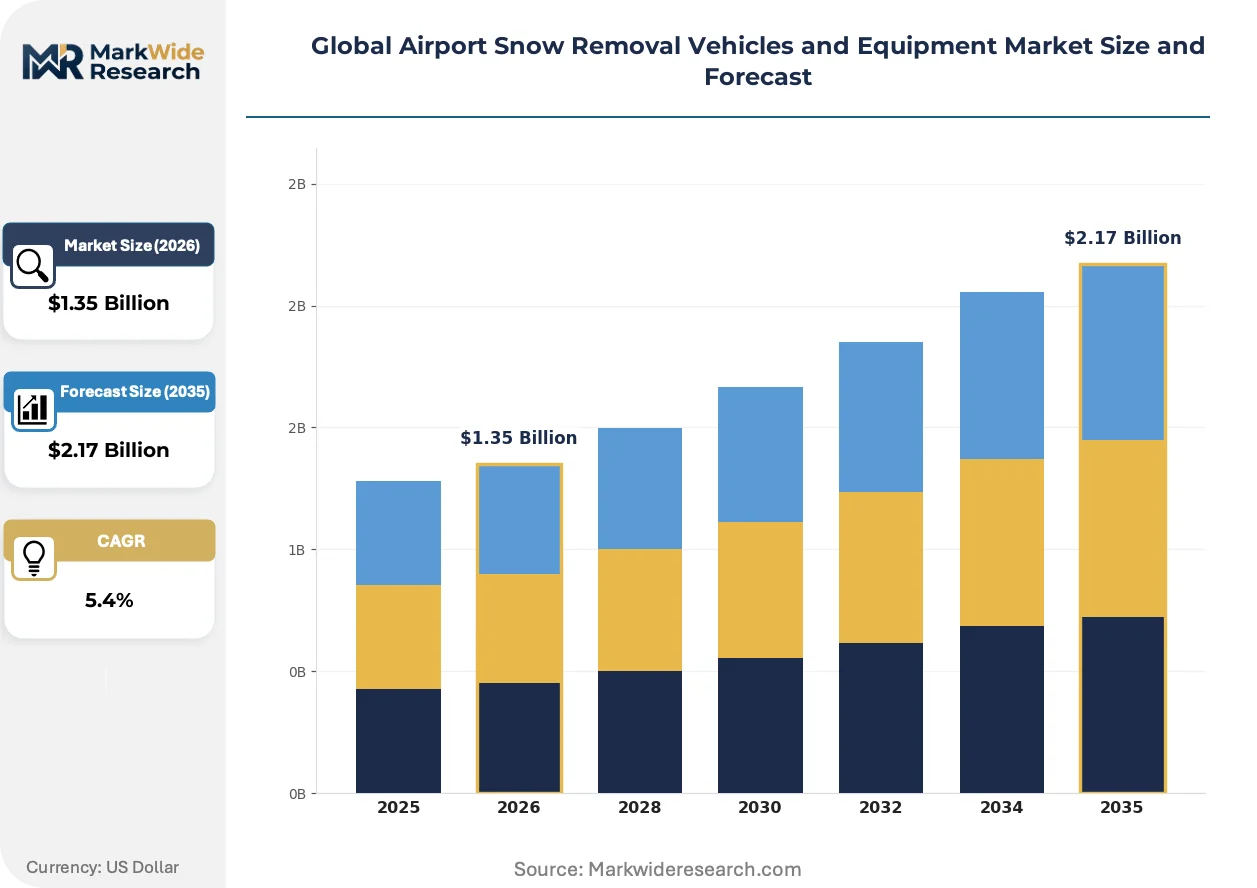
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snow Plows, Rotary Blowers, Sweepers, Deicing Trucks, Multi-Functional Loaders Technology: Hydraulic, Pneumatic, Electric, Diesel Engine, Hybrid Application: Runway Clearing, Taxiway Maintenance, Apron Snow Removal, Deicing Operations, Emergency Snow Management End User: Airport Authorities, Ground Handling Firms, Aviation Service Providers, Facility Management Companies |
| Companies Covered | Alamo Group Inc., Oshkosh Corporation, Aebi Schmidt Holding AG, Boschung Holding AG, M-B Companies Inc., Team Eagle Ltd., Kodiak America LLC, Dulevo International S.p.A., Bucher Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airport Snow Removal Vehicles and Equipment Market Shifts & Advancements
Electrification and autonomous surface monitoring are converging to redefine fleet specifications, while regulatory pressure on emissions and friction reporting accelerates obsolescence of mechanical-only systems.
Hybrid-electric blower drivetrains are supplanting conventional diesel architectures in new procurements. Ground handlers at Amsterdam Schiphol and Zurich Airport specify 30-50% electric range for apron maneuvering. This shift compresses maintenance intervals and enables overnight charging during low-activity periods.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of deicing fluids and corrosion-resistant coatings. Equipment manufacturers must validate alternative surface treatments for salt-exposed undercarriages. European OEMs face compressed certification timelines as ECHA substance evaluations proceed.
Performance-based service contracts now dominate procurement at major US hubs. Fixed annual fees for guaranteed runway availability replace capital purchases and hourly labor billing. This model concentrates at Denver, Chicago O'Hare, and Boston Logan, where snow event frequency justifies risk transfer to specialized contractors.
Global Airport Snow Removal Vehicles and Equipment Market Segmentation
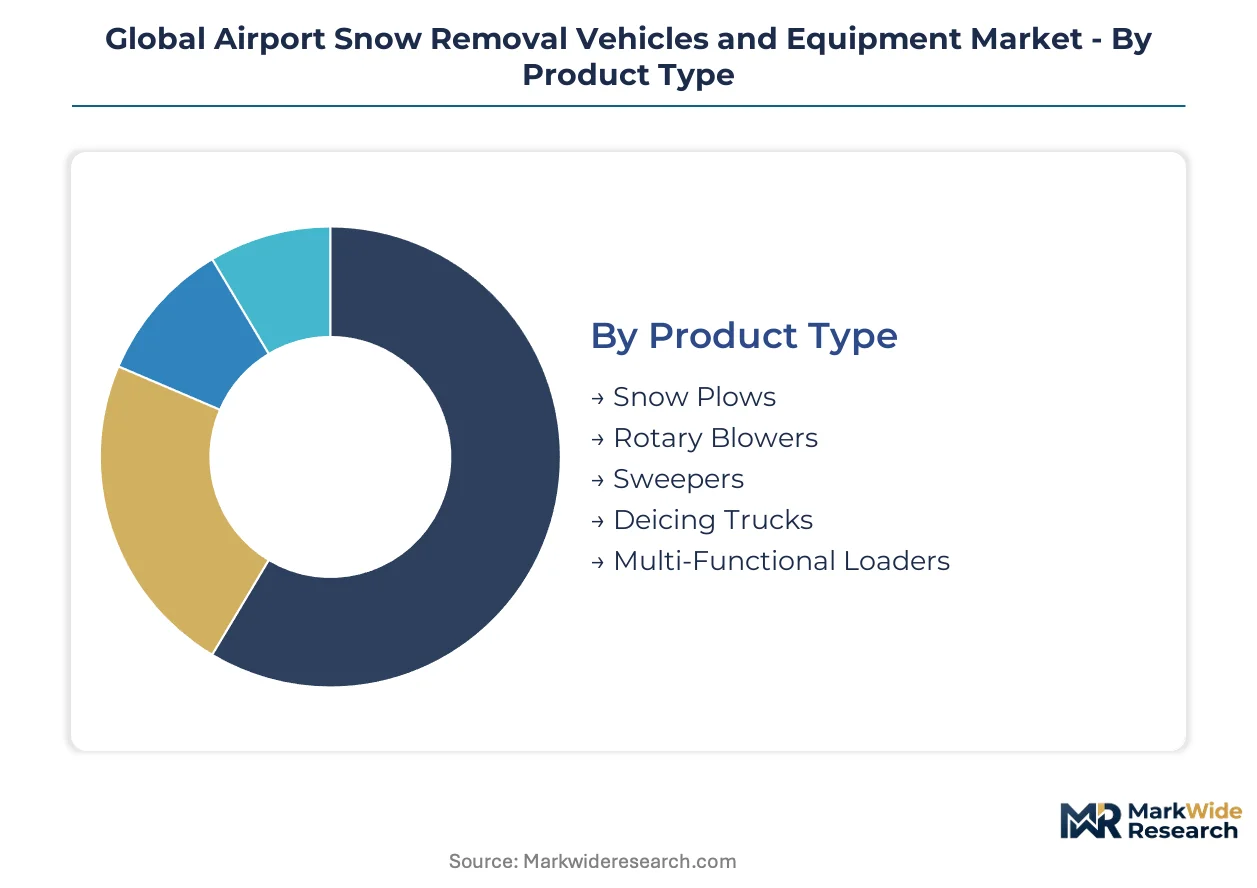
Segmentation in airport snow removal equipment reveals how procurement authority, operational requirements, and technology readiness diverge across buyer types and use cases. Ground handlers prioritize throughput metrics while airport authorities emphasize regulatory compliance and fleet standardization.
Product Type:
Equipment flows through distinct procurement channels: rotary blowers and multi-functional loaders move through ground handler fleet modernization contracts, while deicing trucks and sweepers often route through airport authority capital programs.
- Rotary Blowers:High-capacity machines engineered for rapid clearance of wide-body gate positions and crosswind runways. Demand concentrates at Minneapolis-St. Paul and Denver International, where ground handlers specify 2,500+ ton-per-hour throughput to minimize closure duration during active precipitation.
- Multi-Functional Loaders:Integrated spreader-plow systems with modular attachments for variable snow conditions. European ground handling firms at Zurich and Amsterdam Schiphol favor these units for apron maneuverability and reduced fleet footprint.
- Snow Plows:Conventional blade systems for primary runway clearance at secondary airports with budget constraints.
- Sweepers:Post-clearance surface preparation equipment for friction coefficient restoration.
- Deicing Trucks:Purpose-built fluid application vehicles with heated tanks and precision booms for aircraft treatment.
By volume, snow plows lead due to legacy fleet prevalence. By growth pace, rotary blowers are expanding most quickly as FAA friction reporting mandates accelerate replacement cycles.
Technology:
Cost tiers separate the technology landscape: diesel remains the economy baseline, hybrid commands mid-tier positioning with 30-50% electric range specifications, and full electric occupies premium procurement at sustainability-focused hubs.
- Hybrid:Dual-mode drivetrains enabling overnight charging during low-activity periods and diesel range extension for extended events. German and Swiss airport authorities specify these systems under EASA emissions guidelines for apron vehicles.
- Electric:Battery-electric architectures with zero tailpipe emissions for apron maneuvering and short-clearance operations. Oslo Airport and Stockholm Arlanda lead procurement as Nordic climate adaptation funds expand.
- Diesel Engine:Conventional high-horsepower systems dominating legacy fleets from the 2010s with extended service intervals delaying turnover.
- Hydraulic:Fluid power systems for blade and blower actuation in heavy-duty applications.
- Pneumatic:Compressed air systems for specialized deicing fluid distribution and control surfaces.
By installed base, diesel engine technology leads. By procurement momentum, hybrid systems are gaining share fastest as ground handlers balance emissions compliance with operational reliability.
Application:
Volume concentration varies by operational criticality: runway clearing commands capital intensity per event, while apron snow removal generates recurring service contract value through performance-based availability guarantees.
- Runway Clearing:Friction-critical pavement maintenance requiring FAA-compliant equipment with sensor integration for surface condition assessment matrix documentation. US hub airports face certification deadlines accelerating capital deployment.
- Deicing Operations:Aircraft anti-icing and deicing fluid application with REACH-mandated PFAS reformulation driving equipment coating validation requirements.
- Taxiway Maintenance:Secondary pavement clearance with lower throughput requirements than primary runways.
- Apron Snow Removal:Gate position and stand clearance for aircraft maneuvering safety.
- Emergency Snow Management:Rapid deployment protocols for unforecasted precipitation events.
By operational priority, runway clearing leads capital allocation. By contract innovation, deicing operations show the steepest expansion trajectory as performance-based service models replace hourly billing.
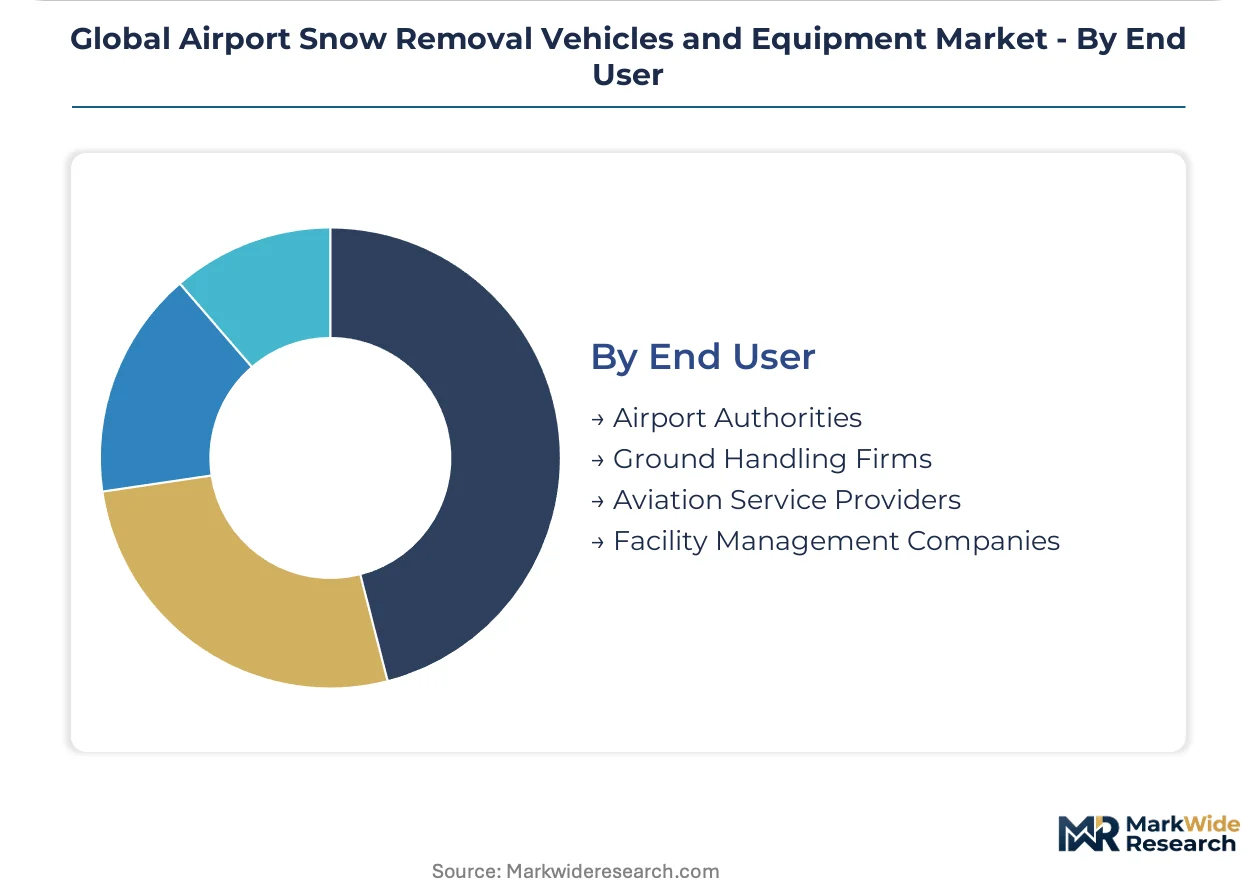
End User:
Customer type determines specification authority: airport authorities retain compliance-driven procurement for runway systems, while ground handling firms now dominate fleet decisions for integrated spreader-blower deployments.
- Ground Handling Firms:Specialized contractors now specifying integrated fleets with bundled training, telemetry, and maintenance contracts. These buyers concentrate at Denver, Chicago O'Hare, and Boston Logan where snow event frequency justifies risk transfer.
- Airport Authorities:Regulatory-focused procurement for runway condition reporting compliance and standardization across multi-hub networks.
- Aviation Service Providers:Niche operators supporting regional strips and private aviation facilities.
- Facility Management Companies:Integrated service contractors expanding into winter operations through acquisition.
By procurement volume, ground handling firms now lead. By contract value concentration, airport authorities remain ahead for single-event capital deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ground handling firms concentrate procurement authority across four distinct national markets, each shaped by unique regulatory timelines and climate exposure patterns. FAA certification deadlines in the United States, EASA emissions protocols in Germany, and Nordic adaptation funds in Norway and Finland collectively determine equipment deployment trajectories.
United States
Denver International and Minneapolis-St. Paul anchor North American demand for high-capacity rotary blowers. FAA Runway Condition Assessment Matrix deadlines compel hub airports to retire legacy plows before the 2026 certification window. Ground handlers at Chicago O'Hare and Boston Logan now specify integrated spreader-blower fleets with bundled telemetry contracts.
Germany
Amsterdam Schiphol and Frankfurt Airport procurement patterns influence German ground handling specifications. EASA emissions guidelines for apron vehicles extend to snow removal fleets, driving hybrid-electric drivetrain adoption. Munich and Zurich-based handlers prioritize 30-50% electric range for overnight charging compatibility.
Norway
Secondary regional strips across Troms and Finnmark operate aging equipment from the 2000s. National climate adaptation funds expand procurement budgets for autonomous runway patrol integration. Avinor-operated airports in Bodø and Alta test LiDAR-enabled surface monitoring tied to automated blower dispatch.
Finland
Helsinki-Vantaa and Oulu Airport maintain extensive snow removal fleets for extreme winter throughput requirements. Finnish Transport Infrastructure Agency grants prioritize electrification of ground support equipment at state-owned facilities. Lapland regional strips near Rovaniemi face replacement pressure as Arctic precipitation patterns intensify.
India
Noida International and Navi Mumbai greenfield projects specify modern winter capability despite historically mild climates. Airport Authority of India mandates ICAO-compliant surface condition reporting infrastructure for all new facilities. Delhi-Indira Gandhi and Bengaluru Kempegowda evaluate climate volatility contingencies in master planning documents.
Global Airport Snow Removal Vehicles and Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with chassis manufacturing heritage, supplemented by specialized surface treatment technology firms and regional ground support equipment fabricators. Market structure exhibits moderate consolidation around multi-product portfolio holders capable of bundling blowers, spreaders, and telemetry platforms. Two strategic archetypes dominate: military-derived chassis specialists leveraging armor-grade alloy expertise, and integrated environmental technology providers converging snow removal with autonomous surface monitoring. Competitive dynamics center on vertical integration into sensor manufacturing and performance-based service contract structuring.
Within the military-chassis tier, Oshkosh Corporation and Alamo Group Inc. occupy positions reflecting defense contractor heritage applied to airfield applications. Aebi Schmidt Holding AG represents the European integrated-systems archetype, while Boschung Holding AG anchors the autonomous monitoring convergence. Among specialized fabricators, M-B Companies Inc. and Team Eagle Ltd. exemplify North American regional equipment production. Bucher Industries AG and Dulevo International S.p.A. sit within the municipal-industrial crossover segment, with Kodiak America LLC reflecting focused ground support specialization.
| Leading Market Players |
|---|
| Alamo Group Inc. |
| Oshkosh Corporation |
| Aebi Schmidt Holding AG |
| Boschung Holding AG |
| M-B Companies Inc. |
| Team Eagle Ltd. |
| Kodiak America LLC |
| Dulevo International S.p.A. |
| Bucher Industries AG |
| Others |
Supply & Pricing Matrix
FAA airfield maintenance standards and EASA winter operations certification simultaneously gate supplier qualification and stratify pricing tiers, creating a dual-filter where only chassis manufacturers with military-grade alloy expertise command premium positioning while regional fabricators compete on spot availability.
Pricing Analysis
Cost-plus contracts with steel indexation dominate capital equipment procurement, with nickel and molybdenum volatility passed through to ground handling firms. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated blowers from mechanical-only units from refurbished legacy fleets. Cost compression in the standard tier is intensifying because Indonesian nickel supply concentration exposes OEMs to input volatility. Regional airports in Norway and Finland show highest price sensitivity, while US hub authorities prioritize guaranteed runway availability over unit economics.
Supply Chain Analysis
Inventory cycles stretch 18-24 months for precision snow depth sensors, compressing to 8-12 weeks for hydraulic actuators. Manufacturing concentrates in Germany, the United States, and Switzerland for optical sensor modules, with chassis fabrication anchored in Wisconsin and Baden-Württemberg. Supply chains draw from Russian and Indonesian nickel deposits, Japanese optical components, and German precision hydraulics. Single-source vulnerability runs through LiDAR mapping arrays sourced from Bavarian and Osaka manufacturers. Distribution runs through ground handler fleet modernization contracts rather than dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified airfield equipment operators now represent the binding constraint across North American and European winter operations, with FAA-mandated training programs facing instructor bottlenecks that limit fleet deployment velocity regardless of equipment availability.
For Market Incumbents: Compound telemetry integration capabilities through in-house production of CAN bus interfaces and fleet management platforms, defending against emerging autonomous monitoring specialists. Lock in multi-year performance-based service contracts at Denver and Chicago O'Hare before certification deadlines consolidate procurement authority. Prioritize backward integration into corrosion-resistant coating formulation as REACH restrictions on PFAS compounds accelerate. For New Entrants and Emerging Players: Lead with electrification retrofit kits for legacy diesel blowers lacking CAN bus architecture, targeting Nordic secondary airports with climate adaptation fund eligibility. White-space concentration sits in autonomous runway patrol systems converging LiDAR with automated dispatch, where Boschung's early positioning has not yet saturated Avinor's procurement pipeline. Pursue certification partnerships with FAA-approved training providers to bypass operator scarcity bottlenecks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid-electric drivetrain development, favoring scaled manufacturers with captive battery supply agreements over specialized fabricators. Long-term viability through the next decade rests on vertical integration into sensor manufacturing and telemetry platforms rather than chassis production alone. Acquisition target archetype: mid-cap European OEMs with EASA certification depth and underutilized production capacity. The signal to watch is ground handler consolidation into transnational contracts with bundled maintenance obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of snow depth sensors insulates against German and Japanese export control disruptions. |
| Performance-Based Service Contract Expansion | Fixed annual fees for runway availability transfer weather risk from Denver authorities to specialized contractors. |
| Hybrid-Electric Drivetrain Certification | EASA emissions guidelines for apron vehicles extend eligibility to snow removal fleets at Zurich and Amsterdam Schiphol. |
| Autonomous Runway Patrol Integration | LiDAR-enabled surface monitoring reduces overnight labor costs at Avinor-operated airports in Bodø and Alta. |
| PFAS-Free Coating Validation | REACH-compliant surface treatments secure European market access as ECHA substance evaluations proceed. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with ground handling fleet managers, airport authority procurement officers, FAA-certified training instructors, and OEM aftermarket service heads; and secondary validation through FAA airfield maintenance directives, EASA winter operations certification databases, SEC filings from publicly traded chassis manufacturers, and customs records for corrosion-resistant alloy imports. Bottom-up equipment deployment counts triangulated against top-down airport capital expenditure budgets.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type, technology tier, application criticality, and end-user procurement authority. CAGRs were derived from replacement cycle analysis, regulatory deadline clustering, and fleet modernization pipeline visibility. Forecast inputs included FAA certification timeline compliance rates, EASA emissions guideline adoption curves, and Nordic climate adaptation fund disbursement patterns.
Forecasts assume regulatory continuity in FAA airfield maintenance standards and EASA winter operations protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Jackhammer Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Press Brakes Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
India Crane Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Construction Equipment Market