
 Latin America General Aviation Market | 2026-2036
Latin America General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America General Aviation Market Foresight
Market Context
Shortages of certified airframe and powerplant mechanics are redrawing competitive boundaries across Latin America's general aviation sector. Embraer SA leverages its São Paulo manufacturing base to sustain regional supply chain advantages in light jet production. Textron Inc. competes through extensive service center networks that anchor aftermarket revenue streams across Mexico and Brazil. Leonardo S.p.A. specializes in rotorcraft configurations that dominate offshore energy transport contracts in the Gulf of Mexico.
Technical Definition and Segment Structure
Latin America general aviation encompasses all civil aircraft operations excluding scheduled commercial airlines, typically involving fixed-wing aircraft under 19 passenger seats, rotorcraft, and unmanned aerial vehicles used for private transport, cargo, surveillance, and specialized missions. These platforms employ piston or turbine propulsion systems with maximum takeoff weights ranging from light sport categories below 600 kg to super-midsize business jets approaching 18,000 kg, serving industrial connectivity needs across remote infrastructure corridors. Fixed-wing aircraft and business jets command the dominant revenue share where mature replacement cycles and pre-owned import flows define transaction liquidity. Agricultural aviation and emergency medical services represent the fastest-growing application segments as Brazilian agribusiness operators adopt aerial application fleets and Mexican healthcare networks expand air ambulance coverage into mountainous terrain.
Regulatory Environment and Outlook
ANAC in Brazil, DGAC in Mexico, and the FAA through bilateral agreements collectively govern type certification, airworthiness directives, and pilot licensing standards that shape fleet import eligibility and operational authorization timelines. EASA-aligned design standards and ICAO Annex 8 compliance requirements influence manufacturer market access decisions and product specification priorities for Latin American deliveries. Stakeholders must monitor evolving emissions disclosure obligations and sustainable aviation fuel blending mandates that will reshape operating cost structures and equipment financing terms.
Market Dynamics
Fractional ownership models are compressing traditional aircraft sales cycles across Brazil and Mexico, forcing manufacturers to reconfigure revenue recognition around flight-hour subscriptions rather than asset transfers.
Growth Catalysts
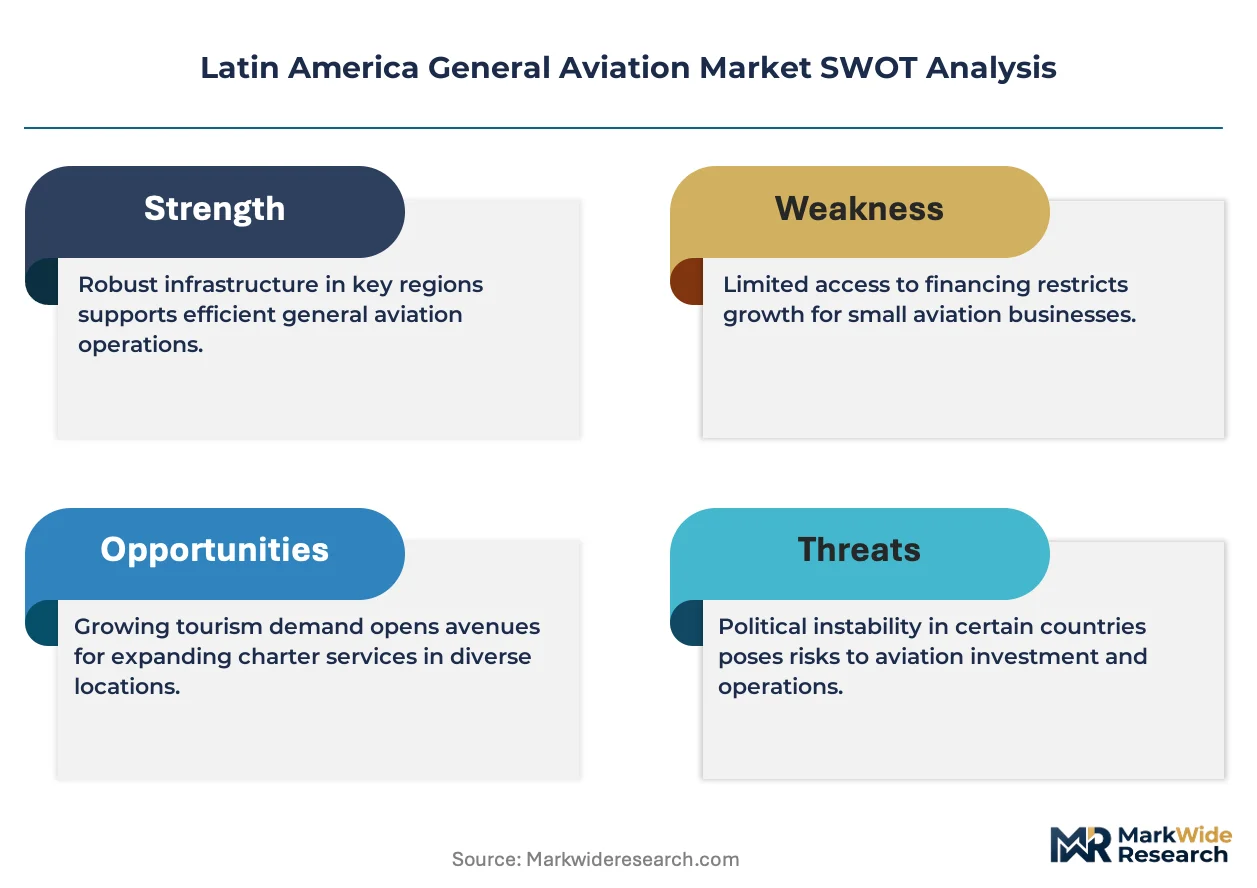
- ICAO Annex 8 Harmonization:Unified airworthiness standards across ANAC and DGAC jurisdictions are streamlining cross-border aircraft registration and reducing type certification duplication costs for importers.
- Aerial Application Expansion:Brazilian soybean and sugarcane operators are scaling turbine-powered spray fleets to cover expanding plantation footprints in Mato Grosso and Goiás.
- Offshore Energy Logistics:Leonardo rotorcraft configurations are securing multi-year crew transport contracts with Pemex and Petrobras for Gulf of Mexico platform access.
Market Restraints
- Aviation Turbine Fuel Volatility:Jet-A price swings tied to refined product import dependencies in Brazil and Mexico are compressing operating margins for flight departments and charter operators.
- Powerplant Mechanic Scarcity:Certified A&P technician pipelines in São Paulo and Mexico City cannot match fleet expansion rates, extending maintenance turnaround times.
- Used Aircraft Import Friction:DGAC and ANAC airworthiness directive harmonization gaps are delaying pre-owned business jet entry-into-service timelines.
Strategic Opportunities
- Amazon Basin Connectivity:Unpaved airstrip infrastructure in Rondônia and Acre is creating demand for ruggedized turboprop configurations serving mining and agribusiness outposts.
- Sustainable Aviation Fuel Certification:ANAC's emerging SAF blending mandate frameworks are positioning early-adopter FBOs to capture premium pricing from corporate flight departments.
- Helicopter Emergency Medical Services:Mexican healthcare network expansion into Oaxaca and Chiapas mountain corridors is driving twin-engine IFR rotorcraft procurement.
Industry Challenges
- Airworthiness Inspector Capacity:ANAC's reduced field office staffing is extending annual inspection scheduling windows for Part 135 operators in Brazil's interior states.
- Avionics Retrofit Integration:Legacy Garmin and Collins Pro Line systems require costly STC modifications to meet ADS-B Out mandates across aging imported fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America General Aviation Market |
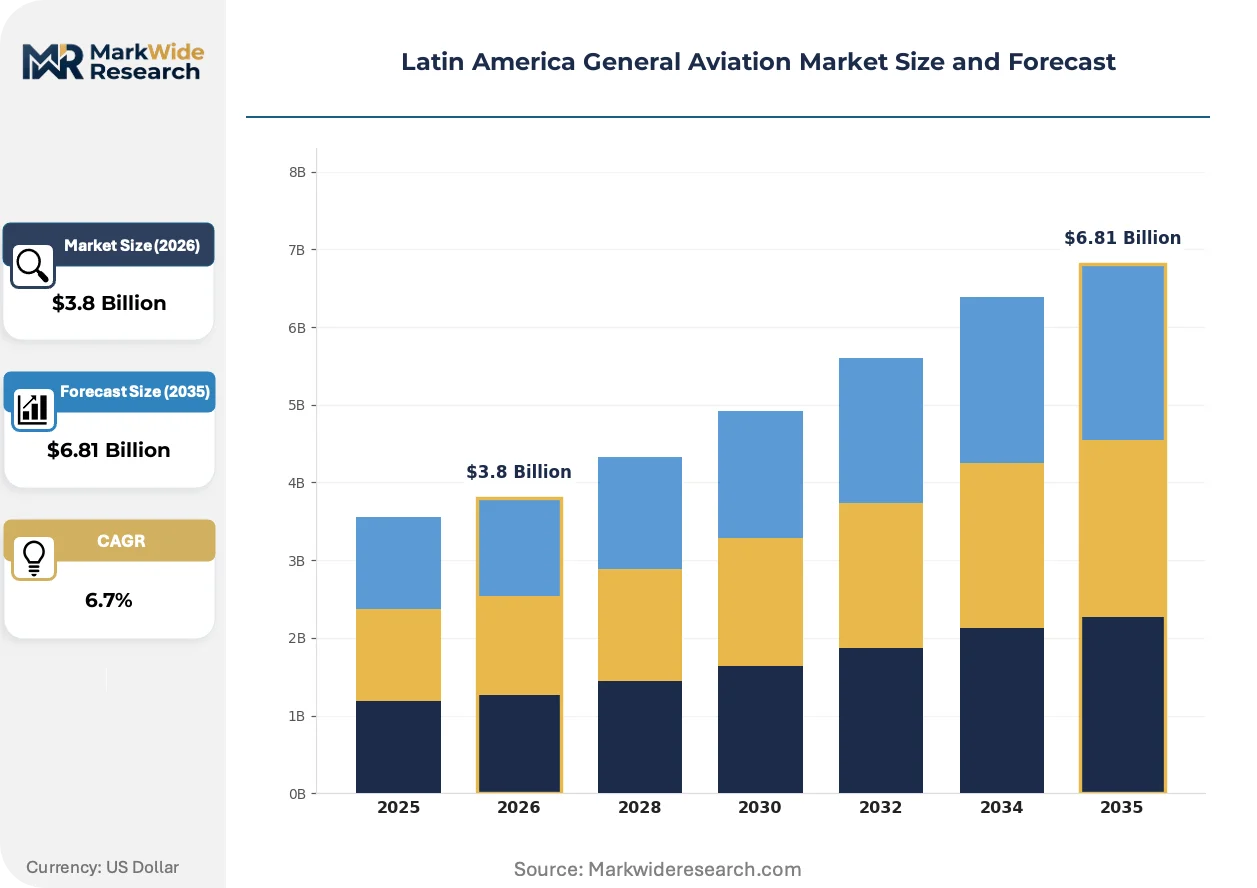
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fixed-Wing, Rotorcraft, UAV, Business Jets Application: Aerial Surveying, Private Travel, Emergency Medical Services, Agricultural Aviation End User: Private Owners, Corporations, Government, Flight Schools Service Type: Charter Services, Maintenance, Pilot Training, Leasing |
| Companies Covered | Bombardier Inc., Leonardo S.p.A., Embraer SA, Pilatus Aircraft, Dassault Aviation SA, Textron Inc., Honda Aircraft Company, Piper Aircraft Inc., Gulfstream Aerospace Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America General Aviation Market Shifts & Advancements
Digital flight operations platforms are compressing dispatcher-to-pilot communication loops while reshaping how charter brokers source aircraft availability across fragmented Latin American FBO networks.
Advanced air mobility propulsion architectures are fragmenting established supply chain relationships as Brazilian urban air mobility ventures evaluate hybrid-electric versus hydrogen fuel cell configurations for São Paulo metropolitan routes. Energy majors including Shell and BP are piloting localized SAF production partnerships with sugarcane ethanol refiners to secure feedstock advantages. Regulatory uncertainty around eVTOL pilot certification timelines under ANAC is delaying infrastructure investment commitments from vertiport developers.
ANAC's alignment with ICAO carbon offsetting and reduction schemes is mandating emissions disclosure protocols that reshape equipment financing terms for business jet acquisitions. Lenders are incorporating projected carbon credit liabilities into loan covenants and residual value calculations. Corporate flight departments in São Paulo and Rio de Janeiro are responding by prioritizing newer-generation airframes with reduced fuel burn profiles.
Subscription-based aircraft access models are displacing traditional whole-aircraft ownership among Mexican manufacturing executives and Brazilian private equity principals. NetJets and local competitors are capturing demand from buyers who previously acquired pre-owned light jets directly. This shift concentrates fleet management expertise with specialized operators while reducing direct OEM sales volumes in the entry-level business jet segment.
Latin America General Aviation Market Segmentation
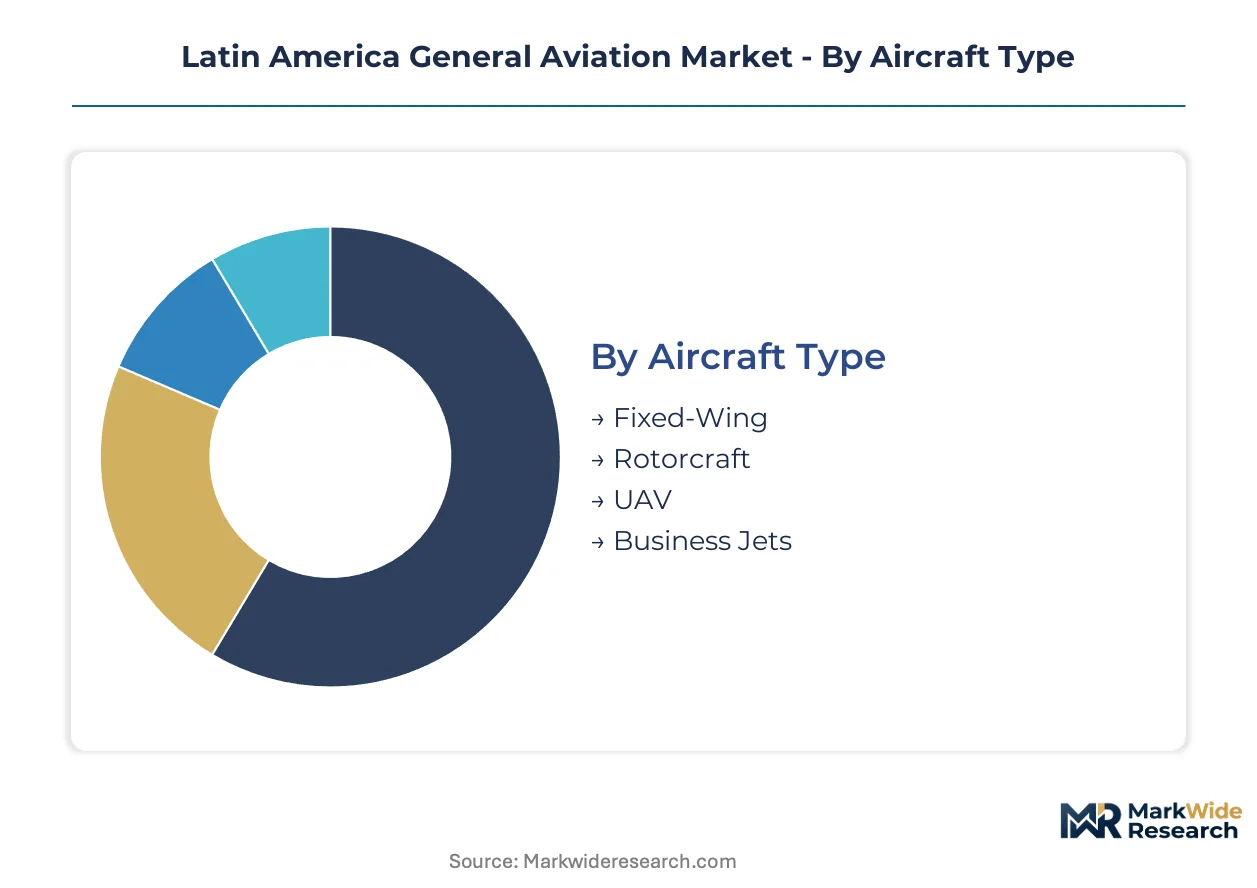
Segmentation in Latin American general aviation reveals how substitution pressures from commercial aviation and surface transport reshape equipment procurement priorities across distinct operational profiles. Understanding these boundaries clarifies where fractional ownership models displace traditional asset purchases and where regulatory harmonization unlocks cross-border fleet mobility.
Aircraft Type:
Substitution pressure from commercial airline connectivity improvements weighs most heavily on light fixed-wing configurations, while rotorcraft and business jets defend irreplaceable mission profiles across remote infrastructure corridors.
- Fixed-Wing:Piston and turboprop platforms under 19 seats dominate agricultural spraying, cargo feeder routes, and unpaved airstrip operations across Brazil's interior states. São Paulo-based flight departments favor these configurations for their lower operating economics on short-haul corporate shuttles to mining and agribusiness sites in Mato Grosso.
- Business Jets:Light to super-midsize turbine aircraft serve time-sensitive executive transport between São Paulo, Mexico City, and regional financial centers. Fractional ownership programs are compressing direct sales cycles as NetJets and local competitors capture demand from private equity principals who previously acquired pre-owned assets outright.
- Rotorcraft:Leonardo and Bell configurations secure multi-year crew transport contracts with Pemex and Petrobras for Gulf of Mexico platform access.
- UAV:Unmanned platforms are displacing manned aircraft for pipeline surveillance and precision agriculture mapping across Brazilian soybean plantations.
Fixed-Wing anchors the volume base while UAV gains share at the steepest rate.
Application:
Cost tier differentiation separates capital-intensive emergency medical infrastructure from variable-cost agricultural operations that track commodity price cycles.
- Agricultural Aviation:Turbine-powered spray fleets cover expanding soybean and sugarcane footprints in Mato Grosso and Goiás. Brazilian agribusiness operators are scaling aerial application capacity faster than ground-based mechanized alternatives can match across vast plantation geometries.
- Emergency Medical Services:Twin-engine IFR rotorcraft configurations serve Mexican healthcare network expansion into Oaxaca and Chiapas mountain corridors where road access fails during monsoon seasons. ANAC and DGAC certification harmonization is streamlining cross-border air ambulance dispatch protocols.
- Private Travel:Corporate flight departments in Brazil's southeastern corridor manage fleet renewal cycles around São Paulo and Rio de Janeiro connectivity needs.
- Aerial Surveying:LiDAR-equipped fixed-wing and UAV platforms support mining concession mapping across the Amazon Basin.
Agricultural Aviation commands the largest equipment installed base while Emergency Medical Services climbs the fastest on healthcare infrastructure investment.
End User:
Customer type determines financing structure sophistication, with corporations accessing operating leases unavailable to individual private owners.
- Corporations:Flight departments across Brazilian manufacturing and Mexican energy sectors structure fleet acquisitions through managed services contracts rather than balance-sheet ownership. Subscription-based access models are displacing whole-aircraft purchases among executives prioritizing capital efficiency.
- Private Owners:High-net-worth individuals in São Paulo and Rio de Janeiro concentrate demand for pre-owned light jet imports, though DGAC and ANAC airworthiness directive gaps delay entry-into-service timelines.
- Government:Federal and state agencies procure rotorcraft for border surveillance and disaster response across remote territories.
- Flight Schools:Training operators in Mexico City and São Paulo face powerplant mechanic scarcity that extends maintenance turnaround times for training fleet availability.
Corporations anchor equipment demand volume while Flight Schools expand most quickly on pilot certification pipeline pressures.
Service Type:
Geographic concentration of MRO infrastructure in São Paulo and Mexico City shapes where maintenance revenue pools relative to dispersed charter operations.
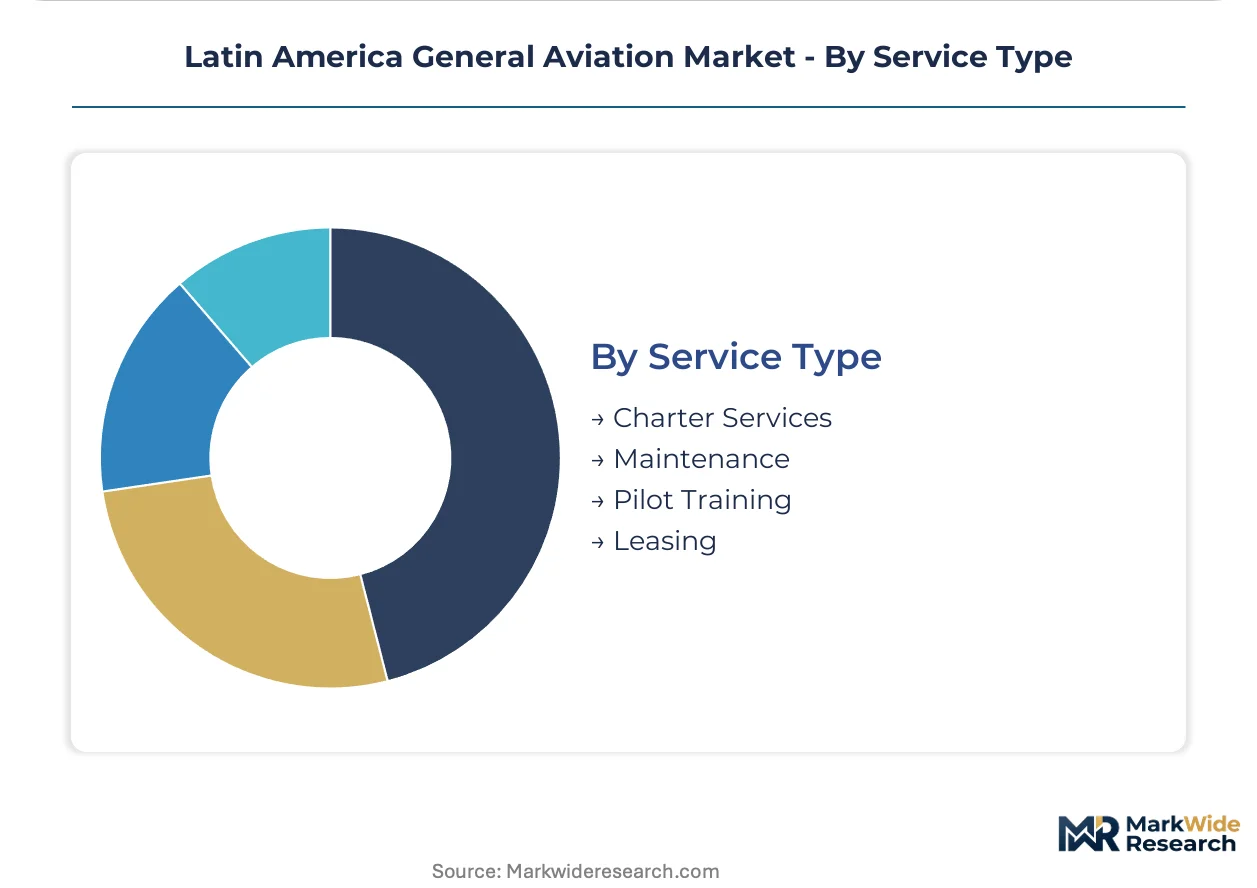
- Charter Services:Digital flight operations platforms compress dispatcher-to-pilot communication loops while fragmented FBO networks across Latin America complicate real-time aircraft sourcing. Brokers are consolidating around platforms that aggregate availability across Brazil and Mexico rather than single-country operators.
- Maintenance:Certified airframe and powerplant mechanic shortages redraw competitive boundaries, with Textron's service center networks anchoring aftermarket revenue streams. ANAC's reduced field office staffing extends annual inspection scheduling windows for Part 135 operators in Brazil's interior states.
- Pilot Training:Simulator-based instruction expands as airlines recruit from general aviation certificate pipelines.
- Leasing:Operating lease structures gain traction among corporate flight departments seeking off-balance-sheet treatment for business jet acquisitions.
Maintenance anchors service revenue concentration while Charter Services gains share fastest on fractional ownership model proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANAC in Brazil anchors regulatory harmonization efforts across Latin America's general aviation sector, with DGAC in Mexico and civil aviation authorities in Argentina, Chile, and Colombia following ICAO Annex 8 frameworks to streamline cross-border operations.
Brazil
Corporate flight departments in São Paulo and Rio de Janeiro drive fleet renewal cycles for light and midsize business jets. ANAC's alignment with sustainable aviation fuel certification frameworks is reshaping equipment financing terms for operators in the southeastern corridor. Embraer SA's manufacturing base in São José dos Campos sustains regional supply chain advantages for turboprop and light jet production serving domestic and export markets.
Mexico
Fractional ownership models are compressing traditional aircraft sales cycles among manufacturing executives in Mexico City and Monterrey. DGAC airworthiness directive harmonization gaps with ANAC continue delaying pre-owned business jet entry-into-service timelines. Leonardo rotorcraft configurations secure multi-year crew transport contracts with Pemex for Gulf of Mexico offshore platform access.
Argentina
Agricultural aviation operators in Buenos Aires and Córdoba provinces are scaling turbine-powered spray fleets to cover expanding soybean and wheat plantation footprints. The country's national civil aviation regulator maintains type certification requirements that influence import eligibility for used aircraft from Brazil and the United States. Rosario anchors agribusiness flight operations connecting Pampas grain belts to river port logistics hubs.
Chile
Mining concessionaires in Antofagasta and Atacama regions deploy fixed-wing and rotorcraft platforms for remote site connectivity across the Andean cordillera. The civil aviation authority's pilot licensing standards shape training pipeline outputs for charter operators serving copper extraction corridors. Santiago concentrates MRO infrastructure and corporate flight department management for cross-border operations into Peru and Bolivia.
Colombia
Helicopter emergency medical services are expanding into mountainous terrain of Antioquia and Cundinamarca departments where road access fails during monsoon seasons. The civil aviation regulator's adoption of ICAO standards is streamlining cross-border air ambulance dispatch protocols with Ecuador and Venezuela. Bogotá anchors charter broker networks aggregating aircraft availability across fragmented Andean FBO infrastructure.
Latin America General Aviation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Latin America's general aviation market. Embraer SA leverages captive manufacturing depth to sustain regional supply chain advantages, while Textron Inc. anchors aftermarket revenue through extensive service center networks across Mexico and Brazil. Leonardo S.p.A. occupies a distinct position in rotorcraft configurations for offshore energy logistics. Competitive moves concentrate on strategic partnerships for sustainable aviation fuel distribution and geographic expansion of fractional ownership platforms.
Within the integrated manufacturing tier, Embraer SA exemplifies the vertically anchored archetype through its São Paulo production base, while Textron Inc. represents the service-network-driven model. Leonardo S.p.A. occupies a specialist position in twin-engine IFR rotorcraft for energy transport contracts. These three companies collectively illustrate how manufacturing depth, aftermarket infrastructure, and mission-specific configurations define competitive positioning across Brazilian and Mexican demand centers.
| Leading Market Players |
|---|
| Bombardier Inc. |
| Leonardo S.p.A. |
| Embraer SA |
| Pilatus Aircraft |
| Dassault Aviation SA |
| Textron Inc. |
| Honda Aircraft Company |
| Piper Aircraft Inc. |
| Gulfstream Aerospace Corporation |
| Others |
Supply & Pricing Matrix
ICAO Annex 8 harmonization across ANAC and DGAC jurisdictions gates both airframe import eligibility and price stratification between certified and non-certified pre-owned fleets. This regulatory overlay compresses margins for gray-market importers while concentrating pricing power with OEM-authorized distributors who control documentation pipelines.
Pricing Analysis
Brazil-to-Mexico price spreads for equivalent pre-owned light jets now exceed fifteen percent on identical airframe hours, reflecting ANAC's stricter airworthiness directive enforcement. Three-tier pricing structure across OEM-certified, independent-dealer-verified, and as-is-import categories tracks documentation completeness rather than equipment age alone. Cost compression in the independent-dealer tier is intensifying because DGAC-ANAC directive gaps delay entry-into-service timelines. Corporate flight departments show lowest price sensitivity, while individual private owners in São Paulo concentrate demand in the as-is-import tier.
Supply Chain Analysis
Brazil anchors turboprop and light jet final assembly through Embraer's São José dos Campos complex, while Mexico concentrates avionics integration and interior completion for North American export markets. The regional supply chain draws from US turbine engine imports, Canadian flight control systems, and European avionics suites. Single-source vulnerability runs through Pratt & Whitney Canada PT6A engine allocations, where production backlogs extend delivery timelines. Distribution runs through São Paulo and Mexico City MRO hubs that anchor aftermarket parts logistics across the continent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American general aviation sits in early-cycle expansion as fractional ownership models displace whole-aircraft purchases among corporate flight departments, compressing traditional sales cycles while extending fleet management contract durations.
For Market Incumbents: Shield installed base relationships from NetJets and local fractional competitors by embedding proprietary maintenance protocols that raise switching costs for flight departments. Deepen backward integration into avionics retrofit capabilities to capture ADS-B Out mandate spending across aging imported fleets. Prioritize ANAC field office staffing partnerships that reduce inspection scheduling friction for Part 135 operators in Brazil's interior states. For New Entrants and Emerging Players: ANAC's emerging SAF certification fast-track creates regulatory arbitrage opportunities for FBOs willing to invest in blending infrastructure ahead of mandate enforcement. White-space targets concentrate in Amazon Basin turboprop connectivity for mining and agribusiness outposts, and in Mexican HEMS expansion across Oaxaca and Chiapas mountain corridors. Go-to-market positioning should emphasize ruggedized STOL configurations with unpaved airstrip certification. For Investors and Strategic Acquirers: Carve-out targets emerge from energy majors' non-core aviation logistics units, particularly Pemex and Petrobras helicopter transport divisions facing capital discipline pressures. Long-term viability hinges on exposure to corporate subscription models rather than transactional aircraft sales. Watch ANAC's SAF blending mandate timeline as the inflection signal for FBO valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Certification Investment | ANAC's emerging blending mandates position early-adopter FBOs to capture premium corporate pricing. |
| Fractional Platform Expansion | NetJets and local competitors are compressing OEM direct sales cycles across São Paulo and Mexico City. |
| Amazon Basin Connectivity Buildout | Unpaved airstrip infrastructure in Rondônia and Acre creates demand for ruggedized turboprop configurations. |
| Helicopter Emergency Medical Services | Mexican healthcare network expansion into mountain corridors drives twin-engine IFR rotorcraft procurement. |
| Avionics Retrofit Capability | ADS-B Out mandates across aging imported fleets require costly STC modifications that anchor aftermarket revenue. |
Research Methodology
Desk research of ANAC and DGAC regulatory filings, ICAO Annex 8 implementation documents, and OEM delivery disclosures preceded structured interviews with flight department managers, FBO operators, airframe and powerplant mechanics, and aircraft finance underwriters. Secondary validation drew from ANAC airworthiness directive databases, Brazilian agricultural aviation association fleet surveys, and Mexican civil aviation authority registration extracts. Bottom-up aircraft unit economics and top-down regional GDP elasticity models were triangulated against primary field intelligence.
Variance decomposition across aircraft type, application, end user, and service type dimensions structured the analytical framework over the projection horizon. CAGRs were derived from logistic diffusion curves fitted to fractional ownership penetration rates and SAF blending mandate adoption schedules. Modeled inputs included Jet-A price volatility assumptions, certified mechanic pipeline graduation rates, and pre-owned import documentation processing timelines.
Underlying assumptions cover regulatory harmonization completion, continued agribusiness plantation expansion, and offshore energy production stability, with deviation risk concentrated in ANAC field office staffing levels and DGAC-ANAC directive synchronization pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Aircraft Elevator Market
Aircraft
Aircraft Mounts Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Docking System Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Aircraft Door Market
Aircraft
North America General Aviation Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aircraft Autopilot System Market
Aircraft
US Business Jet Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Aero Wing Market
Aircraft
Small Evtol Aircraft Market