
 Global Fintech Market | 2026-2036
Global Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fintech Market Analysis
The EU AI Act is expanding compliance obligations for automated credit decisioning, forcing new entrants to allocate substantial resources to algorithmic auditability and explainability infrastructure. Visa leverages its network scale to sustain cross-border payment dominance across multiple corridors. Ant Group anchors its position through embedded finance integrations within super-app ecosystems. Stripe differentiates via developer-centric API architecture that reduces merchant onboarding friction.
Fintech encompasses technology-enabled financial services delivered through software platforms, mobile applications, and API-based infrastructure, typically operating with sub-second transaction processing latency and 99.99% uptime requirements for payment clearing. Its primary commercial purpose is to disintermediate traditional banking intermediaries while reducing unit transaction costs through automated underwriting, real-time risk scoring, and cloud-native core banking systems. Payment Processing occupies the largest value pool due to recurring transaction volume density, while AI-Driven Solutions represents the fastest-expanding technology segment as neural network models compress fraud detection latency from minutes to milliseconds. Blockchain retains structural importance in cross-border settlement corridors where correspondent banking delays persist.
The US Federal Reserve shapes real-time payment infrastructure through FedNow service mandates, while the UK's FCA enforces open banking standards that compel incumbent banks to share customer-permissioned data. China's SAMR and PBOC jointly govern Ant Group and Tencent through platform economy antitrust and financial holding company regulations. India's RBI operationalizes fintech licensing through its regulatory sandbox, testing digital lending models before full market authorization. Stakeholders must monitor whether fragmented national data localization rules fragment cloud infrastructure economics or create arbitrage opportunities for jurisdictional optimization.
Market Dynamics
AI-driven credit scoring infrastructure is compressing underwriting cycles from weeks to minutes, forcing incumbent banks to rebuild risk engines around neural network architectures or cede SME lending to algorithmic-native competitors.
Growth Catalysts
- UPI Infrastructure:India's real-time payment rails process billions of monthly transactions, creating density for embedded lending and insurance distribution.
- EU AI Act:Mandatory algorithmic transparency requirements for automated credit decisions are accelerating investment in explainable AI tooling across European fintech stacks.
- Cloud-Native Core Banking:Containerized banking platforms reduce capital deployment timelines, enabling neobanks to launch deposit products within regulatory sandboxes.
Market Restraints
- Data Localization Mandates:Fragmented sovereignty rules across India, China, and the EU inflate cloud infrastructure costs and complicate cross-border data flows.
- Correspondent Banking Concentration:Cross-border settlement remains tethered to a shrinking pool of tier-one banks, creating single-point-of-failure risk in emerging market corridors.
- Legacy Core Modernization Debt:Incumbent banks' COBOL-dependent systems impose integration friction that slows open banking API deployment.
Strategic Opportunities
- Brazil's Open Finance:Central bank mandates for data sharing are creating white space for credit intermediaries to aggregate permissioned transaction histories.
- Embedded Insurance Convergence:Payment platforms are integrating parametric coverage at transaction origination, compressing distribution costs.
- FedNow Instant Settlement:The Federal Reserve's real-time rail enables 24/7 liquidity management, unlocking working capital products for US-based SMEs.
Industry Challenges
- Model Risk Management Talent:Shortage of professionals capable of validating machine learning credit models under SR 11-7 guidelines constrains deployment velocity.
- Multi-Jurisdictional Compliance:Fintechs operating across EU AI Act, RBI sandbox, and state-level US money transmitter rules face divergent audit timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fintech Market |
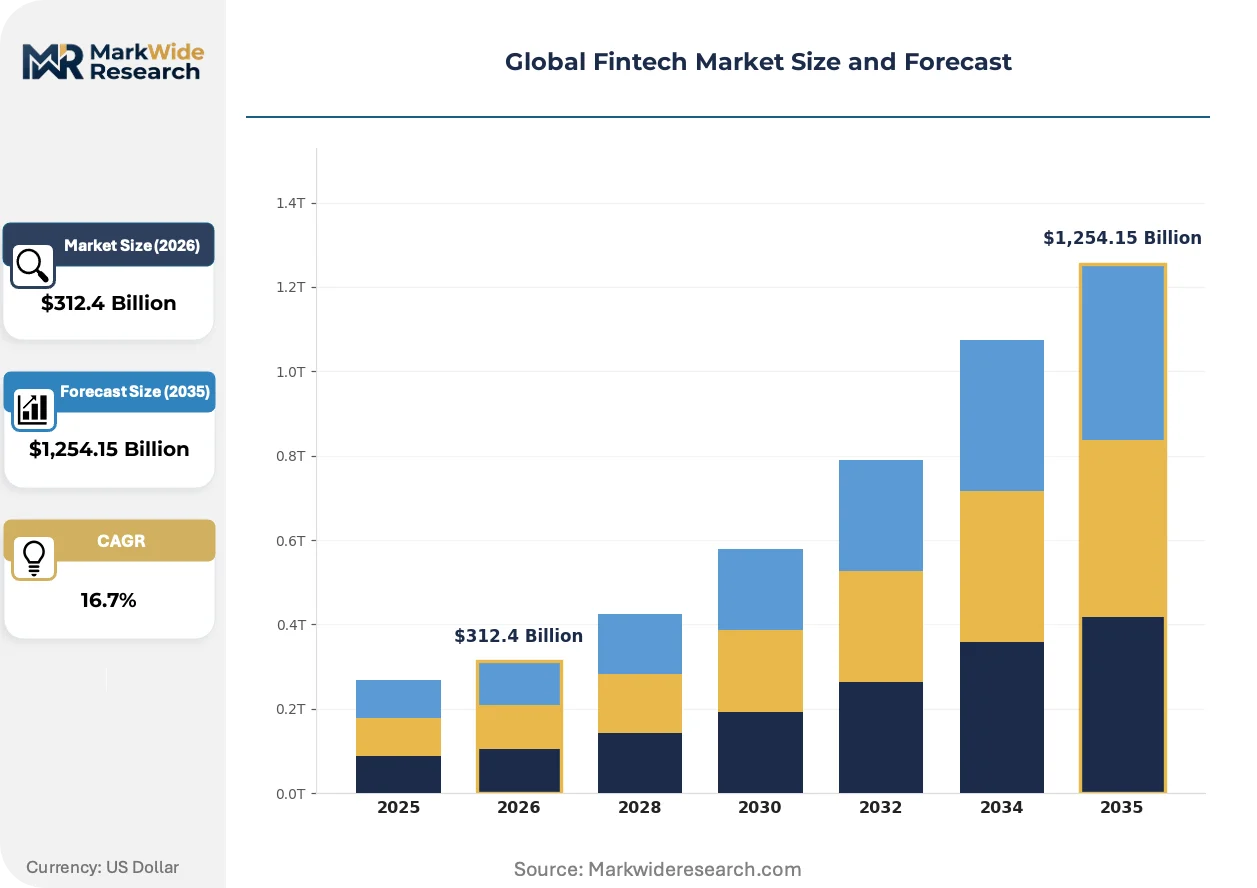
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $1,254.15 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Lending, Investment Management, WealthTech Client Type: Retail Consumers, SMEs, Large Enterprises, Institutional Investors Technology: Blockchain, AI-Driven Solutions, Digital Wallets, Mobile Banking Solutions Business Model: Subscription-Based, Transaction Fees, Commission-Based, Freemium |
| Companies Covered | Tencent, Visa, Mastercard, Intuit, Stripe, Ant Group, PayPal Holdings Inc., Block Inc., Adyen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fintech Market Emerging Trajectories
Neural network architectures are compressing fraud detection latency while regulatory sandboxes in India and Brazil are accelerating product-market validation cycles for algorithmic credit models.
Embedded finance infrastructure is modularizing merchant-facing financial services, allowing non-bank platforms to offer lending, payments, and insurance without building captive banking licenses. Retailers and logistics platforms are adopting white-label banking stacks within twelve-month implementation windows. This architecture is compressing customer acquisition costs by embedding financial products at existing transaction touchpoints.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on automated credit decisioning systems. Lenders must maintain technical files demonstrating algorithmic fairness and non-discrimination. European neobanks are responding by hiring dedicated AI ethics officers and rebuilding model governance frameworks around explainability-by-design principles.
SMEs are consolidating financial service procurement onto unified platforms that combine treasury management, FX hedging, and working capital credit. Traditional branch-based relationship banking is losing share to API-first providers that embed these capabilities directly into accounting software. This pattern is most pronounced in India, where UPI-linked cash flow data enables cash-based businesses to access formal credit for the first time.
Global Fintech Market Segmentation
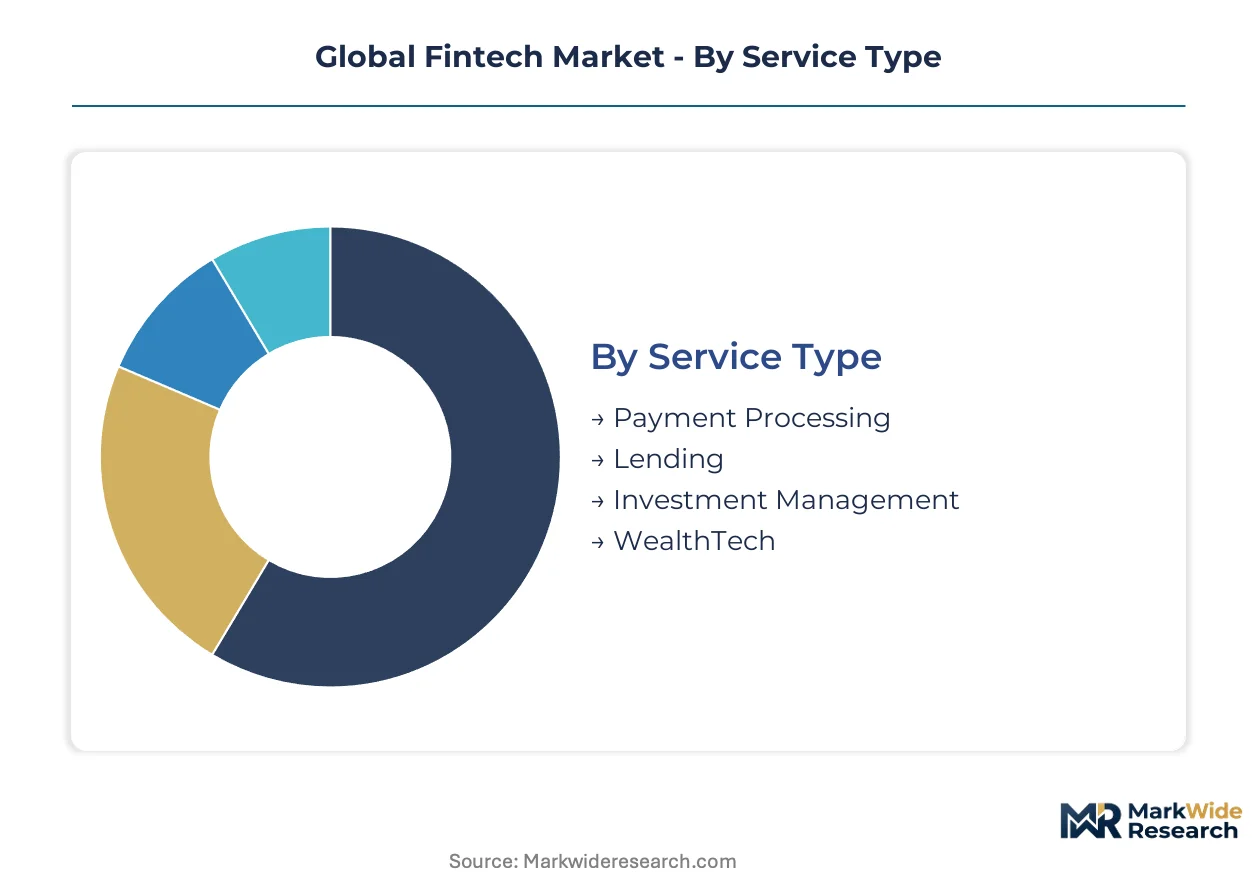
Fintech market segmentation reveals how technology architecture, client economics, and revenue mechanics interact to determine competitive positioning. Distinct service layers and technology stacks command divergent capital intensity and regulatory exposure.
Service Type:
Technology architecture determines processing latency requirements and infrastructure investment thresholds across service categories.
- Payment Processing:Real-time clearing infrastructure processes transactions with sub-second latency, sustaining recurring revenue through volume density. Demand concentrates in India's UPI corridors and Brazil's instant payment rails, where regulatory sandboxes compress go-to-market timelines for new entrants.
- Lending:Algorithmic underwriting engines using alternative data streams reduce decision cycles from weeks to minutes. SME segments in India and Southeast Asia drive adoption as UPI-linked cash flow data enables formal credit access for previously unbanked businesses.
- Investment Management:Robo-advisory platforms automate portfolio rebalancing through ETF-based strategies. Retail penetration rises in markets with fractional share trading permissions.
- WealthTech:Holistic financial planning tools integrate tax optimization, estate structuring, and alternative asset access. Institutional-grade analytics migrate downstream to mass-affluent segments.
Payment Processing leads on scale; Lending leads on momentum.
Client Type:
Customer economics vary sharply across sophistication tiers, dictating acquisition cost thresholds and lifetime value calculations.
- Retail Consumers:Mobile-first interfaces dominate engagement, with biometric authentication and one-tap checkout reducing abandonment rates. India's digital payment adoption demonstrates how public infrastructure investment unlocks mass-market penetration.
- SMEs:Cash flow visibility tools embedded in accounting software drive platform consolidation. Treasury management, FX hedging, and working capital credit converge onto single dashboards as branch-based relationship banking loses share.
- Large Enterprises:Custom API integrations and white-label banking stacks support complex treasury operations. Multi-entity cash pooling and cross-border liquidity management command premium pricing.
- Institutional Investors:Execution algorithms, risk analytics, and regulatory reporting infrastructure require dedicated compliance architecture. MiFID II and SEC disclosure mandates shape product development priorities.
SMEs anchor volume growth; Retail Consumers show the steepest expansion trajectory.
Technology:
Underlying technology stacks determine scalability boundaries and regulatory scrutiny intensity.
- Blockchain:Distributed ledger infrastructure reduces settlement latency in cross-border corridors where correspondent banking delays persist. Smart contract automation enables programmable compliance for multi-jurisdictional transactions.
- AI-Driven Solutions:Neural network architectures compress fraud detection from minutes to milliseconds while powering alternative credit scoring. The EU AI Act's risk-based classification imposes documentation burdens on automated decisioning systems.
- Digital Wallets:Tokenized credential storage enables secure in-app and in-store transactions. Super-app ecosystems in Asia integrate merchant services, transport, and government payments into unified interfaces.
- Mobile Banking Solutions:Cloud-native core systems allow neobanks to launch deposit products within regulatory sandboxes. Containerized deployment reduces capital deployment timelines versus legacy core modernization.
AI-Driven Solutions command the fastest technology adoption curve; Digital Wallets sustain the broadest geographic penetration.
Business Model:
Revenue mechanics determine customer acquisition investment horizons and churn sensitivity.
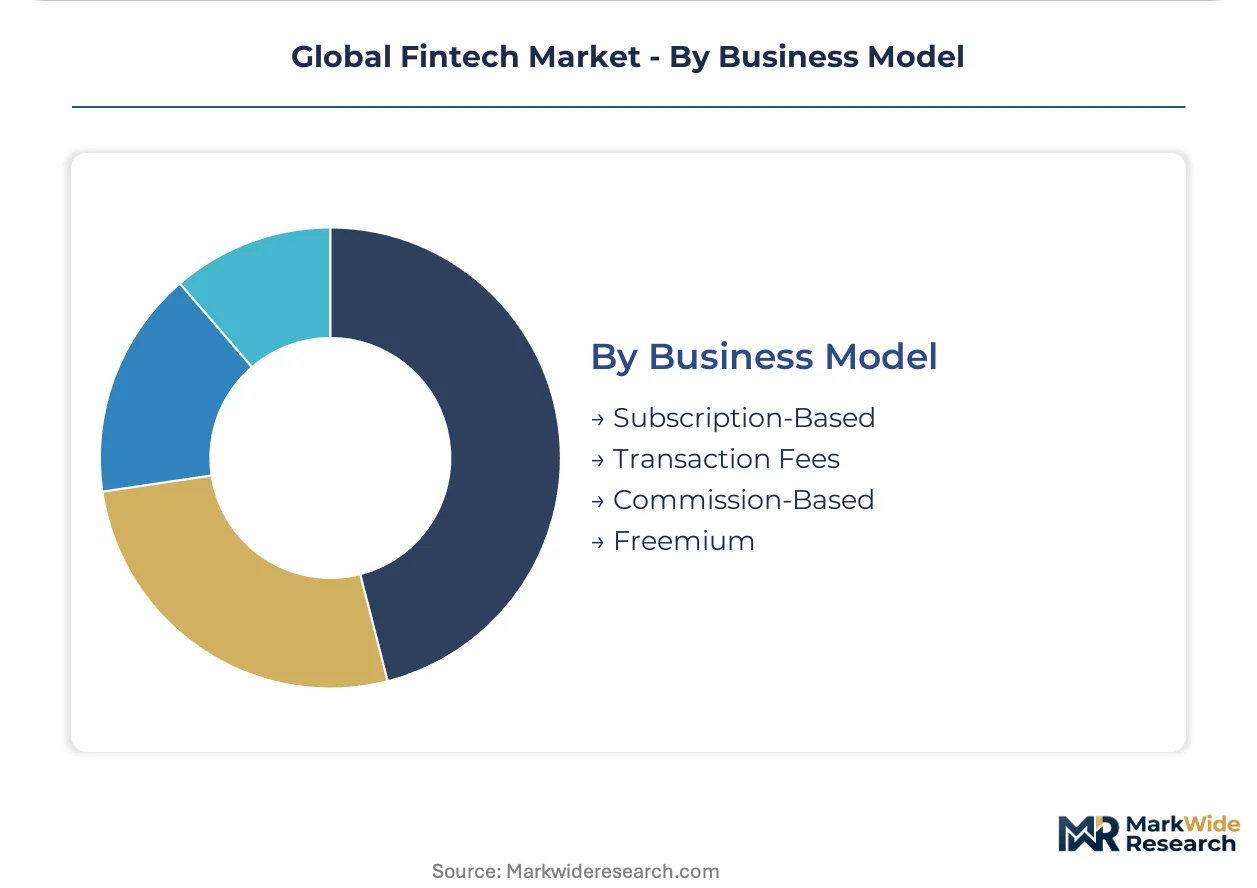
- Subscription-Based:Recurring revenue models support predictable unit economics for SaaS-delivered treasury and analytics tools. Annual contracts with upfront payment improve cash conversion cycles.
- Transaction Fees:Interchange and processing spreads scale directly with payment volume density. Cross-border corridors command premium spreads due to FX conversion and regulatory complexity.
- Commission-Based:Origination fees on lending and distribution spreads on investment products align provider incentives with customer outcomes. Embedded finance integrations expand distribution reach without captive license requirements.
- Freemium:Zero-cost entry tiers drive user acquisition, with premium features monetizing power users. Conversion optimization focuses on transaction volume thresholds triggering paid tier benefits.
Transaction Fees dominate current revenue pools; Subscription-Based models are climbing the fastest as enterprise SaaS penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Bangalore, Singapore, and London anchor fintech infrastructure development across three continents. Regulatory sandbox frameworks in India and Brazil compress product validation timelines. Payment density concentrates where real-time rails intersect with SME credit demand.
United States
FedNow instant settlement infrastructure and embedded finance API adoption drive SME working capital innovation. The Federal Reserve and OCC enforce bank-fintech partnership oversight through tailored guidance. New York and San Francisco clusters concentrate neobank engineering and venture deployment.
India
UPI transaction volume density and cash-flow-based alternative credit scoring unlock formal lending for unbanked SMEs. The RBI operationalizes fintech licensing through its regulatory sandbox and data localization directives. Bangalore and Mumbai anchor super-app engineering and digital lending platform headquarters.
United Kingdom
Open banking API standards and real-time account aggregation reshape retail and SME financial management. The FCA mandates customer-permissioned data sharing while supervising cryptoasset registration. London's Square Mile and Shoreditch clusters concentrate WealthTech engineering and institutional fintech infrastructure.
Brazil
Pix instant payment rails and open finance data-sharing mandates create white space for credit intermediaries. The Central Bank of Brazil enforces interoperability standards and payment system access rules. São Paulo anchors LatAm fintech engineering and embedded finance platform development.
Singapore
Cross-border payment corridor density and wealth management platform demand attract regional headquarters investment. The Monetary Authority of Singapore licenses digital banks and supervises cryptoasset service providers. The city-state's fintech cluster concentrates ASEAN market entry engineering and regulatory technology development.
Global Fintech Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across payment processing, lending infrastructure, and embedded finance orchestration. Market structure tilts toward platform consolidation where network effects and regulatory scale create defensive moats. Three archetypes dominate: technology conglomerates with super-app ecosystems, payment networks with cross-border scale, and developer-centric infrastructure providers. Competitive moves concentrate on embedded finance API expansion and algorithmic credit model licensing.
Within the technology conglomerate tier, Tencent and Ant Group exemplify super-app anchoring strategies that bundle payments, lending, and insurance within unified consumer interfaces. Visa and Mastercard occupy positions as network-scale incumbents sustaining cross-border payment dominance through tokenization infrastructure and real-time clearing investments. Stripe represents the developer-centric archetype, reducing merchant onboarding friction through API-first architecture that compresses integration timelines.
| Leading Market Players |
|---|
| Tencent |
| Visa |
| Mastercard |
| Intuit |
| Stripe |
| Ant Group |
| PayPal Holdings Inc. |
| Block Inc. |
| Adyen N.V. |
| Others |
Supply Flow & Price Mechanics
Machine learning engineering talent concentration in Bangalore and Singapore generates labor-cost differentials that widen pricing-tier spreads between algorithmic-native fintechs and legacy-dependent incumbents. Cloud infrastructure arbitrage across regulatory jurisdictions further stratifies service economics as data localization mandates inflate operational overhead in premium-tier markets.
Pricing Analysis
Bundled super-app financial services versus unbundled API-first infrastructure splits the pricing landscape into two dominant models. SaaS-tiered subscription structures anchor enterprise treasury and risk analytics tools, while per-transaction interchange spreads dominate payment processing revenue pools. Price differentiation stems from API integration complexity and regulatory compliance tier—EU AI Act-mandated explainability tooling commands premium positioning over basic automated underwriting. Pricing pressure stems from compressed fraud-detection latency races as neural network architectures commoditize. SME segments exhibit highest price sensitivity due to thin working capital margins, while institutional investors tolerate premium tiers for multi-entity cash pooling and cross-border liquidity management.
Supply Chain Analysis
Cloud compute infrastructure rests on hyperscaler concentration across the United States, Ireland, and Singapore, with specialized AI accelerator chip supply anchored in Taiwan and South Korea. Raw material dependencies span semiconductor-grade silicon, rare earth elements for data center magnets, and cobalt-lithium battery chemistries for edge computing deployments. Single-source vulnerability in advanced node GPU fabrication creates chokepoint exposure for real-time risk scoring platforms. Distribution runs through API gateway providers and white-label banking stack vendors that modularize financial service delivery to non-bank platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fintech rests on cloud-native core banking cost compression displacing COBOL-dependent legacy infrastructure, alongside premium-tier migration toward embedded finance orchestration.
For Market Incumbents: Anticipate algorithmic-native competitors compressing SME lending margins through UPI-linked cash flow underwriting. Defensive consolidation should prioritize vertical integration into cloud-native core banking licenses and certification investment under EU AI Act model governance frameworks. Channel control through exclusive super-app distribution partnerships with logistics and retail platforms preserves deposit-gathering scale. For New Entrants and Emerging Players: Cash-based SMEs in India's tier-2 and tier-3 urban corridors represent the most penetrable buyer archetype for formal credit access. White-space targets include parametric insurance distribution at UPI transaction origination and FX hedging tools embedded in accounting software for cross-border e-commerce merchants. Go-to-market execution should leverage RBI regulatory sandbox validation to compress trust-building timelines before national scale authorization. For Investors and Strategic Acquirers: Payment networks with cross-border scale are the most active acquirer in this space, consolidating tokenization infrastructure and real-time clearing capabilities. Long-term viability favors platform consolidation where network effects and regulatory scale create defensive moats. Acquisition target archetypes include developer-centric API infrastructure providers and algorithmic credit model licensing specialists. The signal to watch is FedNow adoption velocity among US-based neobanks as an inflection indicator for instant settlement infrastructure monetization.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Stripe's developer-centric architecture reduces merchant onboarding friction from months to days. |
| Regulatory Sandbox Entry | RBI and Central Bank of Brazil frameworks compress product-market validation cycles for algorithmic credit models. |
| Embedded Finance Partnership | Ant Group's super-app ecosystem bundles payments, lending, and insurance within unified consumer interfaces. |
| Explainable AI Tooling Investment | EU AI Act mandates force neobanks to rebuild model governance around algorithmic auditability infrastructure. |
| Cross-Border Tokenization Scale | Visa leverages network effects to sustain dominance in corridors where correspondent banking delays persist. |
Methodological Framework
Bottom-up SME and enterprise client modeling reconciled against top-down payment volume and cloud infrastructure tracking forms the analytical core of this study. Primary interviews with neobank CTOs, RBI sandbox program officers, EU regulatory technology consultants, and merchant platform integration specialists combined with secondary validation against SEC filings, UPI transaction databases, and European Banking Authority algorithmic transparency guidance. Triangulation across stakeholder perspectives and data sources ensures segmentation integrity.
Input-output matrices map transaction density, regulatory licensing timelines, and technology adoption curves to revenue pool projections across the analysis window. Segmentation dimensions modeled include service type, client sophistication tier, underlying technology stack, and revenue mechanics. CAGRs derive from compounding annual transaction volume growth, cloud infrastructure cost deflation rates, and regulatory sandbox expansion trajectories. Forecast inputs incorporate FedNow adoption velocity, UPI corridor density saturation, and EU AI Act compliance cost escalation.
Underlying measurement precision varies by segment; payment processing and digital wallet volumes carry tighter precision than emerging blockchain settlement corridors. Forecasts reflect assumptions around regulatory sandbox authorization timelines, hyperscaler capex continuity, and central bank real-time rail deployment schedules. Model risk management talent shortages, multi-jurisdictional compliance divergence, and data localization mandate fragmentation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Germany AI in Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Africa AI in Fintech Market
FinTech
Account Checking Software Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Business Analytics in Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Financial Forecasting Software Market
FinTech
Smart Finance Connectivity Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
North America AI in Fintech Market
FinTech
Generative AI in Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
UAE Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
AI in Fintech Market