
 United States Bio-Fungicide Market | 2026-2036
United States Bio-Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bio-Fungicide Market Insights
A shift from outsourced fermentation to in-house microbial production is repositioning supply economics for domestic bio-fungicide manufacturers. BASF SE leverages captive bioreactor capacity in North Carolina to secure strain consistency for its microbial portfolio. Marrone Bio Innovates anchors its competitiveness on proprietary screening platforms that isolate novel actinomycetes from U.S. soil collections. Certis USA LLC specializes in bacillus-based formulations, dominating distribution through agricultural retail cooperatives.
Bio-fungicides comprise living microorganisms, botanical extracts, and biochemical compounds formulated to suppress fungal plant pathogens through antagonism, competition, or induced systemic resistance; most registered products contain colony-forming units exceeding 10^8 per milliliter to ensure field efficacy. Microbial Solutions command the largest revenue share among product types due to established grower familiarity with bacillus and trichoderma platforms, while Bio-Stimulants represent the fastest-expanding category as suppliers bundle fungistatic activity with plant health benefits. Among applications, Crops absorbs the majority of volume, though Greenhouses generate premium pricing through concentrated, high-value production environments where residue restrictions are strictest.
EPA biopesticide registration under FIFRA Section 3(c)(5) shapes market access timelines, with the agency's Biopesticides and Pollution Prevention Division typically evaluating microbial products faster than conventional chemistries. USDA Organic certification and state-level restricted-entry interval rules in California and Washington further filter which formulations reach commercial channels. Stakeholders must track how EPA's evolving metabolite data requirements for microbial products alter registration costs and competitive moats.
Market Dynamics
The transition from outsourced fermentation to captive bioreactor capacity is compressing production economics and redrawing competitive moats among domestic bio-fungicide suppliers. Strain consistency and metabolite standardization now separate viable commercial platforms from marginal formulations.
Growth Catalysts
- EPA Biopesticide Registration Streamlining:FIFRA Section 3(c)(5) evaluation timelines for microbial products run shorter than conventional chemistry pathways, accelerating commercial access for novel actinomycete and bacillus formulations.
- Midwest Row-Crop Integration:Soybean and corn farmers embed microbial solutions into fungicide resistance management protocols, creating pull-through demand for multi-mode-of-action biologicals.
- California Specialty Crop Expansion:Grape, strawberry, and vegetable growers scale biological programs under state-level restricted-entry interval constraints and residue tolerance pressures.
Market Restraints
- Fermentation Input Volatility:Molasses and soy-derived substrate costs fluctuate with commodity agriculture cycles, squeezing gross margins for manufacturers lacking long-term supply contracts.
- Metabolite Data Requirements:EPA's evolving secondary metabolite characterization standards for microbial products extend registration preparation timelines and inflate toxicology study expenditures.
- Shelf Stability Limitations:Viable colony-forming unit degradation in liquid formulations constrains distribution radius and retail inventory holding periods.
Strategic Opportunities
- Greenhouse Premium Segments:Controlled-environment agriculture operators in Florida and Texas absorb price premiums for zero-residue biologicals serving export markets with strict maximum residue limits.
- Bio-Stimulant Bundling:Suppliers pair fungistatic activity with plant health benefits, accessing USDA Organic certification pathways that command price premiums in specialty retail channels.
- Agricultural Cooperative Distribution:Direct-to-grower models through farmer-owned retail cooperatives bypass traditional agrichemical distributor markups and capture margin.
Industry Challenges
- Strain Banking and Cryopreservation Expertise:Domestic talent pools for industrial microbiology and fermentation process engineering remain thin relative to pharmaceutical biologics sectors.
- Integration with Precision Application Systems:Biological compatibility with drone and variable-rate spray infrastructure requires reformulation and adjuvant testing that delays field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bio-Fungicide Market |
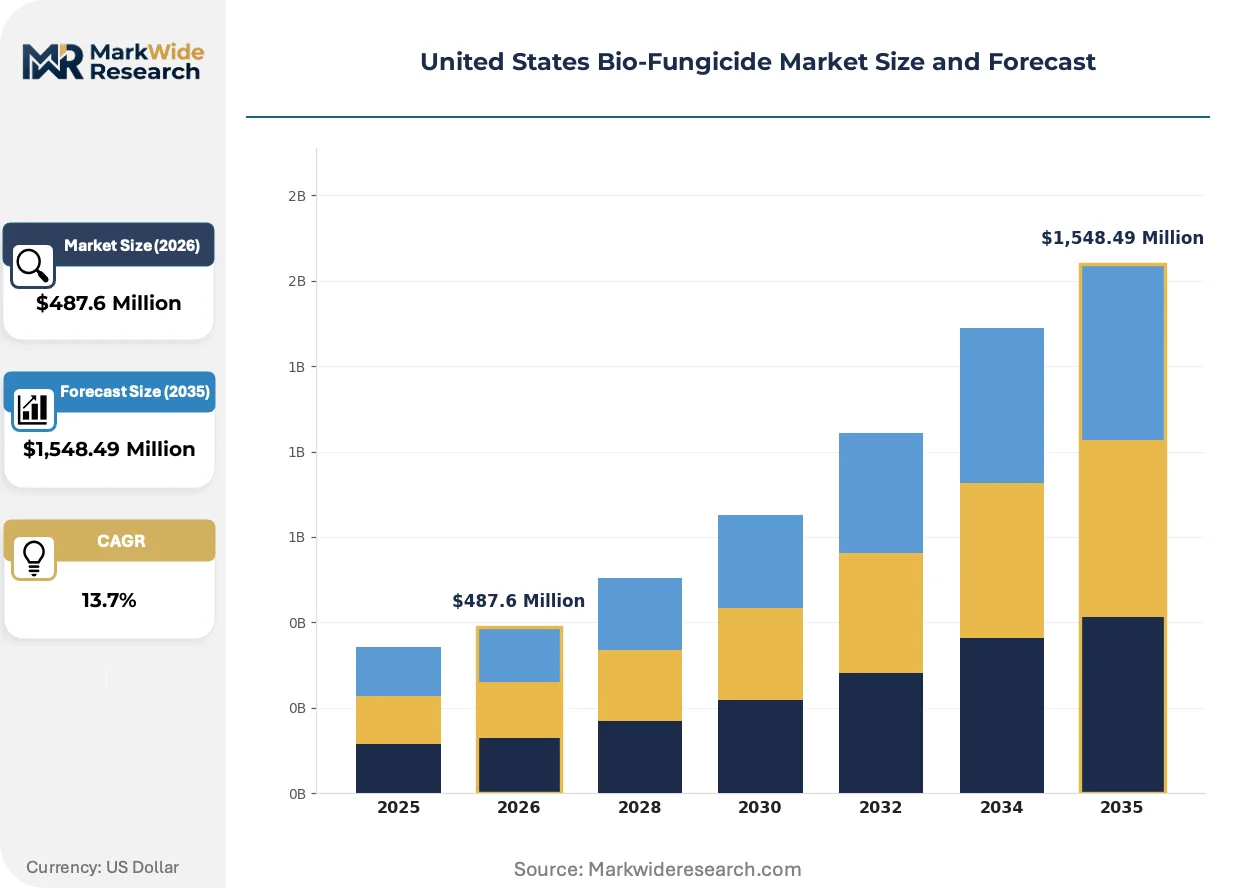
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,548.49 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BCAs, Microbial Solutions, Botanical Extracts, Bio-Stimulants Application: Crops, Turf, Ornamentals, Greenhouses End User: Agriculture, Horticulture, Landscaping, Residential Distribution Channel: Online Retail, Direct Sales, Distributors, Garden Centers |
| Companies Covered | Valent BioSciences LLC, Syngenta AG, Bioceres Crop Solutions, Gowan Company, Certis USA LLC, BioWorks Inc, Marrone Bio Innovations, FMC Corporation, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bio-Fungicide Market Trends and Innovations
Formulation science and regulatory data packages are converging to compress development-to-commercialization cycles. Manufacturers now prioritize metabolite fingerprinting and adjuvant compatibility earlier in strain selection workflows.
RNA interference and peptide-based bio-fungicides are overtaking conventional microbial platforms in pre-commercial pipelines. Greenhouse operators in California and Florida trial these modalities for targeted pathogen suppression without residue accumulation. The shift is compressing market space for broad-spectrum chemical alternatives in high-value cropping systems.
EPA's Biopesticides and Pollution Prevention Division has clarified metabolite identification thresholds for microbial product registrations. Manufacturers must now submit secondary metabolite structural data earlier in the review process. California Department of Pesticide Regulation incorporates these federal standards into state-level restricted material permitting, affecting bacillus and trichoderma formulation commercialization timelines.
Buyer concentration through agricultural retail cooperatives is consolidating procurement leverage in the Midwest. Corn and soybean growers now negotiate biological program pricing through pooled purchasing agreements rather than individual farm-level transactions. Iowa and Illinois cooperatives drive this pattern, pressuring suppliers to unbundle technical support from product pricing.
United States Bio-Fungicide Market Segmentation
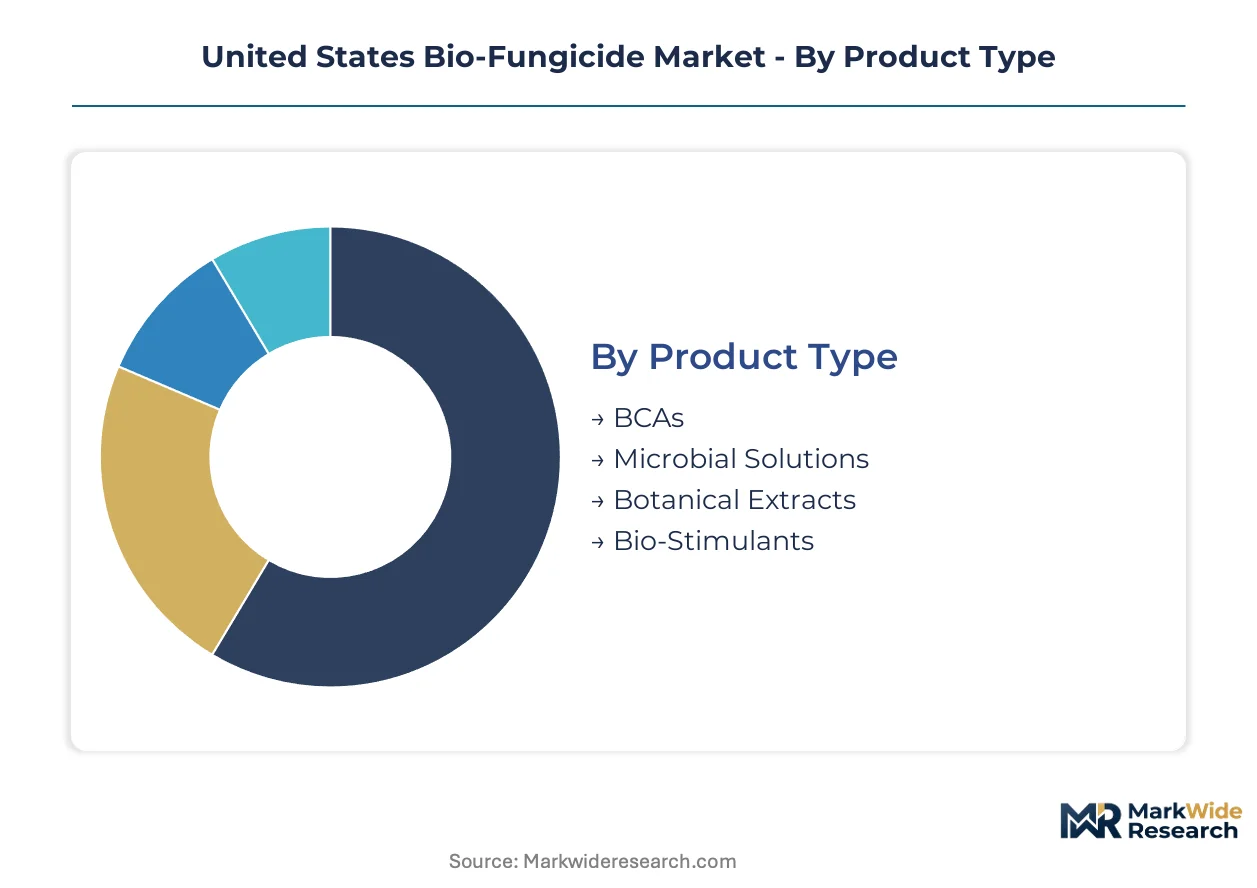
Segmentation reveals how capital deployment, regulatory exposure, and channel economics vary across the U.S. bio-fungicide landscape. Manufacturers prioritize segments where fermentation scale and EPA registration costs align with pricing power.
Product Type:
Capital intensity clusters heavily in microbial fermentation infrastructure, with bioreactor capacity requirements separating viable commercial platforms from formulation-dependent competitors.
- Microbial Solutions:Living organisms—primarily bacillus and trichoderma strains—formulated at colony-forming unit densities exceeding 10^8 per milliliter. Midwest row-crop operators in Iowa and Illinois integrate these into soybean and corn resistance management protocols, though metabolite standardization costs strain smaller manufacturers.
- Bio-Stimulants:Biochemical compounds bundled with plant health benefits rather than pure pathogen suppression. California specialty crop growers absorb price premiums for formulations carrying USDA Organic certification, creating margin expansion unavailable in commodity channels.
- BCAs:Beneficial microorganisms deployed as biocontrol agents through direct antagonism or competition with fungal pathogens.
- Botanical Extracts:Plant-derived fungistatic compounds requiring less fermentation infrastructure but facing variable raw material supply from domestic herb and oilseed crops.
Microbial Solutions absorb the bulk of installed capacity; Bio-Stimulants are expanding most quickly.
Application:
Application segments diverge sharply in residue tolerance requirements, with zero-residue environments commanding pricing multiples that justify specialized formulation development.
- Crops:Field-scale deployment across corn, soybean, wheat, and specialty fruit and vegetable production. Volume concentrates in the Midwest belt where cooperatives negotiate pooled procurement agreements, compressing per-unit margins despite large tonnage.
- Greenhouses:Controlled-environment agriculture in Florida and Texas serving export markets with strict maximum residue limits. Operators absorb 40-60% price premiums for biologicals that eliminate pre-harvest intervals entirely.
- Turf:Golf course and sports field maintenance requiring broadcast application compatibility with existing spray infrastructure.
- Ornamentals:Nursery and floriculture operations where aesthetic damage thresholds drive rapid treatment adoption.
Crops dominates volume throughput; Greenhouses generates the steepest margin expansion.
End User:
End user categories map directly to technical support requirements and repurchase frequency, with commercial agriculture demanding integrated pest management consultation that residential channels cannot support profitably.
- Agriculture:Commercial farming operations managing pathogen pressure across hundreds to thousands of acres. EPA FIFRA Section 3(c)(5) registration familiarity and resistance management planning drive supplier stickiness in this segment.
- Horticulture:Specialty crop producers in California's Central Valley and Florida's winter vegetable belt, where state-level restricted-entry interval rules filter allowable chemistries and biologicals gain preferential access.
- Landscaping:Commercial grounds maintenance contractors with lower technical sophistication but higher price sensitivity than agricultural buyers.
- Residential:Home gardeners purchasing through garden centers and online retail, with minimal repeat purchase reliability.
Agriculture locks in the majority of manufacturer technical support resources; Horticulture climbs the fastest as residue restrictions tighten.
Distribution Channel:
Channel economics determine whether manufacturers capture margin directly or surrender markup to intermediaries, with cooperative structures in the Midwest rewriting traditional agrichemical distribution patterns.
- Distributors:Traditional agrichemical wholesalers serving independent retail locations and large farming operations. Channel power concentrates among three national networks controlling Midwest inventory placement.
- Direct Sales:Manufacturer-to-grower relationships bypassing distributor markups, prevalent among Iowa and Illinois agricultural cooperatives negotiating biological program pricing through pooled purchasing agreements.
- Online Retail:E-commerce platforms serving residential and small-scale horticultural buyers with limited technical guidance.
- Garden Centers:Independent and chain retail locations targeting ornamental and residential segments with seasonal purchase patterns.
Distributors retain the largest share of commercial volume; Direct Sales gains share fastest as cooperative procurement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest corn and soybean belt fermentation feedstock availability anchors domestic bio-fungicide manufacturing economics. State-level regulatory divergence and specialty crop concentration reshape demand geography across the United States.
Midwest Belt
Iowa and Illinois row-crop operators integrate bacillus-based solutions into fungicide resistance management protocols for soybean and corn rotations. EPA FIFRA Section 3(c)(5) registration familiarity accelerates adoption timelines in this geography. Agricultural retail cooperatives in Des Moines and Peoria negotiate pooled procurement agreements that compress per-unit margins despite large volume throughput.
California
Central Valley grape, strawberry, and vegetable growers scale biological programs under state-level restricted-entry interval constraints and residue tolerance pressures. California Department of Pesticide Regulation incorporates federal metabolite standards into state-level restricted material permitting. Sacramento-based formulation specialists cluster near UC Davis agricultural research corridors.
Florida
Winter vegetable belt and greenhouse operators absorb price premiums for zero-residue biologicals serving export markets with strict maximum residue limits. State environmental regulations filter allowable chemistries and biologicals gain preferential access. Miami-Dade and Palm Beach counties concentrate controlled-environment agriculture infrastructure.
North Carolina
Research Triangle bioreactor capacity supports captive microbial production for strain consistency and metabolite standardization. EPA biopesticide registration pathways streamline commercial access for novel formulations. Raleigh-Durham anchors industrial microbiology talent pools for fermentation process engineering.
Pacific Northwest
Washington state apple and hop producers face residue restrictions that drive biological adoption in integrated pest management programs. State-level organic certification requirements exceed federal USDA standards. Yakima Valley and Wenatchee clusters concentrate specialty crop processing and biological distribution infrastructure.
United States Bio-Fungicide Market Competitive Landscape
Global majors compete with regional champions across fermentation capacity and EPA registration expertise. The supplier base stratifies between captive bioreactor operators and formulation-dependent competitors. Three archetypes dominate: integrated agrochemical conglomerates with microbial platforms, pure-play biological specialists, and agricultural cooperative-aligned distributors. Competitive moves concentrate on backward integration into fermentation infrastructure and strategic partnerships with precision application technology providers.
Among integrated agrochemical conglomerates, BASF SE and Syngenta AG exemplify the scale-driven tier with captive production capabilities. Within pure-play biological specialists, Marrone Bio Innovations and Certis USA LLC occupy positions defined by proprietary screening platforms and bacillus-based formulation expertise respectively. Valent BioSciences LLC represents the cooperative-aligned distribution archetype.
| Leading Market Players |
|---|
| Valent BioSciences LLC |
| Syngenta AG |
| Bioceres Crop Solutions |
| Gowan Company |
| Certis USA LLC |
| BioWorks Inc |
| Marrone Bio Innovations |
| FMC Corporation |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Molasses futures volatility at the Chicago Mercantile Exchange cascades through U.S. bio-fungicide manufacturing economics, compressing margins for suppliers lacking long-term substrate contracts while rewarding integrated producers with captive fermentation capacity. This input-cost pressure stratifies pricing tiers across microbial solutions, botanical extracts, and bio-stimulant formulations.
Pricing Analysis
Warranty and technical support bundling separates premium microbial formulations from unbundled commodity alternatives, with EPA registration data packages and strain consistency guarantees commanding price multiples in California specialty crop channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—USDA Organic and state-level restricted-entry interval compliance drive premiums, while volume scale through Midwest cooperative procurement compresses per-unit economics. Pricing pressure stems from metabolite characterization cost inflation as EPA secondary metabolite standards extend registration preparation timelines. Agricultural retail cooperatives in Iowa and Illinois exhibit highest price sensitivity through pooled negotiating leverage, whereas greenhouse operators in Florida absorb premiums for zero-residue guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian molasses suppliers and domestic soy-derived substrate processors, exposing U.S. bio-fungicide manufacturers to commodity agriculture cycle swings. Production gravity centers on North Carolina's Research Triangle bioreactor clusters, California's Sacramento-Davis formulation corridors, and Midwest belt fermentation feedstock zones. Raw material dependencies encompass molasses, soy meal, and specialized cryopreservation media for strain banking. Tariff exposure on imported fermentation equipment from Germany and Japan constrains capacity expansion timelines. Distribution runs through agricultural retail cooperatives in the Midwest, traditional agrichemical distributors serving independent retailers, and direct manufacturer-to-grower relationships bypassing intermediary markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA metabolite data requirements and fermentation infrastructure capital intensity are forcing consolidation among formulation-dependent competitors lacking captive bioreactor capacity. Weaker players face exit pressure as registration cost inflation and substrate volatility squeeze economics.
For Market Incumbents: Deepen backward integration into strain banking and cryopreservation infrastructure to secure metabolite consistency against emerging RNA interference platforms threatening conventional microbial dominance. Expand captive bioreactor capacity in North Carolina to offset single-source substrate vulnerability. Prioritize precision application compatibility testing to defend position against drone-spray technology entrants. For New Entrants and Emerging Players: Launch via agricultural cooperative direct-sales channels in Iowa and Illinois, bypassing distributor markups that incumbent conglomerates cannot match without channel conflict. Target greenhouse premium segments in Florida and Texas where zero-residue pricing power justifies specialized formulation development. Exploit white-space in bio-stimulant bundling for USDA Organic certification pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play biological specialists with proprietary screening platforms and EPA registration expertise in California and North Carolina. Five-to-ten-year viability hinges on metabolite standardization capabilities and cooperative distribution alignment. Watch EPA biopesticide registration queue velocity as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Bioreactor Capacity Expansion | Secures strain consistency and metabolite standardization against outsourced fermentation cost volatility. |
| Metabolite Fingerprinting Investment | Accelerates EPA FIFRA Section 3(c)(5) registration timelines and defends against data package cost inflation. |
| Precision Application Compatibility Testing | Unlocks drone and variable-rate spray infrastructure adoption in Midwest row-crop channels. |
| Agricultural Cooperative Distribution Partnership | Bypasses traditional agrichemical distributor markups and captures margin in pooled procurement markets. |
| RNA Interference Platform Development | Displaces conventional microbial solutions in greenhouse premium segments with targeted pathogen suppression. |
Research Methodology
Independent corroboration across EPA registration filings, USDA organic certification databases, and state-level pesticide regulation records underwrites the qualitative findings. Primary interviews with fermentation process engineers, EPA biopesticide registration consultants, agricultural cooperative procurement managers, and specialty crop growers in California and Florida combined with secondary validation from SEC 10-K disclosures, customs substrate import data, and trade association production surveys. Bottom-up strain-level production estimates and top-down market sizing triangulate volume figures.
Comparable-period anchoring to historical EPA registration approval timelines and fermentation capacity utilization rates structured the forecast window. Segmentation dimensions encompass product type, application environment, end-user category, and distribution channel across the projection horizon. CAGRs derive from installed bioreactor capacity expansion curves, cooperative procurement penetration rates, and metabolite standardization cost trajectories. Forecast inputs include molasses price index movements and greenhouse acreage expansion in Florida and Texas.
The model assumes a particular technology adoption path; alternative pathways for RNA interference and peptide-based bio-fungicides would alter the outlook. Forecasts reflect assumptions regarding EPA metabolite data requirement stability and substrate supply contract availability. Regulatory acceleration or deceleration, fermentation input cost spikes, and precision application infrastructure rollout pace constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market