
 Global Female Contraceptive Market | 2026-2036
Global Female Contraceptive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Female Contraceptive Market Foresight
Indian generic pharmaceutical producers is decoupling from Western API dependency for oral contraceptive manufacturing. Bayer AG leverages its integrated hormone synthesis operations to sustain supply chain control across European and Asian markets. Pfizer Inc. competes through R&D intensity in novel progestin formulations, while Organon & Co. anchors its position through specialized portfolio focus on women's health beyond contraception alone.
Global female contraceptives comprise pharmacological and mechanical interventions designed to prevent pregnancy through hormonal suppression of ovulation, physical barrier mechanisms, or copper-ion spermicidal action, with efficacy rates varying by method from typical-use ranges of 75-99%. These products serve clinical family planning, menstrual regulation, and fertility management purposes across institutional and retail channels. Intrauterine devices and long-acting reversible contraception capture the strongest margin pools due to extended duration and reduced patient compliance burden, while oral pills retain volume leadership through pharmacy accessibility and established prescribing patterns among gynecologists.
FDA oversight governs new drug applications and device premarket approvals for hormonal implants and vaginal rings in the United States, while the EMA's Medical Device Regulation and REACH chemical safety standards shape market access across European member states. India's CDSCO and BIS standards enforce quality benchmarks for domestically manufactured and imported contraceptive supplies. Stakeholders must monitor evolving reimbursement frameworks at national health systems and the pace of biosimilar erosion in hormonal segments.
Market Dynamics
Long-acting reversible contraception is compressing oral pill volumes as healthcare systems prioritize patient compliance and reduced clinic visit frequency over pharmacy-dispensed daily regimens.
Growth Catalysts
- India's National Family Planning Program:Government-funded health centers are expanding subsidized IUD and implant distribution networks into rural districts, creating volume anchors for domestic manufacturers.
- FDA 510(k) Pathway Streamlining:Accelerated premarket review for hormonal ring modifications is reducing time-to-market for next-generation progestin formulations.
- Copper IUD Synthesis Automation:Continuous wire-drawing and frame-molding equipment is cutting per-unit production costs for non-hormonal device manufacturers.
Market Restraints
- API Import Dependency:Levonorgestrel and etonogestrel active pharmaceutical ingredient supply concentrates among Chinese and European specialty chemical producers, exposing formulators to freight cost volatility.
- EU MDR Compliance Burden:Enhanced clinical evidence requirements for Class III contraceptive devices are extending certification timelines and inflating regulatory affairs headcount.
- Surgical Sterilization Persistence:Tubal ligation remains the dominant permanent method in Latin American public health systems, capping reversible method penetration in those markets.
Strategic Opportunities
- Sub-Saharan Africa Clinic Networks:Underpenetrated regions with rising contraceptive prevalence targets present first-mover advantages for implant insertion training programs.
- Telehealth Prescription Channels:Direct-to-patient hormonal pill delivery platforms are bypassing traditional pharmacy distribution in North American and European urban markets.
- Biodegradable Subdermal Implants:Convergence of polymer science and controlled-release engineering promises elimination of removal procedures, addressing patient acceptance barriers.
Industry Challenges
- Insertion Training Capacity:IUD and implant placement requires certified provider networks; gynecological workforce shortages in rural United States and Indian states limit service availability.
- Legacy ERP Integration:Established manufacturers face data migration friction when connecting batch manufacturing records to cloud-based quality management systems for FDA and EMA audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Female Contraceptive Market |
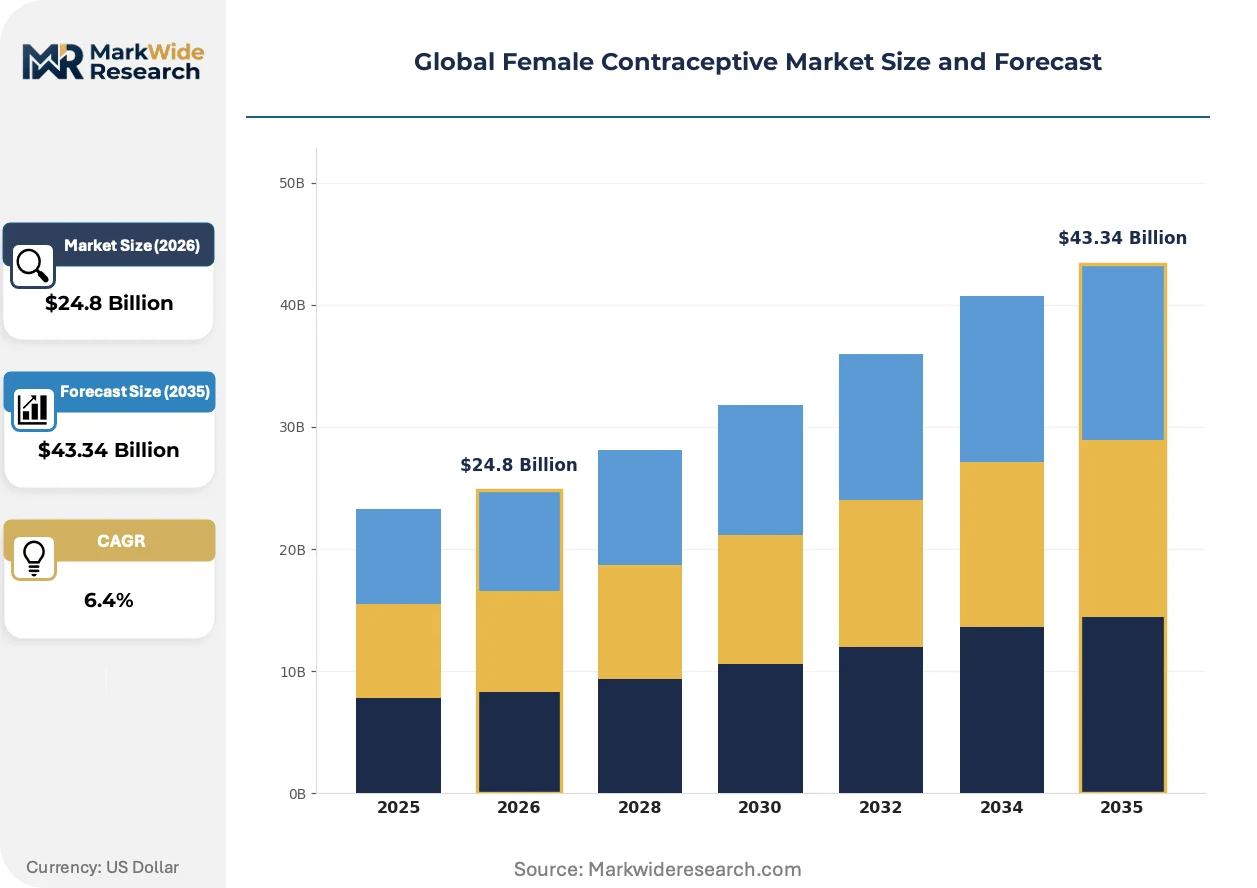
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Pills, Contraceptive Implants, Intrauterine Devices, Vaginal Rings, Injectable Contraceptives Technology: Hormonal, Non-Hormonal, Barrier, Long-Acting Reversible Contraception, Natural Methods Application: Birth Control, Family Planning, Menstrual Regulation, Population Control, Fertility Management End User: Gynecologists, Family Planning Clinics, Hospitals, Pharmacies, Health Centers |
| Companies Covered | Bayer AG, Pfizer Inc., Organon & Co., Teva Pharmaceutical Industries, Johnson & Johnson, Merck & Co., Inc., CooperSurgical Inc., Viatris Inc., Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Female Contraceptive Market Shifts & Advancements
Biodegradable materials and digital adherence tools are reshaping product architecture, while regulatory convergence across FDA and EMA frameworks is compressing development cycle variance for multinational contraceptive portfolios.
Hormonal microarray patches are modularizing delivery system design by separating drug reservoir layers from adhesive backing structures. Family planning clinics in Scandinavian health systems are piloting these formats for patients with oral pill adherence difficulties. This architecture is modularizing supplier relationships, allowing device assemblers to swap API sources without redesigning entire product platforms.
REACH chemical safety standards are tightening scrutiny of phthalate plasticizers in vaginal ring elastomers, forcing reformulation toward bio-based alternatives. European notified bodies are demanding migration studies for new polymer candidates, adding 12-18 months to technical documentation preparation. Hormonal ring manufacturers with early bio-elastomer investments are capturing preferential positioning in EU tender processes.
Self-administered subcutaneous depot injections are displacing clinic-dependent intramuscular delivery for progestin-only methods. Pharmacy chains in the United Kingdom and Australia are expanding training programs to support patient self-injection competence. This behavioral shift is most visible among 25-34 year-old cohorts seeking method control without provider gatekeeping.
Global Female Contraceptive Market Segmentation
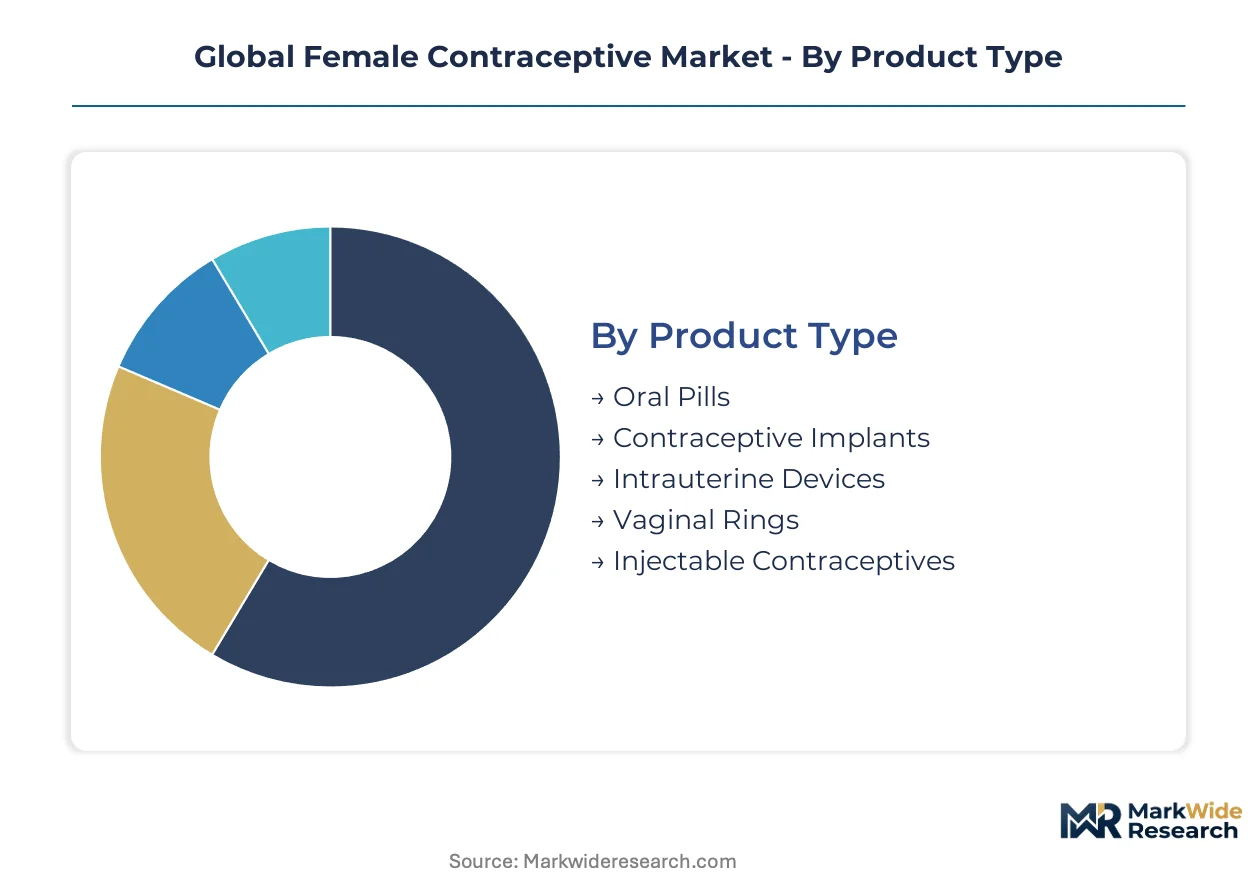
Product architecture and delivery mechanisms fragment the Global Female Contraceptive Market into distinct competitive arenas. Each segment carries unique manufacturing requirements, regulatory pathways, and margin structures that reshape supplier positioning.
Product Type:
Supply concentration for active pharmaceutical ingredients and device components clusters around distinct manufacturing geographies for each format.
- Intrauterine Devices:Copper and hormonal IUDs require precision polymer molding and wire-drawing capabilities. Indian domestic manufacturers and European specialty device firms capture volume from government procurement programs in India and Scandinavian national health systems.
- Contraceptive Implants:Subdermal rods demand controlled-release polymer engineering and sterile rod-extrusion lines. Demand concentrates in Sub-Saharan Africa clinic networks and Southeast Asian public health programs seeking multi-year protection without daily compliance.
- Oral Pills:High-volume tablet pressing and coating operations dominate pharmaceutical manufacturing.
- Vaginal Rings:Elastomer formulation and drug-reservoir integration define production.
- Injectable Contraceptives:Depot formulations require sterile fill-finish capacity and cold-chain logistics.
Intrauterine Devices absorb the bulk of installed capacity; Contraceptive Implants are expanding most quickly.
Technology:
Cost tier stratification separates premium hormone synthesis from commodity barrier manufacturing.
- Long-Acting Reversible Contraception:Implants and hormonal IUDs deploy progestin-eluting polymers or copper-ion mechanisms. European notified bodies under EU MDR and FDA premarket approval pathways govern access, with reimbursement concentration in Germany, France, and United Kingdom national formularies.
- Hormonal:Synthetic progestin and estrogen combinations suppress ovulation through oral, transdermal, or intravaginal delivery.
- Non-Hormonal:Copper IUDs and barrier methods avoid endocrine disruption concerns.
- Barrier:Physical obstruction methods carry lower regulatory burden.
- Natural Methods:Fertility awareness tracking requires no pharmaceutical or device manufacturing.
Long-Acting Reversible Contraception commands premium pricing tiers; Hormonal methods retain volume leadership through pharmacy accessibility.
Application:
Customer type differentiation separates clinical prescription from over-the-counter access channels.
- Birth Control:Pregnancy prevention drives the majority of product utilization across all delivery formats. Demand clusters in United States retail pharmacies and Indian government health centers, with telehealth platforms in United Kingdom and Australia expanding direct-to-patient access.
- Family Planning:Clinical counseling and method selection services anchor institutional procurement.
- Menstrual Regulation:Hormonal methods address cycle management beyond contraception alone.
- Population Control:National policy programs drive bulk purchasing in China and India.
- Fertility Management:Post-contraceptive restoration of ovulation guides method selection.
Birth Control absorbs the bulk of installed capacity; Family Planning is expanding most quickly through clinic network investments.
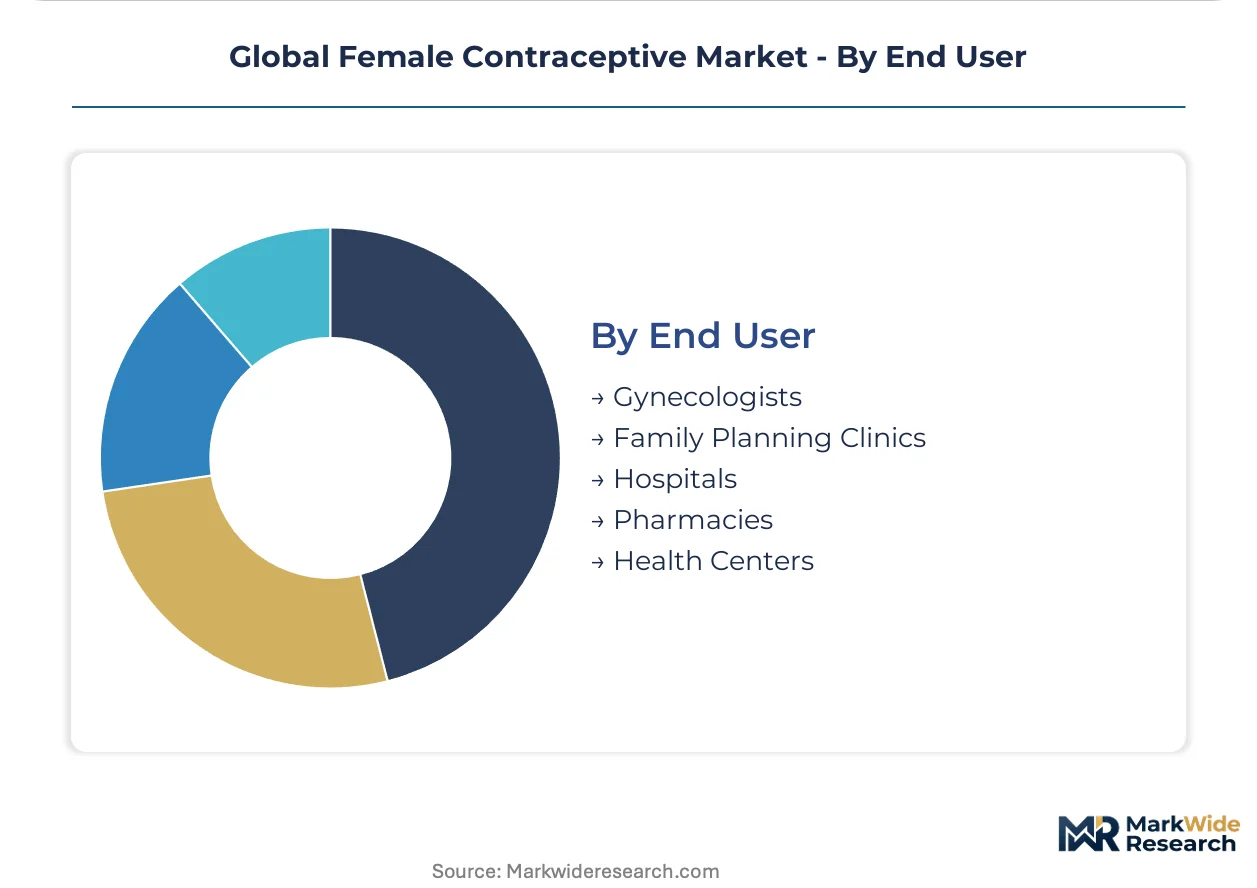
End User:
Margin structure varies sharply between institutional tender processes and retail pharmacy markups.
- Family Planning Clinics:Specialized reproductive health centers combine counseling with device insertion services. Volume concentrates in India's National Family Planning Program rural expansion and Planned Parenthood affiliate networks across United States metropolitan areas.
- Gynecologists:Private practice specialists prescribe premium hormonal and long-acting methods.
- Hospitals:Acute care settings manage postpartum contraceptive counseling.
- Pharmacies:Retail chains dominate oral pill and condom distribution.
- Health Centers:Primary care facilities bridge clinical and community access.
Family Planning Clinics absorb the bulk of installed capacity; Pharmacies are expanding most quickly through telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Levonorgestrel and etonorgestrel API synthesis clusters in Chinese coastal provinces and European specialty chemical corridors, anchoring supply-side geography for formulators worldwide. Demand-side expansion concentrates in government-funded health systems and private clinic networks across five national markets.
United States
Planned Parenthood affiliate networks and independent gynecology practices drive long-acting reversible contraception uptake in metropolitan corridors. FDA premarket approval pathways govern hormonal implant and vaginal ring introductions, with 510(k) streamlining reducing review timelines for next-generation progestin formulations. Texas and Florida health center expansions face workforce constraints for IUD insertion certification.
India
Government-funded health centers under the National Family Planning Program subsidize copper IUD and implant distribution into rural districts, creating volume anchors for domestic manufacturers. CDSCO quality benchmarks and BIS standards enforce compliance for locally produced and imported supplies. Maharashtra and Gujarat pharmaceutical clusters host tablet pressing and hormone synthesis operations serving public procurement tenders.
Germany
National health system reimbursement concentration in Germany, France, and United Kingdom formularies drives premium-tier hormonal IUD prescribing patterns. EU Medical Device Regulation clinical evidence requirements extend certification timelines for Class III contraceptive devices. Baden-Württemberg specialty polymer molding facilities supply precision components for European device manufacturers.
Brazil
Tubal ligation persistence in Latin American public health systems caps reversible method penetration, though municipal family planning clinics in São Paulo and Rio de Janeiro expand implant insertion capacity. ANVISA pharmaceutical registration governs hormonal product market access. Southeast pharmaceutical distributors bridge import logistics for API-dependent domestic formulators.
Australia
Pharmacy chains in Sydney and Melbourne expand patient self-injection training programs for subcutaneous depot progestin delivery, displacing clinic-dependent intramuscular administration. TGA therapeutic goods administration oversees hormonal product registration and post-market surveillance. Urban telehealth platforms bypass traditional pharmacy distribution for direct-to-patient hormonal pill access.
Global Female Contraceptive Market Competitive Landscape
Global majors compete with regional champions across API synthesis, device manufacturing, and distribution reach. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates controlling hormone supply chains, specialized women's health spin-offs focusing on gynecological portfolios, and generic manufacturers competing on public tender pricing. Strategic moves concentrate on backward integration into API production and geographic expansion through clinic network partnerships.
Within the integrated pharmaceutical tier, Bayer AG exemplifies captive hormone synthesis operations sustaining supply chain control across European and Asian markets. Pfizer Inc. and Organon & Co. occupy positions on the R&D-intensive and women's health specialization vectors respectively, with the latter anchoring portfolio focus beyond contraception alone. These three entities represent distinct competitive archetypes: upstream-integrated supply chain command, novel formulation development intensity, and vertical therapeutic area concentration.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Organon & Co. |
| Teva Pharmaceutical Industries |
| Johnson & Johnson |
| Merck & Co., Inc. |
| CooperSurgical Inc. |
| Viatris Inc. |
| Church & Dwight Co., Inc. |
| Others |
Supply & Pricing Matrix
Levonorgestrel API spot prices in Chinese coastal provinces cascade through three distinct pricing tiers for finished hormonal contraceptives, with European specialty chemical producers commanding premium positioning against Indian generic formulators competing on public tender economics.
Pricing Analysis
Insertion training and device removal warranties separate premium-tier hormonal IUD vendors from unbundled commodity suppliers in government procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA premarket approval status versus CE marking equivalence versus non-certified regional alternatives. Cost compression in the economy tier is intensifying because Indian domestic manufacturers are absorbing API freight volatility to defend rural health center contracts. Public health systems in Sub-Saharan Africa exhibit highest price sensitivity; private gynecology practices in Germany and France demonstrate lowest sensitivity due to reimbursement concentration.
Supply Chain Analysis
Device return and copper IUD refurbishment flows remain underdeveloped, creating stranded asset risk for expired implant inventory in clinic cold chains. API synthesis concentrates in Chinese coastal provinces, European specialty chemical corridors, and Maharashtra pharmaceutical clusters. Controlled-release polymer rods, sterile extrusion equipment, and hormone precursor chemicals constitute critical input dependencies. Single-source vulnerability characterizes etonogestrel API supply from select European producers. Distribution runs through government procurement warehouses for volume tenders and specialty medical distributors for private clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
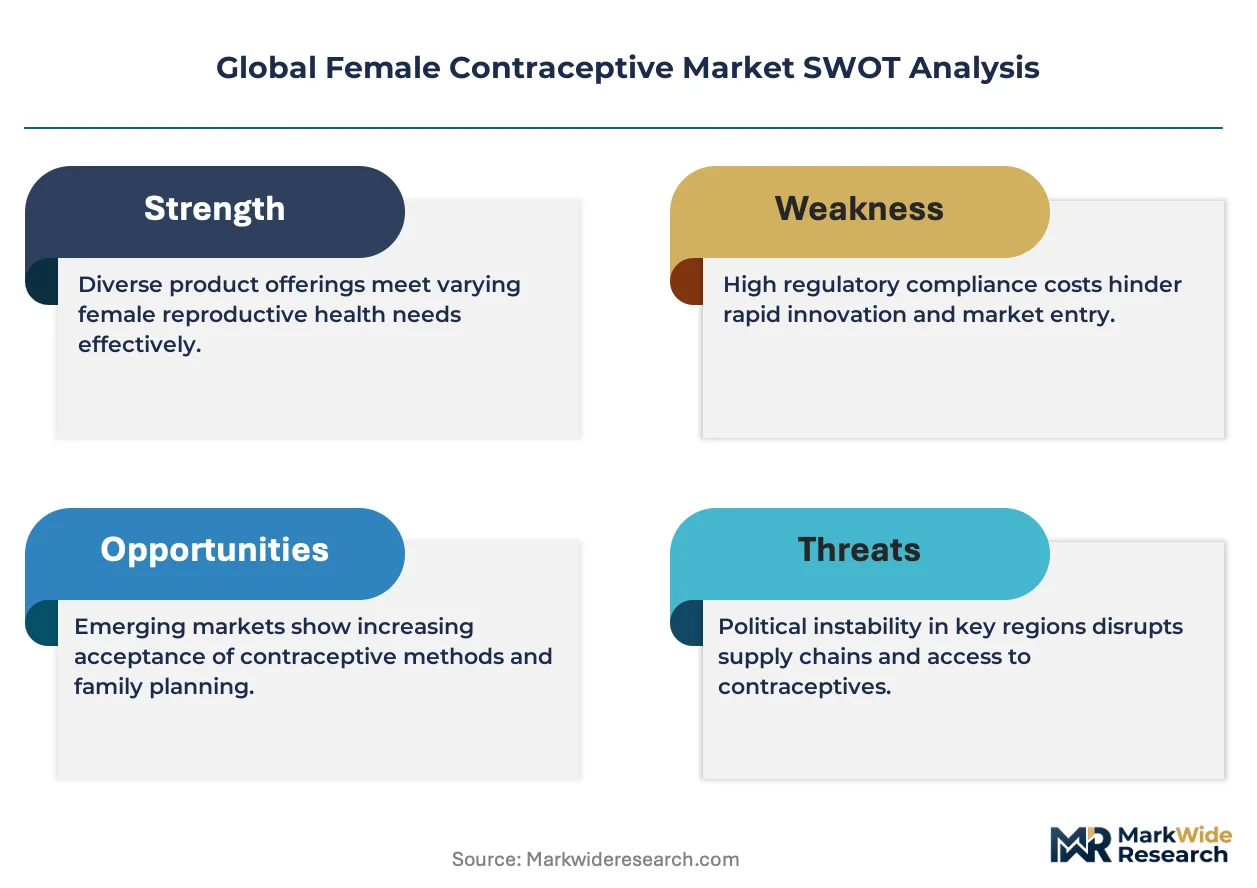
EU MDR clinical evidence requirements for Class III contraceptive devices erect a cost-of-compliance barrier that favors incumbent players with established notified body relationships and regulatory affairs infrastructure.
For Market Incumbents: Hedge against biosimilar erosion in hormonal segments by deepening backward integration into API synthesis operations and securing multi-year offtake agreements with Indian government health centers. Bayer AG's captive hormone production model offers a template for supply chain control. Threat: Chinese API producers expanding downstream into finished dosage form manufacturing. Lever: Certification investment in EU MDR technical documentation ahead of competitor timelines.
For New Entrants and Emerging Players: Telehealth prescription platforms offer a direct-to-patient route that bypasses entrenched pharmacy distribution and clinic gatekeeping in North American and Australian urban markets. White-space targets: biodegradable subdermal implant development and self-administered subcutaneous depot injection formats. Most penetrable segment: 25-34 year-old cohorts seeking method control without provider dependency. Go-to-market angle: Partnership with pharmacy chains for patient self-injection training certification.
For Investors and Strategic Acquirers: Distressed-cycle entries favor women's health portfolio specialists with EU MDR transition completion in Germany and United Kingdom markets over the next five-to-ten year window. Acquisition target archetype: Controlled-release polymer engineering firms with sterile rod-extrusion capabilities and existing notified body relationships. Signal to watch: ANVISA registration timeline acceleration for hormonal implants in Brazilian municipal clinic networks as inflection indicator for Latin American reversible method penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Notified body pre-submission meetings with TÜV SÜD or BSI accelerate Class III device certification timelines. |
| Backward Integration into API Synthesis | Captive levonorgestrel production insulates formulators from Chinese freight cost volatility and supply disruption. |
| Biodegradable Implant Polymer Development | PLGA and PCL polymer science convergence eliminates removal procedure barriers in patient acceptance research. |
| Telehealth Platform Partnership | Direct-to-patient hormonal pill delivery in United Kingdom and Australian urban markets bypasses pharmacy markup layers. |
| Sub-Saharan Africa Clinic Network Expansion | Implant insertion training programs in underpenetrated regions capture first-mover advantages in rising prevalence markets. |
Research Methodology
Document review covered FDA 510(k) filings, EMA MDR technical documentation, CDSCO registration databases, and Indian government procurement tender records, complemented by interviews with regulatory affairs directors at hormonal device manufacturers, gynecology clinic network administrators, and pharmaceutical procurement officers at national health systems. Secondary validation drew from WHO contraceptive prevalence databases, national family planning program expenditure reports, and trade flow data for API imports. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, and end-user segments.
Quantitative outputs span volume and value projections across the analysis window, with segmentation dimensions including delivery mechanism format, hormonal versus non-hormonal technology classification, and institutional versus retail channel end-use. CAGRs derive from regression analysis of historical procurement volume trends, adjusted for policy program expansion timelines and reimbursement framework evolution. Industry-specific forecast inputs incorporate EU MDR certification pipeline visibility and Indian National Family Planning Program rural district penetration targets.
The model holds under stable regulatory enforcement timelines and continued government health center funding commitments; deviation in API export restriction policies or MDR notified body capacity constraints would shift volume trajectories. Practitioners should monitor CDSCO quality benchmark enforcement intensity and ANVISA registration acceleration signals for early indicators of supply-side constraint or demand-side inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Global Encephalitis Vaccine Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Nicorandil Market