
 Asia-Pacific Retort Packaging Market | 2026-2036
Asia-Pacific Retort Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Retort Packaging Market Outlook
Vietnam is fragmenting as new flexible packaging lines enter the Mekong Delta industrial corridor. Toyo Seikan Group Holdings anchors high-barrier retort can production across Japan and Thailand. Amcor leverages its regional film extrusion network to supply multilayer laminates for shelf-stable food brands. Huhtamaki Oyj competes through specialized retort lidding solutions targeting ASEAN dairy processors.
Asia-Pacific retort packaging comprises sterilizable multilayer structures—typically aluminum foil or metallized film sandwiched between polypropylene and polyester—that withstand 121°C thermal processing for commercial sterility. These constructions enable ambient distribution of low-acid foods without refrigeration dependency. Stand-up pouches capture premium positioning in ready-meal segments where shelf differentiation and microwave convenience command higher unit economics. Aluminum-based barrier layers retain dominance in long-life military and emergency rations despite sustainability-driven material substitution trials. Rigid containers sustain volume in institutional foodservice channels across South Korea and Australia where portion consistency and stackability outweigh flexible alternatives.
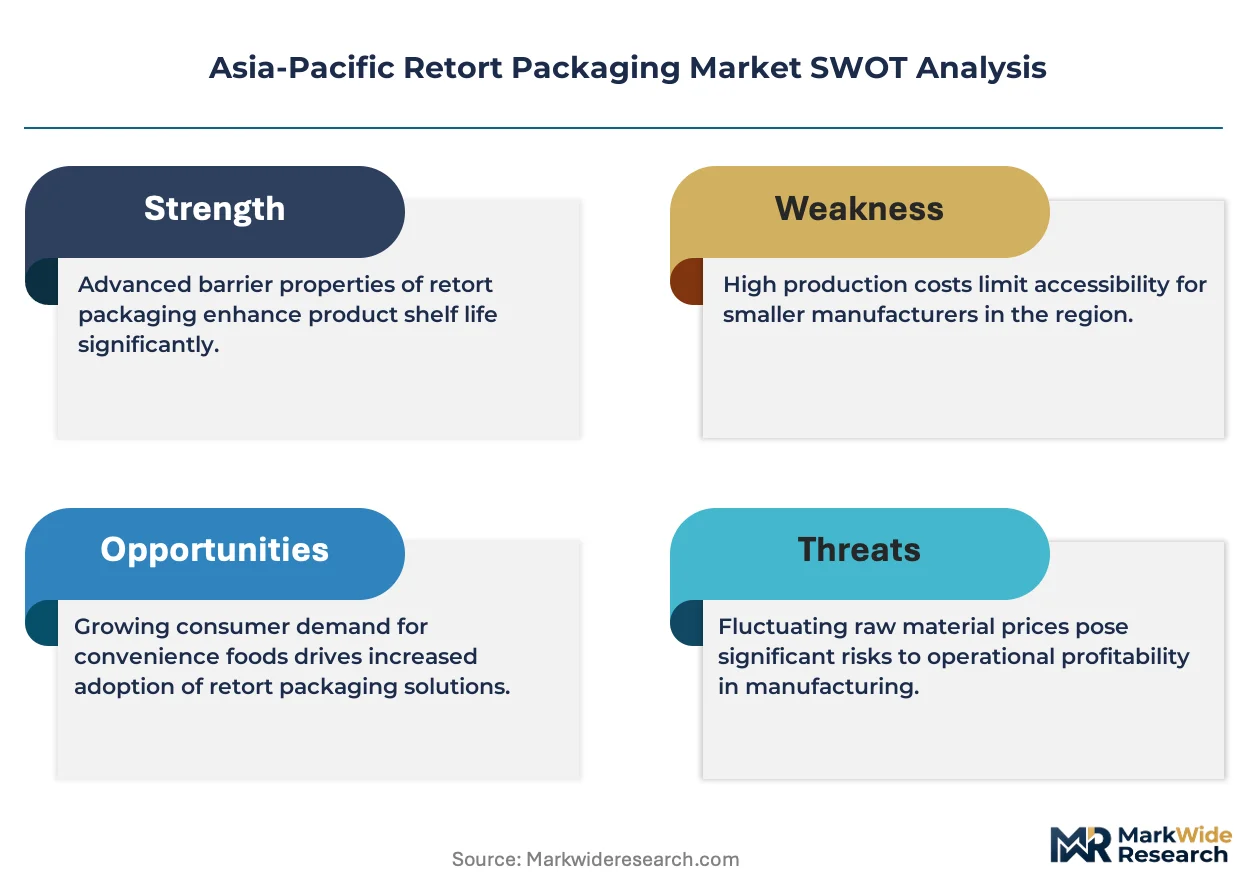
Japan's PMDA and METI coordinate food-contact notification protocols that delay new material introductions by 12-18 months. India's FSSAI enforces incremental migration limits for retort adhesives and coatings that reshape supplier qualification criteria. China's SAMR implements GB standards for composite food packaging that mandate batch-level traceability. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and country-specific pre-market approval regimes to avoid stranded capacity investments.
Market Dynamics
Japan's METI and PMDA notification protocols are compressing new material introduction timelines, forcing suppliers to front-load regulatory capital before commercial deployment across Asia-Pacific sterilizable packaging markets.
Growth Catalysts
- Urban ready-meal consumption:Working households across Bangkok, Jakarta, and Ho Chi Minh City are adopting shelf-stable prepared foods. This demand pull is accelerating flexible retort pouch line investments in Vietnam's Mekong Delta industrial corridor.
- FSSAI migration limits:India's enforcement of incremental thresholds for retort adhesives and coatings is filtering supplier bases. Qualified material providers are capturing expanded share in South Asian dairy and curry exports.
- Aluminum barrier performance:Metallized film and foil laminates retain dominance in military and emergency ration specifications. Long-life ambient storage requirements sustain premium positioning against bio-based alternatives.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyester resin prices fluctuate with naphtha cracking economics. Margin compression is acute for converters lacking backward integration into polymer supply.
- Regulatory fragmentation:Divergent pre-market approval regimes between ASEAN harmonization efforts and country-specific protocols strand capacity. METI's 12-18 month notification delays diverge from China's SAMR batch-traceability mandates.
- Mechanical recycling incompatibility:Multilayer aluminum-PP-polyester structures resist conventional reprocessing. Collection infrastructure gaps in Indonesia and the Philippines block circular economy positioning.
Strategic Opportunities
- Rural India penetration:Cold-chain-deficient interior states present ambient distribution advantages. Retort pouches for pulses, dairy, and traditional sweets address preservation gaps in Uttar Pradesh and Bihar.
- Pet food premiumization:Human-grade ingredient positioning in Australia and Japan is driving single-serve retort formats. Wet food shelf stability without refrigeration enables veterinary and specialty retail channels.
- China dual carbon alignment:SAMR guidelines for composite packaging traceability favor domestic suppliers with integrated extrusion-printing-converting capabilities. Energy-efficient retort processing equipment qualifies for provincial green manufacturing incentives.
Industry Challenges
- High-barrier adhesive formulation:Retort-grade laminating adhesives require specialized chemistry expertise scarce in Southeast Asian technical labor pools. Migration-compliant bonding agents demand 18-24 month qualification cycles.
- Legacy equipment retrofit costs:Converting lines designed for conventional flexible formats require substantial modification for precision seal integrity at 121°C sterilization. Capital deployment timelines extend payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Retort Packaging Market |
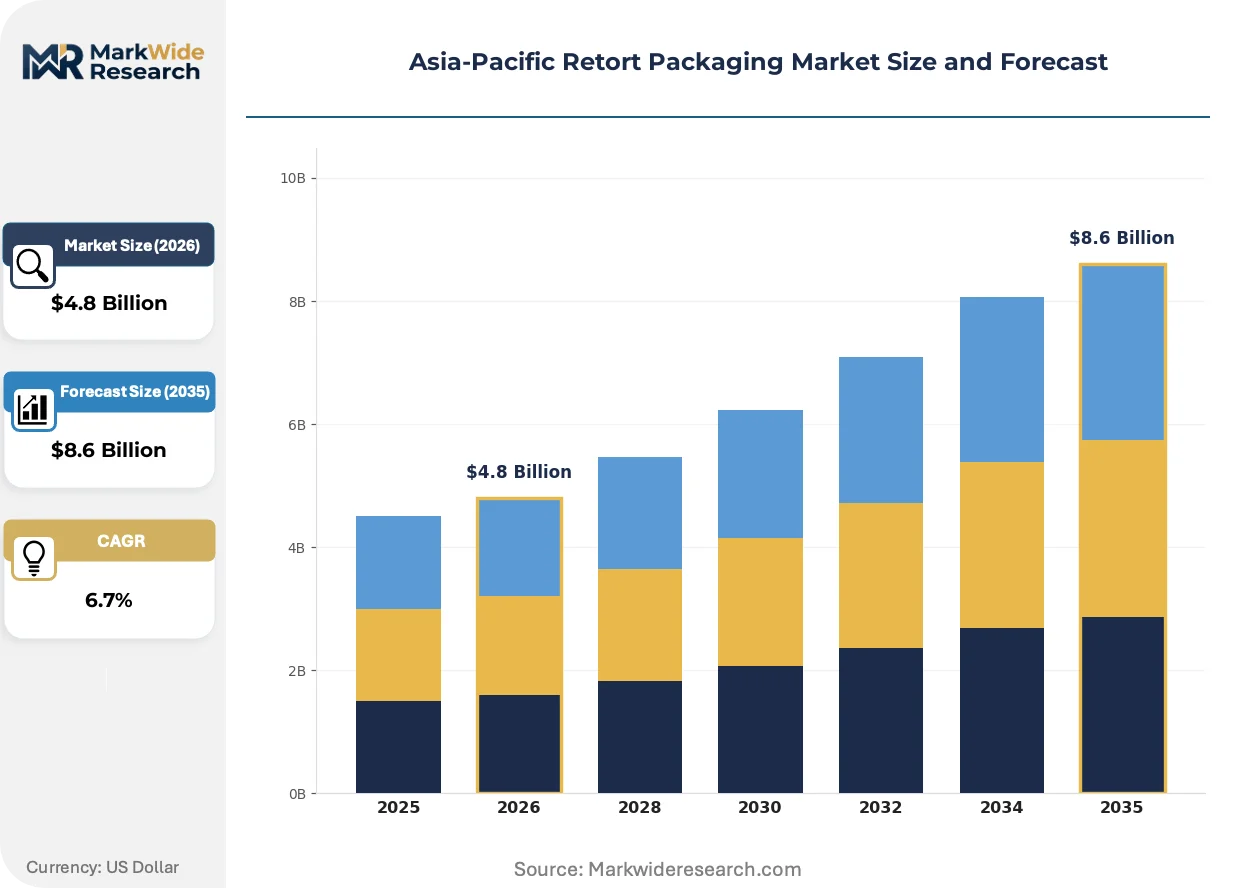
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Vacuum Pouches, Rigid Containers, Sachets Material: Aluminum, Polypropylene, Polyester, Nylon End User: Food Industry, Beverage Sector, Pharmaceutical, Personal Care Packaging Type: Flexible Packaging, Rigid Packaging, Pouches, Trays |
| Companies Covered | Sonoco Products Company, Coveris, Toyo Seikan Group Holdings, ProAmpac, Huhtamaki Oyj, Amcor, Sealed Air Corporation, Constantia Flexibles, Mondi Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Retort Packaging Market Strategic Shifts
Digital integration is penetrating sterilization validation and supply chain verification, while regulatory authorities tighten material traceability requirements across the Asia-Pacific food-contact landscape.
Smart retort monitoring systems are digitizing thermal process documentation. Seafood processors in China's Yangtze River Delta are deploying IoT-enabled autoclave sensors to log F0 values in real time. This data capture is digitizing compliance reporting for SAMR batch-traceability mandates while compressing audit preparation labor.
Japan's METI is coordinating revised food-contact notification protocols with PMDA pharmaceutical-grade material standards. The industrial consequence is elevated documentation burdens for new barrier film introductions. Ready-meal manufacturers are responding by consolidating supplier relationships around established qualified material providers.
Direct-to-retail procurement patterns are consolidating buyer power among Asia-Pacific supermarket chains. Private-label ready-meal programs in South Korea and Australia are bypassing traditional distributor networks. This channel compression is most visible in Melbourne and Sydney, where Coles and Woolworths are specifying custom retort pouch formats for their ambient meal ranges.
Asia-Pacific Retort Packaging Market Segmentation
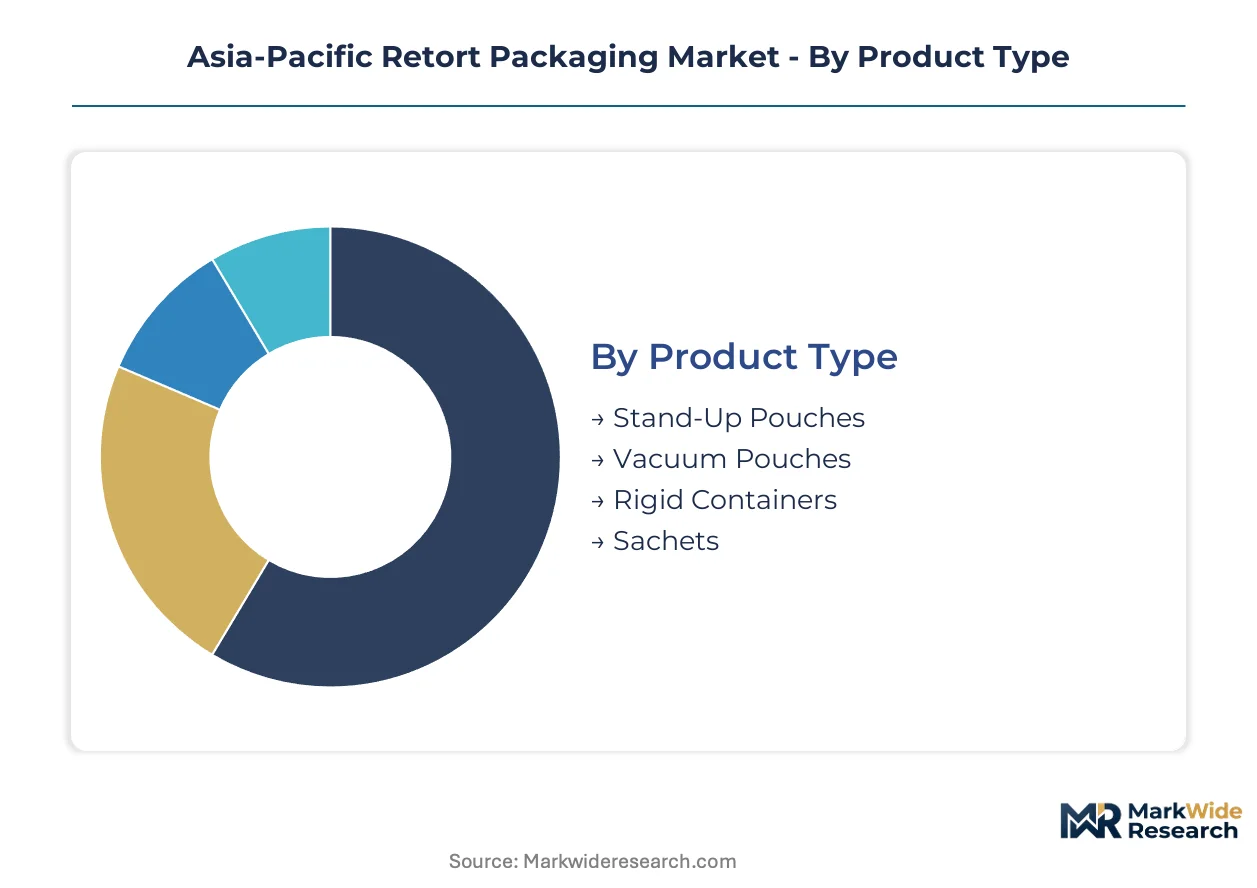
Retort packaging configurations vary sharply across sterilization requirements, barrier performance, and distribution economics. Material selection and format geometry determine thermal processing compatibility and shelf-life extension for ambient-stored products.
Product Type:
Cost tier stratification separates premium convenience formats from commodity bulk packaging across Asia-Pacific food manufacturing.
- Stand-Up Pouches:Multilayer laminated structures with gusseted bases enable vertical shelf presentation and microwave venting. Premium ready-meal brands in Japan and South Korea specify these for retail differentiation and consumer convenience.
- Vacuum Pouches:High-barrier metallized or aluminum foil laminates eliminate headspace oxygen to extend protein shelf stability. Seafood processors in China's Yangtze River Delta and Vietnam's Mekong Delta concentrate procurement here for export-grade preservation.
- Rigid Containers:Polypropylene or polyester trays with sealed lidding suit institutional portion control. South Korean and Australian foodservice channels favor stackability and mechanical protection over flexible alternatives.
- Sachets:Small-format three-side-seal pouches deliver single-serve condiments and sauces. Mass-market penetration in India and Indonesia drives volume through low unit economics.
Rigid containers command the established base in institutional channels. The steepest expansion runs through stand-up pouches capturing premium retail positioning.
Material:
Application requirements dictate barrier-layer selection between metalized shielding and polymer flexibility for thermal processing compatibility.
- Aluminum:Foil or metallized film laminates deliver near-zero oxygen and moisture transmission for multiyear shelf life. Military and emergency ration specifications in Japan and Australia sustain demand despite sustainability scrutiny.
- Polypropylene:Sealant layers and structural substrates withstand 121°C autoclave cycles without deformation. India's FSSAI-compliant dairy and curry exports rely on PP-based constructions for migration-limit adherence.
- Polyester:Outer web printability and mechanical strength support high-speed form-fill-seal operations. ASEAN beverage and personal care applications favor PET clarity and dimensional stability.
- Nylon:Intermediate layers provide puncture resistance and toughness for bone-in meat and seafood. Processing complexity limits adoption versus commodity alternatives.
Aluminum barrier configurations anchor long-life specifications. Polypropylene is gaining share fastest through regulatory-compliant food-contact expansion.
End User:
Customer type diversity spans from mass-market food manufacturing to specialized pharmaceutical sterilization requirements.
- Food Industry:Ready-meals, seafood, pet food, and traditional preserves dominate procurement. Urban consumption shifts in Bangkok, Jakarta, and Ho Chi Minh City accelerate flexible pouch adoption.
- Beverage Sector:Retortable cartons and pouches for coconut water, coffee, and dairy alternatives. Shelf-stable distribution without cold chain suits Southeast Asian infrastructure gaps.
- Pharmaceutical:Sterilizable barrier packaging for medical devices and nutritional preparations. Japan's PMDA notification protocols extend material qualification timelines.
- Personal Care:Cosmetic and hygiene products requiring thermal stability for preservative-free formulations. Niche positioning limits scale versus food applications.
Food industry procurement commands volume leadership. Pharmaceutical specifications are climbing the fastest through regulatory tightening.
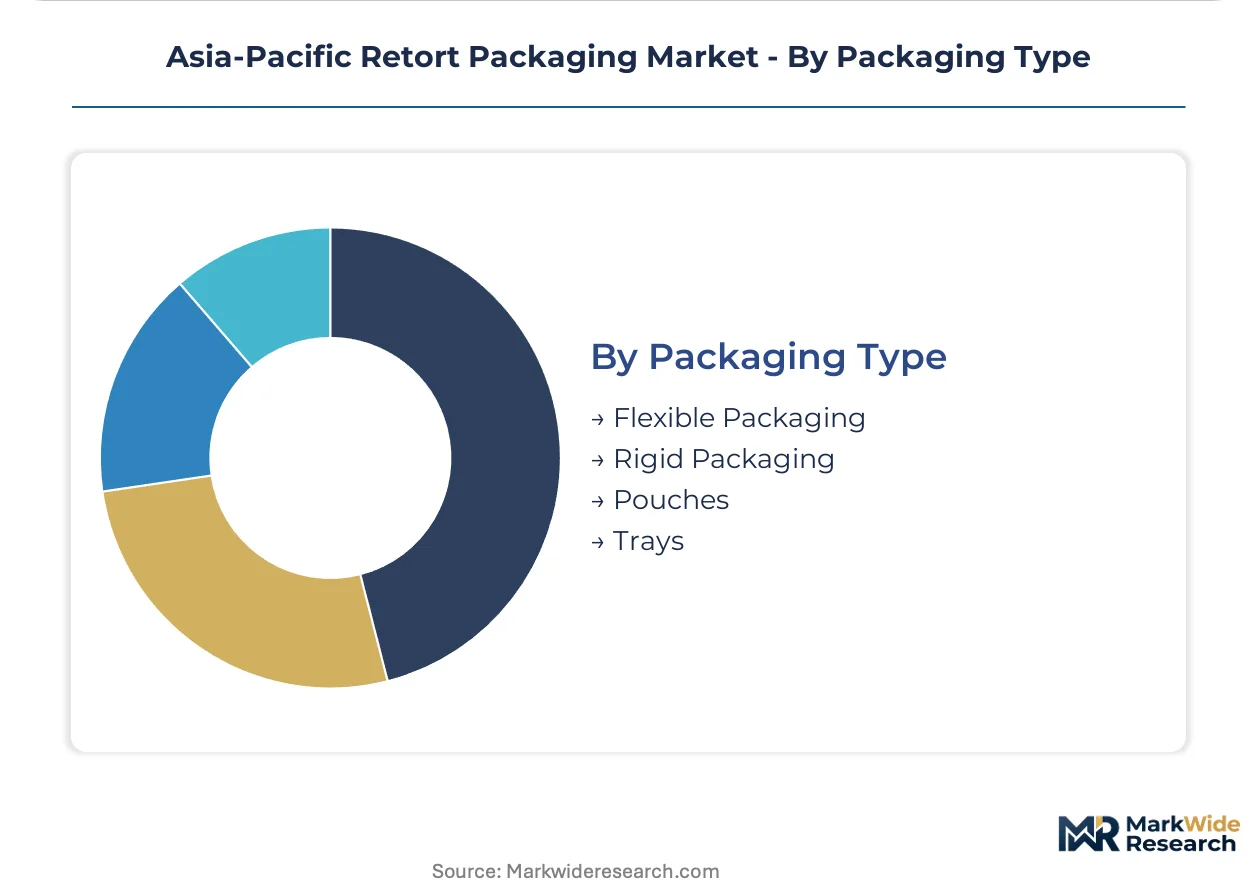
Packaging Type:
Volume and margin profiles diverge between flexible film converting and rigid thermoforming operations.
- Flexible Packaging:Roll-fed laminates and preformed pouches minimize material weight and shipping cube. China's integrated extrusion-printing-converting clusters achieve cost compression at scale.
- Rigid Packaging:Thermoformed trays and injection-molded containers protect fragile contents. Australian and South Korean retail chains specify these for premium private-label meal presentation.
- Pouches:Stand-up and flat formats bridge flexible efficiency with retail-ready functionality. Vietnam's Mekong Delta corridor attracts dedicated production line investments.
- Trays:Lidded rigid or semi-rigid formats for ovenable and microwaveable convenience. Portion consistency appeals to healthcare and senior nutrition programs.
Flexible packaging holds the volume base through material efficiency. Pouch configurations are expanding most quickly via convenience-format premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's food-contact notification protocols anchor Japan's dominant regulatory position across Asia-Pacific sterilizable packaging markets. Country-specific pre-market approval regimes create divergent compliance burdens that reshape supplier qualification and capacity deployment patterns.
Japan
Ready-meal brands in Tokyo and Osaka specify stand-up pouches for retail differentiation and microwave convenience. METI coordinates with PMDA to enforce pharmaceutical-grade material standards that extend new barrier film qualification timelines. Toyo Seikan Group Holdings anchors high-barrier retort can production across Kanto and Kyushu manufacturing bases.
China
Seafood processors in the Yangtze River Delta concentrate procurement of vacuum pouches for export-grade preservation. SAMR implements GB standards for composite food packaging that mandate batch-level traceability across all production runs. Integrated extrusion-printing-converting clusters in Shanghai and Jiangsu achieve cost compression at scale for domestic wet food brands.
India
Cold-chain-deficient interior states in Uttar Pradesh and Bihar present ambient distribution advantages for pulse and dairy retort formats. FSSAI enforces incremental migration limits for retort adhesives and coatings that filter supplier bases. Flexible packaging line investments accelerate in Gujarat and Maharashtra to serve South Asian curry export demand.
Vietnam
Working households in Ho Chi Minh City adopt shelf-stable prepared foods that pull flexible pouch demand. The country's national food safety authority maintains alignment with ASEAN harmonization efforts while retaining country-specific testing protocols. New flexible packaging lines enter the Mekong Delta industrial corridor to capture regional ready-meal growth.
Australia
Coles and Woolworths specify custom retort pouch formats for private-label ambient meal ranges in Melbourne and Sydney. TGA pharmaceutical-grade standards extend to sterilizable medical device packaging applications. Pet food premiumization drives single-serve retort formats for veterinary and specialty retail channels nationwide.
Asia-Pacific Retort Packaging Market Competitive Environment
Integrated multinationals and specialized regional converters split the market across distinct capability tiers. Consolidation pressure concentrates around qualified material providers capable of navigating 12-18 month regulatory notification cycles. Three archetypes dominate: film extrusion networks with backward polymer integration, specialized lidding and barrier solution providers, and rigid container specialists with canning heritage. Capacity expansion and strategic supplier consolidation represent the dominant competitive moves as brands seek to reduce qualification burden.
Among Asia-Pacific headquartered specialists, Toyo Seikan Group Holdings exemplifies the rigid container archetype with deep canning heritage across Japan and Thailand. Amcor occupies a position representing integrated film extrusion networks supplying multilayer laminates. Huhtamaki Oyj sits within the specialized solutions tier, anchoring retort lidding capabilities targeting ASEAN dairy processors. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Coveris |
| Toyo Seikan Group Holdings |
| ProAmpac |
| Huhtamaki Oyj |
| Amcor |
| Sealed Air Corporation |
| Constantia Flexibles |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
China's integrated extrusion-printing-converting clusters in Shanghai and Jiangsu feed the dominant supply position for multilayer laminates, capturing margin pools downstream at brand-specification and qualified-material tiers where FSSAI and METI compliance costs erect barriers.
Pricing Analysis
Geographic price spreads of 15-25% separate Yangtze River Delta manufacturing bases from ASEAN converter operations. Three-tier pricing structure across premium, standard, and economy levels reflects certification-grade differentiation, with METI-notified materials commanding substantial premia over generic alternatives. Price erosion runs through commodity pouch formats as Vietnam's Mekong Delta capacity expansion intensifies competition. Institutional buyers in South Korean foodservice channels exhibit lowest price sensitivity due to portion-consistency requirements, while Indian mass-market sachet procurement remains most cost-driven.
Supply Chain Analysis
Upstream polypropylene and polyester resin supply anchors in China, South Korea, and Japan, with naphtha-cracking economics feeding volatility into converter margins. Raw material procurement draws from petrochemical complexes in Dalian, Ulsan, and Yokkaichi, while aluminum foil supply rests on rolling mill capacity in Henan and Shandong provinces. Single-source vulnerability concentrates in high-barrier adhesive formulations where 18-24 month qualification cycles limit supplier switching. Distribution runs through integrated brand-converter relationships for qualified materials, with spot-market spot purchasing surviving only at commodity tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a regulatory-capital cycle as FSSAI and METI notification burdens peak, positioning qualified-material incumbents to capture margin expansion through the next urban ready-meal demand wave.
For Market Incumbents: Insulate specification relationships by accelerating backward integration into polymer compounding and adhesive formulation. Deploy capital toward Gujarat and Maharashtra flexible line expansion to capture Indian curry export growth. METI notification backlogs and 18-24 month qualification cycles protect entrenched positions against fast-follower threats.
For New Entrants and Emerging Players: Build out white-space presence in rural Uttar Pradesh and Bihar ambient distribution channels where cold-chain gaps favor retort preservation formats. Target pet food premiumization in Australia through single-serve wet food packaging specifications. Pursue veterinary and specialty retail channel partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging converters in Vietnam's Mekong Delta corridor lacking regulatory qualification depth. Long-term viability hinges on 5-10 year migration toward recyclable mono-material structures as ASEAN circular economy mandates mature. Watch for SAMR batch-traceability enforcement tightening as the inflection signal for integrated-versus-fragmentated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Investment | METI and FSSAI notification capabilities erect 12-18 month barriers against unqualified competitors. |
| Backward Integration into Polymer Compounding | In-house PP and PET supply hedges naphtha-cracking volatility compressing converter margins. |
| Rural India Distribution Partnership | Cold-chain-deficient interior states present ambient-ready-meal penetration opportunities. |
| Pet Food Single-Serve Format Development | Veterinary channel specifications in Australia and Japan command premium unit economics. |
| Energy-Efficient Retort Equipment Deployment | China's provincial green manufacturing incentives reward SAMR-compliant traceability integration. |
Study Parameters
Cross-validation between converter procurement data and regulatory filing records anchors the qualitative findings across Asia-Pacific sterilizable packaging markets. Primary interviews with film extrusion plant managers, FSSAI compliance officers at Indian dairy exporters, METI notification specialists, and ASEAN retail category buyers combined with secondary validation from SAMR GB standard publications, customs trade databases, and SEC filings from listed packaging multinationals. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Calibration against historical CAGRs from comparable flexible packaging segments informed the projection framework across the analysis window. Segmentation dimensions modeled include product format geometry, barrier material specification, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating urban household formation rates and ready-meal penetration indices. Industry-specific inputs include autoclave processing capacity expansion in the Yangtze River Delta and Mekong Delta industrial corridor investment pipelines.
Stress conditions across polypropylene resin price volatility, METI notification timeline extensions, and ASEAN harmonization failure scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution elasticity for aluminum barrier layers. Cross-checking against Japan Packaging Institute shipment statistics and China Plastics Processing Industry Association capacity surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Retort Machine Market