
 Middle East and Africa Aseptic Packaging Market | 2026-2036
Middle East and Africa Aseptic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aseptic Packaging Market Foresight
Extended-shelf-life grade specifications is bifurcating the Middle East and Africa Aseptic Packaging Market into performance-tier supply tiers. Tetra Pak International SA leverages its integrated carton-converting and filling-machine ecosystem to dominate ambient dairy across the Gulf. SIG Group AG anchors its position through regional filling-equipment service hubs that reduce downtime for Nigerian and Kenyan processors. Amcor Group GmbH differentiates via multilayer polymer expertise tailored to hot-climate distribution challenges.
Aseptic packaging denotes a sterilization-based containment system wherein product and package undergo separate thermal or chemical decontamination before sealed assembly under microbiologically controlled conditions, typically achieving commercial sterility with residual oxygen levels below 1% in barrier laminates. This technology enables ambient distribution of perishable liquids without refrigeration, cutting cold-chain capital expenditure by half in infrastructure-scarce territories. Liquid cartons lead volume throughput across the region, though pharmaceutical-grade glass vials command the densest margin pools due to parenteral sterility requirements. UHT processing technology sustains the steepest adoption curve as dairy processors in Ethiopia and Tanzania retrofit existing pasteurization lines.
Saudi Arabia's SFDA enforces pharmaceutical packaging sterility protocols that exceed baseline ISO 15378 standards, while South Africa's national pharmaceutical regulator mandates batch-level seal-integrity documentation for intravenous products. Egypt's food safety authority applies EFSA-aligned migration limits on plastic-contact layers in dairy applications, tightening material qualification cycles. Stakeholders must monitor harmonization gaps between Gulf standardization bodies and sub-Saharan national regulators as regional trade integration accelerates.
Market Dynamics
Extended-shelf-life dairy demand across the Gulf Cooperation Council is forcing material suppliers to bifurcate their product portfolios into hot-climate performance tiers, creating divergent qualification cycles for barrier laminates.
Growth Catalysts
- UHT Retrofit Wave:Dairy processors in Ethiopia and Tanzania are converting existing pasteurization infrastructure to aseptic filling lines, expanding addressable equipment demand across East Africa.
- SFDA Pharmaceutical Standards:Saudi Arabia's sterility protocols exceeding ISO 15378 baseline are mandating upgraded barrier-performance specifications for parenteral packaging suppliers.
- Lagos-Ibadan Manufacturing Corridor:Nigerian food and beverage producers are retrofitting production lines for ambient distribution, concentrating regional demand in this industrial cluster.
Market Restraints
- Aluminum Foil Supply Concentration:Regional dependence on imported metallized barrier substrates exposes converters to currency volatility and elongated lead times from European and Asian suppliers.
- Multilayer Polymer Technical Ceiling:Hot-climate distribution requirements push laminate complexity beyond current regional coextrusion capabilities, forcing reliance on imported pre-qualified structures.
- Harmonization Gaps:Divergent migration limit enforcement between Egypt's EFSA-aligned food safety authority and Gulf standardization bodies fragments material qualification protocols.
Strategic Opportunities
- Pharmaceutical-Grade Glass Vial Expansion:South Africa's national pharmaceutical regulator mandates batch-level seal-integrity documentation, creating premium-margin capture potential for compliant domestic converters.
- Hot-Fill PET Convergence:Integration of aseptic blow-fill-seal technology with high-acid beverage processing opens ambient juice and nectar applications previously restricted to carton formats.
- Regional Filling-Equipment Service Hubs:Localized technical support infrastructure in Kenya and Nigeria reduces processor downtime, enabling penetration of mid-cap dairy operations previously served by informal packaging.
Industry Challenges
- Barrier Metrology Skill Scarcity:Regional laboratories lack trained personnel for oxygen transmission rate and seal-integrity validation, extending certification timelines for new laminate qualifications.
- Legacy Pasteurization Integration:Retrofitting existing dairy lines for aseptic operation requires simultaneous upgrade of CIP systems, bottle sterilization tunnels, and filling environments, compressing project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aseptic Packaging Market |
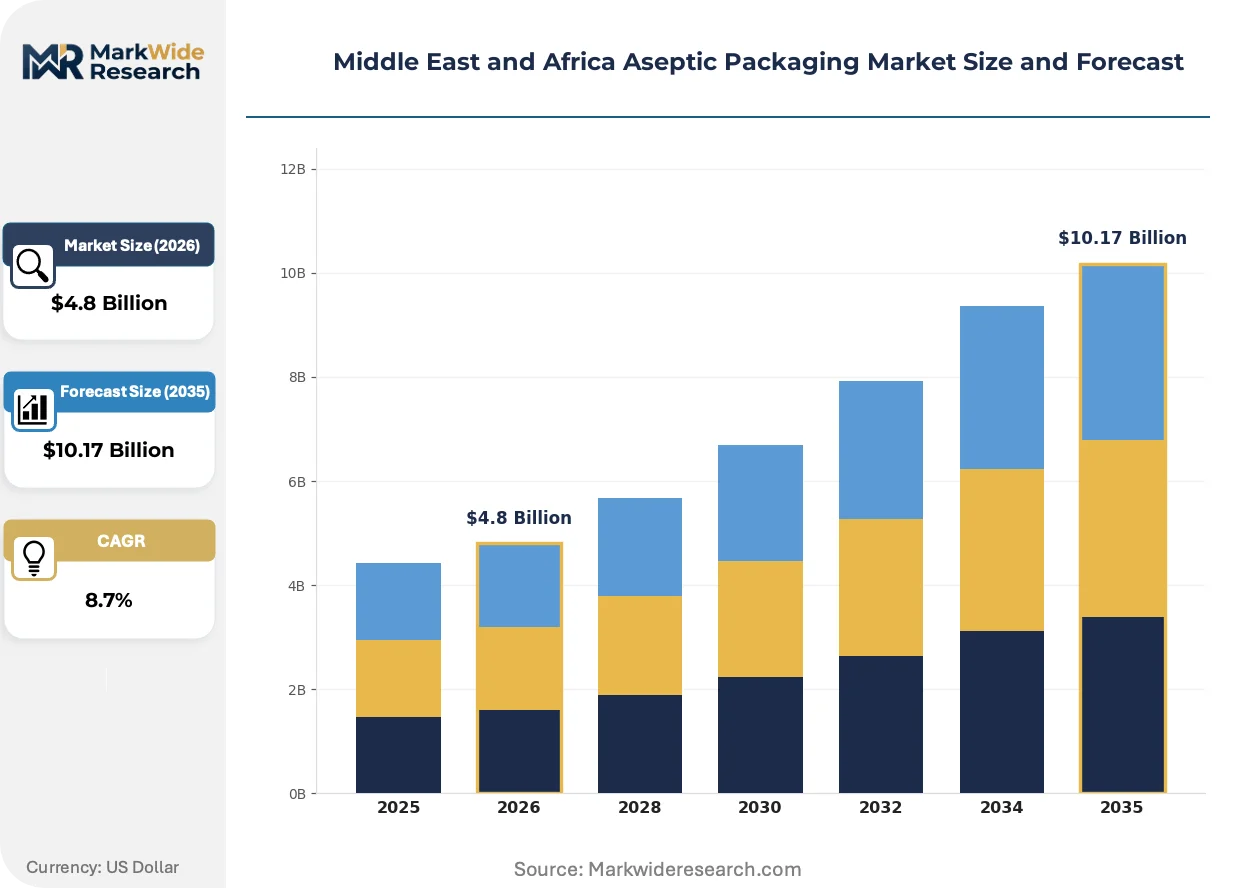
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Semi-Solid, Solid, Pastes End User: Food & Beverage, Pharmaceuticals, Cosmetics, Dairy Material: Plastic, Glass, Paperboard, Metal Technology: Hot Fill, Cold Fill, UHT, Aseptic |
| Companies Covered | Tetra Pak International SA, SIG Group AG, Amcor Group GmbH, Greatview Aseptic Packaging Company, Nampak Ltd, DS Smith PLC, Mondi PLC, Elopak, Smurfit Kappa Group PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aseptic Packaging Market Shifts & Advancements
Material science advances and regulatory stringency are reshaping competitive positioning across the Middle East and Africa aseptic packaging landscape. Three developments merit particular attention.
Paperboard-based barrier structures are fragmenting the liquid carton segment as converters develop fiber-dominant alternatives to aluminum-foil laminates. Saudi and UAE dairy processors are piloting these substrates for ambient milk distribution. The technology is fragmenting supply chains by enabling regional paper mills to enter barrier packaging previously locked to metallized film converters.
Egypt's food safety authority applies EFSA-aligned migration limits on plastic-contact layers, tightening material qualification cycles for dairy applications. This regulatory compression forces converters to front-load toxicological documentation and accelerates obsolescence of legacy polymer formulations. Multilayer dairy cartons face the steepest requalification burden as contact-layer chemistry comes under renewed scrutiny.
Buyer concentration among Gulf dairy cooperatives is compressing supplier negotiation cycles and unbundling after-sales technical service from equipment procurement. Nigerian and Kenyan processors are adopting this Gulf-derived procurement model, shifting from transactional material purchasing to integrated filling-line performance contracts. The behavioral shift is most visible in Kenya's Rift Valley dairy cluster, where cooperative processors now demand uptime guarantees from packaging system suppliers.
Middle East and Africa Aseptic Packaging Market Segmentation
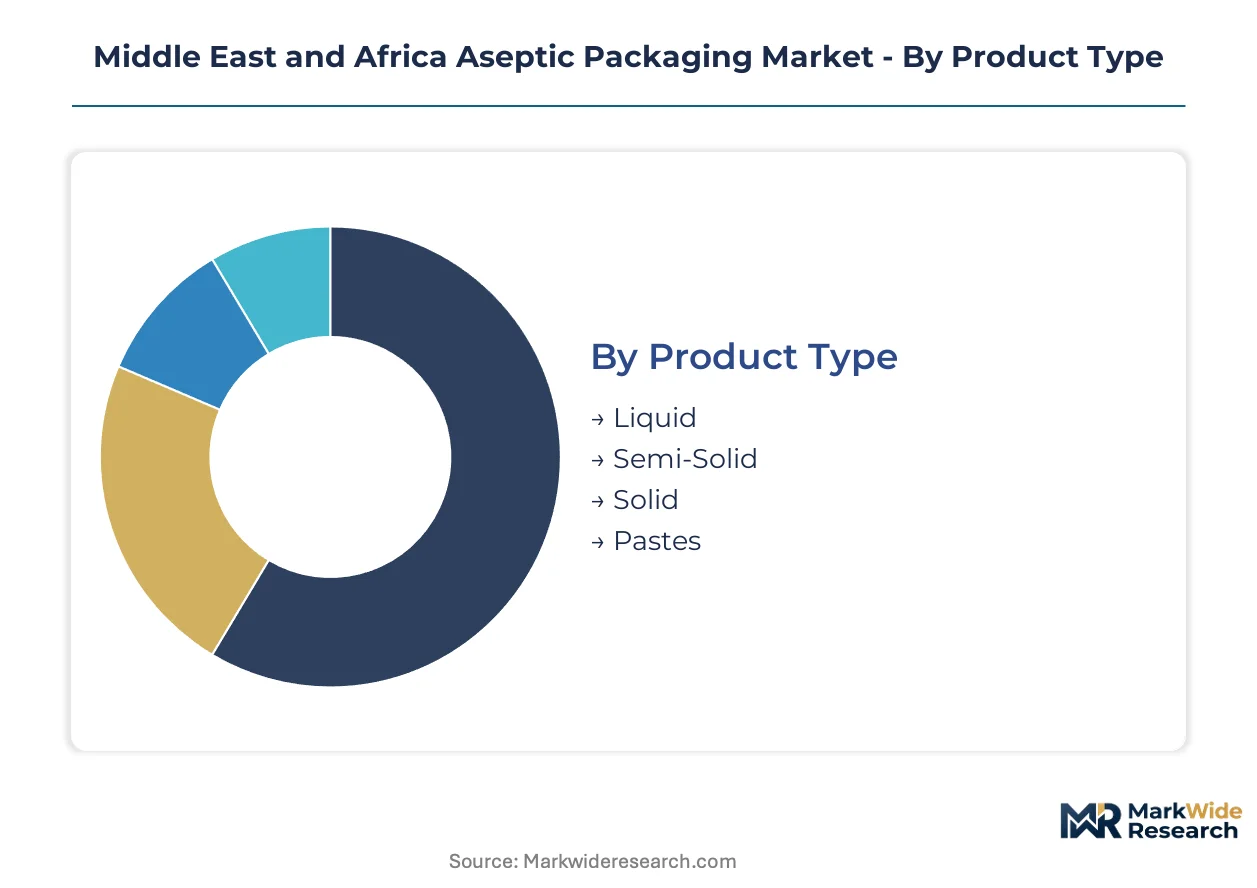
Aseptic packaging configurations diverge sharply between Gulf dairy cooperatives prioritizing shelf-stable liquid formats and sub-Saharan pharmaceutical regulators enforcing parenteral sterility tiers. Material selection and filling technology choices cascade from these demand anchors, fragmenting supply capabilities across the region.
Product Type:
Domestic demand concentrates in liquid and semi-solid formats serving Gulf ambient dairy distribution, while paste and solid formats track export-oriented pharmaceutical packaging toward European and Asian markets.
- Liquid:UHT-processed milk and juice cartons dominate throughput across Saudi Arabia and UAE dairy cooperatives. Lagos-Ibadan corridor beverage processors are retrofitting lines specifically for ambient liquid distribution, compressing equipment procurement cycles.
- Semi-Solid:Yogurt and dessert applications in Tetra Pak and SIG formats anchor Gulf retail distribution. South African pharmaceutical regulators enforce stricter oxygen barrier specifications for semi-solid parenteral nutrition than food-grade equivalents, bifurcating material qualification.
- Solid:Freeze-dried pharmaceutical and nutraceutical applications supply export markets from Egyptian and Moroccan converters.
- Pastes:Tomato concentrate and puree packaging for regional food processing clusters in Nigeria and Kenya.
Liquid holds the largest share; momentum sits with semi-solid as pharmaceutical nutrition applications expand.
End User:
Cost tier stratification separates premium pharmaceutical-grade barrier investments from economy-tier food packaging serving price-sensitive African markets.
- Food & Beverage:Ambient juice and ready-to-drink applications in Nigeria and Kenya drive carton volume. Hot-climate distribution requirements push laminate complexity beyond regional coextrusion capabilities, forcing reliance on imported pre-qualified structures.
- Pharmaceuticals:Parenteral vials and ampoules command densest margin pools due to South Africa's batch-level seal-integrity documentation mandates. Saudi SFDA sterility protocols exceeding ISO 15378 baseline accelerate barrier-performance upgrades.
- Cosmetics:Premium skincare ampoules serve Gulf luxury retail channels from UAE-based converters.
- Dairy:UHT milk cartons sustain steepest adoption curve as Ethiopian and Tanzanian processors retrofit pasteurization infrastructure.
Dairy captures the greatest volume throughput; pharmaceuticals generate the steepest margin expansion trajectory.
Material:
Supply concentration patterns fragment procurement, with paperboard and glass anchoring domestic production while plastic and metal laminates depend on Asian and European import channels.
- Plastic:Multilayer polyethylene and polypropylene structures dominate Nigerian and Kenyan beverage applications. Egypt's EFSA-aligned migration limits on plastic-contact layers tighten material qualification cycles, accelerating obsolescence of legacy polymer formulations.
- Glass:Pharmaceutical-grade borosilicate vials serve South African parenteral markets under strict national regulator documentation requirements. Domestic converter capability gaps force import dependence for high-barrier pharmaceutical glass.
- Paperboard:Fiber-dominant barrier alternatives to aluminum-foil laminates are piloting in Saudi and UAE dairy applications, enabling regional paper mills to enter packaging previously locked to metallized film converters.
- Metal:Aluminum foil laminates face supply concentration risks from European and Asian substrate sources, exposing converters to currency volatility.
Paperboard is gaining share fastest; plastic retains the broadest installed base across food applications.
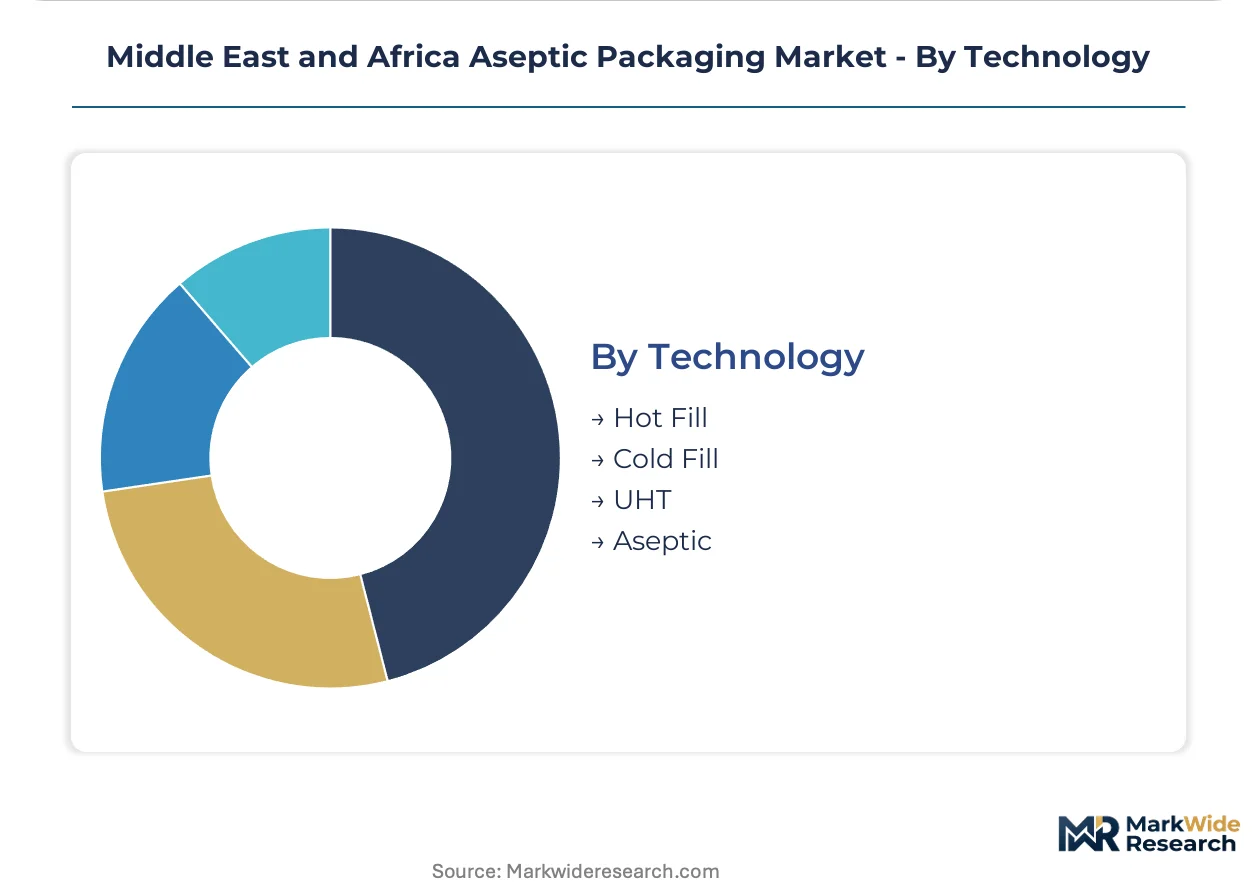
Technology:
Customer type segmentation separates integrated dairy cooperates demanding turnkey filling-line performance contracts from mid-cap processors purchasing discrete equipment packages.
- UHT:Ultra-high-temperature processing sustains the steepest retrofit wave across East African dairy infrastructure. Ethiopian and Tanzanian conversions of existing pasteurization lines expand addressable equipment demand.
- Hot Fill:High-acid beverage processing integration with aseptic blow-fill-seal technology opens ambient juice applications previously restricted to carton formats. Nigerian processors are piloting PET hot-fill convergence for nectar distribution.
- Cold Fill:Aseptic cold-chain-dependent applications serve premium dairy and pharmaceutical segments with limited regional penetration.
- Aseptic:Standalone sterilization-based containment systems achieve commercial sterility with residual oxygen below 1% in barrier laminates, enabling ambient distribution without refrigeration.
UHT commands the largest installed capacity; hot fill is climbing the fastest as PET format adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters cluster capacity around Gulf dairy cooperatives and South African pharmaceutical corridors, with supply chains radiating into sub-Saharan retrofit markets. Regional trade integration accelerates, yet divergent sterility protocols fragment material qualification cycles.
Saudi Arabia
UHT milk carton demand drives laminate throughput across Riyadh and Jeddah processing clusters. The Saudi Food and Drug Authority enforces pharmaceutical packaging sterility protocols exceeding baseline ISO 15378 standards. Eastern Province dairy cooperatives pilot fiber-dominant barrier alternatives to aluminum-foil laminates.
United Arab Emirates
Ambient juice and ready-to-drink applications concentrate carton procurement in Dubai and Abu Dhabi free zones. The Ministry of Health and Prevention monitors migration limits on food-contact plastics. Sharjah-based converters serve Gulf re-export markets with hot-climate performance-tier laminates.
South Africa
Batch-level seal-integrity documentation mandates for intravenous products elevate barrier-performance requirements. The national pharmaceutical regulator enforces stricter oxygen specifications than food-grade equivalents. Gauteng province pharmaceutical corridors command premium-margin glass vial production.
Nigeria
Food and beverage producers retrofit lines for ambient distribution across the Lagos-Ibadan manufacturing corridor. The national food safety authority applies evolving migration limits on plastic-contact layers. Mid-cap dairy operations in Ogun State adopt integrated filling-line performance contracts.
Egypt
Tomato concentrate and puree packaging anchors regional food processing demand. The national food safety authority applies EFSA-aligned migration limits on dairy-contact plastics. Cairo-Alexandria industrial zones face compressed material qualification cycles as legacy polymer formulations accelerate toward obsolescence.
Middle East and Africa Aseptic Packaging Market Competitive Landscape
Concentration sits with integrated carton-converting and filling-machine ecosystems dominating Gulf dairy procurement. The supplier base stratifies into three tiers: multinational turnkey system providers, regional laminate specialists, and emerging fiber-based barrier developers. Competitive moves center on localized service hub deployment and backward integration into metallized substrate supply.
Within the integrated-system tier, Tetra Pak International SA and SIG Group AG exemplify turnkey ecosystem dominance. Amcor Group GmbH anchors multilayer polymer expertise for hot-climate distribution challenges. Greatview Aseptic Packaging Company occupies a position among Asia-origin specialists penetrating African retrofit markets. These archetypes represent divergent strategic postures: ecosystem lock-in versus material science specialization versus geographic arbitrage.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| SIG Group AG |
| Amcor Group GmbH |
| Greatview Aseptic Packaging Company |
| Nampak Ltd |
| DS Smith PLC |
| Mondi PLC |
| Elopak |
| Smurfit Kappa Group PLC |
| Others |
Supply & Pricing Matrix
Capacity utilization gaps between Gulf dairy cooperatives and sub-Saharan mid-cap processors create divergent price floors across the Middle East and Africa Aseptic Packaging Market. Scale concentration in Riyadh-Jeddah clusters compresses per-unit laminate costs, while Nigerian and Kenyan retrofit demand absorbs premium pricing for imported pre-qualified barrier structures.
Pricing Analysis
Saudi SFDA pharmaceutical sterility protocols exceeding ISO 15378 baseline dictate the pricing tier structure across barrier laminate categories. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade seal-integrity documentation from food-grade ambient dairy specifications. Cost compression in standard-tier UHT carton laminates is intensifying because Egyptian EFSA-aligned migration limits accelerate legacy polymer obsolescence. Nigerian mid-cap dairy processors exhibit the highest price sensitivity, while South African parenteral packaging buyers prioritize certification compliance over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites metallized barrier substrate flows from European and Asian converters to Gulf dairy clusters. Supply concentration in Germany, China, and Japan feeds regional dependence on imported aluminum foil and multilayer coextrusion equipment. Raw material procurement draws from petroleum-derived polymer resins, metallized films, and pharmaceutical-grade borosilicate glass. Single-source vulnerability in aluminum foil substrate channels exposes converters to currency volatility. Distribution runs through Dubai-Jebel Ali free zone re-export hubs serving sub-Saharan retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
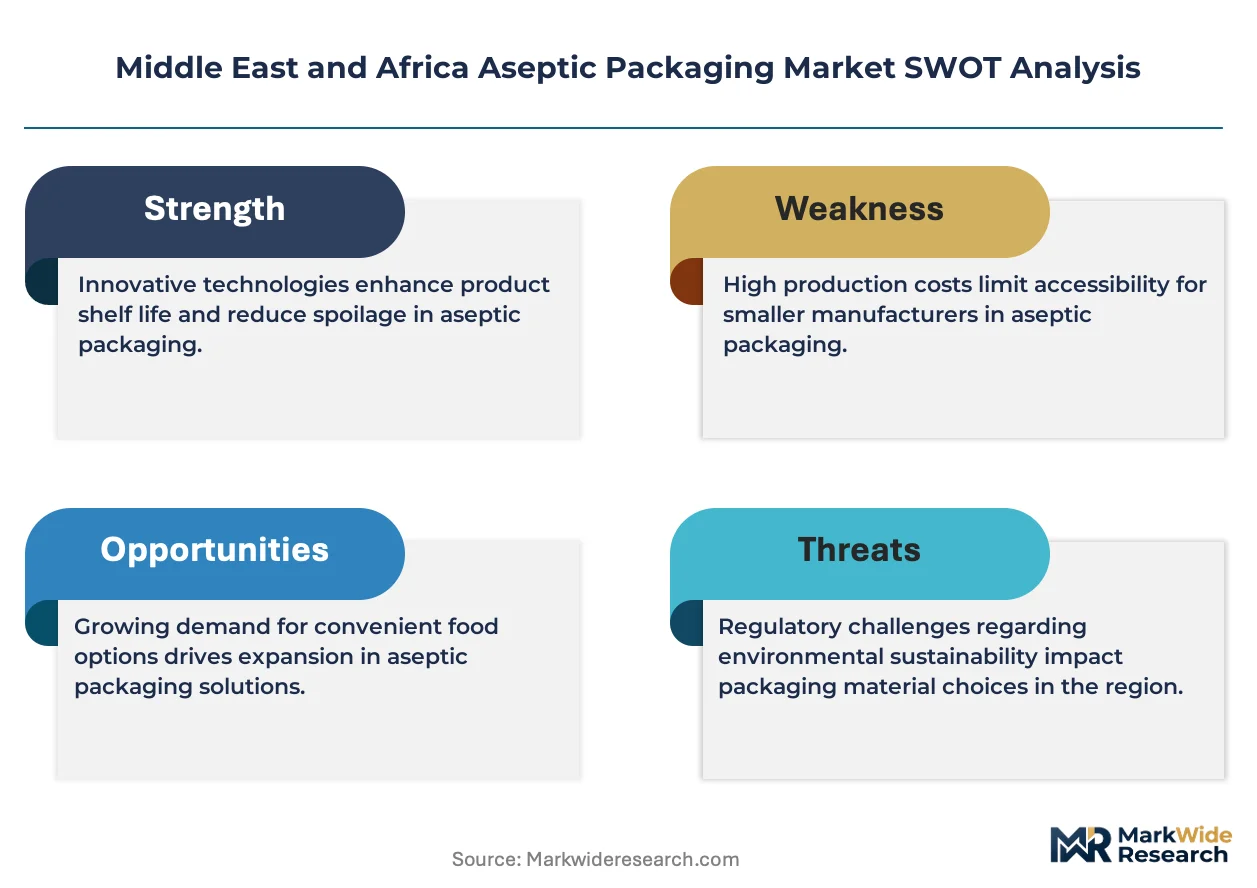
Fragmentation across the Middle East and Africa Aseptic Packaging Market creates niche capture opportunities as Gulf dairy cooperatives unbundle after-sales technical service from equipment procurement. This demand-side shift opens margin pools for specialized service providers and regional laminate developers.
For Market Incumbents: Consolidate filling-equipment service hub coverage across Kenya's Rift Valley and Nigeria's Ogun State to defend against Asia-origin specialists penetrating African retrofit markets. Backward integration into metallized substrate supply reduces exposure to European aluminum foil import volatility. Capture premium-margin pharmaceutical-grade glass vial production in Gauteng corridors before domestic converter capability gaps close. For New Entrants and Emerging Players: Anchor in fiber-dominant barrier alternatives piloting across Saudi Eastern Province dairy cooperatives, where regional paper mills seek packaging market entry. Target hot-fill PET convergence opportunities in Nigerian ambient juice processing previously restricted to carton formats. Lead with localized barrier metrology laboratory partnerships to compress certification timelines for new laminate qualifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional filling-equipment service specialists with captive spare parts inventory and uptime guarantee contracts. Long-term viability hinges on exposure to East African UHT retrofit waves rather than Gulf market saturation. Acquisition target archetype: mid-cap converters with SFDA pharmaceutical certification and installed multilayer polymer expertise. Watch aluminum foil supply concentration indices as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Substrate Supply | Reduces currency volatility exposure from European aluminum foil import dependence. |
| Regional Filling-Equipment Service Hub Deployment | Captures uptime guarantee contracts from Kenya's Rift Valley dairy cooperatives. |
| Pharmaceutical-Grade Glass Vial Capacity Expansion | Addresses South African batch-level seal-integrity documentation mandate gaps. |
| Fiber-Dominant Barrier Alternative Development | Enables Saudi paper mills to enter metallized film converter territory. |
| Hot-Fill PET Blow-Fill-Seal Technology Integration | Opens Nigerian ambient juice applications from carton format restriction. |
Research Methodology
Initial hypotheses were tested against primary input from dairy processing plant managers, pharmaceutical packaging procurement leads, barrier laminate technical directors, and regional regulatory affairs specialists and refined through secondary validation against customs trade records, Saudi SFDA regulatory filings, Egyptian food safety authority migration limit documentation, and industry association capacity surveys. Bottom-up equipment procurement tracking and top-down laminate throughput estimates were triangulated to reconcile variance.
Forecast variance decomposes across product type, material substrate, end-use application, and technology platform dimensions modeled throughout the projection horizon. CAGRs were derived from segment-level adoption curves weighted by retrofit infrastructure investment cycles and regulatory compliance phase-in schedules. UHT processing line conversion rates in Ethiopia and Tanzania, alongside Gulf dairy cooperative procurement contract renewal patterns, anchored volume projections.
Material uncertainties — harmonization gaps between Gulf standardization bodies and sub-Saharan national regulators, aluminum foil supply channel disruptions, and barrier metrology skill scarcity extending certification timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and infrastructure investment continuity. Practitioners should keep alternative scenarios live as regional trade integration protocols and pharmaceutical sterility standard convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Cartons Market