
 Aseptic Containment Systems Market | 2026-2036
Aseptic Containment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Containment Systems Market Analysis
ISO 14644-1 Class 5 certification is redrawing procurement benchmarks across pharmaceutical containment. SKAN AG anchors European supply of high-grade isolator systems through precision engineering in Switzerland. Thermo Fisher Scientific extends its reach via integrated biosafety and monitoring platforms. Esco Group competes aggressively in Asia-Pacific with localized manufacturing scale.
Aseptic containment systems enclose critical processes within unidirectional airflow environments maintained at positive or negative pressure differentials, typically employing HEPA filtration rated at 99.97% efficiency at 0.3 microns to exclude or contain biological agents. These systems serve primarily to protect product sterility, operator safety, or both during pharmaceutical manufacturing and biohazard handling. Isolators command the largest installed base among product types due to their closed architecture and validated decontamination cycles, while automation technology within containment is expanding fastest as manufacturers seek to eliminate human intervention during aseptic operations. Cleanrooms retain mature, high-volume demand but face margin compression compared to specialized isolator and glove box configurations.
FDA sterility guidance, EU GMP Annex 1 revisions, and ISO 14644 cleanroom classifications collectively tighten validation requirements and extend replacement cycles for legacy equipment. The EU AI Act introduces emerging compliance complexity for automated containment systems with embedded diagnostic algorithms. Stakeholders must weigh capital allocation between retrofitting existing isolator suites against greenfield installations designed for closed robotic processing.
Market Dynamics
Closed robotic processing architectures are compressing validation timelines and displacing open cleanroom configurations across pharmaceutical manufacturing facilities. This shift toward operator-excluded aseptic environments is redrawing capital allocation priorities between retrofit investments and greenfield isolator installations.
Growth Catalysts
- EU GMP Annex 1 Revisions:The sterility assurance mandate is accelerating isolator adoption over conventional cleanrooms in fill-finish operations across Germany, Switzerland, and France.
- Gene therapy manufacturing scale-up:Viral vector production facilities in Massachusetts and North Carolina are commissioning negative-pressure isolator suites to meet containment requirements for BSL-2/3 biological agents.
- Stainless steel substitution:Single-use isolator technologies are displacing fixed stainless steel barrier systems in multi-product biologics facilities seeking campaign flexibility.
Market Restraints
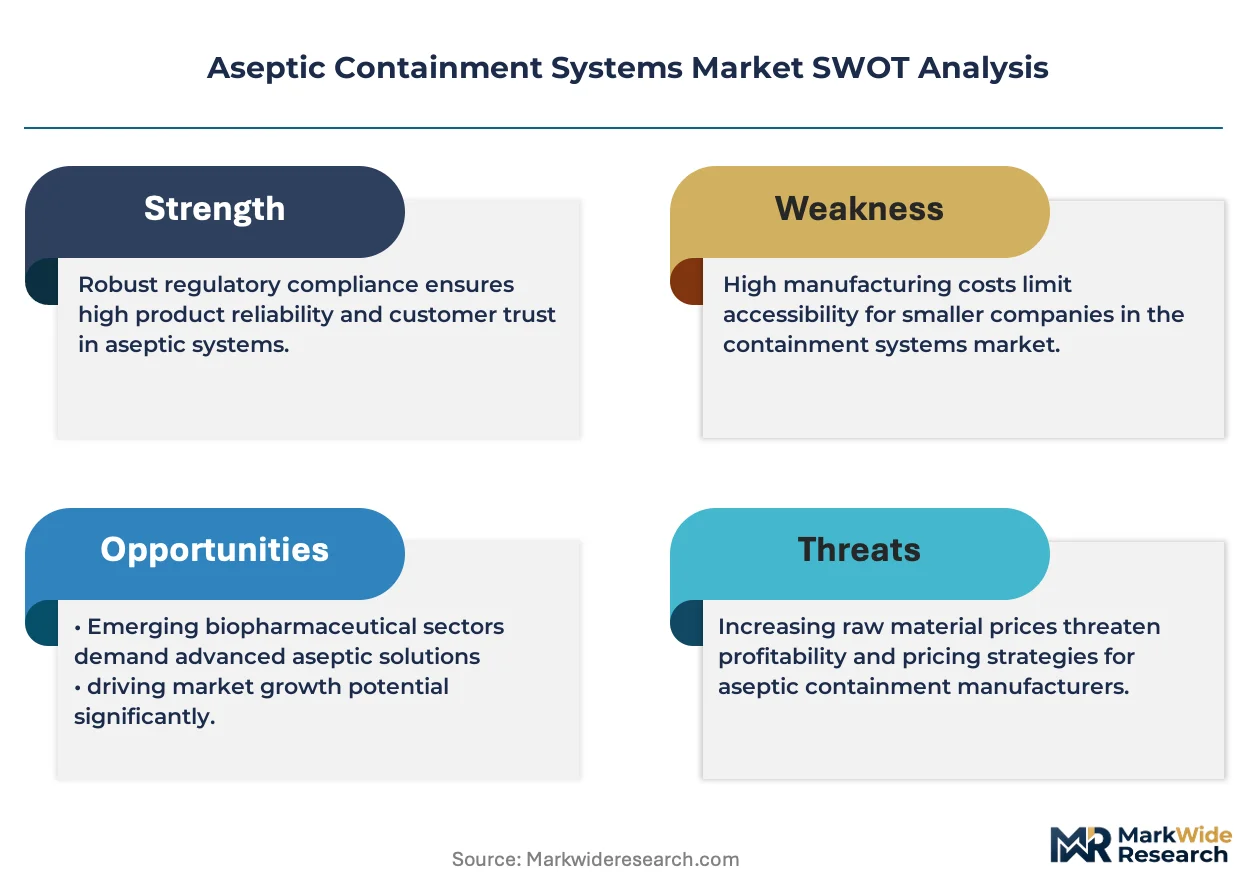
- Specialized steel and HEPA filter input volatility:Electropolished 316L stainless steel pricing fluctuates with nickel supply constraints from Indonesian mining operations.
- Swiss-German engineering concentration:Precision isolator fabrication clusters in Basel and Stuttgart create geographic supply vulnerability for North American buyers.
- Legacy cleanroom asset lock-in:Existing ISO 14644-1 Class 7 facilities face stranded investment risk as certification thresholds tighten toward Class 5 isolator equivalents.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO's streamlined biopharma licensing framework is attracting greenfield isolator investments in Hyderabad and Bangalore.
- Cell therapy point-of-care processing:Portable isolator systems are enabling decentralized aseptic manipulation at hospital pharmacy sites and regional cell processing centers.
- EU AI Act diagnostic compliance:Automated isolators with embedded contamination detection algorithms can capture premium positioning through validated self-monitoring capabilities.
Industry Challenges
- Containment engineering talent scarcity:Cross-disciplinary expertise combining HEPA filtration physics, pharmaceutical process validation, and robotic integration remains concentrated among Swiss and German specialist firms.
- Decontamination cycle validation complexity:Vaporized hydrogen peroxide (VHP) cycle development for novel isolator geometries extends commissioning timelines and regulatory submission burdens.
- Legacy building infrastructure incompatibility:Older pharmaceutical facilities face structural load, HVAC capacity, and floorplan constraints when retrofitting rigid isolator suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Containment Systems Market |
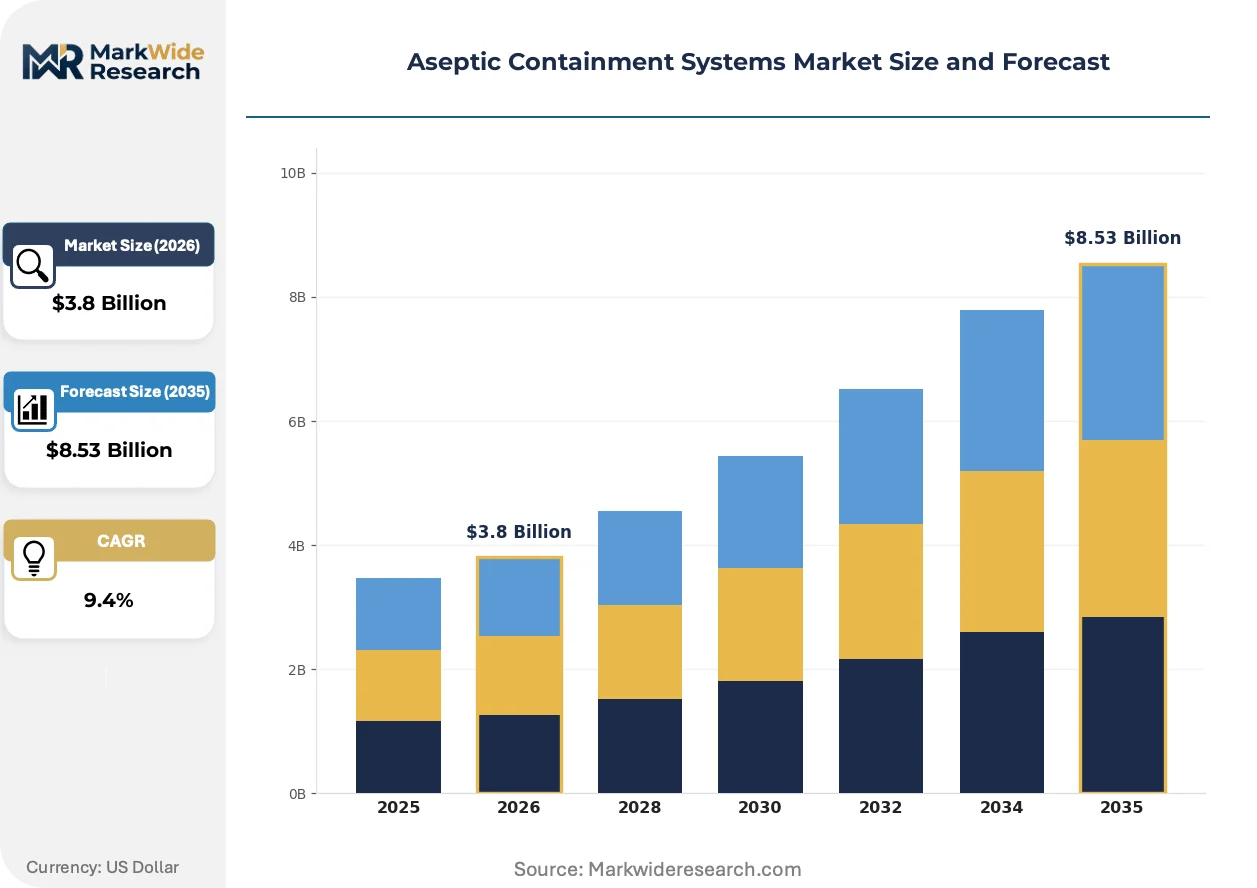
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolators, Glove Boxes, Biosafety Cabinets, Cleanrooms Technology: Filtration, Sterilization, Automation, Monitoring End User: Pharmaceuticals, Biotechnology, Research Laboratories, Hospitals Compliance Standard: FDA, EU GMP, ISO 14644, cGMP |
| Companies Covered | Labconco Corporation, Comecer S.p.A., Thermo Fisher Scientific Inc, SKAN AG, The Baker Company, Getinge Group, NuAire Inc, Esco Group, STERIS plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Containment Systems Market Emerging Trajectories
Modular isolator architectures are displacing fixed stainless steel installations as pharmaceutical manufacturers prioritize reconfigurable production lines. This structural shift is compressing equipment procurement cycles and enabling faster product changeovers in multi-asset facilities.
Modular gloveless isolator systems utilizing pre-validated skids and plug-and-play robotic interfaces are miniaturizing aseptic processing footprints while maintaining ISO 14644-1 Class 5 compliance. Contract development and manufacturing organizations (CDMOs) in Switzerland and Massachusetts are adopting these configurations to accommodate shorter product campaigns. The technology is miniaturizing facility capital requirements and enabling distributed manufacturing networks closer to patient populations.
REACH restrictions on perfluorinated compounds are forcing HEPA filter manufacturers to reformulate membrane materials and validate alternative hydrophobic coatings. The regulatory pressure is accelerating qualification timelines for new filter assemblies and creating temporary supply constraints for pharmaceutical-grade containment systems. High-potency API handling facilities in Germany and the Netherlands are absorbing the bulk of compliance costs through accelerated filter replacement protocols.
Biopharma procurement teams are consolidating vendor relationships around integrated containment-monitoring-service packages rather than discrete equipment purchases. Large molecule manufacturers in Denmark and Singapore are negotiating multi-year performance contracts that bundle isolator hardware, VHP consumables, and predictive maintenance analytics. This bundling trend is most pronounced among top-20 pharmaceutical companies with centralized engineering procurement functions.
Aseptic Containment Systems Market Segmentation
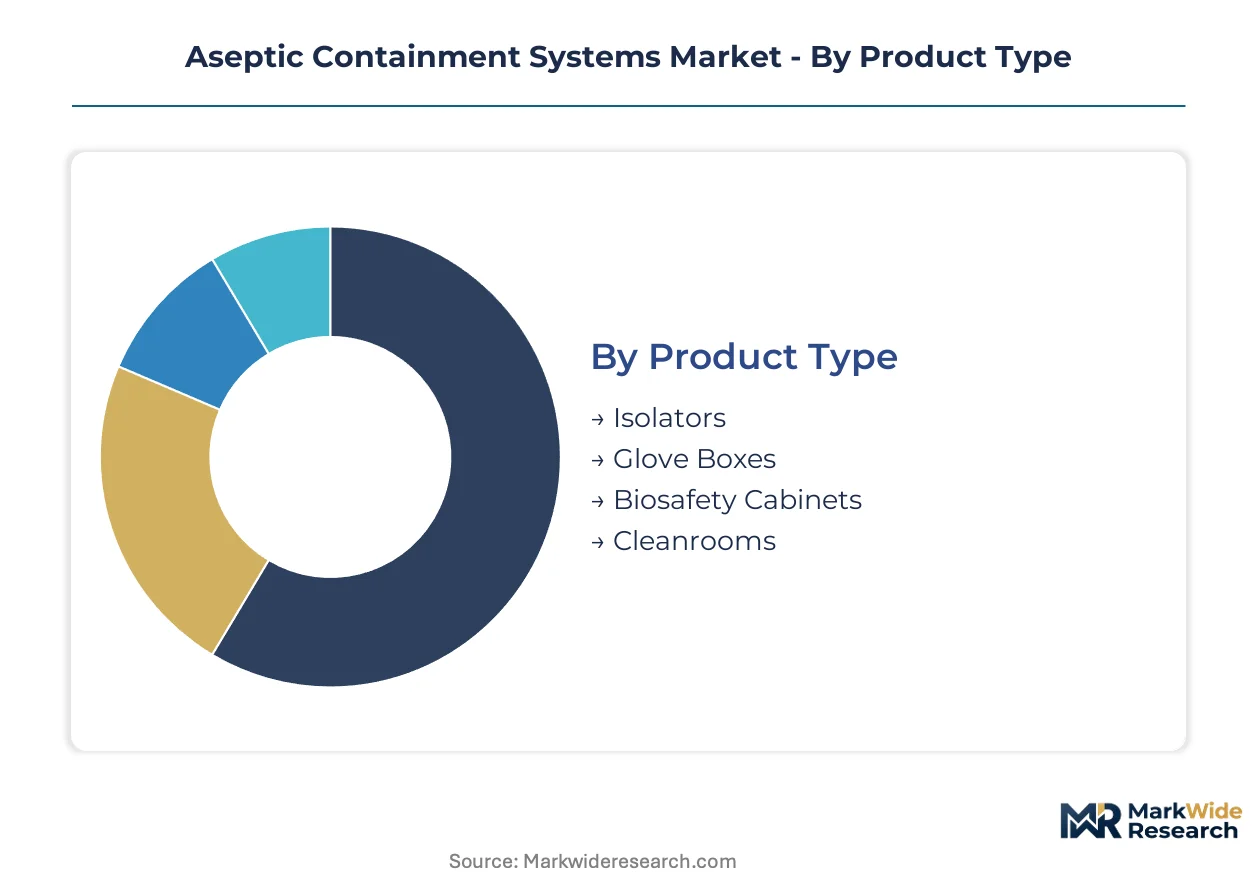
Segmentation in aseptic containment systems determines capital allocation priorities across pharmaceutical manufacturing facilities. Equipment specifications vary sharply by sterility assurance level, operator exposure risk, and regulatory jurisdiction. Procurement teams weight total cost of ownership against validation complexity when matching product categories to production workflows.
Product Type:
Margin pools concentrate in closed-architecture systems that reduce facility HVAC burden and accelerate regulatory approval timelines. Isolator systems command premium positioning through validated decontamination cycles and robotic integration capabilities.
- Isolators:These enclosed barrier systems maintain ISO 14644-1 Class 5 environments through unidirectional airflow and pressure differentials, typically employing HEPA filtration at 99.97% efficiency. Pharmaceutical fill-finish operations in Germany and Switzerland are expanding isolator-based lines as EU GMP Annex 1 tightens sterility assurance mandates. Vaporized hydrogen peroxide decontamination cycles enable rapid product changeovers in multi-campaign biologics facilities.
- Cleanrooms:Conventional controlled environments with defined air cleanliness classes remain essential for high-volume, lower-risk operations. Mature installed bases across North American generic drug manufacturing face margin compression as certification thresholds tighten toward isolator-equivalent performance. Facility retrofit costs and extended downtime create stranded asset risk for legacy Class 7 installations.
- Glove Boxes:Sealed enclosures with operator access through attached gloves serve laboratory-scale aseptic manipulation and high-potency API handling. Research institutions and contract testing laboratories represent primary demand concentration.
- Biosafety Cabinets:Ventilated enclosures protecting personnel, product, and environment through HEPA filtration serve BSL-2/3 containment requirements. Viral vector production facilities in Massachusetts deploy negative-pressure configurations for gene therapy manufacturing.
The dominant share belongs to Isolators, while Cleanrooms face share erosion fastest under regulatory pressure.
Technology:
Technology selection tracks the industry shift toward operator-excluded aseptic processing and continuous environmental verification. Automation and integrated monitoring systems are capturing disproportionate R&D investment as manufacturers eliminate human intervention from critical zones.
- Automation:Robotic material handling, closed vial transfer systems, and automated decontamination sequences reduce contamination risk and compress batch release timelines. Swiss and German engineering clusters lead development of gloveless robotic interfaces for fill-finish applications.
- Filtration:HEPA and ULPA media rated at 99.999% efficiency for 0.12-micron particles form the physical barrier foundation for all containment architectures. REACH restrictions on perfluorinated compounds are forcing membrane material reformulation and accelerated requalification cycles.
- Sterilization:Vaporized hydrogen peroxide, steam, and irradiation modalities enable validated bioburden elimination for isolator interiors and product contact surfaces. Cycle development for novel isolator geometries extends commissioning timelines.
- Monitoring:Continuous particle counting, viable air sampling, and pressure differential logging systems provide real-time compliance documentation. EU AI Act requirements for automated diagnostic algorithms are reshaping software validation protocols.
Automation is expanding most quickly as closed robotic processing displaces open cleanroom configurations, while Filtration retains foundational revenue stability across all product categories.
End User:
End user segmentation reflects divergent procurement authority and technical specification complexity. Pharmaceutical manufacturers drive volume demand with enterprise-scale capital projects, while biotechnology firms prioritize reconfigurable systems for pipeline flexibility.
- Pharmaceuticals:Large molecule and sterile injectable manufacturers deploy isolator suites for commercial fill-finish operations. FDA sterility guidance and EU GMP Annex 1 revisions mandate barrier technology upgrades across legacy facilities in France, Germany, and Italy.
- Biotechnology:Cell and gene therapy developers require negative-pressure isolators for BSL-2/3 viral vector production. Massachusetts and North Carolina facilities are commissioning specialized containment infrastructure.
- Research Laboratories:Academic and government institutions utilize biosafety cabinets and glove boxes for developmental-stage work. Procurement cycles emphasize capital cost containment over operational efficiency.
- Hospitals:Hospital pharmacy compounding and point-of-care cell processing drive demand for portable isolator systems. Decentralized manufacturing networks are emerging around regional treatment centers.
Pharmaceuticals anchor volume demand, while Biotechnology is scaling fastest through gene therapy manufacturing expansion.
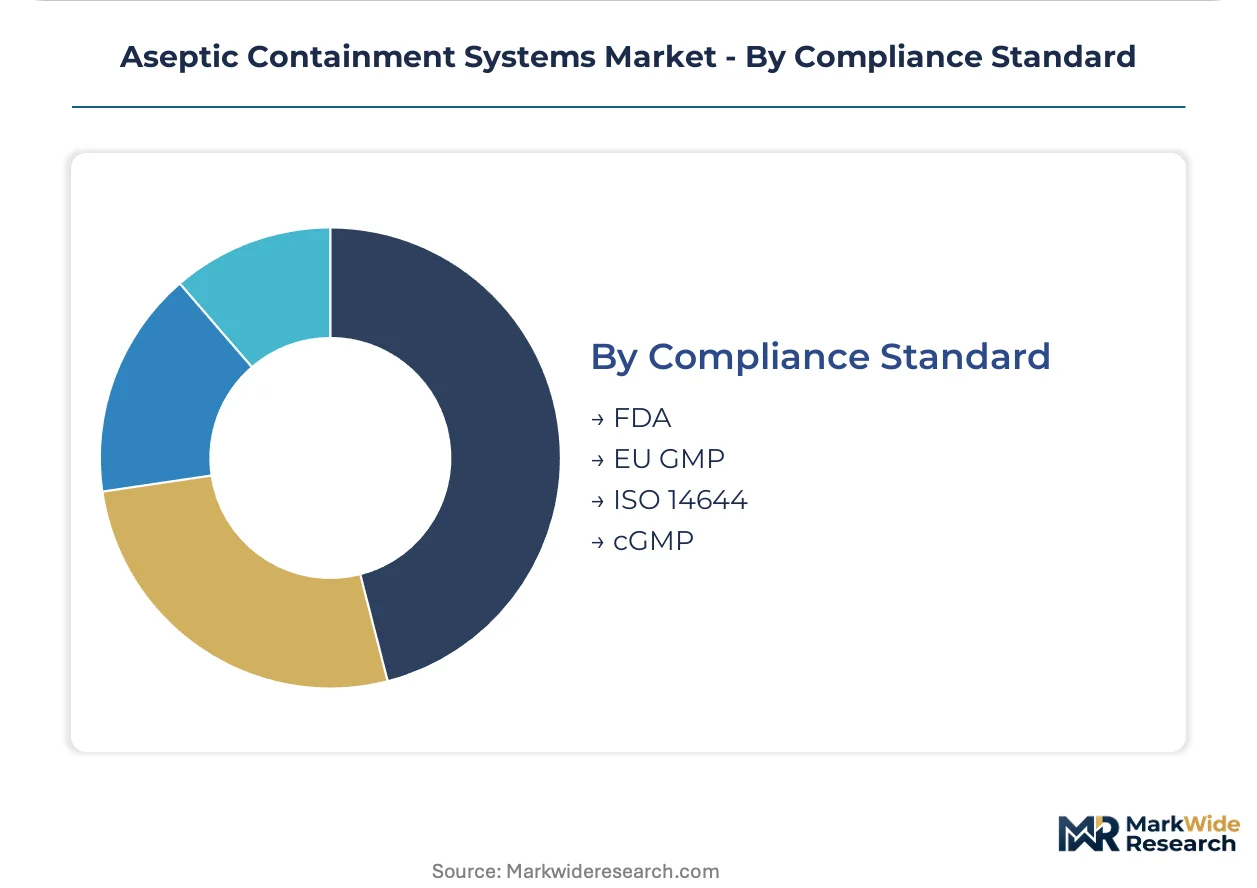
Compliance Standard:
Compliance segmentation determines validation protocol complexity and geographic market access. Regulatory divergence between FDA and EU GMP creates specification fragmentation for multinational pharmaceutical manufacturers.
- EU GMP:Annex 1 sterility assurance revisions mandate isolator adoption and continuous monitoring systems across European manufacturing. German and Swiss facilities face accelerated replacement cycles for open cleanroom configurations.
- FDA:Sterility guidance emphasizes contamination control strategies and risk-based validation approaches. Massachusetts and North Carolina viral vector facilities align with FDA expectations for gene therapy containment.
- ISO 14644:Cleanroom classification standards define airborne particulate limits and verification methodologies. ISO 14644-1 Class 5 certification is redrawing procurement benchmarks across pharmaceutical containment.
- cGMP:Current Good Manufacturing Practice requirements govern facility design, equipment qualification, and process validation. Multi-jurisdictional facilities must harmonize FDA and EU GMP interpretations.
EU GMP specifications command premium system configurations, while FDA alignment enables broader geographic deployment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export dependency defines the competitive geography of aseptic containment systems. Swiss and German engineering clusters supply precision isolator hardware to North American and Asian pharmaceutical manufacturers. Import substitution pressures are building in India and China as domestic biologics capacity expands.
United States
Viral vector production facilities in Massachusetts and North Carolina are commissioning negative-pressure isolator suites for gene therapy manufacturing. FDA sterility guidance mandates contamination control strategies that accelerate barrier technology adoption. Greater Boston hosts concentrated demand from cell therapy developers building point-of-care processing networks.
Germany
Large molecule manufacturers in Baden-Württemberg and Bavaria are retrofitting fill-finish lines to meet EU GMP Annex 1 sterility assurance revisions. The national pharmaceutical regulator enforces accelerated replacement cycles for open cleanroom configurations. Stuttgart anchors precision isolator fabrication clusters serving European biopharma demand.
Switzerland
Contract development and manufacturing organizations in Basel are adopting modular gloveless isolator systems for shorter product campaigns. Swissmedic aligns with EU GMP standards while maintaining distinct validation protocols for high-potency API handling. The Lake Geneva region concentrates containment engineering talent across filtration physics and robotic integration.
India
CDSCO's streamlined biopharma licensing framework is attracting greenfield isolator investments in Hyderabad and Bangalore. Domestic biologics manufacturers are substituting imported containment hardware with locally fabricated systems. The Telangana-Andhra corridor is emerging as a secondary supply hub for standardized isolator skids.
China
NMPA is harmonizing sterile manufacturing standards with EU GMP Annex 1, forcing domestic upgrades in biologics facilities. Yangtze River Delta pharmaceutical parks are importing Swiss isolator technology while building captive engineering capabilities. Shanghai-based system integrators are reverse-engineering modular architectures for cost-sensitive domestic buyers.
Aseptic Containment Systems Market Vendor Landscape
Concentration sits with precision engineering specialists and diversified life science platforms. The vendor base stratifies across three tiers: Swiss-German fabricators commanding premium positioning for validated isolator systems, integrated multinationals bundling containment with monitoring and service contracts, and Asia-Pacific manufacturers competing on localized production scale. Strategic moves center on modular architecture development and multi-year performance contracting with top-20 pharmaceutical procurement functions.
Within the precision engineering tier, SKAN AG and Comecer S.p.A. represent archetypal positioning. SKAN AG anchors European supply through Swiss-based fabrication of high-grade isolator systems. Comecer S.p.A. occupies a comparable position among Italian specialists serving nuclear medicine and pharmaceutical containment applications. Thermo Fisher Scientific Inc exemplifies the integrated platform approach, extending reach through combined biosafety, monitoring, and service capabilities.
| Leading Market Players |
|---|
| Labconco Corporation |
| Comecer S.p.A. |
| Thermo Fisher Scientific Inc |
| SKAN AG |
| The Baker Company |
| Getinge Group |
| NuAire Inc |
| Esco Group |
| STERIS plc |
| Others |
Supply Flow & Price Mechanics
Specialized electropolished 316L stainless steel fabrication capacity in Basel and Stuttgart shapes both supply concentration and price floors for high-grade isolator systems. Swiss-German engineering clusters capture premium positioning through validated decontamination cycles and robotic integration capabilities that North American and Asian buyers cannot replicate domestically.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing with tiered certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates EU GMP Annex 1-compliant isolators from FDA-aligned systems and basic cleanroom configurations. Price differentiation hinges on decontamination cycle validation depth and robotic integration density. Cost compression in standard-tier isolators is intensifying because Indian and Chinese manufacturers are reverse-engineering modular architectures for cost-sensitive domestic buyers. CDMOs in Switzerland and Massachusetts demonstrate lowest price sensitivity through multi-year performance contracts bundling hardware, consumables, and predictive maintenance.
Supply Chain Analysis
Germany and Switzerland anchor precision isolator fabrication through electropolished 316L stainless steel machining and HEPA filter integration. Component sourcing draws from Indonesian nickel supply for steel alloy feedstock, specialized membrane manufacturers reformulating hydrophobic coatings under REACH restrictions, and Swiss robotic interface specialists. Single-source vulnerability concentrates in Basel-Stuttgart engineering talent pools for cross-disciplinary expertise combining filtration physics and pharmaceutical validation. Distribution runs through direct OEM relationships with top-20 pharmaceutical procurement functions and regional system integrators in Hyderabad and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment. EU GMP Annex 1 and FDA sterility guidance create switching costs that lock pharmaceutical manufacturers into validated supplier relationships across decade-long replacement cycles.
For Market Incumbents: Secure decontamination cycle IP through accelerated VHP validation protocols for novel isolator geometries. Lock in capacity addition in Basel and Stuttgart to preempt Indian import substitution. Vertical integration into HEPA filter membrane manufacturing mitigates REACH-driven supply disruption from perfluorinated compound restrictions.
For New Entrants and Emerging Players: Differentiate on portable isolator systems for hospital pharmacy point-of-care cell processing. White-space targets include decentralized manufacturing networks in regional treatment centers and standardized skid configurations for Indian CDSCO-licensed biologics facilities. Go-to-market angle emphasizes plug-and-play robotic interfaces with pre-validated decontamination cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Swiss-German precision engineering specialists with embedded regulatory validation capabilities. Long-term viability rests on automation technology integration and EU AI Act diagnostic compliance for contamination detection algorithms. Acquisition target archetype combines isolator hardware with integrated monitoring platforms. Signal to watch is NMPA harmonization progress with EU GMP Annex 1 in Chinese biologics facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Isolator Architecture Development | Pre-validated skids enable faster product changeovers for Swiss CDMOs. |
| EU AI Act Diagnostic Compliance Investment | Embedded contamination detection algorithms capture premium positioning. |
| Backward Integration into HEPA Filter Manufacturing | In-house membrane production mitigates REACH reformulation supply risk. |
| Multi-Year Performance Contracting | Bundled hardware-service packages lock in Danish large molecule manufacturers. |
| Localized Production Scale-Up in India | Hyderabad fabrication addresses CDSCO licensing surge with cost-competitive skids. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with containment engineering directors, pharmaceutical procurement leads, regulatory affairs specialists, and CDMO facility planners; and secondary validation through FDA 483 observations, EMA inspection reports, ISO 14644 certification databases, and Swissmedic GMP certificates. Bottom-up triangulation cross-referenced isolator installation records with top-down pharmaceutical capital expenditure disclosures across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, technology tier, end-user segment, and compliance standard cluster. CAGRs were derived from facility investment pipelines and regulatory-driven replacement cycle acceleration. Industry-specific forecast inputs included EU GMP Annex 1 implementation timelines and gene therapy manufacturing capacity buildouts in Massachusetts and North Carolina.
Forecasts assume regulatory continuity in FDA sterility guidance and EU GMP Annex 1 enforcement; material policy shifts would require re-modeling. Specific risk factors include nickel supply disruption from Indonesian mining operations and REACH expansion to additional perfluorinated compound categories. Recalibration cycles align with material shifts in sterility assurance mandates and automation technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market