
 North America Aseptic Packaging Market | 2026-2036
North America Aseptic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aseptic Packaging Market Analytics
Market Context
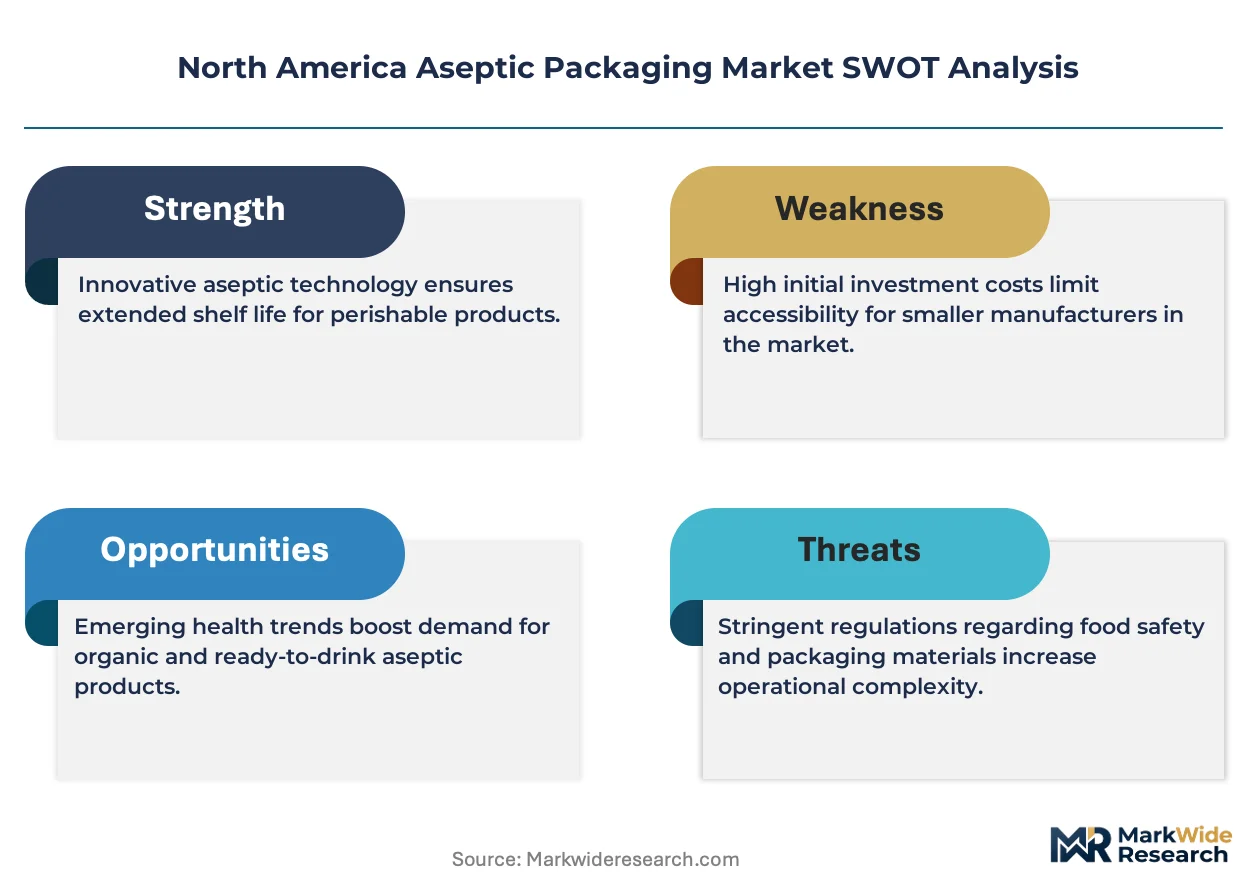
A capital-intensity divergence between integrated cartonboard producers and specialized film converters is bifurcating competitive dynamics across the region. Tetra Pak International S.A. leverages its end-to-end filling equipment ecosystem to anchor long-term dairy contracts. WestRock Company competes through captive paperboard supply and extensive North American boxboard infrastructure. SIG Combibloc Group differentiates via modular filling technology that reduces line conversion downtime for mid-size beverage runs.
Technical Definition and Segment Structure
North America aseptic packaging encompasses sterilized barrier systems—typically multilayer cartons with aluminum foil cores or polymer bottles with hydrogen peroxide surface treatment—that maintain commercial sterility without refrigeration for six to twelve months. The technology serves shelf-stable distribution chains where cold-chain economics prove prohibitive for liquid foods, pharmaceuticals, and nutritional products. Paperboard-based cartons command established volume in dairy and juice applications due to favorable fiber sourcing and printability. Flexible pouches represent the fastest-expanding format as retort-compatible coextruded films displace rigid alternatives in ready-to-drink nutrition and pediatric pharmaceuticals. Glass vials and bottles retain premium positioning in parenteral drug delivery where USP <1207> container closure integrity requirements limit polymer substitution.
Regulatory Environment and Outlook
FDA oversight through 21 CFR Part 113 and Part 114 governs low-acid and acidified foods, while USP Chapter <797> and <800> compounding standards shape pharmaceutical packaging validation protocols. The EPA's evolving per- and polyfluoroalkyl substances restrictions are pressuring fluorochemical-based sterilization barriers toward alternative surface treatments. Health Canada and PMRA coordinate with FDA on cross-border harmonization for dairy and juice carton standards, though provincial labeling variances persist. Stakeholders must monitor emerging state-level extended producer responsibility legislation in California and New York that could reshape post-consumer carton recovery economics and material specifications.
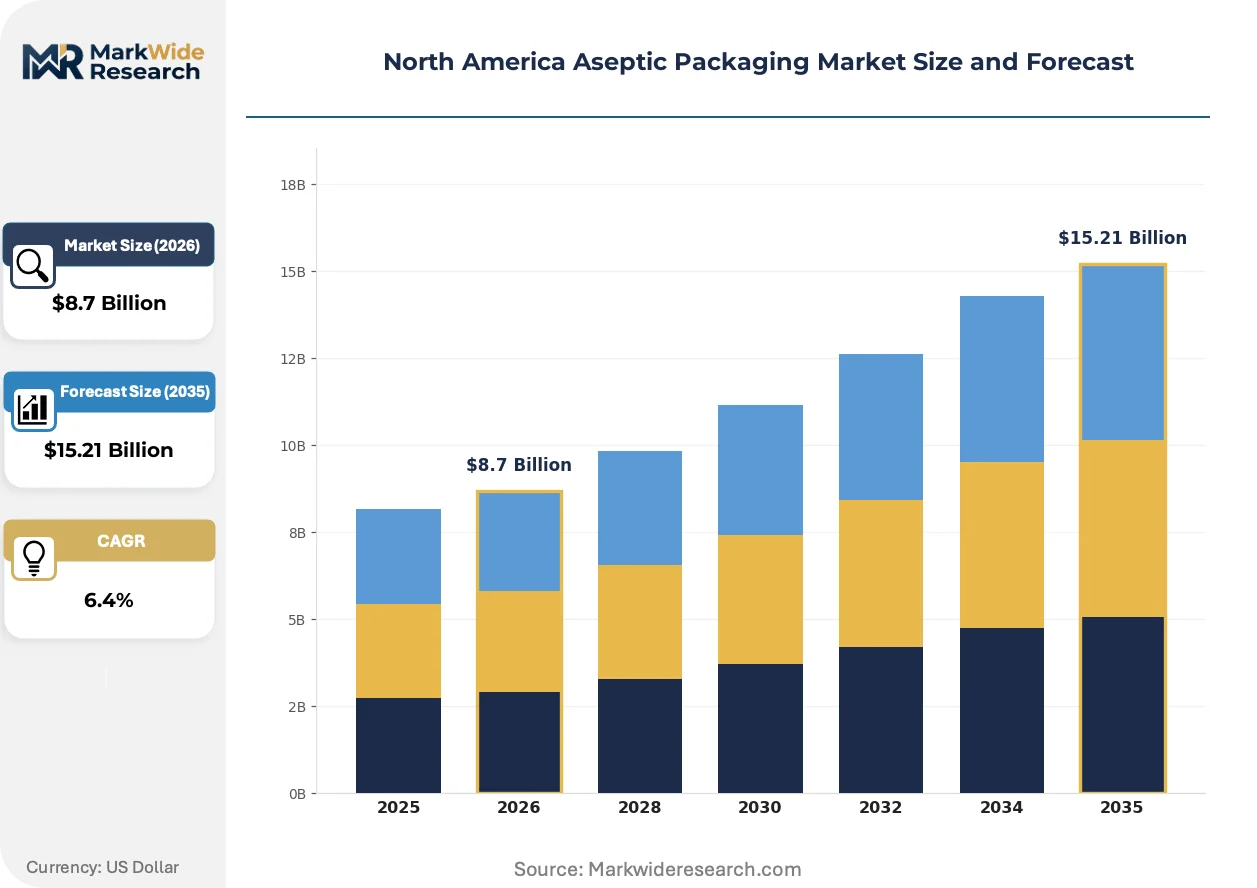
Market Dynamics
FDA's updated sterile drug guidance is compressing validation timelines while biologics manufacturing expands across the United States dairy corridor, forcing packaging suppliers to synchronize pharmaceutical-grade capabilities with food-sector scale economics.
Growth Catalysts
- Biologics manufacturing expansion:Pharmaceutical injectables now require high-barrier aseptic formats that extend shelf stability without cold-chain infrastructure, pulling film and carton technologies from adjacent dairy applications.
- 21 CFR Part 113 enforcement:FDA's intensified low-acid food sterilization audits are disqualifying marginal suppliers and consolidating contract awards toward validated multi-layer barrier producers.
- Wisconsin-New York dairy concentration:Regional milk processing clusters generate dense demand for extended-shelf-life cartons, amortizing filling equipment investments across high-volume production runs.
Market Restraints
- Aluminum foil supply concentration:Aseptic carton cores depend on thin-gauge foil supply dominated by European and Asian smelters, exposing converters to energy-cost volatility and trade-policy friction.
- Fluorochemical barrier restrictions:EPA's evolving PFAS limitations threaten hydrogen peroxide sterilization adjuncts, forcing costly reformulation of polymer surface treatments without mature alternatives.
- Glass vial substitution ceiling:USP Chapter 1207 container closure integrity requirements prevent polymer displacement in premium parenteral drugs, capping addressable market expansion for plastic formats.
Strategic Opportunities
- Pediatric nutrition pouches:Flexible retort-compatible films are capturing ready-to-drink formula share from rigid bottles, enabled by coextrusion advances that match barrier performance at lower per-unit weight.
- California extended producer responsibility:Pending state legislation will reshape post-consumer carton recovery economics, creating first-mover advantage for fiber-based formats with established recycling infrastructure.
- Modular filling technology convergence:Mid-size beverage processors are adopting quick-changeover lines that reduce conversion downtime between SKUs, opening contract manufacturing opportunities beyond captive dairy operations.
Industry Challenges
- Pharmaceutical validation timelines:USP Chapter 797 and 800 compliance for sterile compounding packaging requires 18-24 month certification cycles that strain working capital and delay revenue recognition.
- Cross-border standard harmonization gaps:Health Canada and FDA coordinate dairy carton standards, but provincial labeling variances in Quebec and Ontario force redundant SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aseptic Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible, Rigid, Pouches, Containers Material: Plastic, Glass, Metal, Paperboard End User: Food & Beverage, Pharmaceuticals, Personal Care, Dairy Technology: Hot Filling, Cold Filling, Aseptic, Blow Fill Seal |
| Companies Covered | SIG Combibloc Group, WestRock Company, Tetra Pak International S.A., DS Smith PLC, Elopak AS, Amcor plc, Schott AG, Mondi PLC, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aseptic Packaging Market Evolving Landscape
Active and intelligent packaging integration is compressing the traditional separation between barrier function and supply-chain visibility, forcing converters to embed sensing layers without compromising sterilization integrity.
Multilayer coextruded films with ethylene vinyl alcohol cores are miniaturizing barrier thickness while maintaining oxygen transmission rates below 0.1 cc per square meter per day. Pediatric pharmaceutical manufacturers are adopting these formats fastest, replacing glass vials in non-critical therapeutic categories. The technology is miniaturizing equipment footprints and enabling portable filling lines for regional contract manufacturers.
EPA's PFAS restriction roadmap is eliminating fluorochemical-based sterilization barriers from aseptic packaging specifications by 2027. Converters are accelerating plasma-based surface activation and peracetic acid alternatives to maintain validation continuity. Pharmaceutical applications face the steepest compliance burden, as USP container closure standards limit experimental material substitutions.
Direct-store-delivery networks are consolidating procurement authority at regional dairy cooperative headquarters, bypassing traditional distributor intermediaries. This concentration shifts volume toward suppliers with integrated filling equipment ecosystems and captive technical service teams. The pattern is most advanced in the upper Midwest, where processor-owned logistics networks dominate shelf-stable distribution.
North America Aseptic Packaging Market Segmentation
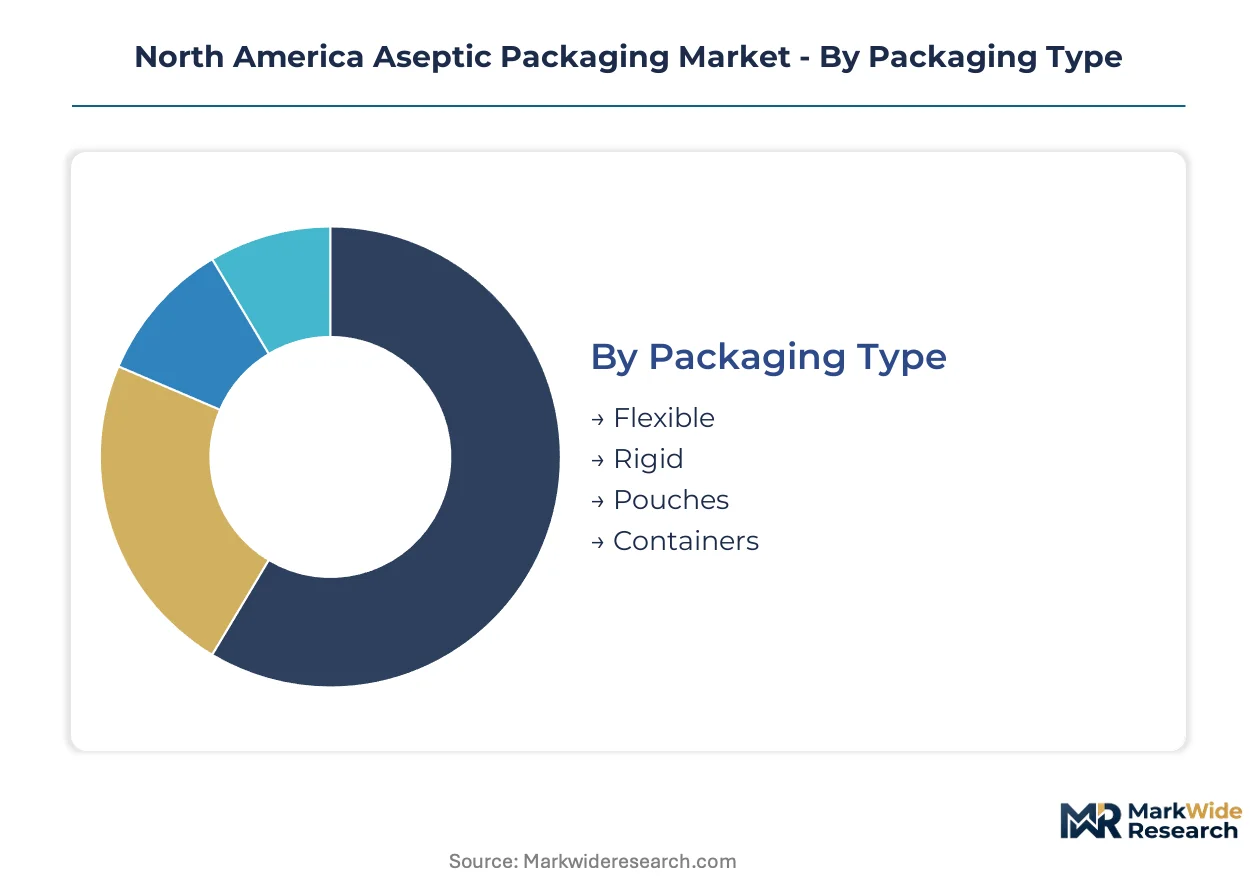
Aseptic packaging technology serves divergent supply chain economics across North American end-uses. Material selection and sterilization method directly determine which segments serve domestic dairy corridors versus export-oriented pharmaceutical operations.
Packaging Type:
Domestic dairy processing concentrates demand for rigid formats in Wisconsin and New York, while pharmaceutical exporters favor flexible solutions that reduce freight costs to Latin American and Asian markets.
- Flexible:Multilayer coextruded films with ethylene vinyl alcohol barriers achieve oxygen transmission below 0.1 cc per square meter per day. Pediatric nutrition manufacturers in Illinois and Ohio are displacing rigid bottles with retort-compatible pouches that cut per-unit shipping weight by 60 percent.
- Rigid:Polymer bottles and multilayer cartons with aluminum foil cores dominate extended-shelf-life milk distribution. The Wisconsin-New York dairy corridor generates dense procurement volumes that amortize high-speed filling equipment across cooperative processing networks.
- Pouches:Stand-up and spouted formats capture ready-to-drink nutrition share through blow-fill-seal compatibility.
- Containers:Rectangular gable-top cartons retain volume leadership in private-label juice and dairy club-store formats.
Rigid formats command the established base. The steepest expansion runs through flexible films.
Material:
Cost tier stratification separates commodity fiber from premium barrier substrates, with pharmaceutical validation requirements forcing grade-specific supply chain segregation.
- Plastic:Polyethylene terephthalate and high-density polyethylene bottles serve mass-market dairy and juice applications where hydrogen peroxide surface treatment meets FDA 21 CFR Part 113 standards. Blow-fill-seal pharmaceutical lines in New Jersey and North Carolina demand medical-grade resin specifications that exclude recycled content.
- Paperboard:Liquid packaging board with aluminum foil lamination anchors dairy carton economics through favorable printability and established post-consumer recovery infrastructure. California extended producer responsibility legislation is elevating fiber-based formats with proven recycling pathways.
- Glass:Borosilicate and soda-lime vials retain parenteral drug positioning where USP Chapter 1207 container closure integrity requirements prevent polymer substitution.
- Metal:Tinplate and aluminum cans serve niche retort applications in ready-to-eat soups and nutritional supplements.
Paperboard formats dominate volume. Plastic solutions are gaining share fastest in pharmaceutical conversion.
End User:
Customer type concentration splits between high-volume dairy cooperatives with captive technical service requirements and pharmaceutical manufacturers demanding 18-24 month validation cycles.
- Food & Beverage:Shelf-stable juice and broth applications drive carton demand through direct-store-delivery networks that bypass traditional distributor markups. Regional cooperative procurement consolidation in the upper Midwest favors suppliers with integrated filling equipment ecosystems.
- Pharmaceuticals:Biologics manufacturing expansion across Massachusetts and California requires high-barrier formats that extend shelf stability without cold-chain infrastructure. USP Chapter 797 and 800 compliance timelines strain working capital for packaging suppliers.
- Dairy:Extended-shelf-life milk and cream products concentrate procurement authority at processor headquarters in Wisconsin and New York.
- Personal Care:Aseptic lotions and serums represent emerging demand from contract manufacturers serving premium cosmetic brands.
Food and beverage commands the established base. Pharmaceuticals are climbing the fastest.
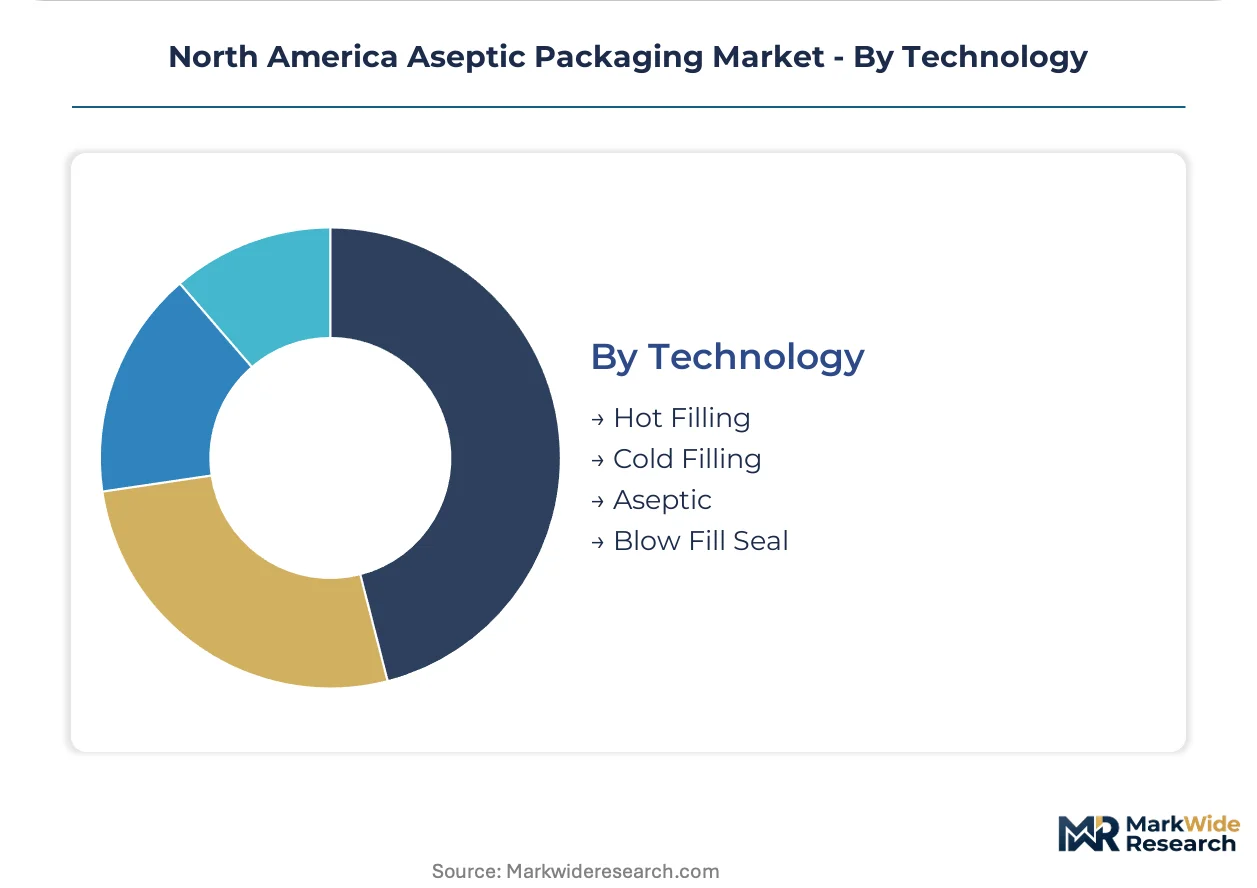
Technology:
Volume scale separates continuous high-speed dairy lines from batch-oriented pharmaceutical systems, with equipment footprint determining regional manufacturing placement.
- Aseptic:Hydrogen peroxide vapor and UV-C sterilization systems maintain commercial sterility without refrigeration for six to twelve months. The technology serves shelf-stable distribution chains where cold-chain economics prove prohibitive for liquid foods and injectable drugs.
- Blow Fill Seal:Form-fill-seal integration for polymer bottles serves ophthalmic and respiratory pharmaceutical applications where USP validation requirements limit equipment supplier options. Modular quick-changeover configurations reduce conversion downtime for mid-size contract manufacturers.
- Hot Filling:Acidified food applications in juice and sports drinks rely on thermal pasteurization before container closure.
- Cold Filling:Refrigerated distribution chains for fresh dairy and probiotic beverages operate outside true aseptic parameters.
Aseptic technology commands the established base. Blow fill seal is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands pricing leverage through its Wisconsin-New York dairy corridor density, while Canadian converters absorb cross-border regulatory friction without equivalent volume scale to negotiate input cost relief.
United States
Biologics manufacturing expansion across Massachusetts and California pulls high-barrier film technologies from adjacent dairy applications. FDA's updated sterile drug guidance compresses validation timelines for packaging suppliers serving both sectors. The Wisconsin-New York dairy corridor generates concentrated demand for extended-shelf-life cartons that amortizes filling equipment investments.
Canada
Health Canada coordinates dairy carton standards with FDA, though provincial labeling variances in Quebec and Ontario force redundant SKU proliferation. PMRA oversight of aseptic food packaging aligns with cross-border harmonization efforts. Ontario's dairy processing clusters in the Golden Horseshoe region concentrate procurement authority at cooperative headquarters.
Mexico
Export-oriented juice processors in Jalisco and the Bajío Region adopt aseptic cartons for North American market access. COFEPRIS pharmaceutical packaging regulations lag FDA validation stringency, creating dual-track compliance burdens for suppliers. Monterrey-based dairy cooperatives are expanding shelf-stable milk capacity to serve domestic informal retail channels.
North America Aseptic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American aseptic packaging market. Integrated cartonboard producers with captive fiber supply compete against specialized film converters on capital efficiency metrics. Three strategic archetypes dominate: end-to-end filling equipment ecosystems, modular quick-changeover specialists, and captive paperboard infrastructure players. Competitive moves concentrate on filling equipment bundling contracts and regional dairy cooperative procurement consolidation.
Within the integrated equipment ecosystem tier, Tetra Pak International S.A. and SIG Combibloc Group exemplify divergent approaches to line flexibility and conversion downtime reduction. WestRock Company anchors the captive infrastructure archetype through North American boxboard assets. These three occupy positions that reflect capital-intensity divergence between fiber-based and polymer-based barrier systems.
| Leading Market Players |
|---|
| SIG Combibloc Group |
| WestRock Company |
| Tetra Pak International S.A. |
| DS Smith PLC |
| Elopak AS |
| Amcor plc |
| Schott AG |
| Mondi PLC |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
High-speed filling equipment utilization rates above 85 percent in the Wisconsin-New York dairy corridor create scale economies that compress per-unit conversion costs and establish regional price floors. This concentration of amortized capital shapes competitive dynamics, as suppliers outside these dense procurement zones struggle to match unit economics without equivalent volume throughput.
Pricing Analysis
The customization-premium spread separates standard multilayer carton contracts from configured-to-order pharmaceutical-grade barrier systems. Three-tier pricing structure across premium, standard, and economy levels reflects validation tier differentiation, with USP Chapter 797-certified formats commanding substantial premiums over food-grade equivalents. Pricing pressure stems from aluminum foil energy-cost volatility transmitted from European smelters. Dairy cooperatives exhibit highest price sensitivity due to thin commodity margins, while biologics manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Inventory buffers for thin-gauge aluminum foil extend to sixteen weeks as European energy markets destabilize supplier reliability. Raw material sourcing draws from Germany, Norway, and China for foil cores, with polymer resin supply anchored in Texas and Louisiana petrochemical corridors. Single-source vulnerability concentrates in specialty hydrogen peroxide sterilization adjuncts facing EPA PFAS restrictions. Distribution runs through processor-owned logistics networks that bypass traditional distributor markups in the upper Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FDA validation entrenchment creates switching costs that lock pharmaceutical buyers into established supplier relationships for 18-24 month certification cycles.
For Market Incumbents: Consolidate filling equipment bundling contracts with regional dairy cooperatives to deepen captive relationships before modular quick-changeover specialists capture mid-size beverage processors. Expand pharmaceutical-grade film capacity in Massachusetts and California biologics clusters to capture cross-sector demand pull. Prioritize plasma-based surface activation R&D to preempt EPA PFAS compliance disruption.
For New Entrants and Emerging Players: Technical service response gaps in pediatric nutrition pouches present white-space entry points where incumbents under-serve mid-size contract manufacturers. Target Illinois and Ohio flexible film conversion demand with portable blow-fill-seal lines that reduce capital barriers. Penetrate through coextrusion barrier performance guarantees backed by accelerated validation support.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated equipment ecosystem providers with long-term dairy contracts and pharmaceutical validation pipelines. Five-to-ten-year viability favors converters with backward integration into captive fiber supply or polymer resin specifications. Monitor California extended producer responsibility implementation as inflection signal for fiber-based format preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Based Surface Activation Investment | Replaces fluorochemical sterilization barriers ahead of EPA PFAS deadlines without compromising USP validation continuity. |
| Modular Filling Equipment Deployment | Captures mid-size beverage contract manufacturing demand through quick-changeover configurations that reduce SKU conversion downtime. |
| Pharmaceutical-Grade Film Capacity Expansion | Addresses biologics manufacturing pull from Massachusetts and California clusters requiring high-barrier formats without cold-chain infrastructure. |
| Dairy Cooperative Procurement Consolidation | Locks in volume commitments across Wisconsin-New York corridor through integrated technical service and equipment bundling contracts. |
| Pediatric Nutrition Pouch Format Development | Displaces rigid bottles in Illinois and Ohio through retort-compatible coextruded films that cut per-unit shipping weight. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR guidance documents, EPA PFAS restriction roadmaps, and dairy cooperative procurement records. Primary interviews engaged filling equipment engineers, pharmaceutical packaging validation specialists, dairy processor procurement directors, and flexible film coextrusion technologists. Secondary validation drew from USP Chapter documentation, Health Canada-PMRA harmonization protocols, and state-level extended producer responsibility legislation. Bottom-up demand modeling triangulated against top-down capacity assessments across North American converter facilities.
Segmentation dimensions modeled include packaging type, material substrate, end-use application, sterilization technology, and regional regulatory cluster. Revenue projections across the analysis window incorporate equipment utilization rates, validation cycle durations, and input cost trajectories for aluminum foil and medical-grade resins. CAGRs derive from volume-throughput elasticities and price-cost compression dynamics specific to dairy versus pharmaceutical demand segments.
Underlying assumptions cover continued FDA-Health Canada regulatory harmonization and aluminum foil supply stability, with deviation risk concentrated in EPA PFAS restriction acceleration and cross-border tariff friction. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market