
 Aseptic Packaging Market | 2026-2036
Aseptic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Packaging Market Intelligence
Modular portion-size packaging is recalibrating buyer choice across the aseptic carton sector, as brands seek to balance convenience with waste reduction. Tetra Pak International SA leverages its integrated processing and packaging technology to anchor global dairy and beverage supply chains. SIG Combibloc Group competes through scalable filling equipment platforms that reduce converter capital requirements. Amcor PLC extends its material science capabilities into high-barrier films for aseptic pouch applications.
Aseptic packaging refers to the sterilization of product and container separately before sealed assembly under sterile conditions, typically employing hydrogen peroxide vapor or UV-C treatment on paperboard-polyethylene-aluminum laminate structures to achieve commercial sterility without refrigeration. Its primary purpose is to extend shelf life for sensitive liquids and semi-solids while preserving nutritional and sensory properties. Cartons and pouches within the product type dimension lead volume adoption in beverages, though bags and trays capture expanding share in prepared meals and institutional foodservice. Composites dominate the material mix due to their oxygen and light barrier performance, while plastic and glass alternatives occupy distinct niches in pharmaceutical and premium personal care segments.
The US FDA enforces sterility assurance and container closure integrity standards for aseptic pharmaceutical packaging, while the EU MDR tightens material migration limits and traceability requirements for medical and food-contact applications. China's SAMR implements GB standards for composite packaging safety that directly shape import qualification and local sourcing decisions. Stakeholders must monitor evolving extended producer responsibility frameworks and carbon border adjustments that will redefine cost structures and geographic sourcing strategies.
Market Dynamics
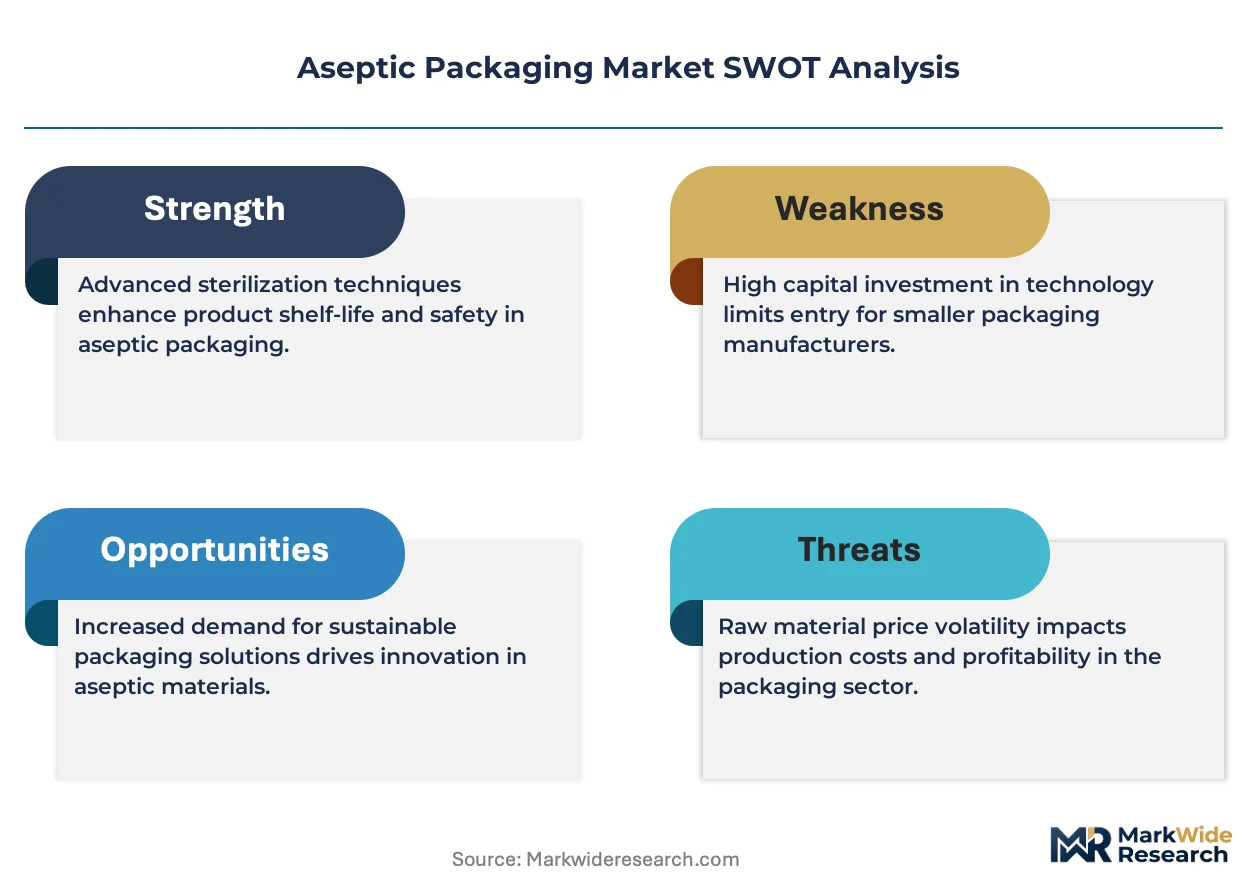
The EU F-Gas Regulation and China's dual carbon goals are compressing material choices for converters, forcing rapid substitution of high-GWP barrier films and aluminum-intensive laminates while simultaneously opening procurement advantages for bio-based and recycled-content alternatives.
Growth Catalysts
- UHT milk penetration in India:FSSAI's food safety modernization and cold-chain gaps in rural distribution are accelerating carton adoption for dairy and plant-based beverages.
- REACH-compliant barrier films:ECHA's restrictions on per- and polyfluoroalkyl substances are redirecting R&D toward silicon oxide and aluminum oxide vapor-deposited coatings.
- Pharmaceutical export compliance:India's CDSCO alignment with EU MDR traceability requirements is expanding aseptic vial and bag demand for sterile injectables.
Market Restraints
- Aluminum price volatility:Primary aluminum smelter curtailments in Sichuan and Yunnan provinces are transmitting cost spikes through laminate supply chains.
- Barrier film supply concentration:Three Asian petrochemical conglomerates control over 70% of global EVOH resin capacity, creating single-source vulnerability.
- Hydrogen peroxide sterilization limits:Residual H2O2 thresholds under FDA 21 CFR 176.170 constrain line speeds and capital efficiency.
Strategic Opportunities
- Sub-Saharan Africa dairy:Tetra Pak's school milk programs and Nestlé's rural distribution partnerships are establishing carton infrastructure ahead of competitor entry.
- Cell-cultured meat media:Aseptic bag-in-box formats for growth factor solutions represent an uncaptured pharmaceutical-adjacent vertical.
- Extended Producer Responsibility frameworks:France's Citeo eco-modulation bonuses and Italy's CONAI packaging tax reductions incentivize fiber-based format switches.
Industry Challenges
- Sterile validation engineering shortage:ISO 13485 and FDA process validation expertise concentrates in Basel and Boston clusters, constraining facility expansion timelines.
- Legacy filling line retrofit complexity:Converters face 18-24 month integration cycles when upgrading from roll-fed carton to pouch formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Packaging Market |
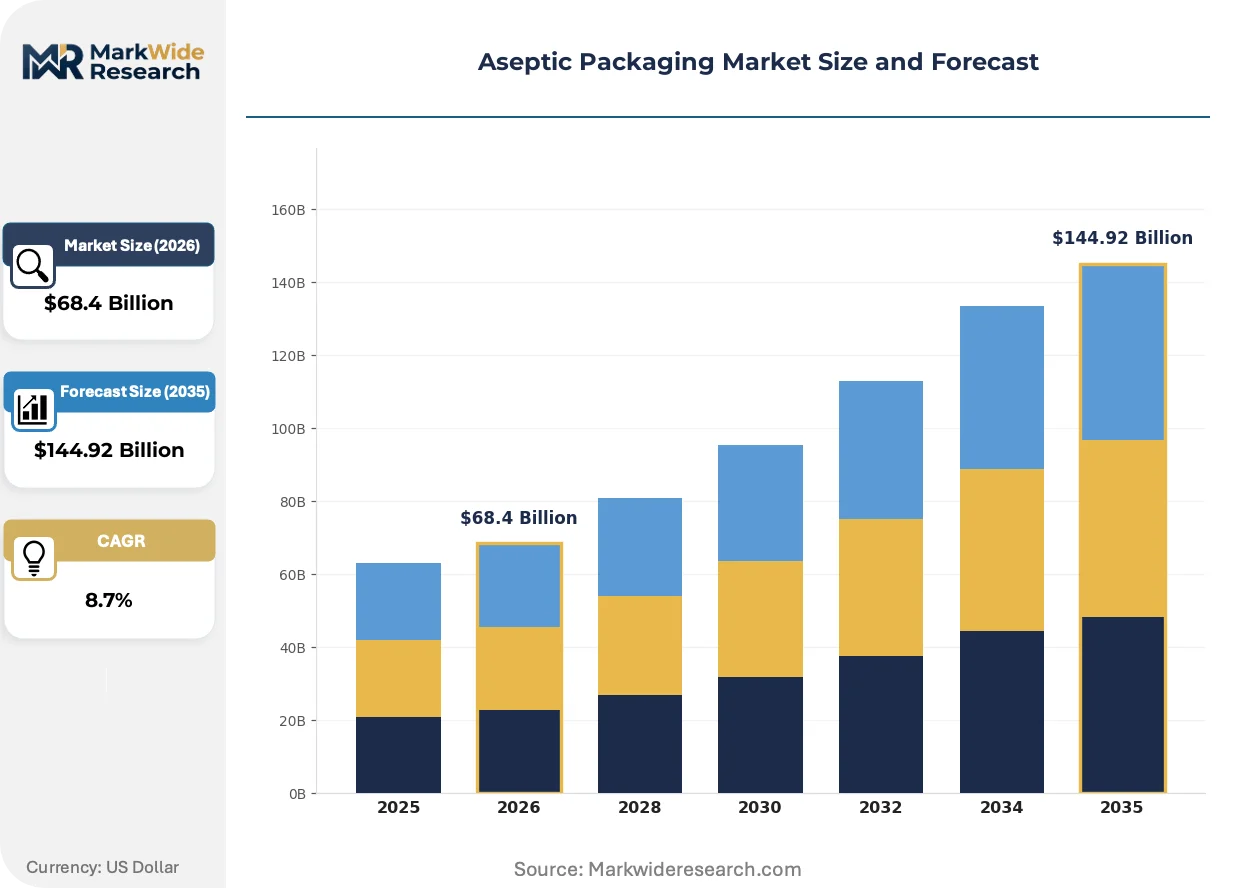
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Bags, Trays, Pouches Material: Plastic, Glass, Metal, Composites End User: Food & Beverages, Pharmaceuticals, Personal Care, Chemicals Technology: Hot Filling, Cold Filling, Aseptic Processing, Ultra-High Temperature |
| Companies Covered | Tetra Pak International SA, SIG Combibloc Group, Amcor PLC, Elopak AS, Greatview Aseptic Packaging, Robert Bosch GmbH, Reynolds Group Holdings Limited, Sealed Air Corporation, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging integration, hydrogen peroxide reduction technologies, and mono-material laminate architectures are compressing traditional multi-layer composite dominance while enabling new circularity claims.
Electron beam sterilization is decentralizing aseptic processing economics. Dairy cooperatives in Wisconsin and Bavaria are piloting compact e-beam units that eliminate chemical sterilants and reduce energy intensity by 40%. This technology is decentralizing filling operations from centralized mega-plants to regional dairy hubs, collapsing the radius of fresh milk collection and shortening finished goods distribution.
The EU F-Gas Regulation's phasedown schedule is forcing refrigerant-dependent cold chains toward ambient-stable alternatives. Beverage brands are responding by accelerating UHT and ESL format transitions in Southern Europe, where summer temperature excursions previously mandated refrigerated distribution. This regulatory compression is most acute in Spain and Italy, where ambient distribution networks are expanding fastest.
Direct-to-retailer procurement contracts are displacing traditional converter-distributor relationships. German discounters and French supermarket chains now negotiate directly with SIG and Tetra Pak for private-label beverage cartons, extracting volume commitments and sustainability certifications that intermediaries cannot match. This channel consolidation is most visible in the Benelux region, where retailer buying groups command 60% of ambient dairy volume.
Aseptic Packaging Market Segmentation
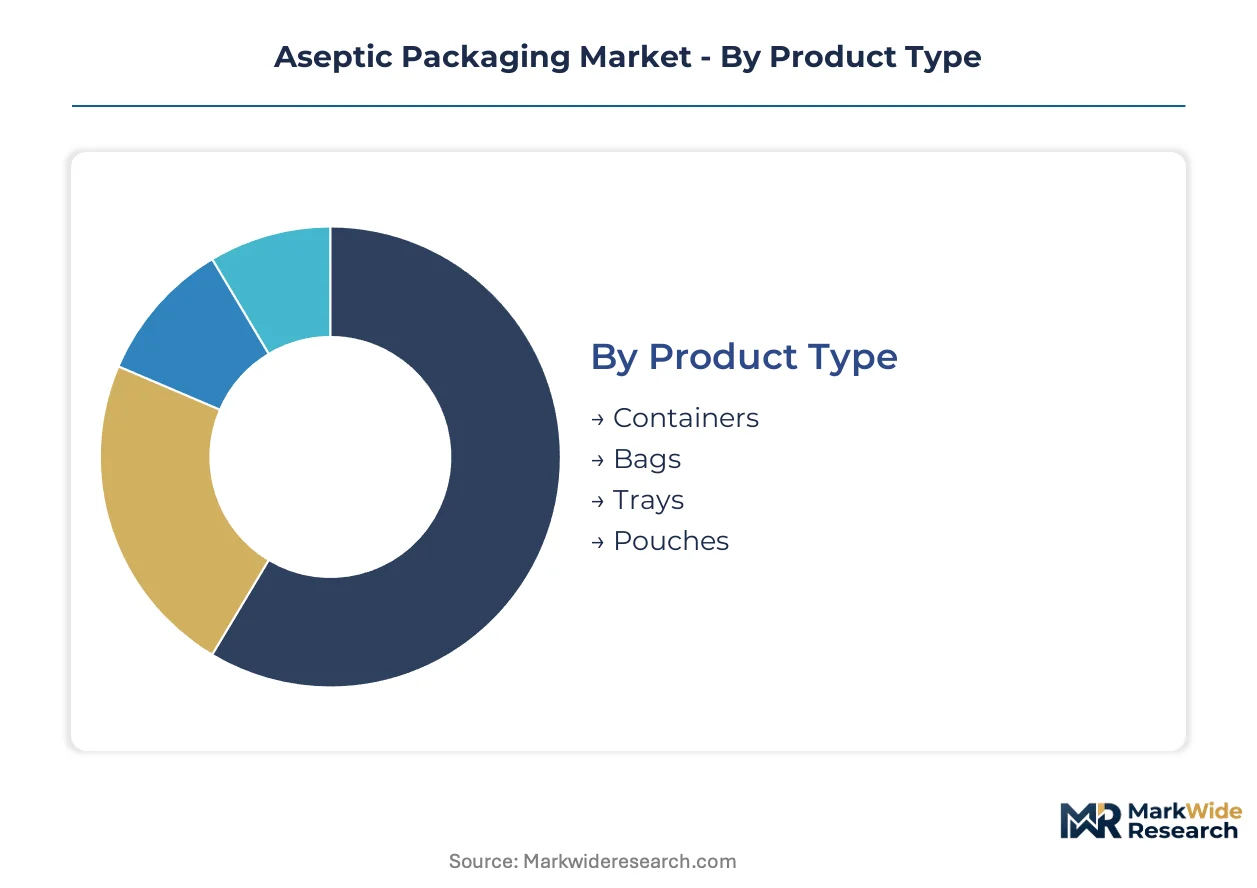
Aseptic packaging segmentation reveals divergent margin structures across format types and sterilization technologies. Material choices and regulatory compliance requirements reshape competitive positioning differently in dairy versus pharmaceutical applications.
Product Type:
Volume concentration favors rigid formats for liquid beverages, while flexible alternatives capture prepared meal and institutional growth corridors.
- Containers:Paperboard-polyethylene-aluminum laminates dominate UHT milk and juice distribution in India and Southern Europe. Tetra Pak and SIG filling lines anchor dairy supply chains where cold-chain gaps persist.
- Pouches:Stand-up and spouted formats for plant-based beverages and liquid pharmaceuticals are climbing the fastest as brands seek lightweighting and shelf differentiation. Amcor and Mondi expand high-barrier film capacity for this transition.
- Bags:Bag-in-box systems for wine, foodservice syrups, and cell-cultured media solutions leverage EVOH barrier layers.
- Trays:Rigid thermoformed formats capture ready-meal and healthcare foodservice demand in Japan and Western Europe.
Today's leader: Containers. Tomorrow's challenger: Pouches.
Material:
Barrier performance requirements stratify material selection by oxygen sensitivity and light exposure tolerance of packaged contents.
- Composites:Multi-layer paperboard-polyethylene-aluminum structures deliver 6-12 month shelf stability for ambient dairy. EU F-Gas Regulation and China's dual carbon goals are compressing aluminum-intensive laminate economics.
- Plastic:PET and HDPE bottles with vapor-deposited silicon oxide coatings serve pharmaceutical oral liquids and premium personal care. REACH-compliant barrier films redirect R&D away from PFAS-containing structures.
- Glass:Borosilicate and molded vials retain dominance for parenteral pharmaceuticals requiring visual inspection and inert contact surfaces.
- Metal:Tinplate and aluminum cans persist in niche beverage segments and institutional foodservice portions.
Composites retain volume dominance. Plastic formats gain share fastest in pharmaceutical adjacencies.
End User:
Regulatory stringency separates food-contact compliance from pharmaceutical validation requirements, creating distinct supplier qualification pathways.
- Food & Beverages:UHT milk, plant-based drinks, and ambient juices drive carton consumption. India's FSSAI modernization and rural cold-chain gaps accelerate adoption.
- Pharmaceuticals:Sterile injectables, ophthalmic preparations, and biologic media demand ISO 13485 and FDA process validation. India's CDSCO alignment with EU MDR traceability requirements expands aseptic vial and bag demand.
- Personal Care:Premium skincare and cosmetic serums utilize glass and high-barrier plastic for oxidation-sensitive formulations.
- Chemicals:Industrial reagents and laboratory media employ bag-in-box and drum formats with chemical resistance specifications.
Food and beverage anchors current volume. Pharmaceuticals deliver premium pricing and longest contract durations.
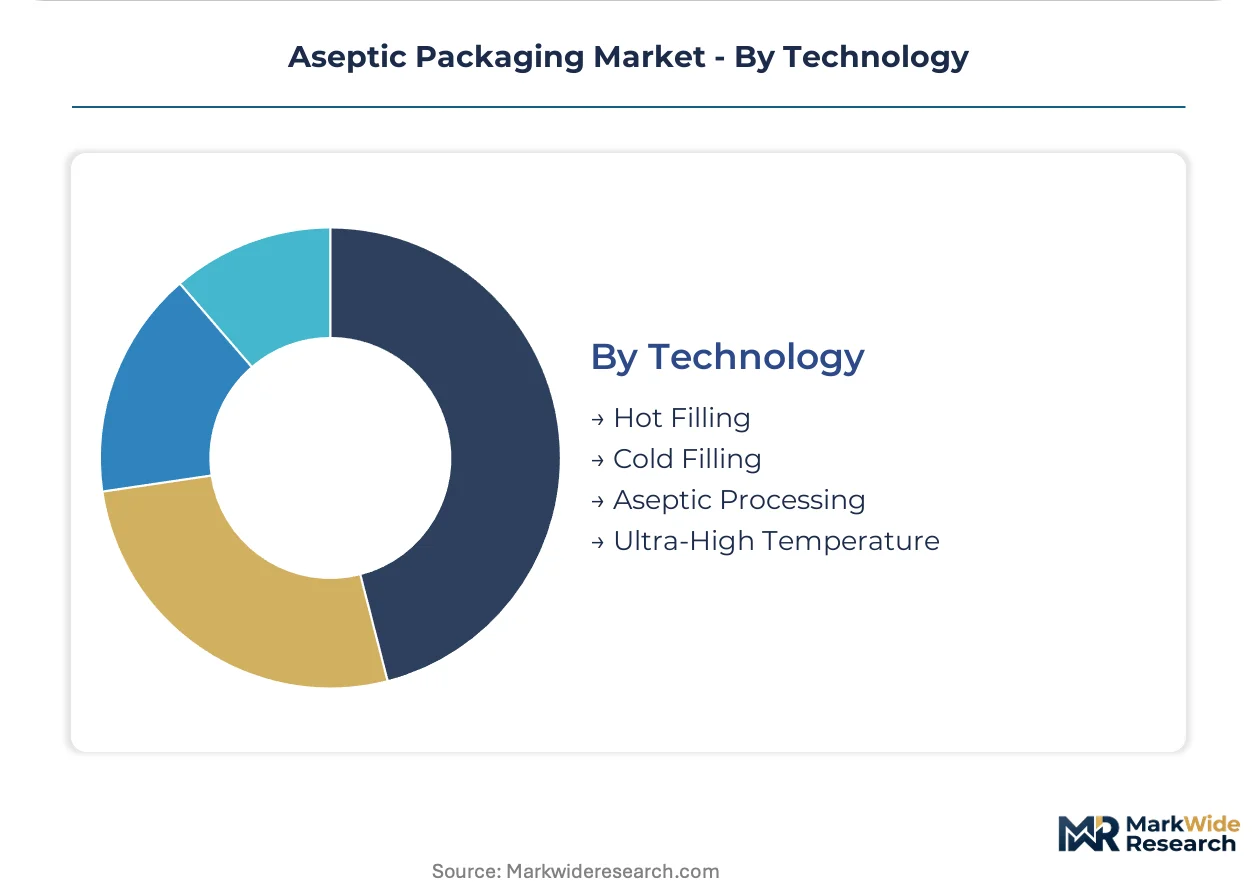
Technology:
Sterilization method selection determines capital intensity, line speed, and energy consumption profiles for converter operations.
- Aseptic Processing:Hydrogen peroxide vapor or UV-C treatment of packaging surfaces combined with UHT product sterilization enables ambient distribution without refrigeration. Residual H2O2 thresholds under FDA 21 CFR 176.170 constrain line speeds.
- Ultra-High Temperature:135-150°C product sterilization paired with sterile filling achieves commercial sterility for extended shelf-life dairy. Electron beam sterilization pilots in Wisconsin and Bavaria eliminate chemical sterilants and reduce energy intensity.
- Hot Filling:85-95°C product temperatures with heat-resistant containers suit high-acid beverages and some prepared foods.
- Cold Filling:Refrigerated distribution chains for fresh-like taste preservation in premium dairy and juice segments.
Aseptic processing dominates installed base. Ultra-high temperature formats expand most quickly as ambient distribution networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aseptic packaging technology achieved commercial scale in Sweden during the 1960s, establishing the technical foundation that now supports ambient distribution networks across multiple continents. The industry's geographic expansion follows cold-chain infrastructure gaps and regulatory tightening on food safety and carbon emissions.
India
UHT milk penetration and pharmaceutical export growth drive carton demand in Maharashtra and Gujarat. FSSAI's food safety modernization mandates sterility assurance standards that accelerate converter qualification timelines. Tetra Pak and domestic suppliers expand filling line capacity around Pune and Ahmedabad to capture rural dairy distribution.
China
Dual carbon goals and GB standards for composite packaging safety compress aluminum-intensive laminate economics in the Yangtze River Delta. SAMR implements stricter migration limits that reshape import qualification protocols. Local converters in Jiangsu and Zhejiang provinces pivot toward bio-based barrier films to maintain procurement access.
Germany
Electron beam sterilization pilots in Bavaria eliminate chemical sterilants and reduce energy intensity for regional dairy cooperatives. ECHA's REACH restrictions on PFAS redirect R&D toward silicon oxide vapor-deposited coatings. SIG Combibloc maintains engineering centers near Lübeck that anchor North European filling equipment supply chains.
United States
FDA sterility assurance standards for pharmaceutical packaging concentrate validation expertise in Greater Boston and Basel-linked operations. Wisconsin dairy hubs pilot compact e-beam units that decentralize processing from mega-plants. Extended producer responsibility frameworks in California and New York reshape material procurement specifications for beverage brands.
Brazil
School milk programs and ambient juice distribution expand carton infrastructure in São Paulo and Minas Gerais states. ANVISA alignment with international pharmaceutical standards opens aseptic bag demand for sterile injectables. Nestlé's rural distribution partnerships establish converter relationships ahead of competitor entry in the Northeast region.
Aseptic Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration and validation capability dimensions. The vendor base clusters around three strategic archetypes: integrated processing-packaging technology providers, scalable filling equipment platforms, and high-barrier material science specialists. Consolidation pressure intensifies as direct-to-retailer procurement contracts displace traditional converter-distributor relationships. Capacity expansion and strategic partnerships dominate competitive moves as brands extract volume commitments and sustainability certifications.
Within the integrated technology tier, Tetra Pak International SA and SIG Combibloc Group exemplify providers that anchor global dairy and beverage supply chains through captive processing and packaging system integration. Amcor PLC occupies a position among material science specialists extending capabilities into high-barrier film applications. These three entities represent distinct competitive vectors: processing-packaging integration, scalable equipment platforms, and barrier material innovation.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| SIG Combibloc Group |
| Amcor PLC |
| Elopak AS |
| Greatview Aseptic Packaging |
| Robert Bosch GmbH |
| Reynolds Group Holdings Limited |
| Sealed Air Corporation |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
Aluminum ingot costs cascade through laminate supply chains into three-tier pricing structures across premium, standard, and economy levels, with converter margins compressing most acutely in aluminum-intensive composite formats serving Southern European dairy brands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier films from food-contact cartons and commodity pouch formats. Price differentiation hinges on ISO 13485 certification status and EVOH barrier layer thickness specifications. Pricing pressure stems from Sichuan and Yunnan smelter curtailments transmitting volatility through primary aluminum markets. Generic dairy converters exhibit highest price sensitivity, while sterile pharmaceutical packaging buyers prioritize validation capability over unit economics.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Zhejiang provinces are forcing automation investments at laminate converting facilities. Supply concentrates in China, Germany, and India for filling equipment and barrier film production. Raw material flows draw from South Korean and Japanese petrochemical complexes for EVOH resin and from Australian bauxite refineries for aluminum feedstock. Single-source vulnerability pervades EVOH capacity concentration among three Asian conglomerates. Distribution runs through direct-to-retailer procurement channels displacing traditional converter-distributor relationships in Benelux and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade validation services and electron beam sterilization equipment, with cost compression in chemical sterilant-dependent processing creating tier shift potential toward premium ambient distribution formats.
For Market Incumbents: Hedge aluminum price exposure through backward integration into recycled-content laminate supply or bio-based barrier film partnerships. Tetra Pak and SIG should accelerate Bavaria-style e-beam pilot deployment to defend processing-packaging integration margins against chemical sterilant cost volatility. Capture CDSCO-aligned validation capability in Pune and Ahmedabad clusters before pharmaceutical export compliance timelines tighten.
For New Entrants and Emerging Players: Capture Sub-Saharan African dairy infrastructure gaps through school milk program partnerships ahead of Tetra Pak's established rural distribution networks. Cell-cultured meat media bag-in-box formats represent the most penetrable pharmaceutical-adjacent vertical with uncapped demand from growth factor solution suppliers. Lead with EPR framework compliance and Citeo eco-modulation bonus qualification to differentiate against legacy composite converters.
For Investors and Strategic Acquirers: Consolidation pressure builds where sterile validation engineering scarcity intersects with ISO 13485 certification backlogs in Basel and Boston clusters. Five-to-ten year viability favors mid-cap specialists with captive barrier film R&D and FDA process validation track records. Monitor ECHA PFAS restriction implementation timelines and FDA residual H2O2 threshold enforcement as inflection indicators for technology substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Sterilization Deployment | Wisconsin and Bavaria dairy hubs eliminate hydrogen peroxide dependency while collapsing distribution radius from mega-plants. |
| Bio-Based Barrier Film Capacity Expansion | Jiangsu and Zhejiang converters pivot from aluminum-intensive laminates to maintain SAMR procurement access under dual carbon goals. |
| Pharmaceutical Validation Service Buildout | Pune and Ahmedabad facilities capture CDSCO-EU MDR alignment demand for sterile injectable packaging. |
| Direct-to-Retailer Contract Negotiation | German discounters and French supermarket chains extract volume commitments that intermediaries cannot match in Benelux dairy. |
| Extended Producer Responsibility Compliance | France's Citeo eco-modulation bonuses and Italy's CONAI tax reductions incentivize fiber-based format switches ahead of regulatory deadlines. |
Research Approach
Bottom-up food and beverage end-use modeling reconciled against top-down filling equipment and barrier film supply tracking forms the analytical core of this study. Primary interviews with dairy processing executives, pharmaceutical packaging validation engineers, retail category buyers, and laminate converting plant managers combined with secondary validation from FDA 21 CFR filings, ECHA REACH restriction updates, FSSAI food safety modernization directives, and customs trade data for aluminum and EVOH resin flows. Triangulation across these sources ensures segmentation integrity across product type, material, end user, and sterilization technology dimensions.
Input-output matrices map carton, pouch, bag, and tray format demand against installed filling line capacity and raw material availability throughout the projection horizon. Segmentation dimensions modeled include product format rigidity, barrier material composition, end-use regulatory stringency, and sterilization technology capital intensity. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporate EU F-Gas Regulation phasedown schedules and India's UHT milk penetration curves.
Primary aluminum smelter curtailment extensions, EVOH resin supply disruptions, and FDA sterility assurance enforcement shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology substitution elasticities. Practitioners should monitor ECHA PFAS restriction implementation, SAMR GB standard updates, and electron beam sterilization pilot scale-up rates for early signals of trajectory deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market