
 Kidney Cancer Drugs Market | 2026-2036
Kidney Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Cancer Drugs Market Intelligence
Next-generation combination immunotherapy protocols is reorganizing competitive dynamics in renal cell carcinoma treatment. Bristol-Myers Squibb leverages its dual checkpoint inhibitor portfolio to anchor market presence in first-line settings. Merck & Co. sustains dominance through pembrolizumab-based combinations across multiple approval lines. Exelixis specializes in tyrosine kinase inhibitor combinations that differentiate its portfolio in the metastatic segment.
Kidney cancer drugs comprise systemic therapeutic agents designed to interrupt tumor proliferation, angiogenesis, or immune evasion in renal cell carcinoma, with molecular targets including VEGF receptors, PD-1/PD-L1 pathways, and mTOR signaling cascades. These agents serve primarily to extend progression-free survival and overall survival in patients with advanced or metastatic disease. Immunotherapy commands the largest revenue pool within product type segmentation due to durable responses in checkpoint inhibitor combinations, while targeted therapy retains substantial share through established VEGF-TKI protocols in second-line and later settings. Oral delivery mode leads volume consumption because of patient convenience and at-home administration feasibility, though intravenous routes persist in hospital-based combination regimens.
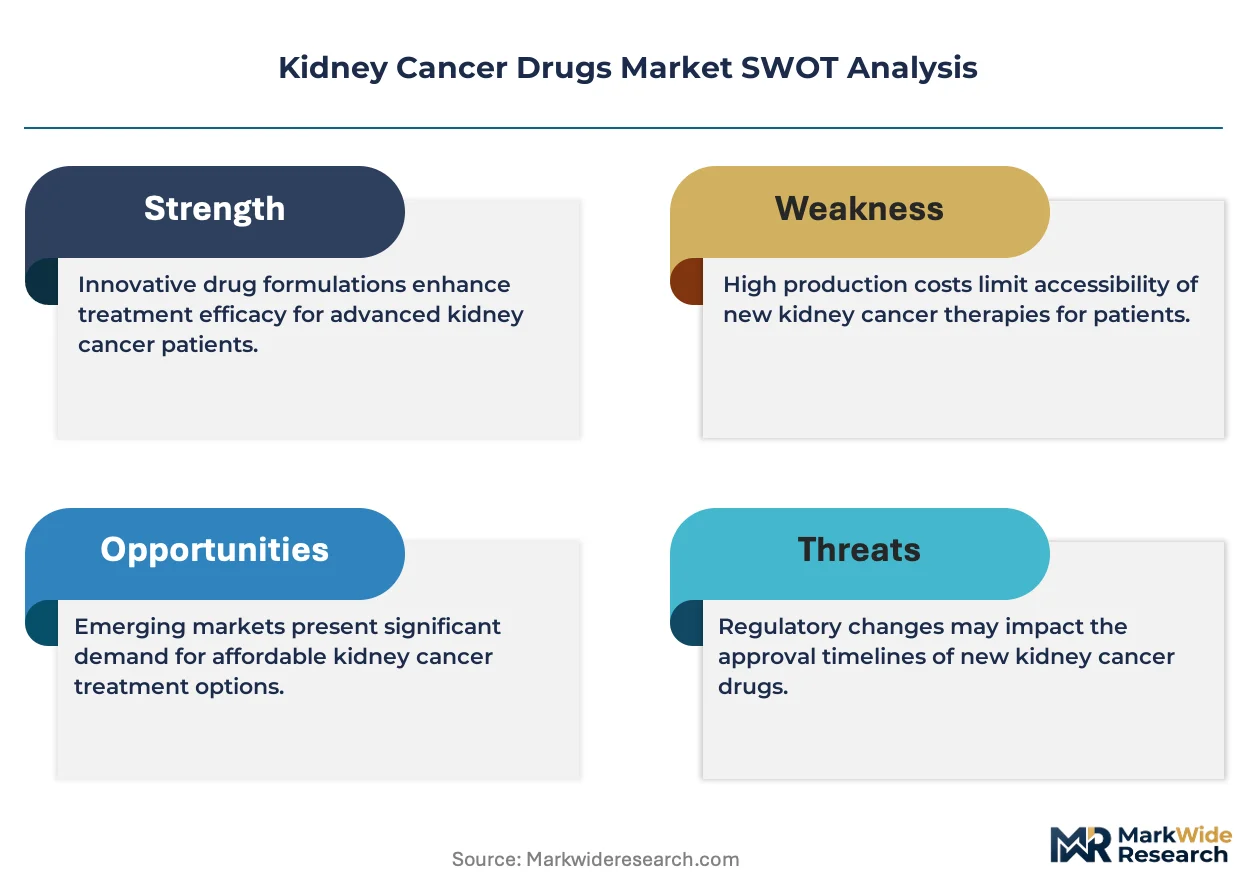
FDA accelerated approval pathways and EMA conditional marketing authorizations compress development timelines for novel renal cell carcinoma therapies, directly shaping competitive entry sequences and prescriber access patterns. REACH compliance and EU MDR requirements govern manufacturing quality and post-market surveillance for European distribution, adding cost layers that influence regional pricing structures. Stakeholders must monitor evolving biomarker-driven patient stratification criteria that will determine which therapeutic classes capture priority positioning in treatment guidelines.
Market Dynamics
Checkpoint inhibitor combination protocols are compressing treatment timelines and reordering prescriber hierarchies across oncology departments. The FDA's accelerated approval pathway enables earlier market entry for dual immunotherapy regimens, forcing rapid formulary adjustments.
Growth Catalysts
- Biomarker-driven patient stratification:PD-L1 expression testing and genomic profiling now guide first-line therapy selection, expanding addressable populations for combination protocols.
- IRA Medicare price negotiation provisions:The Inflation Reduction Act's pricing mechanisms are redirecting R&D investment toward breakthrough-designated therapies with faster commercialization paths.
- Hospital outpatient infusion center expansion:United States health systems are building dedicated immuno-oncology units capable of administering complex combination regimens.
Market Restraints
- Monoclonal antibody manufacturing concentration:Contract manufacturing organizations in Ireland and Singapore control critical biologics capacity, creating single-source vulnerability for combination therapies.
- EMA conditional marketing authorization timelines:European post-approval confirmatory trial requirements extend revenue recognition delays by 18-24 months versus FDA pathways.
- Platinum-group metal catalyst costs:Small-molecule synthesis for tyrosine kinase inhibitors faces input volatility from South African and Russian supply concentration.
Strategic Opportunities
- Adjuvant therapy expansion:Post-surgical immunotherapy protocols in resected renal cell carcinoma represent unpenetrated demand pools outside metastatic settings.
- Japan's Sakigake designation pathway:PMDA's priority review system offers 50% faster approval timelines for combination regimens addressing unmet need.
- Telemedicine-enabled oral therapy management:Remote monitoring platforms for at-home TKI administration are opening rural patient access previously limited to infusion centers.
Industry Challenges
- Immuno-oncology nursing specialization gaps:Combination regimen administration requires certified oncology nurses trained in immune-related adverse event management, with workforce shortages concentrated in community hospital settings.
- Cross-border trial data harmonization:Divergent EMA and FDA biomarker validation requirements force duplicate patient stratification studies, extending development costs.
- Cold chain integrity for biologics distribution:Temperature-controlled logistics for checkpoint inhibitors face last-mile breakdowns in emerging market pharmacy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Cancer Drugs Market |
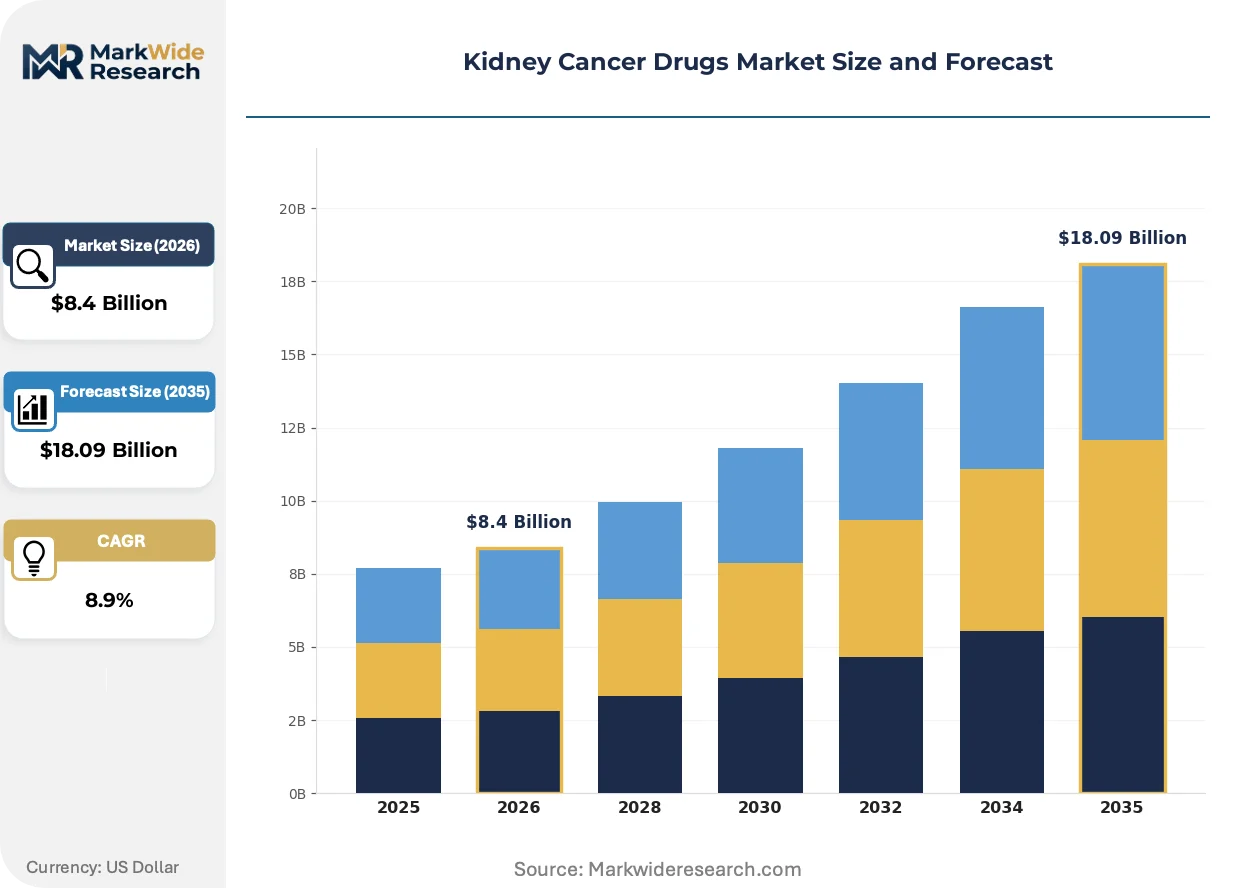
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.09 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Hormonal Therapy Delivery Mode: Oral, Intravenous, Subcutaneous, Localized End User: Hospitals, Clinics, Homecare, Research Institutions Regulatory Approval Status: FDA Approved, EMA Approved, Investigational, Not Approved |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., AstraZeneca PLC, Exelixis Inc., Bayer AG, Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Cancer Drugs Market Strategic Shifts & Innovations
Next-generation sequencing platforms are personalizing therapeutic selection beyond histology-based protocols. Artificial intelligence models trained on real-world evidence datasets now predict immunotherapy response probabilities before treatment initiation.
Chimeric antigen receptor T-cell therapies modified for solid tumor penetration are fragmenting the metastatic renal cell carcinoma treatment algorithm. Academic medical centers in Boston and Houston are piloting CAR-T manufacturing partnerships with hospital-based cell therapy labs. This cellular approach is fragmenting the historical dominance of small-molecule and antibody-based systemic therapies by enabling durable complete responses in checkpoint-refractory populations.
EMA's Medical Device Regulation (MDR) reclassification of companion diagnostic devices is tightening co-approval requirements for PD-L1 assays used in patient selection. In vitro diagnostic manufacturers must now submit parallel quality management system documentation, compressing synchronization timelines between drug and test launches. European oncology practices are responding by consolidating testing contracts with CAP-accredited laboratories capable of dual compliance.
Specialty pharmacy distribution for oral oncology agents is displacing traditional wholesale channels in the United States. CVS Health and OptumRx are building dedicated oncology pharmacist networks capable of adherence monitoring and adverse event triage. This channel shift is most visible in Medicare Part D populations, where mail-order specialty pharmacies now capture over sixty percent of TKI volume through manufacturer rebate optimization.
Kidney Cancer Drugs Market Segmentation
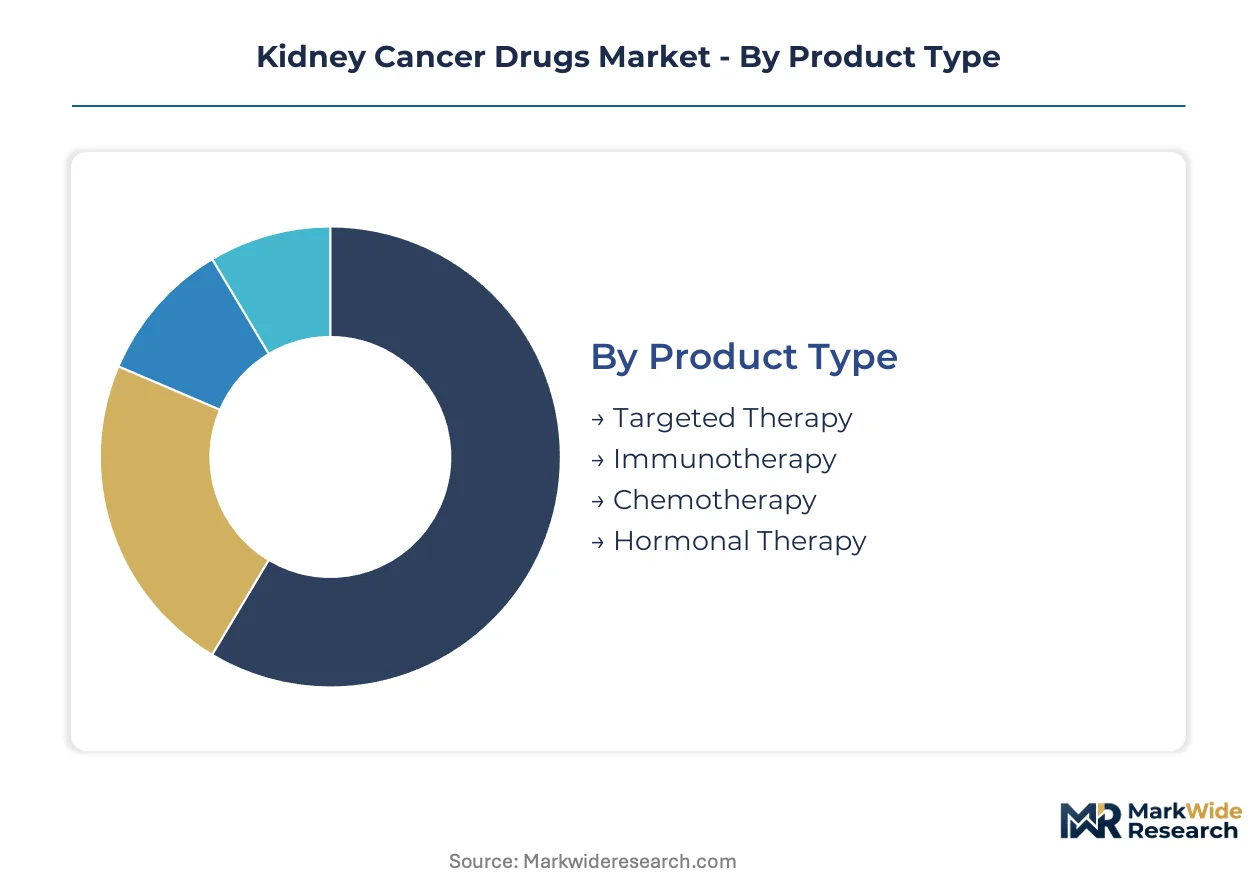
Kidney cancer drug segmentation reveals divergent margin architectures across therapeutic modalities and care settings. Treatment protocol complexity and reimbursement density determine where pharmaceutical manufacturers capture sustainable returns.
Product Type:
Margin pools concentrate in immunotherapy combinations, where checkpoint inhibitor protocols command premium pricing through durable survival benefits in first-line renal cell carcinoma.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR inhibitors interrupt angiogenic signaling through VEGF receptor blockade. Demand concentrates in second-line and later treatment settings across United States community oncology practices, where oral administration protocols reduce infusion center burden.
- Immunotherapy:PD-1 and CTLA-4 checkpoint inhibitors reprogram T-cell antitumor responses. United States hospital outpatient departments drive volume through pembrolizumab-nivolumab combination regimens, supported by Medicare reimbursement density and FDA breakthrough therapy designations.
- Chemotherapy:Cytotoxic agents retain niche application in sarcomatoid variant renal cell carcinoma with limited alternative options.
- Hormonal Therapy:Androgen pathway modulation sees exploratory use in rare papillary subtype presentations.
Targeted therapy holds installed capacity. Immunotherapy is rotating up the share rankings.
Delivery Mode:
Volume distribution splits between patient-convenience oral formats and hospital-controlled infusion routes, with cost tier differentiation determining access patterns.
- Oral:Small-molecule TKIs enable at-home administration with reduced healthcare utilization. United States specialty pharmacy networks capture dispensing volume through Medicare Part D channels, where manufacturer rebate structures optimize patient cost-sharing.
- Intravenous:Monoclonal antibody infusions require supervised administration in certified oncology units. Hospital-based immuno-oncology departments in Boston and Houston medical centers anchor demand for combination checkpoint inhibitor protocols.
- Subcutaneous:Emerging formulations reduce infusion duration and nursing resource requirements.
- Localized:Intra-arterial and intravesical delivery retains experimental status in isolated institutional protocols.
Intravenous holds installed capacity. Oral is rotating up the share rankings.
End User:
Customer type segmentation reflects care setting reimbursement hierarchies and prescriber specialization levels.
- Hospitals:Academic medical centers and community hospital systems administer complex combination regimens requiring immune-related adverse event management capabilities. United States NCI-designated cancer centers in Baltimore and Seattle anchor clinical trial enrollment and early adoption.
- Clinics:Community oncology practices handle stable oral TKI maintenance therapy with remote monitoring support.
- Homecare:Nurse-administered subcutaneous protocols expand rural patient access beyond infusion center geography.
- Research Institutions:Phase I units in Philadelphia and San Francisco academic centers drive investigational pipeline exposure.
Hospitals hold installed capacity. Homecare is rotating up the share rankings.
Regulatory Approval Status:
Maturity stratification determines commercial access velocity and prescriber confidence thresholds.
- FDA Approved:Full marketing authorization enables unrestricted commercial promotion and formulary placement. United States prescribers prioritize these agents for liability protection and payer coverage certainty.
- EMA Approved:European conditional marketing authorizations create parallel market entry with post-approval confirmatory requirements.
- Investigational:Expanded access programs and clinical trial participation provide pre-approval revenue streams.
- Not Approved:Compassionate use and off-label prescribing persist in selected refractory cases with documented informed consent.
FDA Approved holds installed capacity. Investigational is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net pharmaceutical trade flows concentrate in jurisdictions with advanced manufacturing infrastructure and regulatory harmonization. The United States maintains substantial import dependency for finished biologics despite domestic formulation capacity. European Union member states balance cross-border supply chains with centralized EMA oversight.
United States
Medicare Part D reimbursement density and FDA breakthrough therapy designations attract first-line immunotherapy launches. The Inflation Reduction Act's price negotiation provisions are redirecting pipeline investment toward orphan indications. NCI-designated cancer centers in Baltimore and Seattle anchor clinical trial enrollment and prescriber training networks.
Germany
Hospital outpatient infusion center expansion drives checkpoint inhibitor volume through statutory health insurance channels. EMA conditional marketing authorizations enable parallel access with post-approval confirmatory requirements. The Rhine-Ruhr metropolitan cluster hosts centralized pharmacy distribution hubs serving Benelux and Nordic markets.
Japan
PMDA's Sakigake designation compresses review timelines for combination regimens addressing unmet need. Aging demographics expand the addressable patient pool for metastatic renal cell carcinoma therapies. The Kanto region's academic medical centers in Tokyo and Yokohama pilot adjuvant immunotherapy protocols in resected disease.
United Kingdom
NICE technology appraisals determine NHS England commissioning decisions with cost-effectiveness thresholds. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes for innovative oncology medicines. The Greater Manchester and London cancer alliances consolidate pathology services for biomarker-driven patient stratification.
Switzerland
Swissmedic's streamlined review procedures attract European headquarters for multinational pharmaceutical operations. Premium pricing acceptance supports early commercialization of novel mechanisms outside EU reference pricing constraints. The Basel biotech corridor concentrates immuno-oncology research partnerships between academic institutions and contract development organizations.
Kidney Cancer Drugs Market Key Industry Players
Listed leaders compete with private specialists across checkpoint inhibitor and tyrosine kinase inhibitor portfolios. The market structure consolidates around large-cap pharmaceutical groups with dual immunotherapy assets and mid-cap biotechs with targeted therapy specialization. Three archetypes dominate: diversified conglomerates with oncology divisions, immuno-oncology pure-plays, and targeted therapy specialists. Competitive dynamics center on combination regimen data generation and accelerated approval pathway navigation.
Within the diversified pharmaceutical tier, Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions anchored by PD-1 checkpoint inhibitor franchises. Exelixis Inc. represents the targeted therapy specialist archetype with kinase inhibitor expertise. These three entities exemplify the strategic segmentation between immunotherapy scale players and precision medicine innovators reshaping renal cell carcinoma treatment hierarchies.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca PLC |
| Exelixis Inc. |
| Bayer AG |
| Astellas Pharma Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between biologics manufacturers and hospital systems lock in supply access for checkpoint inhibitors while anchoring price visibility through multi-year reimbursement contracts. These structures concentrate negotiating power with United States NCI-designated cancer centers and European hospital consortia, compressing margins for contract manufacturing organizations in Ireland and Singapore.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures for immuno-oncology portfolios, though hospital procurement committees exert countervailing pressure through formulary exclusion threats. Price differentiation rests on FDA breakthrough therapy designation tiering and companion diagnostic bundling, with Medicare Part D rebate optimization intensifying cost compression in oral TKI segments. Community oncology practices demonstrate highest price sensitivity due to limited pass-through reimbursement, while academic medical centers absorb premium pricing for combination protocol access.
Supply Chain Analysis
Just-in-time inventory strategies dominate biologics distribution, though platinum-group metal catalyst stockpiling persists among tyrosine kinase inhibitor manufacturers facing South African and Russian supply volatility. Active pharmaceutical ingredient production concentrates in India and China, with monoclonal antibody fill-finish capacity tethered to Ireland and Singapore. Single-source vulnerability in contract manufacturing creates structural risk for dual checkpoint inhibitor combinations. Distribution runs through specialty pharmacy networks for oral agents and hospital-based infusion centers for intravenous biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kidney cancer drugs market exhibits defensive moat characteristics through regulatory entrenchment, where FDA accelerated approval pathways and EMA conditional marketing authorizations create multi-year lead times for competitive entry.
For Market Incumbents: Shield market position by deepening manufacturing partnerships with Irish and Singaporean contract organizations to secure biologics capacity against emerging biosimilar entrants. Prioritize adjuvant therapy indication expansion to extend patent exclusivity beyond metastatic settings, leveraging existing prescriber relationships in United States NCI-designated cancer centers.
For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track offers accelerated commercialization timelines for novel combination mechanisms in checkpoint-refractory populations. Target Japan's Sakigake pathway for priority review compression, and pursue telemedicine-enabled oral therapy platforms to penetrate rural United States markets underserved by infusion center geography.
For Investors and Strategic Acquirers: Mid-cap biotechs with differentiated tyrosine kinase inhibitor assets and established European distribution represent prime acquisition targets for portfolio diversification. Long-term viability hinges on biomarker-driven patient stratification capabilities and companion diagnostic co-development partnerships. Watch for inflection when adjuvant immunotherapy trial readouts expand addressable populations beyond metastatic disease.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA conditional marketing authorization compresses European market entry timelines for combination regimens. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Singapore reduces single-source dependency for monoclonal antibody production. |
| Licensing Agreement | Companion diagnostic co-development partnerships synchronize PD-L1 assay launches with checkpoint inhibitor approvals. |
| Pipeline Diversification | Adjuvant therapy protocols in resected renal cell carcinoma open unpenetrated demand pools outside metastatic settings. |
| Clinical Trial Advancement | CAR-T manufacturing partnerships with Houston and Boston academic centers pilot solid tumor penetration strategies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov enrollment data, and Medicare Part D formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Across the analysis window, the forecasting framework modeled treatment line progression, dosage form preferences, administration route evolution, and regional regulatory cluster adoption patterns. CAGRs were derived through indication-specific patient share projections and pricing trajectory assumptions, with immuno-oncology nursing workforce expansion and biomarker testing penetration serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement density and IRA price negotiation stability would require recalibration. Forecasts reflect assumptions around clinical trial success rates and regulatory approval timelines. Revision becomes warranted when biomarker-driven stratification criteria or manufacturing capacity constraints cross thresholds that reorder prescriber hierarchies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Prescription Stimulants Market