
 China Agricultural Machinery Market | 2026-2036
China Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
China Agricultural Machinery Market Analysis
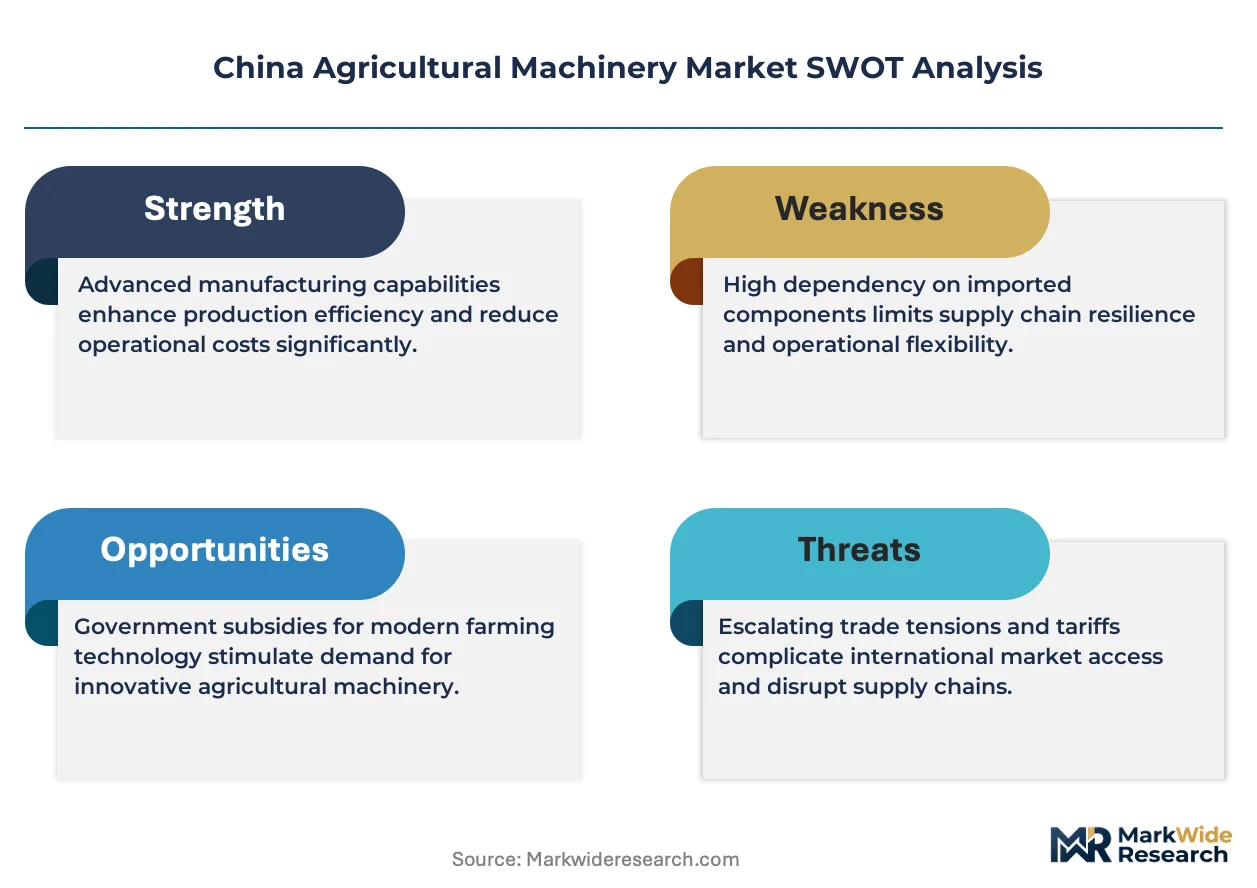
The China agricultural machinery sector is recalibrating around a widening gap between premium smart-equipment tiers and commodity hardware. YTO Group Corporation leverages its state-backed manufacturing scale to dominate conventional tractor volumes. Lovol Heavy Industry anchors its position through deep R&D investment in precision agriculture systems. Zoomlion Agriculture differentiates via integrated automation platforms that merge harvesting with real-time yield mapping.
Agricultural machinery encompasses powered and towed equipment engineered for soil preparation, planting, crop management, and post-harvest processing, with engine displacement ratings and tillage widths serving as core functional parameters. Tractors and harvesters occupy the largest installed base, though margin pools are shifting toward precision agriculture and IoT solutions as state subsidies tilt toward technology-intensive equipment. Electric machinery remains nascent but captures disproportionate policy attention under national decarbonization mandates.
MIIT equipment standards, MEE emissions regulations, and GB national safety codes collectively shape product certification timelines and factory gate compliance costs. NMPA-aligned testing protocols for autonomous systems are extending development cycles for smart machinery entrants. Stakeholders must monitor subsidy recalibration signals from the Ministry of Agriculture and Rural Affairs, as payment velocity and eligibility criteria determine effective demand elasticity across farmer and cooperative segments.
Market Dynamics
MIIT equipment standards and MEE emissions mandates are compressing certification timelines while state subsidy recalibration pulls demand toward technology-intensive equipment tiers, forcing manufacturers to accelerate R&D cycles or cede share to state-backed incumbents.
Growth Catalysts
- Dual carbon targets under MEE:National decarbonization mandates channel subsidy velocity toward electric drivetrain development in harvesters and autonomous tractors, creating procurement preference for low-emission equipment tiers.
- Large-scale cooperative expansion:Fleet consolidation in Heilongjiang Province generates concentrated demand for high-horsepower autonomous machinery with integrated yield-mapping capabilities.
- Precision agriculture protocols:NMPA-aligned testing frameworks for smart machinery establish regulatory clarity that accelerates commercial deployment of IoT-enabled equipment across the Northeast China grain belt.
Market Restraints
- GB national safety code compliance:Factory gate testing requirements extend product development cycles by 8-14 months for autonomous system entrants lacking established certification infrastructure.
- High-voltage battery supply concentration:Domestic cell manufacturing capacity clusters in eastern provinces, creating logistics friction for machinery OEMs serving remote Inner Mongolia cooperative buyers.
- Legacy hydraulic system lock-in:Existing installed bases of conventional tractors create switching cost barriers that slow electric platform adoption among smallholder segments outside subsidized cooperative channels.
Strategic Opportunities
- Jilin Province penetration gap:Mechanization rates trail Heilongjiang by 12-18 percentage points, creating whitespace for mid-tier autonomous equipment targeting medium-scale grain operations.
- Real-time yield mapping convergence:Integration of spectral imaging with harvester automation platforms enables outcome-based service contracting that shifts revenue models from hardware sales to per-hectare performance fees.
- Rural Affairs subsidy recalibration:Payment velocity acceleration for technology-intensive equipment creates working capital advantages for manufacturers with pre-certified smart machinery portfolios.
Industry Challenges
- Autonomous systems engineering scarcity:NMPA protocol expertise concentrates in Beijing and Shanghai R&D clusters, forcing manufacturers to absorb talent acquisition premiums or accept slower certification timelines.
- Legacy fleet integration complexity:Retrofit automation kits must interface with 15-20 year-old hydraulic architectures prevalent in Jilin and Inner Mongolia, multiplying field validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Agricultural Machinery Market |
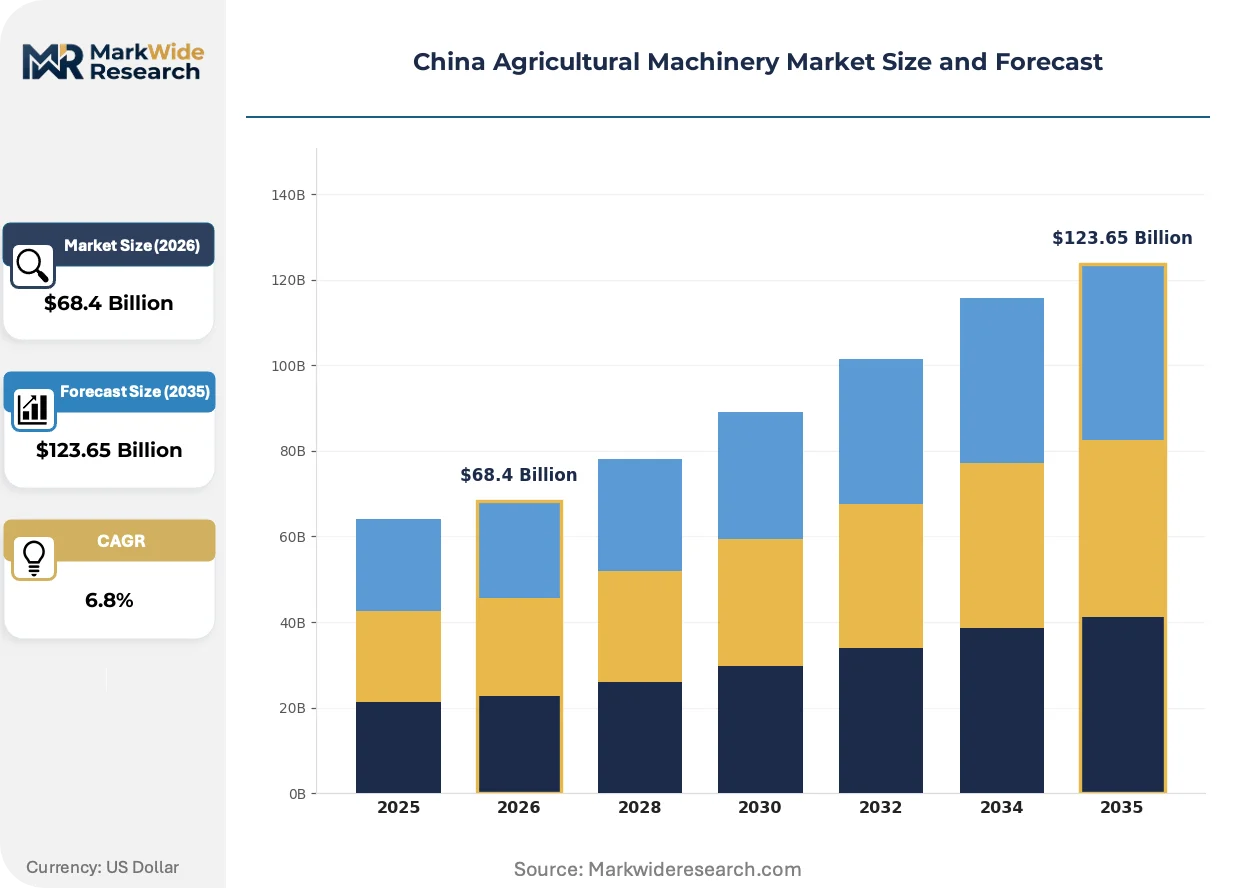
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
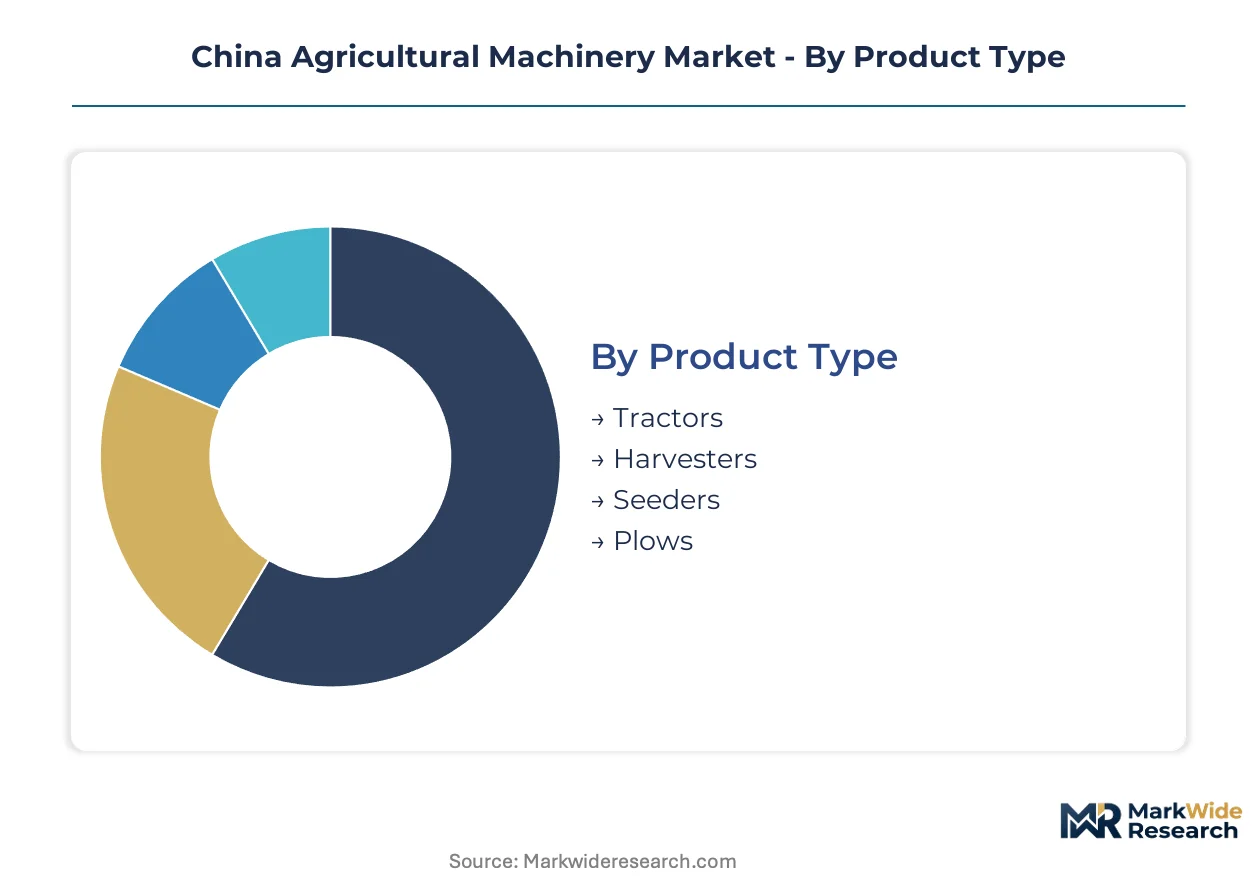
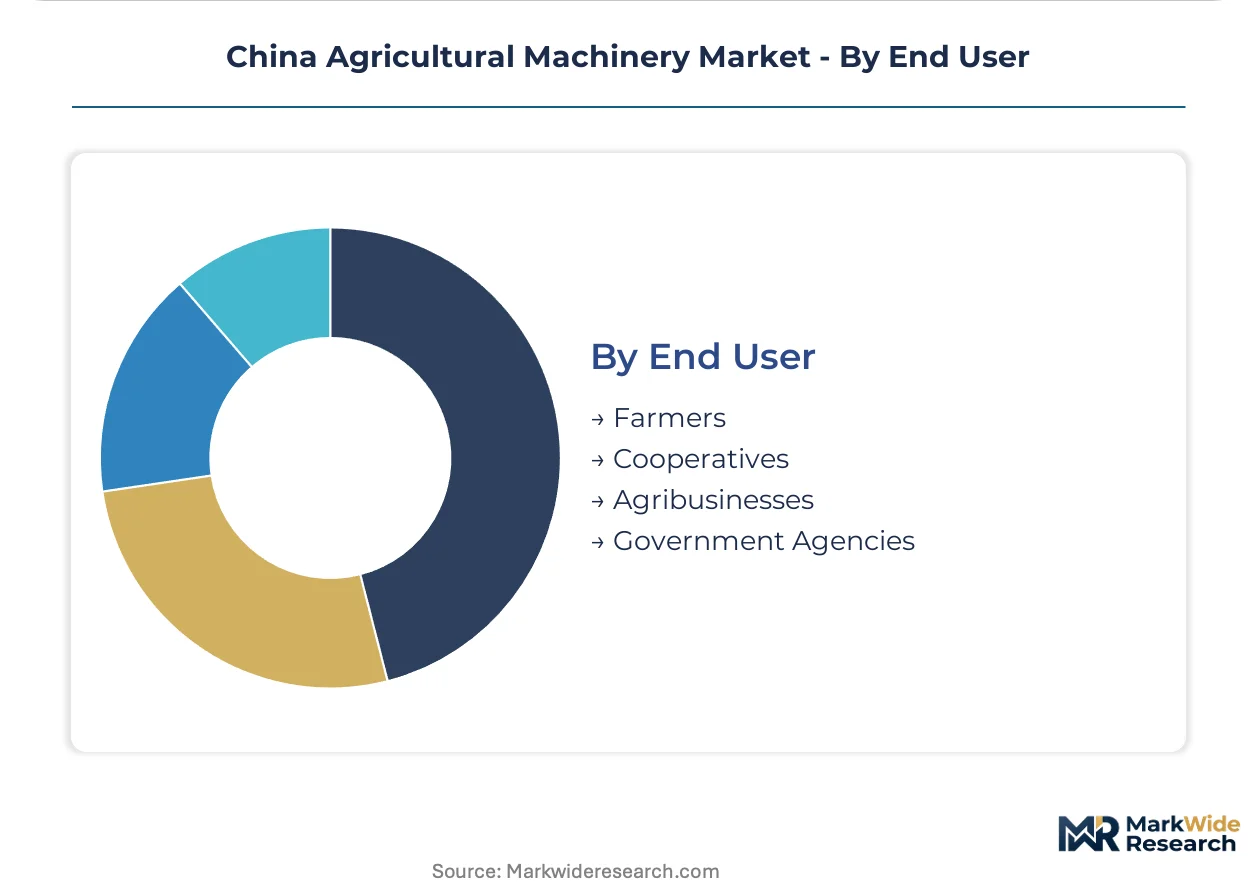
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Plows Application: Crop Farming, Livestock Farming, Aquaculture, Forestry Technology: Automation, Precision Agriculture, IoT Solutions, Electric Machinery End User: Farmers, Cooperatives, Agribusinesses, Government Agencies |
| Companies Covered | YTO Group Corporation, Lovol Heavy Industry, Zoomlion Agriculture, Weichai Lovol Intelligent Agricultural Technology, Wuzheng Agricultural Equipment, Shifeng Group, Shandong MINGSIN Machinery Group, Changfa Agricultural Equipment, Dongfeng Agricultural Machinery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Agricultural Machinery Market Emerging Trajectories
Automation platforms are compressing the traditional separation between soil preparation, planting, and harvest operations into continuous data-linked workflows that reshape how cooperatives evaluate equipment procurement.
Integrated automation architectures are unifying harvester mechanical systems with real-time yield mapping and variable-rate input application into single-platform solutions. Large-scale cooperatives in Heilongjiang are adopting these systems at replacement cycle compression rates of 30-40% versus conventional equipment. This convergence is collapsing the historical segmentation between machinery OEMs and precision agriculture software providers into consolidated platform competition.
MEE emissions regulations are tightening NOx and particulate thresholds for diesel engines above 75 horsepower, effective across all GB certification renewals. Engine suppliers face catalyst and after-treatment cost structures that erode margin pools on mid-tier tractor configurations. Northeast China grain belt OEMs are responding by accelerating electric drivetrain roadmaps to bypass compliance costs entirely.
Cooperative procurement committees are consolidating vendor relationships from fragmented multi-brand fleets toward single-source automation platforms with unified data architectures. Equipment distributors in Heilongjiang and Jilin are repositioning from transactional sales to subscription-based uptime guarantees. This behavioral shift is most pronounced among cooperatives exceeding 5,000 hectares under management, where operational data integration drives total cost of ownership calculations.
China Agricultural Machinery Market Segmentation
Equipment specification tiers in China agricultural machinery diverge sharply between state-subsidized technology-intensive platforms and cost-optimized conventional hardware. Procurement committees at Heilongjiang cooperatives now weight data integration capabilities equally with horsepower ratings when evaluating fleet investments.
Product Type:
Standardization dominates at the commodity tier while premium segments demand extensive customization for soil conditions and crop rotations across the Northeast China grain belt.
- Tractors:Engine displacement ratings from 25 to 300+ horsepower define functional segmentation, with autonomous variants commanding procurement preference from cooperatives exceeding 5,000 hectares under management. Heilongjiang Province drives concentrated demand for high-horsepower autonomous units with integrated navigation systems.
- Harvesters:Combine platforms integrate real-time yield mapping through spectral imaging arrays, enabling outcome-based service contracting that shifts revenue models from unit sales to per-hectare performance fees. Electric drivetrain variants capture disproportionate policy attention under MEE dual carbon mandates.
- Seeders:Precision planting equipment with variable-rate input application.
- Plows:Conventional tillage implements facing displacement from conservation agriculture protocols.
Leading the category by volume: Tractors. Growing fastest: Harvesters.
Application:
Revenue concentration tracks grain belt mechanization intensity, with margin pools shifting toward precision-managed operations.
- Crop Farming:Dominant application spanning soil preparation through post-harvest processing, with automation platforms compressing traditional operational separations into continuous data-linked workflows. Heilongjiang and Jilin Provinces anchor equipment deployment for corn, soybean, and rice production systems.
- Livestock Farming:Mechanized feed handling and waste management systems.
- Aquaculture:Specialized equipment for pond and cage-based production systems.
- Forestry:Harvesting and processing machinery for plantation management.
Volume concentration: Crop Farming. Margin expansion: Crop Farming.
Technology:
Certification velocity separates commercialized tiers from development-stage categories.
- Automation:NMPA-aligned testing protocols establish regulatory clarity for autonomous navigation and control systems, though GB national safety code compliance extends product development cycles by 8-14 months for entrants lacking established certification infrastructure. Heilongjiang cooperatives are adopting these systems at replacement cycle compression rates of 30-40% versus conventional equipment.
- Precision Agriculture:Variable-rate input application and spectral imaging platforms.
- IoT Solutions:Connected equipment architectures enabling fleet-wide data integration.
- Electric Machinery:Battery-electric drivetrains for harvesters and tractors, nascent but capturing disproportionate subsidy velocity under MEE emissions mandates targeting NOx and particulate thresholds.
Fastest certification velocity: Automation. Steepest policy support trajectory: Electric Machinery.
End User:
Procurement scale and subsidy eligibility create distinct service requirements.
- Cooperatives:Fleet consolidation in Heilongjiang Province generates concentrated demand for high-horsepower autonomous machinery with unified data architectures, with procurement committees consolidating vendor relationships from fragmented multi-brand fleets toward single-source automation platforms. Distributors are repositioning from transactional sales to subscription-based uptime guarantees for this segment.
- Farmers:Smallholder segments face switching cost barriers from legacy hydraulic system lock-in outside subsidized cooperative channels.
- Agribusinesses:Corporate farming operations with integrated supply chain requirements.
- Government Agencies:Demonstration and subsidy administration procurement.
Primary volume driver: Cooperatives. Fastest policy response: Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harbin anchors mechanization intensity across the Northeast China grain belt, with provincial equipment deployment rates setting national benchmarks for autonomous fleet adoption.
Heilongjiang Province
Large-scale cooperatives exceeding 5,000 hectares drive concentrated demand for high-horsepower autonomous tractors with integrated navigation systems. MEE dual carbon mandates channel subsidy velocity toward electric drivetrain variants in harvesters. Harbin and surrounding industrial corridors host the densest clustering of smart machinery validation facilities.
Jilin Province
Mechanization rates trail Heilongjiang by 12-18 percentage points, creating whitespace for mid-tier autonomous equipment targeting medium-scale grain operations. Ministry of Agriculture and Rural Affairs subsidy recalibration accelerates payment velocity for technology-intensive tiers. Changchun-based manufacturing clusters are expanding precision agriculture component capacity.
Inner Mongolia
Remote cooperative buyers face logistics friction from eastern battery cell manufacturing concentration. GB national safety code compliance extends development cycles for autonomous system entrants lacking established certification infrastructure. Hohhot and Baotou industrial zones are developing localized electric drivetrain assembly capacity.
Shandong Province
Commodity-tier tractor manufacturing concentrates in Weifang and Yantai machinery corridors. MIIT equipment standards compress certification timelines while state subsidy programs pull demand toward technology-intensive tiers. Jinan hosts emerging R&D clusters for IoT-enabled fleet management platforms.
Henan Province
Legacy hydraulic system lock-in creates switching cost barriers for smallholder segments outside subsidized cooperative channels. Zhengzhou machinery districts specialize in conventional tillage implements facing displacement from conservation agriculture protocols. Luoyang industrial parks are retrofitting automation kit production lines for aging installed bases.
China Agricultural Machinery Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification velocity and subsidy eligibility tiers. State-backed manufacturing scale dominates conventional tractor volumes while precision agriculture specialists capture disproportionate policy attention. Two strategic archetypes prevail: integrated automation platform providers and component-scale commodity fabricators. Competitive moves concentrate on strategic partnerships for NMPA-aligned testing access and geographic expansion into underpenetrated provincial markets.
Among state-backed manufacturing groups, YTO Group Corporation and Lovol Heavy Industry occupy positions across both premium and commodity tiers. Zoomlion Agriculture exemplifies the integrated automation platform archetype. These three anchors represent divergent responses to MIIT standards compression and MEE emissions mandates reshaping factory gate economics.
| Leading Market Players |
|---|
| YTO Group Corporation |
| Lovol Heavy Industry |
| Zoomlion Agriculture |
| Weichai Lovol Intelligent Agricultural Technology |
| Wuzheng Agricultural Equipment |
| Shifeng Group |
| Shandong MINGSIN Machinery Group |
| Changfa Agricultural Equipment |
| Dongfeng Agricultural Machinery |
| Others |
Supply Flow & Price Mechanics
State-backed manufacturing conglomerates anchor supply capacity across the Northeast China grain belt, channeling subsidy velocity toward technology-intensive equipment tiers while compressing margin pools on commodity hardware through scale-driven cost discipline. MIIT equipment standards and MEE emissions mandates reshape factory gate economics, forcing pricing stratification across premium automation platforms, mid-tier compliant configurations, and legacy hydraulic systems.
Pricing Analysis
Per-hectare performance fees tied to real-time yield outcomes anchor value-based contracting for integrated automation platforms in Heilongjiang cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-certified autonomous systems from GB-compliant conventional units and non-subsidized legacy equipment. Cost compression in mid-tier diesel configurations intensifies because MEE catalyst requirements erode supplier margins. Smallholder segments in Henan exhibit highest price sensitivity, while Heilongjiang cooperatives exceeding 5,000 hectares prioritize uptime guarantees over unit economics.
Supply Chain Analysis
High-voltage battery cell manufacturing concentrates in Jiangsu, Zhejiang, and Fujian provinces, creating logistics friction for machinery OEMs serving remote Inner Mongolia cooperative buyers. Lithium iron phosphate cathodes, silicon carbide power modules, and precision hydraulic valves constitute critical input dependencies. Single-source vulnerability in NMPA protocol expertise clusters around Beijing and Shanghai R&D corridors. Distribution runs through provincial machinery bureaus and state-owned agricultural supply cooperatives with embedded subsidy administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT standards compression and MEE emissions mandates are forcing consolidation, eliminating sub-scale fabricators unable to absorb certification infrastructure investments or pre-fund electric drivetrain development cycles.
For Market Incumbents: Lock in NMPA-aligned testing partnerships to compress smart machinery certification timelines, while securing captive supply of high-voltage battery cells through backward integration into eastern province manufacturing corridors. Autonomous systems engineering scarcity in Beijing and Shanghai clusters threatens to extend rival development cycles by 8-14 months. For New Entrants and Emerging Players: Capture Jilin Province mechanization whitespace where rates trail Heilongjiang by 12-18 percentage points, positioning mid-tier autonomous equipment for medium-scale grain operations. Ministry of Agriculture and Rural Affairs subsidy recalibration accelerates payment velocity for technology-intensive tiers, enabling working capital advantages against legacy hydraulic incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision agriculture software specialists with NMPA protocol pre-certification in Shandong and Jilin manufacturing corridors. Long-term viability hinges on consolidation into integrated automation platforms rather than component-scale commodity fabrication. Watch MEE dual carbon mandate enforcement intensity as inflection indicator for electric drivetrain subsidy velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Certification Pre-Investment | Compresses product development cycles by establishing regulatory clarity before rival entrants. |
| Electric Drivetrain Roadmap Acceleration | Bypasses MEE emissions compliance costs entirely while capturing disproportionate subsidy velocity. |
| Jilin Province Distribution Partnership | Secures first-mover position in mechanization whitespace trailing Heilongjiang benchmarks. |
| Subscription-Based Uptime Guarantees | Aligns revenue models with cooperative procurement shift away from transactional hardware sales. |
| Real-Time Yield Mapping Integration | Enables outcome-based service contracting that shifts margin pools from unit sales to performance fees. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across machinery OEM procurement directors, cooperative fleet managers, MEE compliance officers, and precision agriculture R&D leads. China Association of Agricultural Machinery Manufacturers production statistics, MIIT equipment certification databases, and Ministry of Agriculture subsidy disbursement records supplied volume and value benchmarks. Bottom-up equipment deployment tallies triangulated against top-down provincial mechanization rate surveys.
Data-stream reconciliation across shipment records, subsidy eligibility registries, and cooperative procurement committee disclosures shaped analytical framework segmentation by product type, technology tier, and end-user scale throughout the forecast period. CAGRs derived from equipment replacement cycle compression rates and subsidy velocity trajectories modeled across the analysis window. NMPA protocol adoption curves and MEE emissions compliance cost structures served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE mandate enforcement intensity and Ministry of Agriculture subsidy recalibration timing. Assumptions reflect current regulatory trajectory, with revisions contingent on NMPA testing protocol expansion or dual carbon target acceleration. A small set of named triggers—MEE emissions threshold tightening, cooperative consolidation pace, and battery cell logistics cost shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Utility Tractor Market