
 Metallurgical Microscope Market | 2026-2036
Metallurgical Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Metallurgical Microscope Market Analytics
The gap between premium research-grade systems and commodity inspection units is expanding as semiconductor fabs demand sub-nanometer resolution while foundries prioritize throughput. Olympus Corporation leverages its optical heritage to dominate high-end inverted platforms for wafer analysis. Zeiss sustains leadership in laser-scanning confocal extensions for 3D surface mapping. Keyence competes aggressively on automated digital workflows that reduce operator dependency in high-volume manufacturing environments.
A metallurgical microscope employs reflected-light optical paths, polarizing filters, and objectives with long working distances to examine opaque metal surfaces, grain structures, and phase distributions without destructive sample preparation. Digital microscope configurations now lead revenue growth as CMOS sensors and computational sharpening replace eyepiece-dependent workflows across materials testing laboratories. Inverted microscopes anchor margins in semiconductor quality control where wafer-stage geometry dictates instrument architecture, while upright systems occupy educational and routine inspection tiers with lower replacement frequency. Testing laboratories represent the fastest-growing end user category as third-party certification expands under ISO 17025 accreditation requirements.
The FDA enforces Good Manufacturing Practice standards that cascade into metallurgical verification protocols for medical device alloys, while ISO 17025 and ISO 9001 shape laboratory equipment procurement specifications across manufacturing sectors. REACH and RoHS in Europe restrict hazardous substances in optical coatings and electronic subassemblies, forcing redesign cycles among component suppliers. Stakeholders must monitor how NMPA's evolving metrology mandates in China and EPA material disclosure rules in the United States reshape supply chain qualification timelines for instrument OEMs.
Market Dynamics
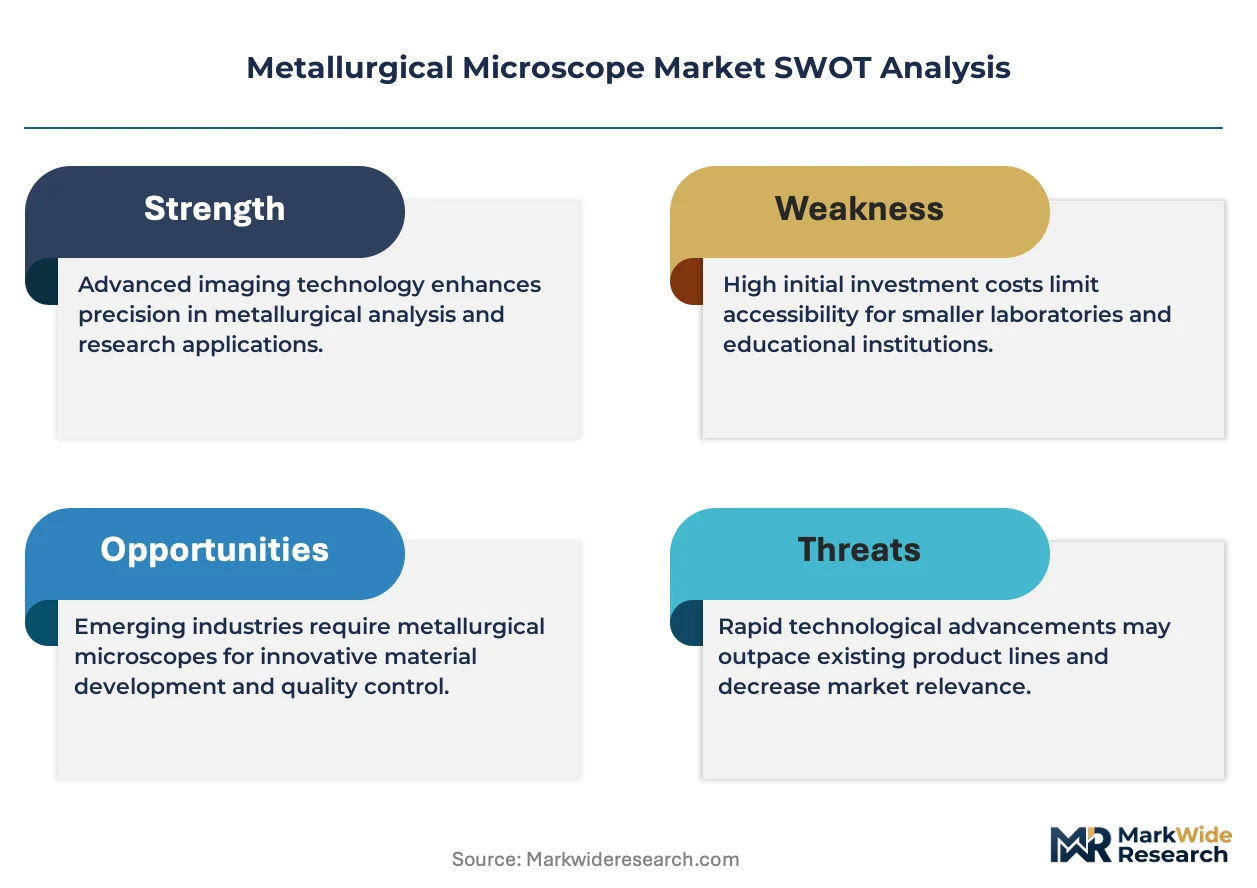
Semiconductor fabs in Taiwan and South Korea are compressing inspection cycle times while demanding sub-nanometer resolution, forcing microscope OEMs to unify computational imaging with automated wafer-handling architectures.
Growth Catalysts
- Wafer-stage automation:Semiconductor manufacturers in Taiwan and South Korea require inverted platforms with motorized stages for high-throughput defect detection.
- ISO 17025 accreditation:Third-party testing laboratories across Germany and the United States are expanding metallurgical verification capacity under quality certification mandates.
- Dual carbon goals:China's MEE and MIIT are tightening material characterization standards for lightweight alloys in electric vehicle powertrains.
Market Restraints
- Optical glass supply concentration:German and Japanese specialty glass suppliers control high-dispersion objective lens substrates, creating single-source vulnerability.
- CMOS sensor cost volatility:Large-format scientific-grade sensors face pricing pressure from competing demand in medical imaging and autonomous vehicles.
- REACH compliance friction:ECHA restrictions on lead-containing optical coatings force redesign cycles that extend qualification timelines by 12-18 months.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives are attracting semiconductor packaging operations that require incoming materials inspection.
- Additive manufacturing qualification:Powder bed fusion and directed energy deposition processes need grain-structure validation for aerospace and medical implant certifications.
- AI-assisted image analysis:Machine learning segmentation algorithms are unifying with digital microscope platforms to reduce operator training requirements in high-volume environments.
Industry Challenges
- Metallography technician scarcity:Specialized skills in sample preparation and phase interpretation are concentrating in aging workforces across Japanese and German industrial regions.
- Multi-site calibration synchronization:Corporate quality departments struggle to maintain measurement traceability across distributed manufacturing facilities under ISO 9001 audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallurgical Microscope Market |
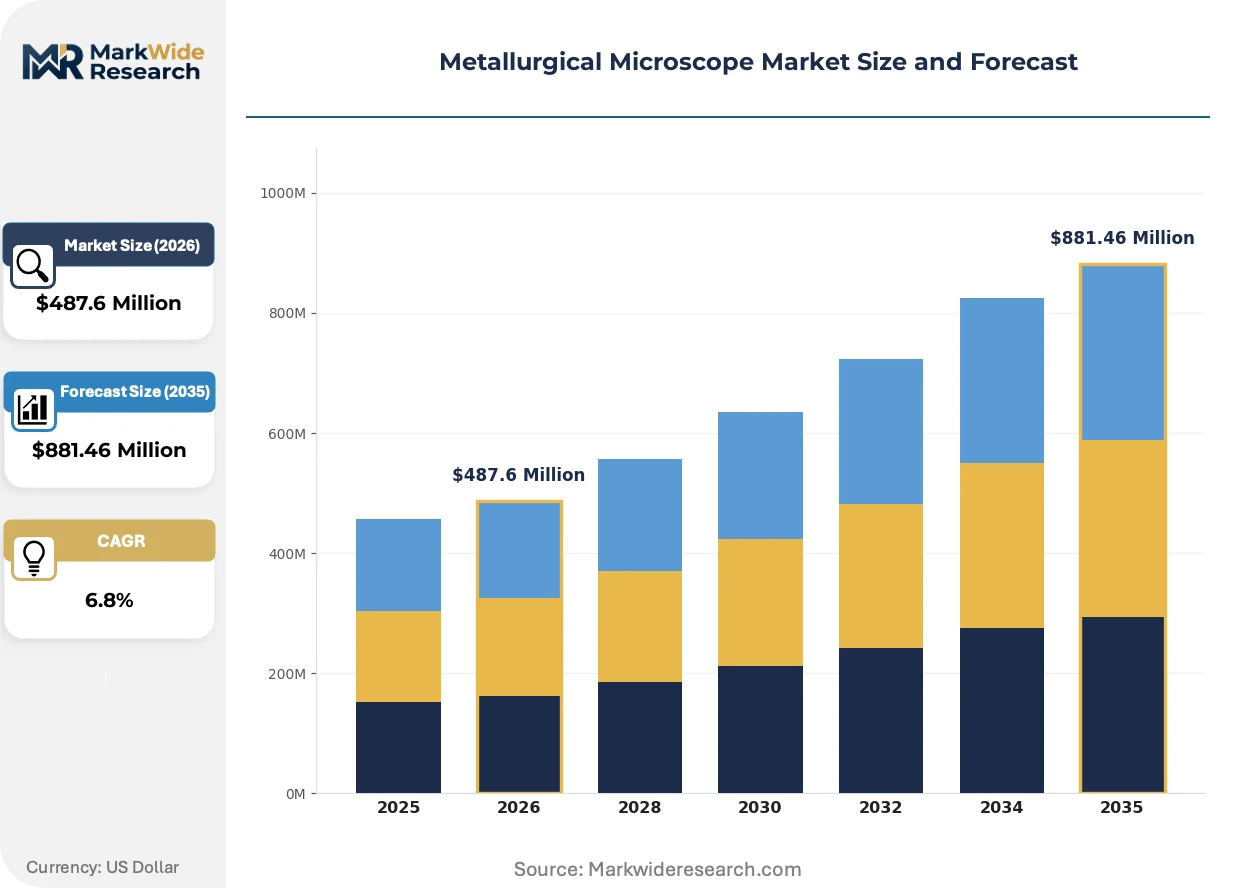
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stereo Microscope, Inverted Microscope, Digital Microscope, Upright Microscope Application: Materials Testing, Quality Control, Research and Development, Educational Purposes End User: Manufacturers, Research Institutions, Educational Institutions, Testing Laboratories Technology: Optical Technology, Digital Imaging, Laser Technology, Automated Microscopy |
| Companies Covered | Olympus Corporation, Meiji Techno, Leica Microsystems, UNITRON, Evident Scientific, Zeiss, Keyence, Thermo Fisher Scientific, Nikon Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallurgical Microscope Market Evolving Landscape
Computational microscopy and automated sample handling are compressing the boundary between research-grade instrumentation and production-floor inspection systems.
Deep-learning deconvolution is unifying with high-speed CMOS acquisition to restore optical sectioning without mechanical Z-stacking. Semiconductor fabs in Taiwan are deploying these configurations for real-time wafer grain analysis. The technology is compressing capital expenditure thresholds for sub-micron resolution in foundry environments.
REACH and RoHS amendments are restricting halogenated flame retardants in microscope electronic subassemblies. European OEMs are redesigning power supply and illumination modules to maintain CE marking compliance. Medical device manufacturers in Germany face the most acute compliance pressure due to FDA-equivalent quality system requirements.
Third-party certification laboratories are unbundling after-sales service contracts from hardware procurement. Testing facilities in the United States now prioritize instrument vendors with remote diagnostic capabilities and regional spare parts depots. This preference shift is most visible among ISO 17025-accredited materials laboratories serving automotive supplier networks.
Metallurgical Microscope Market Segmentation
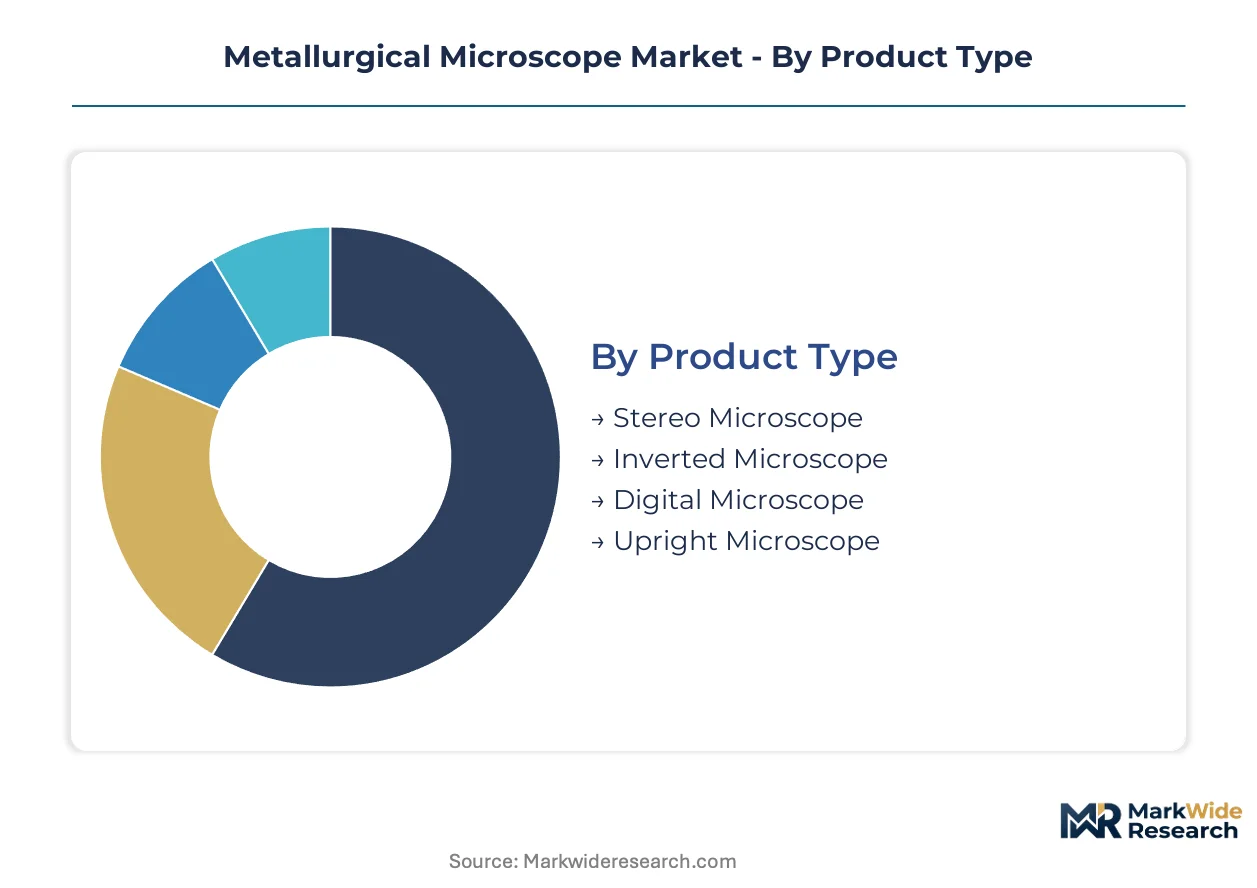
Metallurgical microscope procurement splits across four distinct category hierarchies. Product architecture determines capital expenditure tiers, while end-user accreditation requirements reshape vendor qualification protocols.
Product Type:
Resolution specifications and sample geometry dictate buyer selection between inverted platforms for wafer inspection and upright systems for routine laboratory work.
- Inverted Microscope:Configured with motorized wafer stages and long-working-distance objectives for non-destructive semiconductor substrate analysis. Taiwan and South Korea fabs dominate procurement volumes as sub-nanometer resolution requirements compress inspection cycle times.
- Digital Microscope:Integrates CMOS sensors with computational sharpening algorithms to eliminate eyepiece-dependent workflows. Testing laboratories across Germany and the United States are expanding deployments under ISO 17025 accreditation mandates for automated documentation.
- Stereo Microscope:Lower-magnification binocular systems serve preliminary sample screening and educational demonstrations.
- Upright Microscope:Conventional reflected-light configurations occupy routine inspection tiers with extended replacement cycles.
Volume sits with Inverted Microscope; growth tilts toward Digital Microscope.
Application:
End-use intensity varies by regulatory exposure and certification renewal frequency.
- Quality Control:Incoming materials verification and in-process grain-structure monitoring for automotive supplier networks. German Tier 1 suppliers and Taiwanese semiconductor packaging operations maintain the densest installed bases under IATF 16949 and equivalent quality system requirements.
- Research and Development:Phase distribution analysis and alloy development for aerospace and medical implant applications. REACH compliance friction extends qualification timelines for new coating formulations in European R&D facilities.
- Materials Testing:Destructive and non-destructive characterization for third-party certification bodies.
- Educational Purposes:Undergraduate metallography instruction with limited budget allocation for replacement equipment.
Deployment density clusters in Quality Control; steepest expansion trajectory belongs to Research and Development.
End User:
Procurement authority and budget scale differentiate institutional buyers from commercial operators.
- Testing Laboratories:Third-party certification facilities expanding metallurgical verification capacity under ISO 17025 mandates. United States automotive supplier networks and German industrial clusters are unbundling service contracts from hardware procurement to prioritize remote diagnostic capabilities.
- Manufacturers:In-house quality departments at semiconductor fabs and automotive foundries. Taiwan and South Korea facilities compress capital expenditure thresholds through high-throughput automated configurations.
- Research Institutions:University and national laboratory materials science departments with grant-dependent acquisition cycles.
- Educational Institutions:Technical colleges and undergraduate programs with extended replacement horizons.
Installed base concentrates with Manufacturers; Testing Laboratories gain share fastest.
Technology:
Imaging modality selection determines operator training requirements and data output formats.
- Digital Imaging:CMOS-based acquisition with machine learning segmentation for automated defect classification. Semiconductor fabs in Taiwan deploy these configurations to reduce metallography technician dependency amid workforce scarcity.
- Automated Microscopy:Motorized stage control and software-driven measurement routines for high-volume production environments. South Korean memory manufacturers prioritize these systems for wafer-map correlation with yield management databases.
- Optical Technology:Conventional reflected-light paths with polarizing filters for manual grain-structure interpretation.
- Laser Technology:Confocal and interferometric extensions for 3D surface mapping in precision component verification.
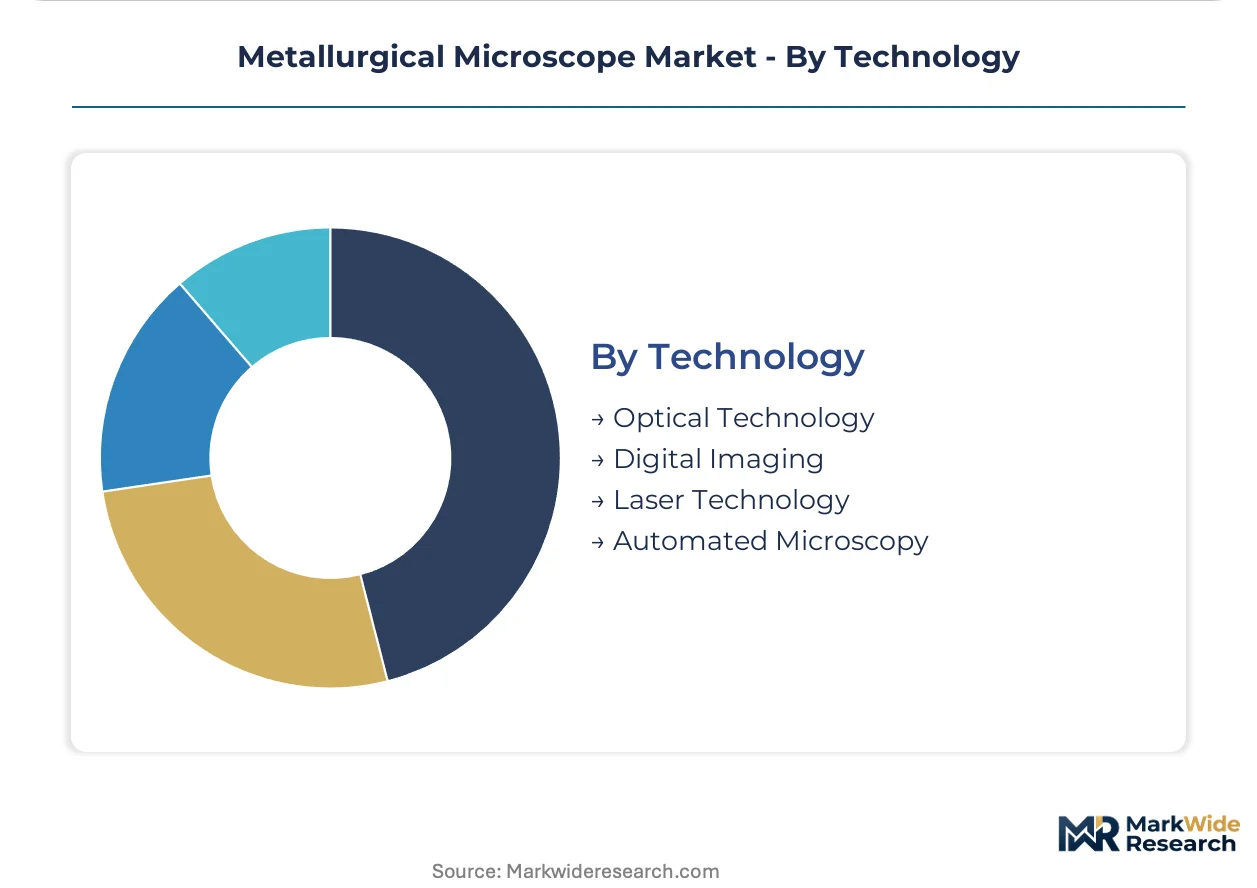
Revenue concentration favors Optical Technology; Automated Microscopy climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan commands the densest concentration of inverted metallurgical microscope deployments, with semiconductor fabs compressing inspection cycle times for sub-nanometer wafer analysis. Procurement patterns across four additional national markets reveal how regional industrial specialization reshapes instrument specifications and vendor qualification protocols.
Taiwan
TSMC and United Microelectronics Corporation fabs in Hsinchu and Tainan drive demand for motorized wafer-stage systems with automated defect classification. The National Science and Technology Council enforces metrology standards for advanced node production. Southern Taiwan Science Park packaging operations now require incoming materials inspection for heterogeneous integration substrates.
United States
Intel's Arizona and Ohio fabrication facilities plus Qualcomm's San Diego R&D centers anchor North American procurement of laser-scanning confocal extensions. FDA Good Manufacturing Practice standards cascade into metallurgical verification protocols for medical device alloys. Boston-area medical device manufacturers face acute compliance pressure for titanium implant characterization.
Germany
Bosch, Continental, and ZF Friedrichshafen Tier 1 suppliers maintain dense installed bases for automotive powertrain materials testing. ECHA REACH restrictions on lead-containing optical coatings force 12-18 month redesign cycles among component suppliers. Bavarian automotive supplier networks unbundle service contracts to prioritize remote diagnostic capabilities.
South Korea
Samsung Electronics and SK Hynix memory fabs in Gyeonggi Province compress capital expenditure thresholds through high-throughput automated configurations. MFDS medical device regulations align with FDA-equivalent quality system requirements for implant materials. Seoul Capital Area testing laboratories expand ISO 17025-accredited verification capacity for export certification.
China
SMIC and Hua Hong Semiconductor fabs in Shanghai and Wuxi expand procurement despite export control friction on sub-14nm equipment. NMPA and MIIT tightening of metrology standards for advanced materials characterization extends qualification timelines. Yangtze River Delta electronics manufacturing clusters concentrate demand for digital workflow systems.
Metallurgical Microscope Market Competitive Landscape
Premium-margin players sit above commodity-margin players across resolution specification and automation integration tiers. The vendor base stratifies into three distinct tiers: optical heritage specialists commanding research-grade pricing, industrial automation integrators capturing volume manufacturing accounts, and regional assemblers serving educational and routine inspection segments. Strategic moves concentrate on computational imaging partnerships and automated sample-handling acquisitions that compress the boundary between laboratory and production-floor configurations.
Within the optical heritage tier, Olympus Corporation and Zeiss exemplify premium positioning through long-working-distance objective portfolios and confocal extension architectures. Keyence occupies a distinct automation-centric position, representing the industrial workflow integration archetype that reduces operator dependency in high-volume environments. These three anchors illustrate how vendor specialization across resolution performance, automation depth, and software integration reshapes competitive boundaries without overlapping positioning.
| Leading Market Players |
|---|
| Olympus Corporation |
| Meiji Techno |
| Leica Microsystems |
| UNITRON |
| Evident Scientific |
| Zeiss |
| Keyence |
| Thermo Fisher Scientific |
| Nikon Instruments |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap optical specialists in Germany and Japan anchor supply discipline through captive objective lens production, translating substrate scarcity into premium pricing power for long-working-distance configurations while fabless digital microscope assemblers absorb CMOS cost volatility in downstream tiers.
Pricing Analysis
Value-based pricing anchored to wafer throughput and defect detection yield dominates semiconductor fab procurement in Taiwan and South Korea. Three-tier pricing structure across research-grade confocal systems, mid-tier automated platforms, and educational upright configurations separates Olympus and Zeiss premiums from Keyence workflow bundles and regional assembler economy tiers. Cost compression in digital microscope tiers is intensifying because CMOS sensor demand from medical imaging and autonomous vehicles constrains large-format scientific supply. Educational institutions exhibit the highest price sensitivity due to grant-dependent acquisition cycles, while semiconductor manufacturers prioritize total cost of ownership metrics over unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fab demand in Hsinchu and Gyeonggi Province, while distributor networks serve testing laboratories and educational buyers across Germany and the United States. High-dispersion optical glass draws from German and Japanese specialty suppliers, with CMOS sensors sourcing from South Korean and Taiwanese semiconductor foundries. Single-source vulnerability in lead-free optical coating substrates under ECHA REACH restrictions extends component qualification timelines. Distribution runs through authorized service partners with regional spare parts depots for ISO 17025-accredited facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a vertical-integration race where objective lens fabrication capabilities and automated stage control software represent the decisive upstream and downstream levers players are pursuing to escape commodity pricing traps.
For Market Incumbents: Deepen backward integration into high-dispersion glass melting and proprietary coating formulations to defend margin position against fabless digital entrants exploiting CMOS commoditization. Secure long-term supply agreements with Taiwan and South Korea semiconductor fabs before China's NMPA metrology mandates accelerate local procurement preferences. Prioritize software-defined automation architectures that reduce operator dependency amid metallography technician scarcity. For New Entrants and Emerging Players: Testing laboratory service providers in the United States and Germany represent the most penetrable channel partner type for digital workflow platforms with remote diagnostic capabilities. Target ISO 17025-accredited facilities unbundling hardware from service contracts as the white-space entry point. Pursue additive manufacturing qualification partnerships with aerospace and medical implant certifiers to bypass entrenched semiconductor fab incumbency. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed Japanese optical component specialists with JIS-certified objective portfolios and dormant semiconductor customer relationships. Long-term viability hinges on computational imaging patent estates and AI-assisted segmentation software assets. Watch for China's MIIT export control retaliation patterns as the inflection signal for regional supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Glass | Captive supply of high-dispersion substrates insulates margins from ECHA REACH coating restrictions. |
| AI-Assisted Image Analysis Platform | Machine learning segmentation reduces Taiwan fab operator training requirements amid workforce aging. |
| Remote Diagnostic Service Capability | ISO 17025 laboratories in Germany and the United States now prioritize vendors with regional spare parts depots. |
| Additive Manufacturing Qualification Partnership | Powder bed fusion certification needs create entry wedge beyond entrenched semiconductor quality control. |
| Automated Wafer-Stage Architecture | Motorized stage control with yield database correlation addresses South Korean memory manufacturer throughput demands. |
Research Methodology
Document review covered SEC 10-K filings from instrument OEMs, ECHA REACH substance restriction updates, and Taiwan NSTC metrology standards, complemented by interviews with semiconductor fab quality directors, testing laboratory ISO 17025 accreditation managers, and automotive Tier 1 supplier procurement leads. Secondary validation drew from customs trade data for optical component flows, patent filings in computational microscopy, and hospital procurement databases for medical device alloy verification requirements. Bottom-up demand modeling across end-user categories triangulated against top-down market sizing from vendor revenue disclosures.
Segmentation outputs across product architecture, application intensity, end-user procurement authority, and imaging modality technology informed the analytical framework across the projection horizon. CAGRs derived from wafer fab capital expenditure trajectories, third-party laboratory accreditation expansion rates, and additive manufacturing certification timelines. Industry-specific forecast inputs incorporated NMPA metrology mandate implementation pacing and MFDS medical device regulation alignment with FDA-equivalent quality systems.
Caveats apply where export control friction on sub-14nm equipment, ECHA coating restriction redesign cycles, or metallography technician workforce contraction could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Electrochemistry Meters Market