
 Atomic Magnetometers Market | 2026-2036
Atomic Magnetometers Market Size, Share, and Industry Trends Forecast 2026-2036
Atomic Magnetometers Market Outlook
The EU Green Deal is hardening sustainability benchmarks for precision instrumentation supply chains, pushing OEMs toward low-power quantum sensor architectures. Honeywell International Inc. leverages its aerospace heritage to anchor defense-grade atomic magnetometer production in controlled facilities. Bartington Instruments Ltd competes through specialized vector magnetometer designs for geophysical survey contractors. QuSpin Inc. differentiates via chip-scale integration that reduces helium-3 consumption in portable deployments.
Atomic magnetometers are quantum sensors that measure magnetic field strength through spin-polarized alkali atoms, achieving sensitivity thresholds below one femtotesla for applications requiring detection of extremely weak biomagnetic or geophysical signals. Their primary purpose spans medical neuromaging, unexploded ordnance detection, and fundamental physics research where conventional superconducting quantum interference devices prove impractical. Optical magnetometers lead current revenue generation due to mature laser-pumped architectures and established calibration protocols. Cold atom technology represents the fastest-expanding segment as national laboratories and defense agencies fund next-generation gradiometers. Medical imaging applications concentrate margin pools where FDA 510(k) clearance barriers limit vendor entry and sustain premium pricing.
The FDA regulates clinical magnetometer systems through device classification pathways that mandate electromagnetic compatibility and patient safety validation. The EPA oversees hazardous material handling in alkali metal vapor cell manufacturing, while ISO 17025 accreditation requirements shape metrology service provider eligibility for government contracts. Stakeholders must monitor how quantum technology export control harmonization between the Wassenaar Arrangement and emerging national frameworks reshapes cross-border component sourcing and joint venture structures.
Market Dynamics
Defense procurement pipelines are compressing development cycles for chip-scale atomic magnetometers as dual-use quantum sensing applications expand from submarine navigation into medical neuromaging and geophysical exploration.
Growth Catalysts
- NIH Brain-Mapping Consortia:Federal neuroscience funding in the United States sustains demand for femtotesla-sensitivity magnetometers in non-invasive neural signal detection.
- EU Green Deal:Sustainability mandates are channeling public R&D toward low-power quantum sensor architectures that reduce helium-3 consumption in portable deployments.
- Submarine Detection:Naval defense agencies are expanding adoption of cold atom gradiometer systems for undersea magnetic anomaly detection and navigation.
Market Restraints
- Alkali Metal Supply Concentration:Vapor cell manufacturing depends on cesium and rubidium sourcing from concentrated geopolitical suppliers, creating input cost volatility.
- FDA 510(k) Barriers:Clinical magnetometer clearance pathways mandate electromagnetic compatibility validation that extends commercialization timelines for medical device entrants.
- SQUID Substitution:Superconducting quantum interference devices retain installed-base advantages in hospital settings where cryogenic infrastructure already exists.
Strategic Opportunities
- Unexploded Ordnance Detection:Demining agencies in Southeast Asia represent underpenetrated demand for portable vector magnetometer surveys.
- Quantum-Photonics Convergence:Integration of chip-scale lasers with atomic vapor cells is enabling handheld magnetometer form factors for field geophysics contractors.
- German Quantum Initiatives:Federal funding programs are creating procurement incentives for miniaturized sensor platforms in precision navigation applications.
Industry Challenges
- Atomic Physics Talent Scarcity:Laser cooling and spin-exchange optical pumping expertise resides in national laboratories, limiting commercial workforce availability.
- ISO 17025 Accreditation Timelines:Metrology service providers face extended validation periods for government contract eligibility in calibration services.
- Legacy System Integration:Defense platforms require magnetometer retrofit compatibility with existing magnetic signature management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atomic Magnetometers Market |
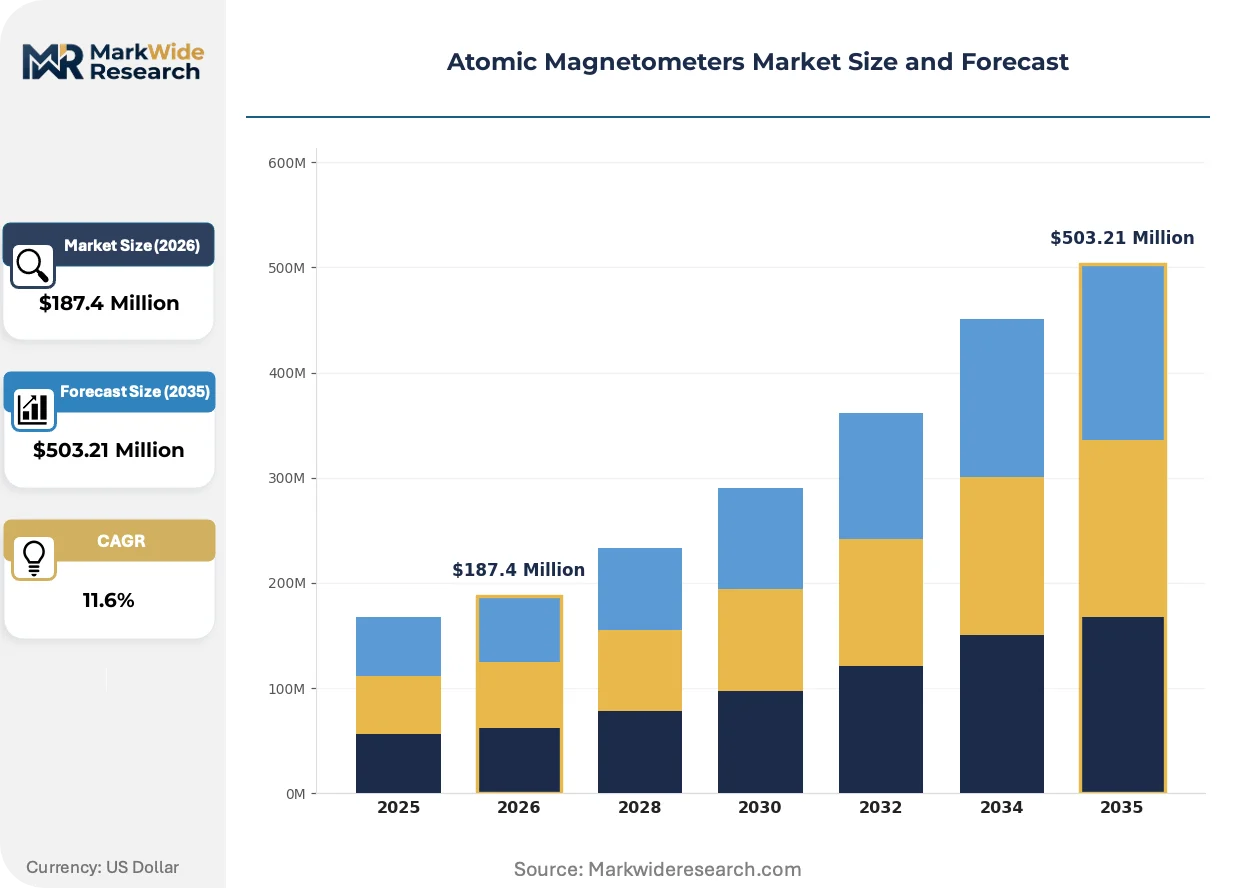
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip-Based Magnetometers, Scalar Magnetometers, Vector Magnetometers, Optical Magnetometers Application: Geophysical Surveys, Medical Imaging, Industrial Monitoring, Research & Development End User: Healthcare, Defense, Aerospace, Academia Technology: Laser-Pumped Technology, RF Excitation Technology, Cold Atom Technology, Magneto-Optical Technology |
| Companies Covered | Honeywell International Inc., Bartington Instruments Ltd, GEM Systems, Geometrics, Inc., QuSpin Inc., Twinleaf LLC, AOSense Inc., Lockheed Martin Corporation, Quantum Design Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atomic Magnetometers Market Strategic Shifts
Chip-scale integration is compressing magnetometer form factors while national quantum programs are reshaping competitive access to defense and medical procurement channels.
Photonic integrated circuits are embedding distributed feedback lasers and vapor cells on silicon substrates, reducing device footprint by orders of magnitude compared to benchtop optical magnetometers. Field geophysics contractors and portable medical diagnostic teams are adopting these miniaturized systems for rapid deployment scenarios. This architecture is decentralizing magnetic sensing capability from centralized laboratory facilities into distributed field operations and point-of-care clinical settings.
REACH and RoHS frameworks in Europe are restricting hazardous substance use in alkali metal vapor cell manufacturing, compelling OEMs to redesign sealing and electrode materials. The industrial consequence is accelerated qualification of glass-ceramic alternatives and lead-free solder processes. Medical device manufacturers targeting EU markets are responding by front-loading materials compliance documentation in their technical files.
Subscription-based calibration and maintenance contracts are displacing traditional capital equipment sales in metrology service channels. Research institutions and defense agencies are unbundling hardware acquisition from ongoing sensor performance verification. This pattern is most visible in United States procurement where DOD quantum sensing programs emphasize total cost-of-ownership metrics over upfront unit pricing.
Atomic Magnetometers Market Segmentation
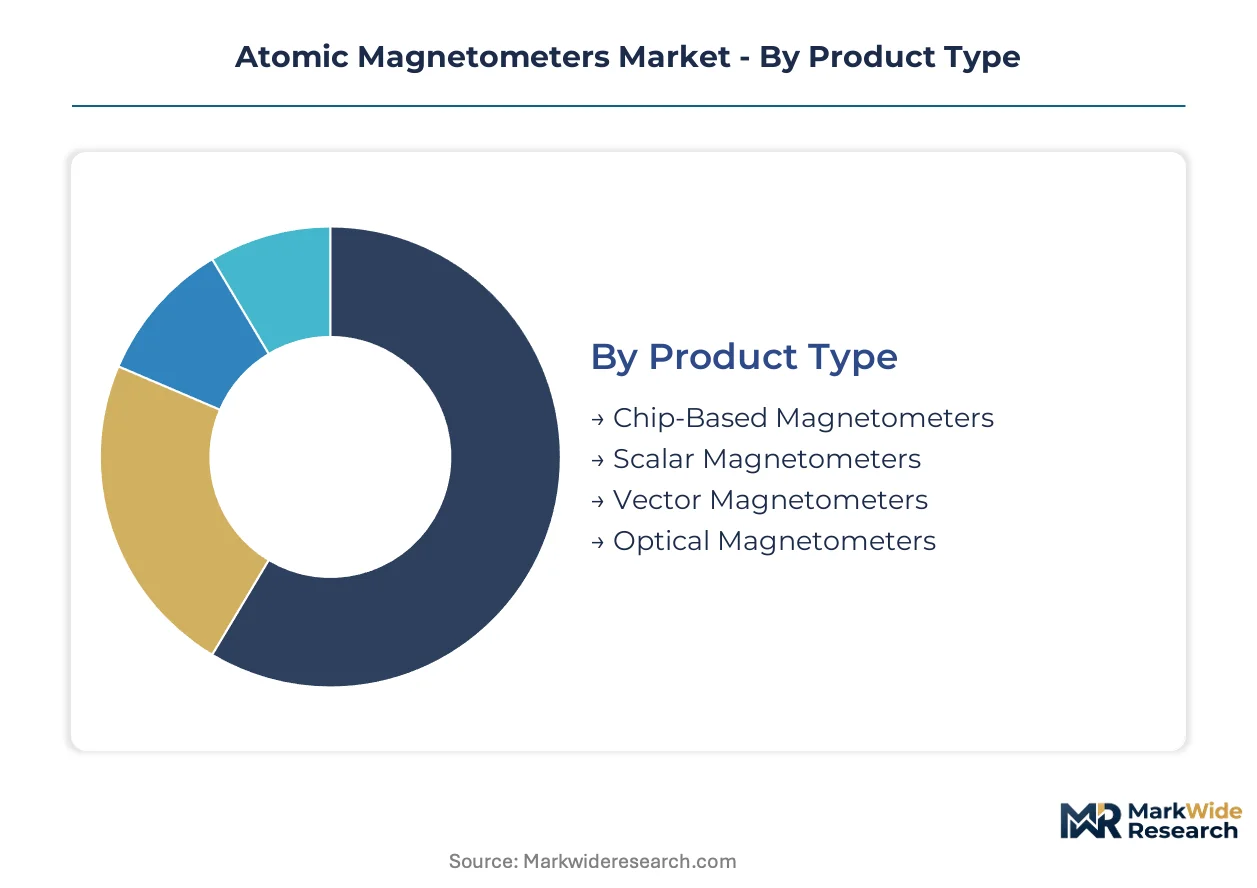
Atomic magnetometers fragment across multiple technical and commercial dimensions. Product architecture determines portability and power consumption. Application context dictates sensitivity requirements and regulatory pathways.
Product Type:
Optical magnetometers anchor current revenue through mature laser-pumped architectures and established calibration protocols. Chip-based systems are climbing the fastest as defense procurement compresses development cycles for miniaturized platforms.
- Optical Magnetometers:Laser-pumped alkali vapor cells achieve femtotesla sensitivity thresholds for biomagnetic signal detection. NIH brain-mapping consortia in the United States sustain procurement volumes where FDA 510(k) clearance barriers limit vendor entry.
- Chip-Based Magnetometers:Photonic integrated circuits embed distributed feedback lasers and vapor cells on silicon substrates. Field geophysics contractors and portable medical diagnostic teams adopt these miniaturized systems for rapid deployment scenarios.
- Scalar Magnetometers:Single-axis field strength measurement devices serve marine navigation and unexploded ordnance detection missions.
- Vector Magnetometers:Three-axis measurement capability supports geophysical survey contractors requiring directional magnetic anomaly mapping.
Mature deployment sits with optical magnetometers. Newer deployment is concentrated in chip-based systems.
Application:
Medical imaging commands premium pricing where regulatory validation extends commercialization timelines. Geophysical surveys deliver volume through defense and resource exploration procurement.
- Medical Imaging:Non-invasive neural signal detection for brain-mapping consortia requires electromagnetic compatibility validation under FDA pathways. Healthcare systems in the United States sustain demand pipelines for femtotesla-sensitivity devices.
- Geophysical Surveys:Submarine detection and unexploded ordnance localization drive cold atom gradiometer adoption. Naval defense agencies in France and Germany fund next-generation magnetic anomaly detection systems.
- Industrial Monitoring:Process control and quality assurance applications leverage scalar devices for ambient field monitoring.
- Research & Development:National laboratories advance spin-exchange optical pumping techniques for fundamental physics investigations.
Volume procurement centers on geophysical surveys. Premium margins concentrate in medical imaging.
End User:
Defense agencies fund technology maturation through submarine navigation programs. Healthcare systems impose the steepest regulatory barriers.
- Defense:Cold atom gradiometer systems for undersea magnetic anomaly detection receive priority funding in United States DOD quantum sensing programs.
- Healthcare:Clinical magnetometer deployment requires electromagnetic compatibility and patient safety validation under FDA device classification pathways.
- Aerospace:Navigation-grade magnetic sensing supports attitude determination and heading reference systems.
- Academia:Research institutions unbundle hardware acquisition from subscription-based calibration contracts emphasizing total cost-of-ownership metrics.
Procurement scale favors defense. Regulatory complexity peaks in healthcare.
Technology:
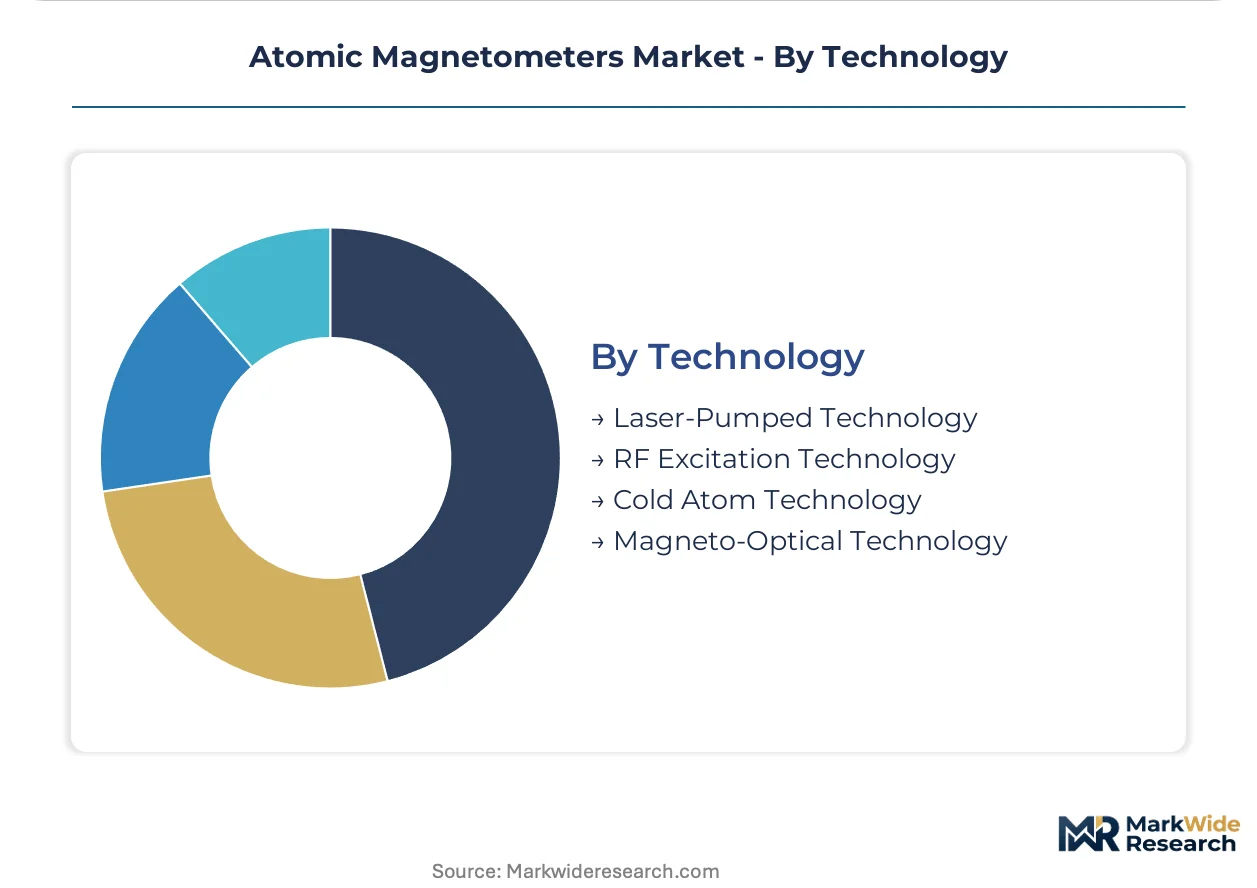
Laser-pumped architectures dominate installed base reliability. Cold atom methods are expanding most quickly through national laboratory and defense agency funding.
- Laser-Pumped Technology:Optical pumping of alkali atoms with circularly polarized light achieves spin polarization for sensitive magnetic field measurement. Mature calibration protocols support commercial deployment.
- Cold Atom Technology:Laser cooling and magnetic trapping of neutral atoms enables quantum-limited sensitivity for gradiometer applications. German and French national quantum initiatives channel public R&D toward miniaturized sensor platforms.
- RF Excitation Technology:Radio frequency modulation of atomic spin states supports compact scalar magnetometer designs.
- Magneto-Optical Technology:Faraday rotation measurement in atomic vapor cells provides vector field sensing capability.
Production maturity resides with laser-pumped systems. Steepest expansion trajectory belongs to cold atom technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors quantum sensing research concentration, with MIT and Harvard laboratories driving cold atom magnetometer maturation alongside DOD-funded defense contractors.
United States
NIH brain-mapping consortia and DOD quantum sensing programs sustain dual-use procurement pipelines for femtotesla-sensitivity devices. FDA device classification pathways mandate electromagnetic compatibility validation that extends commercialization timelines for medical entrants. The Greater Boston corridor concentrates research institutions and defense contractors advancing spin-exchange optical pumping techniques.
Germany
Federal quantum initiatives channel public R&D funding toward miniaturized sensor platforms for precision navigation applications. The EU Green Deal hardens sustainability benchmarks that push OEMs toward low-power quantum sensor architectures. Bavaria hosts industrial clusters where automotive and aerospace suppliers integrate navigation-grade magnetic sensing systems.
France
Naval defense agencies fund next-generation cold atom gradiometer systems for undersea magnetic anomaly detection. ANSM and national research frameworks shape clinical device validation requirements for neuromaging equipment. The Paris-Saclay research cluster concentrates atomic physics expertise and national laboratory infrastructure.
China
Resource exploration agencies and submarine detection programs drive scalar and vector magnetometer procurement volumes. NMPA and MIIT frameworks regulate medical device and precision instrumentation manufacturing standards. The Yangtze River Delta concentrates photonics manufacturing capacity supporting vapor cell component supply chains.
United Kingdom
Geophysical survey contractors and demining agencies sustain demand for portable vector magnetometer platforms. UK Research and Innovation funding channels support quantum technology translation from national laboratories. The Oxford-Cambridge arc anchors atomic physics research clusters with established spin-out pathways.
Atomic Magnetometers Market Competitive Environment
The competitive structure tilts toward defense-aerospace conglomerates with captive quantum research divisions. Tiered specialization separates benchtop optical system providers from chip-scale integration specialists. Three archetypes dominate: diversified technology conglomerates with aerospace heritage, specialized instrumentation houses with geophysical survey focus, and venture-backed quantum startups with national laboratory lineage. Capacity expansion and strategic partnerships with defense procurement channels represent the dominant competitive moves.
Among diversified technology conglomerates, Honeywell International Inc. and Lockheed Martin Corporation exemplify the defense-aerospace archetype with integrated quantum sensing divisions. Bartington Instruments Ltd and QuSpin Inc. represent specialized instrumentation and chip-scale integration specialists respectively, occupying positions that reflect divergent technology maturation strategies.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bartington Instruments Ltd |
| GEM Systems |
| Geometrics, Inc. |
| QuSpin Inc. |
| Twinleaf LLC |
| AOSense Inc. |
| Lockheed Martin Corporation |
| Quantum Design Inc. |
| Others |
Value Chain & Pricing Dynamics
NIH brain-mapping consortia and DOD quantum sensing programs in the United States are mandating femtotesla-sensitivity specifications and electromagnetic compatibility validation that compress supplier margins and force OEMs toward captive vapor cell production or exclusive alkali metal sourcing agreements.
Pricing Analysis
Value-based pricing anchored to clinical throughput and diagnostic yield separates FDA-cleared medical imaging systems from research-grade benchtop units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 17025-accredited calibration bundled into premium tiers. Cost compression in chip-scale systems is intensifying because photonic integrated circuit foundries are achieving economies of scale. Academic research institutions exhibit highest price sensitivity, while defense procurement channels prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense contractor demand, while metrology service providers distribute through subscription-based calibration contracts. Vapor cell manufacturing draws from cesium and rubidium sourcing concentrated in Canada, Kazakhstan, and Zimbabwe, with photonics component supply anchored in the United States, Germany, and China. Single-source vulnerability in alkali metal refining creates input cost volatility. Distribution runs through defense procurement channels, academic research consortia, and geophysical survey contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atomic magnetometers market sits in a technology-transition phase where chip-scale integration is displacing benchtop optical systems, and cold atom gradiometers are supplanting legacy scalar devices in submarine detection applications.
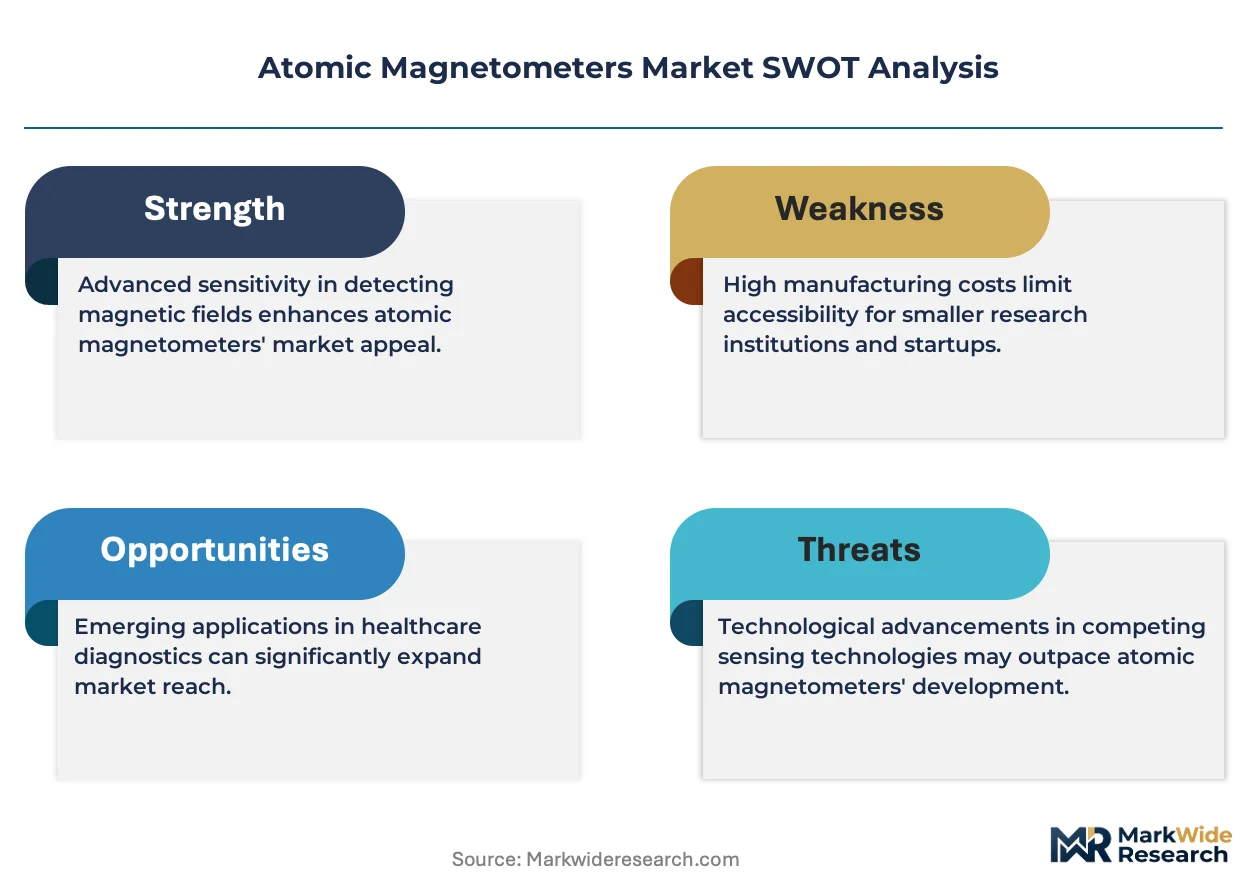
For Market Incumbents: Anticipate SQUID substitution threats in hospital settings where cryogenic infrastructure already exists by accelerating FDA 510(k) clearance pipelines for electromagnetic-compatible clinical systems. Backward integration into alkali metal vapor cell manufacturing reduces exposure to geopolitical supply concentration. Capacity expansion in Bavaria and Greater Boston clusters captures German quantum initiative funding and NIH procurement volumes. For New Entrants and Emerging Players: The price-point gap between premium FDA-cleared medical devices and economy research-grade systems creates entry space for mid-tier chip-scale platforms targeting portable diagnostic teams. Southeast Asian demining agencies represent the most penetrable geography for vector magnetometer surveys. A go-to-market angle through subscription-based calibration contracts unbundles hardware from recurring revenue streams. For Investors and Strategic Acquirers: The window for entry favors venture-backed quantum startups with national laboratory lineage and photonic integrated circuit IP. Long-term viability hinges on defense procurement channel access and medical regulatory clearance capabilities. Watch cold atom gradiometer adoption rates in French and German naval programs as the inflection indicator for technology maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Scale-Up | Silicon substrate embedding reduces helium-3 consumption in portable deployments. |
| FDA 510(k) Clearance Pathway | Electromagnetic compatibility validation opens clinical magnetometer procurement channels. |
| Defense Procurement Partnership | DOD quantum sensing programs anchor multi-year gradiometer acquisition pipelines. |
| Alkali Metal Supply Agreement | Long-term cesium and rubidium contracts mitigate geopolitical sourcing volatility. |
| Quantum-Photonics Convergence R&D | Chip-scale laser integration enables handheld form factors for field geophysics. |
Study Parameters
Independent corroboration across defense procurement officers, biomedical engineers at NIH-funded consortia, vapor cell manufacturing specialists, and geophysical survey contractors underwrites the qualitative findings. Primary interviews with atomic physics researchers, metrology service providers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, DOD budget justification documents, EU Green Deal implementation reports, and customs trade data. Bottom-up vendor revenue estimates and top-down addressable market sizing triangulate segment-level outputs.
Rate-of-change decomposition across the analysis window isolates volume effects from price-mix shifts in optical, chip-based, scalar, and vector magnetometer categories. The analytical framework models technology type, application context, end-user archetype, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from historical procurement trajectories in submarine detection and brain-mapping consortia, overlaid with national quantum initiative funding commitments and REACH-RoHS compliance cost pass-through assumptions.
Inputs from defense contractor earnings disclosures and national laboratory annual reports were available through the study window; gaps in classified program budgets and early-stage startup revenue introduce uncertainty bands around cold atom technology adoption curves. Forecasts reflect documented assumptions regarding FDA clearance timelines, alkali metal supply stability, and photonics foundry capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market