
 Global Psoriatic Arthritis Therapeutics Market | 2026-2036
Global Psoriatic Arthritis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Psoriatic Arthritis Therapeutics Market Foresight
North American biologics manufacturing is pivoting toward modular production platforms that reduce batch-to-batch variability for monoclonal antibodies. AbbVie Inc. leverages its immunology franchise to sustain dominance in interleukin-23 pathway inhibition. Amgen Inc. anchors its position through decades of biologics manufacturing scale and rheumatology channel depth. Pfizer Inc. competes by extending its small-molecule and biosimilar portfolios across multiple administration routes.
Psoriatic arthritis therapeutics comprise pharmaceutical agents designed to modulate immune-mediated joint inflammation, skin manifestations, and entheseal pathology through targeted cytokine inhibition or intracellular signal disruption; these therapies typically require cold-chain distribution, parenteral administration training, and periodic monitoring of immunogenicity and infection risk to preserve functional status and prevent irreversible joint damage. Biologics command the deepest margin pools due to biosimilar lag and patent-protected molecular engineering, while Janus kinase inhibitors represent the fastest-growing drug class as oral alternatives gain traction among patients averse to injection. Conventional DMARDs retain volume leadership in emerging markets where cost constraints dominate formulary decisions.
The FDA oversees clinical trial design and post-market surveillance for immunosuppressive therapies, while EMA's MDR and pharmacovigilance frameworks shape labeling and risk-management obligations across European markets; Japan's PMDA imposes distinct ethnic-sensitivity requirements that extend development timelines but secure premium reimbursement upon approval. The WHO prequalification pathway influences procurement standards in lower-income settings where access programs expand. Stakeholders must monitor evolving payer evidence requirements for comparative-effectiveness data as biosimilar competition intensifies across the interleukin inhibitor landscape.
Market Dynamics
The transition from originator biologics to biosimilars is compressing margin pools across interleukin and tumor necrosis factor inhibitor classes while specialty pharmacies consolidate patient access infrastructure.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses development timelines for novel Janus kinase inhibitors and interleukin-targeting molecules, enabling earlier patient access to mechanism-of-action innovations.
- Oral Administration Preference:Patient aversion to parenteral biologics drives demand for small-molecule alternatives, expanding addressable populations beyond injection-capable cohorts.
- Enthesitis and Dactylitis Recognition:Updated diagnostic criteria from rheumatology societies expand treatable patient pools by capturing subclinical joint and soft-tissue involvement earlier in disease progression.
Market Restraints
- Cold-Chain Distribution Costs:Biologic therapies require continuous temperature-controlled logistics, elevating per-dose fulfillment expenses and limiting pharmacy network participation.
- Immunogenicity Monitoring Burden:Periodic screening for neutralizing antibodies and infection risk adds clinical overhead that constrains prescribing in resource-limited settings.
- Conventional DMARD Substitution:Methotrexate and sulfasalazine retain formulary dominance in cost-constrained markets, delaying biologic initiation despite inferior radiographic outcomes.
Strategic Opportunities
- Brazil ANVISA Fast-Track:Expedited review pathways for immunology assets enable earlier market entry in Latin America's largest reimbursed pharmaceutical market.
- Telemedicine-Integrated Adherence Programs:Remote monitoring platforms reduce injection training burden and capture real-world efficacy data for payer negotiations.
- Japan PMDA Ethnic Bridging:Dedicated pharmacokinetic studies in Japanese populations secure premium reimbursement tiers unavailable to products with only Western clinical data.
Industry Challenges
- Biosimilar Manufacturing Scale-Up:Cell-line development and analytical comparability studies demand capital intensity that excludes mid-scale entrants from interleukin inhibitor competition.
- Rheumatology Workforce Density:Specialist availability constraints in secondary and tertiary markets delay diagnosis and biologic initiation, compressing effective treatment windows.
- Cross-Border Reference Pricing:Parallel trade and international price benchmarking erode country-specific premium positioning for originator molecules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Psoriatic Arthritis Therapeutics Market |
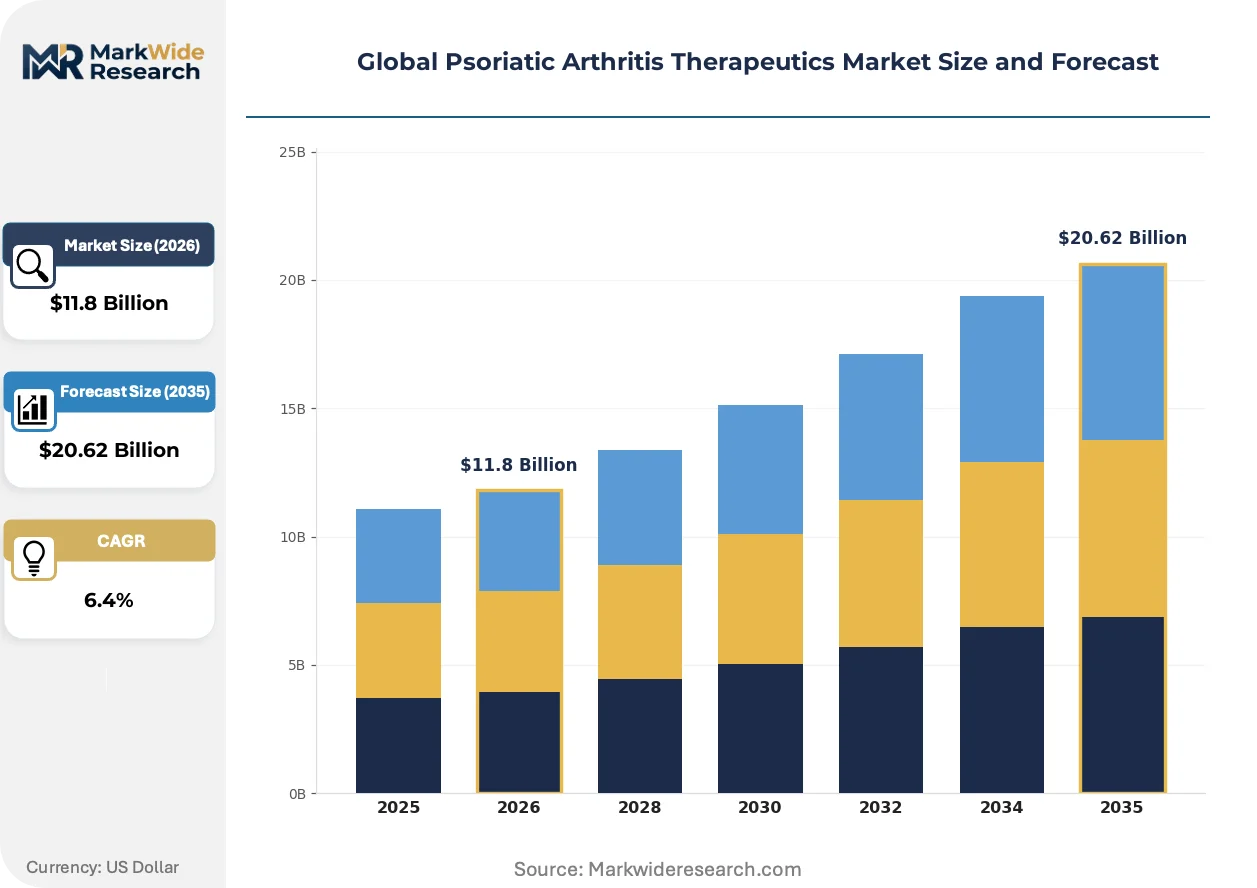
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Biologics, Small Molecule Inhibitors, Conventional DMARDs, PDE4 Inhibitors, Janus Kinase Inhibitors Therapy Area: Peripheral Arthritis, Axial Disease, Enthesitis, Dactylitis, Skin Lesions End User: Rheumatology Clinics, Specialty Pharmacies, Immune Disorder Centers, Ambulatory Surgical Centers Administration Route: Subcutaneous Injection, Oral, Intravenous Infusion, Topical, Intramuscular Injection |
| Companies Covered | AbbVie Inc., Amgen Inc., Pfizer Inc., Novartis AG, Bristol-Myers Squibb Company, Johnson & Johnson, Eli Lilly and Company, UCB Biopharma, Sun Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Psoriatic Arthritis Therapeutics Market Shifts & Advancements
Modular biologics manufacturing and real-world evidence generation are converging to reshape how psoriatic arthritis therapies reach patients and secure reimbursement.
Biospecific antibodies targeting dual cytokine pathways are expanding into earlier treatment lines as rheumatology practices seek steroid-sparing alternatives with superior skin and joint efficacy. Academic medical centers in Germany and the United States are adopting these constructs for biologic-experienced patients with incomplete responses to interleukin-17 or interleukin-23 monotherapy. The technology is expanding into combination protocols that pair cytokine blockade with Janus kinase inhibition, compressing time-to-response metrics for severe disease phenotypes.
EMA's Medical Device Regulation and pharmacovigilance framework now mandate enhanced risk-management plans for immunosuppressive therapies, extending labeling obligations across European markets. Manufacturers must submit periodic safety update reports with real-world infection data, elevating post-market surveillance costs. The interleukin inhibitor segment is responding by embedding patient registries into commercial launch strategies, converting compliance burden into competitive differentiation.
Specialty pharmacy consolidation is altering how biologics reach patients, with three national distributors now controlling cold-chain fulfillment for over half of United States parenteral immunology prescriptions. Independent infusion centers and hospital outpatient departments are losing volume to home administration programs supported by nurse training networks. This channel compression is most visible in Medicare Part B and commercial managed care populations, where prior authorization automation favors integrated pharmacy-benefit managers with dedicated immunology care teams.
Global Psoriatic Arthritis Therapeutics Market Segmentation
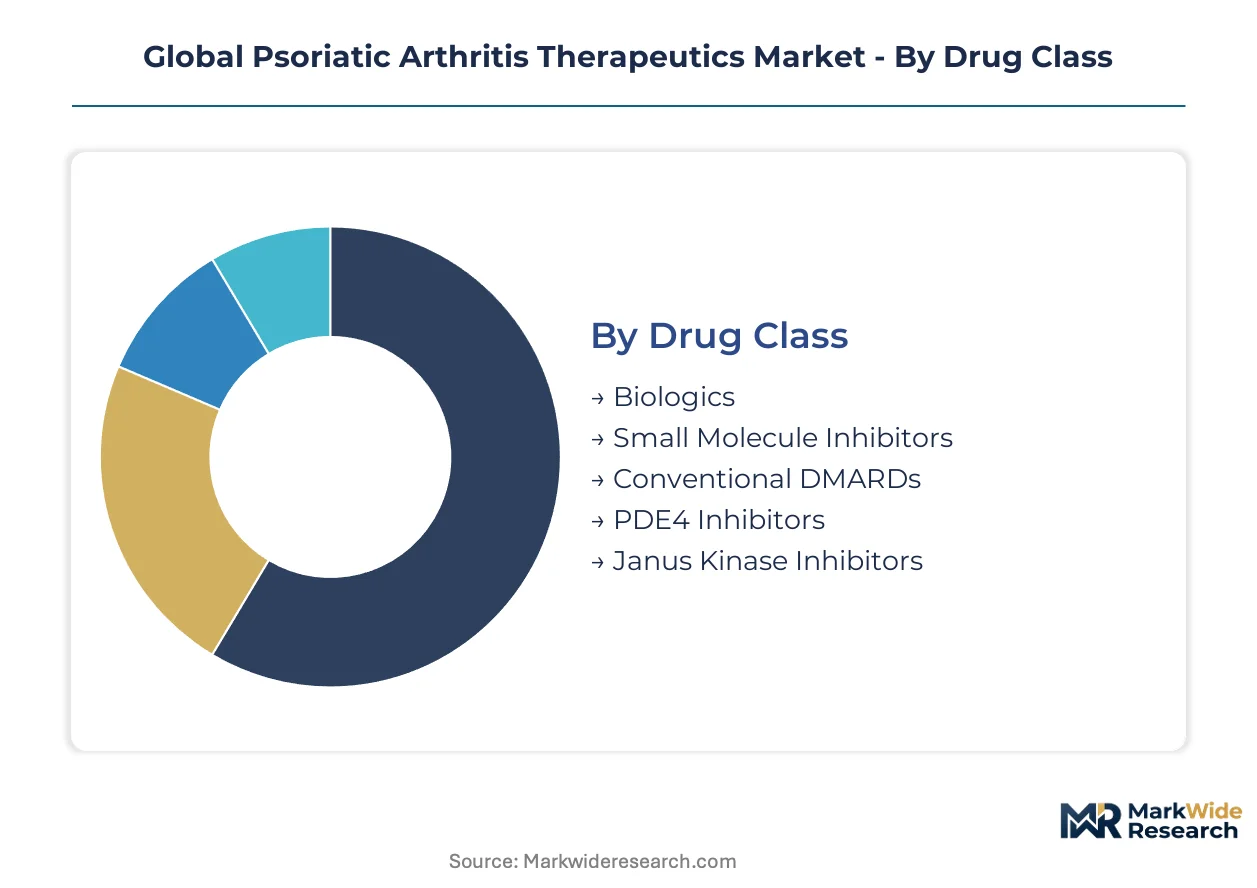
Segmentation reveals how capital allocation and reimbursement infrastructure determine competitive positioning across psoriatic arthritis therapeutics. Drug class and administration route splits expose where manufacturing complexity meets patient preference, while therapy area and end-user dimensions illuminate clinical workflow integration points.
Drug Class:
Capital intensity peaks in segments requiring cell-line development, cold-chain infrastructure, or multi-year clinical programs to demonstrate immunogenicity profiles.
- Biologics:Monoclonal antibodies and fusion proteins targeting interleukin-12/23, interleukin-17, and tumor necrosis factor-alpha pathways require mammalian cell culture facilities and continuous cold-chain distribution. AbbVie and Amgen concentrate manufacturing in Puerto Rico and Ireland to serve United States and European demand while navigating FDA and EMA batch-release protocols.
- Janus Kinase Inhibitors:Small-molecule ATP-competitive inhibitors of JAK1, JAK2, or JAK3 enable oral administration and ambient distribution, expanding addressable populations to injection-averse cohorts in Germany and Japan where PMDA and EMA have established risk-management frameworks for thromboembolic signals.
- Small Molecule Inhibitors:Non-JAK oral agents span phosphodiesterase-4 and other intracellular targets with lower development costs than biologics.
- Conventional DMARDs:Methotrexate and sulfasalazine command volume leadership in India and Brazil where cost constraints dominate formulary decisions.
- PDE4 Inhibitors:Apremilast and related compounds occupy a mid-tier position with favorable pregnancy profiles.
Most installed capacity flows through Biologics. Expansion is steepest in Janus Kinase Inhibitors.
Therapy Area:
Clinical trial design and regulatory endpoints fragment by anatomical manifestation, with separate FDA and EMA guidance documents for peripheral joint versus axial disease assessments.
- Peripheral Arthritis:Synovitis of large and small joints drives the majority of randomized controlled trials, with ACR20/50/70 response criteria serving as primary endpoints for FDA submissions. United States rheumatology practices concentrate biologic prescribing here before axial disease recognition expanded treatable pools.
- Enthesitis:Inflammation at tendon and ligament insertion sites now captures dedicated trial endpoints following GRAPPA and EULAR guideline updates, enabling earlier intervention in German and United Kingdom academic centers where ultrasound protocols standardize diagnosis.
- Axial Disease:Sacroiliitis and spondylitis overlap with ankylosing spondylitis diagnostic boundaries, requiring separate positioning strategies.
- Dactylitis:Digital inflammation serves as a distinctive psoriatic arthritis feature in differential diagnosis protocols.
- Skin Lesions:Psoriasis severity scores determine formulary access in markets where dermatology-rheumatology collaboration remains limited.
Peripheral Arthritis absorbs the deepest development investment. Enthesitis is gaining share fastest as diagnostic criteria tighten.
End User:
Channel configuration determines patient adherence infrastructure, with cold-chain fulfillment and injection training requirements favoring specialized distribution models over general pharmacy networks.
- Specialty Pharmacies:National distributors including CVS Specialty and Accredo control over half of United States parenteral immunology prescriptions through integrated prior authorization automation and nurse-led home administration programs that reduce hospital outpatient department volume.
- Rheumatology Clinics:Private practice and academic medical center infusion suites retain biological prescribing authority in Germany and Japan where specialist density supports direct physician-patient relationships.
- Immune Disorder Centers:Multidisciplinary facilities coordinate dermatology and rheumatology input for complex phenotypes.
- Ambulatory Surgical Centers:Limited penetration due to biologic administration complexity and infection risk monitoring requirements.
Specialty Pharmacies dominate fulfillment volume. Rheumatology Clinics retain the highest-margin infusion services.
Administration Route:
Patient preference and healthcare system capacity constraints reshape competitive dynamics between parenteral and oral delivery modalities.
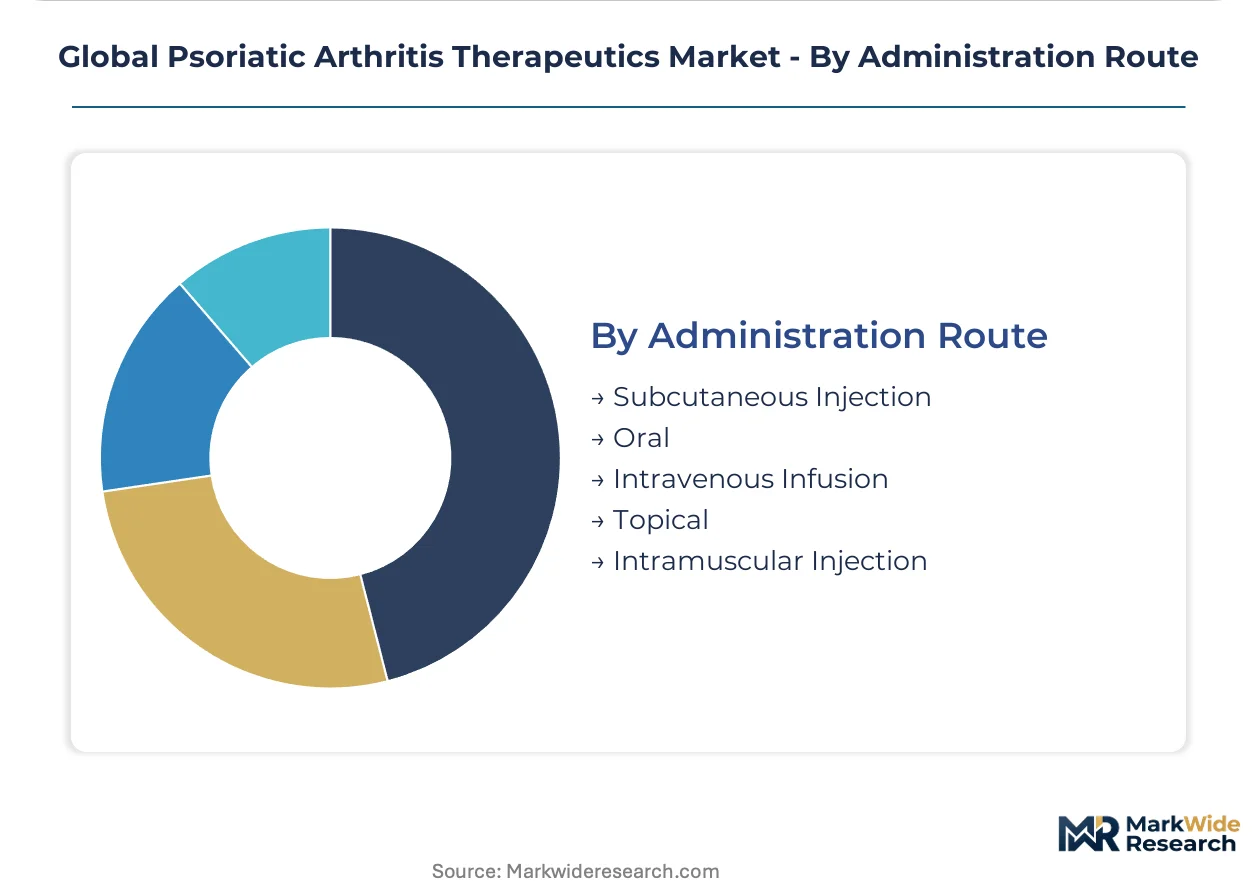
- Subcutaneous Injection:Prefilled syringes and autoinjector devices enable home administration after initial training, with United States Medicare Part B reimbursement favoring this model over intravenous alternatives. Cold-chain requirements limit pharmacy network participation to distributors with validated logistics infrastructure.
- Oral:Small-molecule JAK and PDE4 inhibitors bypass injection burden and expand treatable populations to patients with needle phobia or limited caregiver support, particularly in Japan where PMDA ethnic-bridging studies secure premium reimbursement tiers.
- Intravenous Infusion:Hospital and infusion center administration persists for some tumor necrosis factor inhibitors.
- Topical:Limited to adjunctive skin lesion management rather than joint disease.
- Intramuscular Injection:Minimal adoption due to variable absorption and patient discomfort profiles.
Subcutaneous Injection maintains the largest installed patient base. Oral routes are climbing the fastest as formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics pull biologics manufacturing toward jurisdictions with streamlined batch-release protocols and favorable tax treatment for intellectual property, while demand concentrates where reimbursement infrastructure supports premium-priced immunomodulatory therapies.
United States
Medicare Part B reimbursement for parenteral immunology prescriptions and commercial managed care prior authorization automation drive specialty pharmacy consolidation. The FDA's accelerated approval pathways compress development timelines for novel Janus kinase inhibitors. Puerto Rico hosts AbbVie's mammalian cell culture facilities serving domestic demand under FDA batch-release protocols.
Germany
Rheumatology specialist density and academic medical center ultrasound protocols for enthesitis diagnosis expand treatable patient pools. EMA's MDR and pharmacovigilance frameworks mandate enhanced risk-management plans for immunosuppressive therapies. The Rhine-Main cluster anchors UCB Biopharma's European operations for interleukin-targeting biologics.
Japan
PMDA ethnic-sensitivity requirements extend development timelines but secure premium reimbursement tiers unavailable to products with only Western clinical data. Patient preference for oral administration over injection drives demand for small-molecule alternatives. The Kanto region concentrates Eli Lilly's pharmacokinetic bridging studies and commercial launch infrastructure.
India
Cost constraints dominate formulary decisions, preserving conventional DMARD volume leadership despite inferior radiographic outcomes. CDSCO regulatory pathways for biosimilars attract contract manufacturing investment from multinational sponsors. Gujarat and Maharashtra host Sun Pharmaceuticals' production facilities for methotrexate and emerging biosimilar portfolios.
Brazil
ANVISA fast-track pathways for immunology assets enable earlier market entry in Latin America's largest reimbursed pharmaceutical market. Public procurement through the WHO prequalification pathway influences access program expansion. São Paulo's academic medical centers anchor rheumatology training networks that reduce diagnostic delay for psoriatic arthritis phenotypes.
Global Psoriatic Arthritis Therapeutics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar manufacturing scale-up and oral small-molecule differentiation. The market structures around three archetypes: originator biologics specialists with cell-line development capabilities, diversified pharmaceutical conglomerates with immunology franchise depth, and regional generics manufacturers capturing conventional DMARD volume. Competitive moves concentrate on M&A for pipeline assets and strategic partnerships for cold-chain distribution infrastructure.
Among North American-origin conglomerates, AbbVie Inc., Amgen Inc., and Pfizer Inc. exemplify distinct strategic positioning. AbbVie anchors the interleukin-23 pathway inhibition archetype through immunology franchise concentration. Amgen represents manufacturing scale advantages in biologics production. Pfizer occupies the diversified portfolio position spanning small-molecule and biosimilar development across multiple administration routes.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen Inc. |
| Pfizer Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Eli Lilly and Company |
| UCB Biopharma |
| Sun Pharmaceuticals |
| Others |
Supply & Pricing Matrix
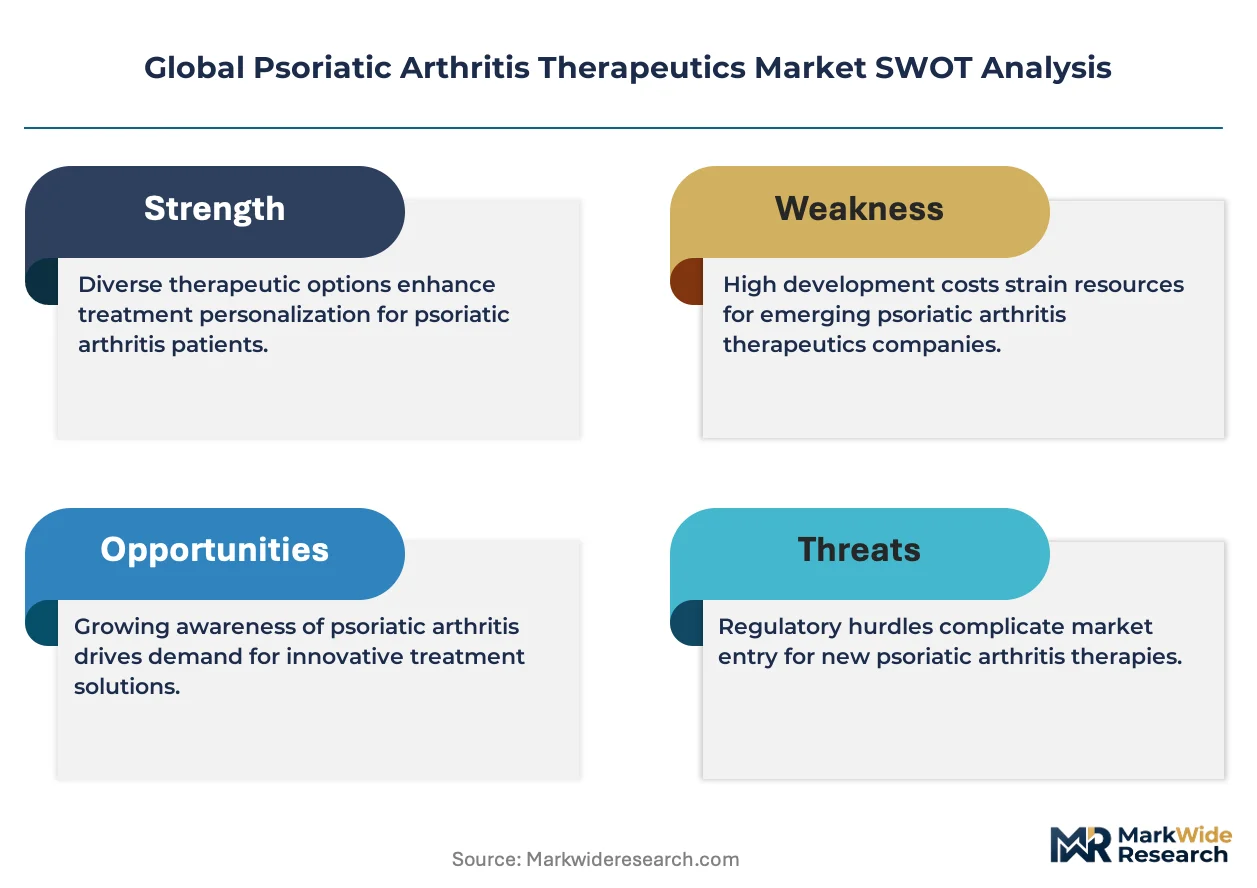
Biologic-originator versus biosimilar-originator divergence splits pricing power across cold-chain-dependent and ambient-distribution categories, with the former commanding premium tiers through patent-protected molecular engineering while the latter compresses margins via manufacturing scale advantages that reshape sourcing decisions toward contract development organizations.
Pricing Analysis
Specialty pharmacy distributor margins absorb significant value capture as prior authorization automation consolidates fulfillment networks. Three-tier pricing structure across originator biologics, biosimilars, and conventional DMARDs stratifies by immunogenicity risk profile and administration training burden. Cost compression in interleukin inhibitor classes intensifies as FDA-approved biosimilars enter European markets through EMA reference pricing mechanisms. Hospital procurement committees exhibit highest price sensitivity; rheumatology clinics with captive infusion suites demonstrate lowest sensitivity due to bundled service revenue.
Supply Chain Analysis
Workforce availability constraints in Puerto Rico and Ireland mammalian cell culture facilities limit batch-release throughput under FDA and EMA protocols. Manufacturing gravity centers on these jurisdictions for United States and European demand, with Singapore emerging for Asia-Pacific supply. Raw material dependencies span recombinant protein media, single-use bioreactor components, and temperature-controlled packaging. Single-source vulnerability in cold-chain logistics partnerships elevates risk profiles. Distribution runs through three national specialty pharmacy networks controlling over half of parenteral immunology prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Psoriatic arthritis therapeutics represent a late-cycle quality story as rheumatology practices shift demand toward steroid-sparing biologics with superior enthesitis and dactylitis efficacy profiles.
For Market Incumbents: Deepen immunology franchise concentration through interleukin-23 pathway extension and JAK inhibitor co-formulation strategies. Biosimilar entrants threaten originator biologics revenue; vertical integration into Puerto Rico and Ireland cell-line development secures manufacturing capacity advantage. Prior authorization automation partnerships with specialty pharmacies reinforce channel control. For New Entrants and Emerging Players: Enter via Brazil ANVISA fast-track pathways for immunology assets, where public procurement expansion creates accessible volume. Conventional DMARD substitution gaps in India and Southeast Asia offer most penetrable white space. Oral small-molecule positioning bypasses cold-chain infrastructure requirements and injection training burdens. For Investors and Strategic Acquirers: Consolidation pressure builds where biosimilar manufacturing scale-up demands exceed mid-scale capital availability. Five-to-ten year viability favors originators with pipeline depth in dual-cytokine bispecifics. Acquisition target archetype: cell-line development specialists with EMA and FDA master file documentation. Watch for interleukin inhibitor patent cliff timing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses timelines for novel JAK inhibitors entering United States markets. |
| Manufacturing Scale-Up | Puerto Rico mammalian cell culture expansion serves FDA batch-release demand with tax-advantaged positioning. |
| Licensing Agreement | Japan PMDA ethnic-bridging studies secure premium reimbursement tiers unavailable to Western-only data packages. |
| Pipeline Diversification | Dual-cytokine bispecific antibodies expand into earlier treatment lines for biologic-experienced patients. |
| Reimbursement Strategy | Medicare Part B prior authorization automation favors integrated pharmacy-benefit managers with immunology care teams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Segment-weighting approaches distributed value across drug class, therapy area, administration route, and regional regulatory clusters throughout the forecast period. CAGRs derived from epidemiological progression models, treatment-line evolution assumptions, and biosimilar penetration curves. Modeled inputs included rheumatology workforce density by metropolitan statistical area and cold-chain logistics cost inflation indices.
The model holds under stable regulatory approval timelines and reimbursement tier structures; deviation in biosimilar interchangeability policy or PMDA ethnic-study requirements would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Autism Spectrum Disorder Management Market