
 Autonomous Last Mile Delivery Market | 2026-2036
Autonomous Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Last Mile Delivery Market Analysis
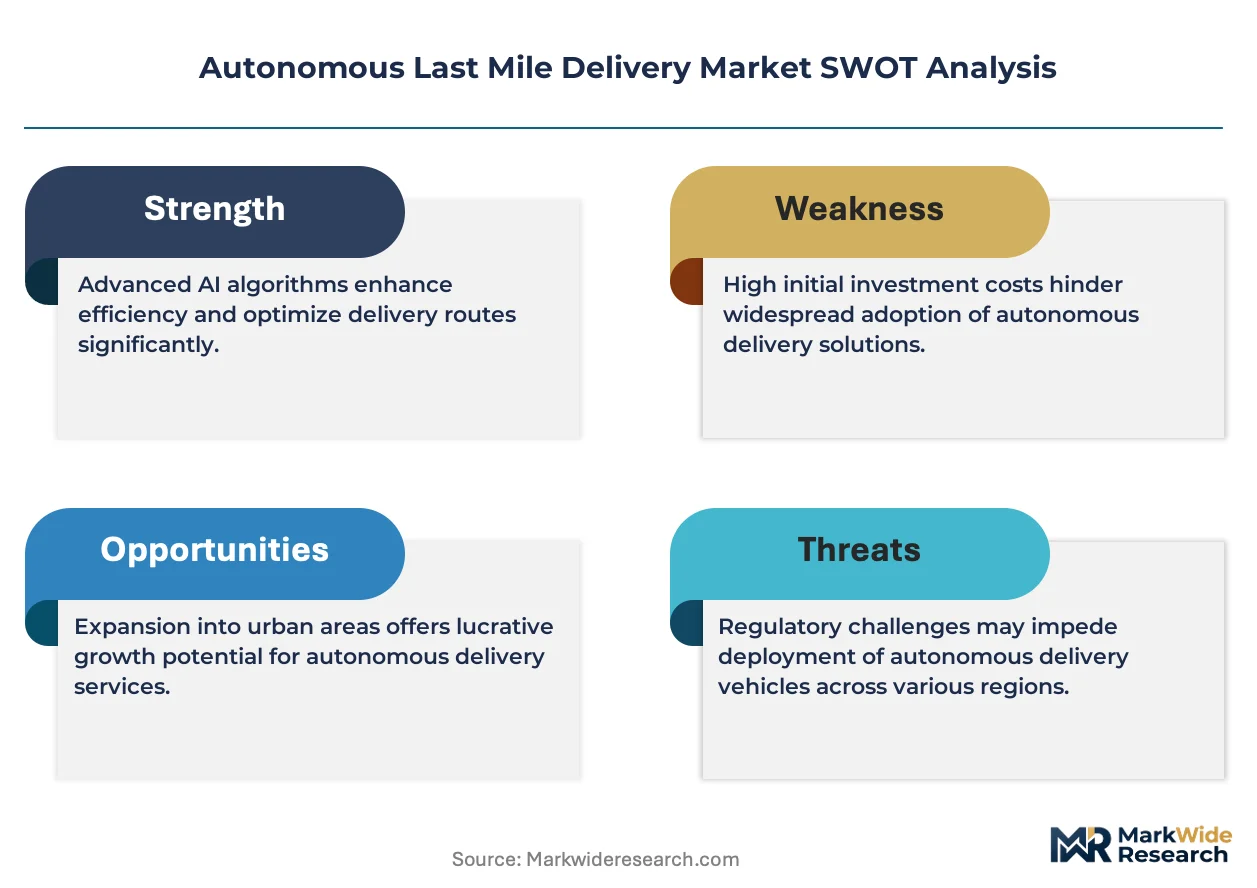
Platform licensing revenue is reshaping competitive economics in autonomous last mile delivery, shifting margin pools from hardware sales to recurring software and fleet-management contracts. Amazon leverages its cloud infrastructure to anchor logistics orchestration at scale. Nuro sustains deep specialization in roadway-certified autonomous vehicles with no human safety driver. Starship Technologies dominates sidewalk robot deployments across university and corporate campuses.
Autonomous last mile delivery denotes the use of self-navigating ground robots, aerial drones, and driverless vans to transport goods from distribution hubs to end consumers without human operators, typically covering distances under five miles at speeds constrained by local ordinances and battery capacity. Robotic delivery occupies mature urban corridors with predictable terrain, while drone delivery captures premium-speed segments constrained by payload limits and airspace coordination. AI routing and computer vision constitute the fastest-growing technology pair as operators demand real-time obstacle detection and dynamic path recalculation.
FAA regulations govern commercial drone operations in the United States, while the EU AI Act and CE marking requirements shape product liability and autonomous system deployment across European member states. NHTSA vehicle safety standards apply to roadway autonomous vans, creating a multi-layered compliance landscape that operators must navigate simultaneously. Stakeholders should monitor regulatory divergence between federal aviation frameworks and municipal traffic ordinances, as fragmented compliance obligations will determine which service models achieve profitable unit economics first.
Market Dynamics
Platform licensing economics are concentrating margin capture among operators with proprietary routing AI and cloud-scale fleet orchestration, compressing hardware-only vendors into commoditized component supply roles.
Growth Catalysts
- FAA Part 135 Certification Pathway:The United States aviation regulator's commercial drone framework is enabling beyond-visual-line-of-sight parcel operations in suburban corridors, unlocking density-dependent route economics for certified operators.
- Computer Vision Sensor Fusion:Multi-modal perception stacks combining lidar, radar, and thermal imaging are reducing collision rates in unstructured sidewalk and roadway environments, accelerating municipal permitting timelines.
- E-commerce Fulfillment Density:Urban micro-fulfillment center placement within five-mile radii of residential clusters is creating dedicated launch infrastructure for autonomous vehicle handoffs.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode material processing capacity clusters in China, exposing fleet operators to input cost volatility and geopolitical supply disruption risks.
- Municipal Traffic Ordinance Fragmentation:City-level sidewalk robot weight limits and speed caps vary across jurisdictions, preventing standardized fleet deployment without costly localization.
- Human Safety Driver Mandates:Several US states retain requirements for onboard attendants during autonomous van testing, delaying labor cost savings and unit economic breakeven.
Strategic Opportunities
- Rural Healthcare Logistics:Underpenetrated exurban territories in the United States present white-space demand for temperature-controlled pharmaceutical drone delivery beyond traditional courier reach.
- EU U-Space Airspace Integration:The European framework for unmanned traffic management is creating regulatory tailwinds for cross-border drone corridor development connecting distribution hubs.
- 5G Edge Computing Convergence:Low-latency connectivity paired with roadside edge nodes enables real-time obstacle processing without onboard supercomputing, reducing vehicle hardware costs.
Industry Challenges
- Autonomy Software Certification Timelines:NHTSA safety assessments for roadway vehicles require extensive mileage accumulation and scenario validation, extending time-to-revenue for new platform entrants.
- Retrofit Integration Complexity:Legacy warehouse management systems lack API standardization for autonomous vehicle dispatch, forcing custom middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Last Mile Delivery Market |
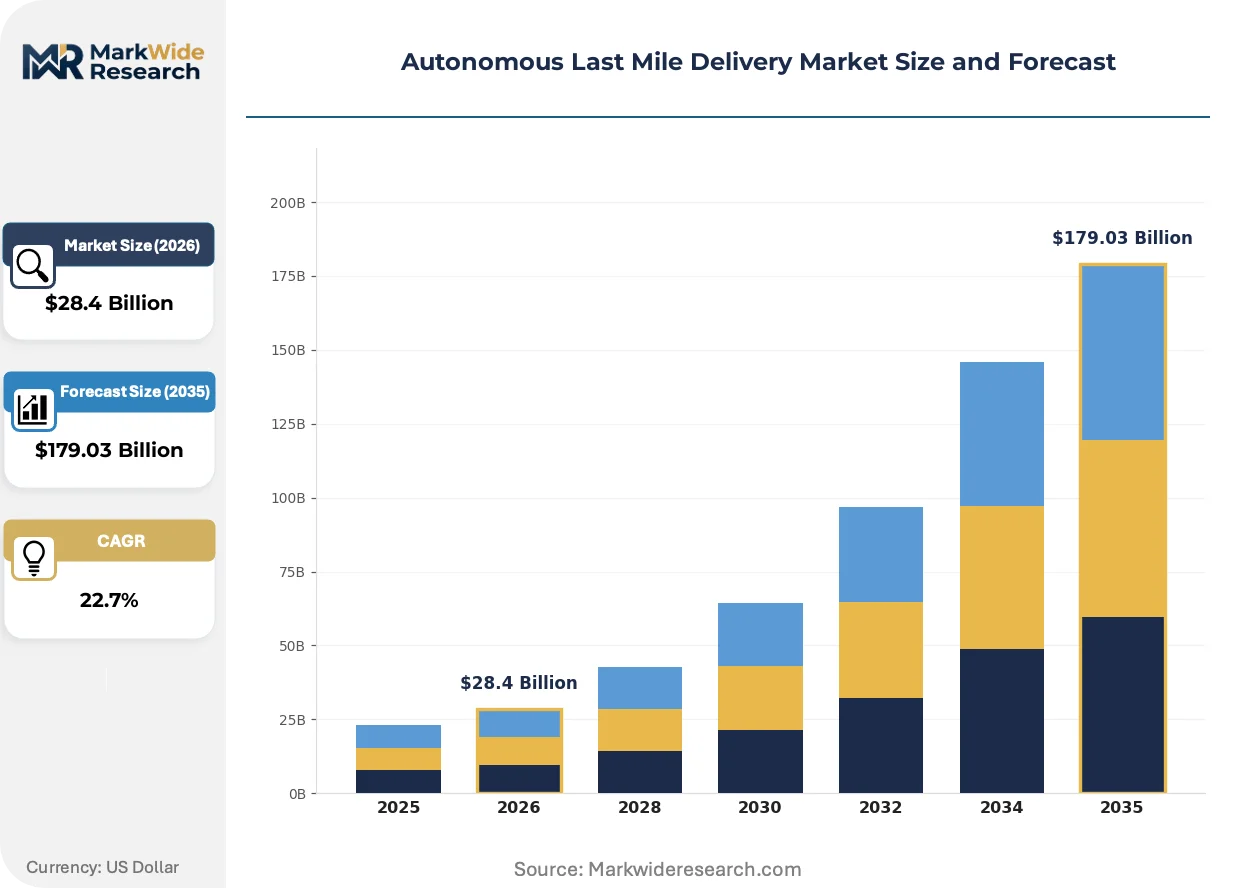
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $179.03 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Type: Drone Delivery, Robotic Delivery, Electric Vehicles, Autonomous Vans Technology: GPS Navigation, Computer Vision, Machine Learning, AI Routing End User: Retailers, E-commerce Platforms, Logistics Providers, Food Delivery Services Service Model: On-Demand, Scheduled, Subscription, Hybrid |
| Companies Covered | Amazon, Starship Technologies, Nuro, JD.com, Kiwibot, UPS, Flirtey, Serve Robotics, Zipline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Last Mile Delivery Market Emerging Trajectories
Digitization of fleet command layers is compressing the role of traditional dispatch operations, with algorithmic orchestration replacing human coordination in high-frequency delivery windows.
Digital twin simulation environments are virtualizing pre-deployment route validation, allowing operators to stress-test autonomous navigation against millions of synthetic edge cases without physical mileage accumulation. Logistics providers with dense historical delivery datasets are adopting these tools fastest, compressing pilot-to-production timelines from years to months. This virtualization is reducing insurance premiums and municipal skepticism by demonstrating safety performance before road presence.
The EU AI Act's risk-classification framework for autonomous systems is imposing conformity assessment obligations on delivery robot manufacturers seeking CE marking access. High-risk categorization triggers mandatory third-party auditing of training data governance and algorithmic transparency. European operators are responding by segregating fleet architectures, deploying simplified autonomy stacks in member states with lighter oversight while reserving full-capability systems for regulatory-aligned markets.
Subscription-based fleet access is displacing capital-heavy vehicle ownership among mid-market retailers, with third-party operators bearing depreciation and maintenance exposure. Food service and grocery verticals are driving this shift, prioritizing operational flexibility over balance-sheet control. This preference is most visible in dense German and Japanese urban districts where parking scarcity and congestion charging make owned fleet economics prohibitive.
Autonomous Last Mile Delivery Market Segmentation
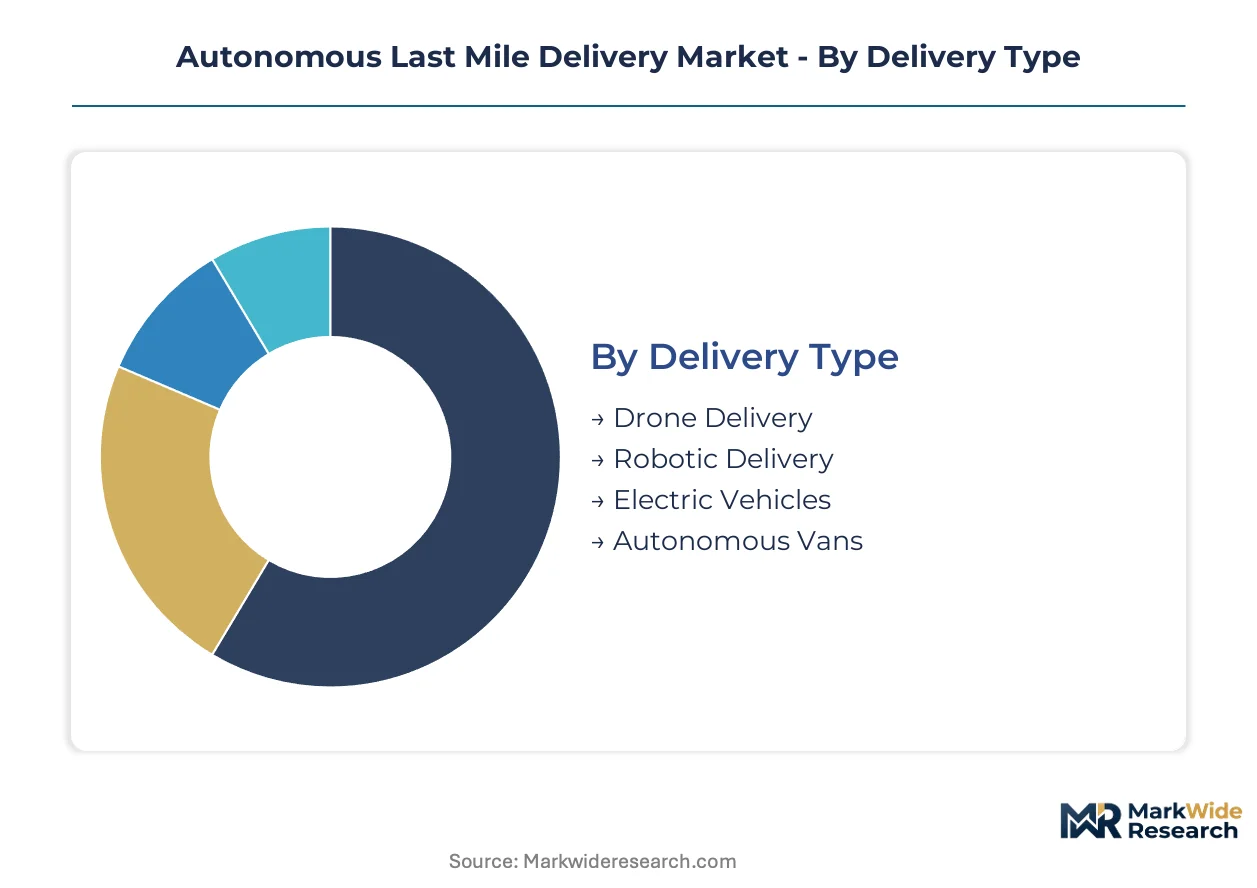
Delivery modality and technology stack selection determine capital intensity, regulatory exposure, and route economics for autonomous last mile operators. Segment alignment with payload requirements, terrain constraints, and customer density patterns separates scalable deployments from pilot-phase stagnation.
Delivery Type:
Aerial and ground modalities address distinct distance-speed-payload tradeoffs across suburban, urban, and campus environments.
- Drone Delivery:Battery-powered quadcopters and fixed-wing systems transport parcels under 10 pounds across 5-15 mile radii. FAA Part 135 certification unlocks beyond-visual-line-of-sight operations in Texas and North Carolina corridors, though payload limits restrict penetration beyond premium-speed retail and medical verticals.
- Robotic Delivery:Six-wheeled sidewalk robots navigate pedestrian corridors at 4-6 mph using stereo cameras and ultrasonic arrays. University campuses in Estonia and corporate parks in California concentrate deployment density, where predictable terrain and localized permitting accelerate fleet replication.
- Electric Vehicles:Human-attended electric cargo bikes and small trucks bridge hub-to-doorstep gaps in dense European districts. Battery swap infrastructure in Amsterdam and Copenhagen supports continuous operation during peak delivery windows.
- Autonomous Vans:Roadway-certified vehicles without safety drivers carry 500-2,000 pound loads across 10-50 mile suburban routes. NHTSA safety assessments and state-level testing permissions in Arizona and California govern deployment timelines.
Established volume favors robotic delivery; emerging adoption favors autonomous vans.
Technology:
Perception and decision layers differentiate reliability margins across unstructured sidewalk, roadway, and low-altitude airspace environments.
- GPS Navigation:Satellite positioning with RTK correction achieves 2-centimeter accuracy for outdoor route following. Signal multipath in urban canyons limits standalone utility, driving integration with visual-inertial odometry in San Francisco and Manhattan deployments.
- Computer Vision:Convolutional neural networks process camera feeds for obstacle classification and lane keeping. Thermal imaging integration extends operational hours into darkness across Finnish and Norwegian winter corridors.
- Machine Learning:Predictive models forecast delivery time windows and customer presence probability. Historical route data from millions of completed trips in Singapore and Dubai refines arrival accuracy.
- AI Routing:Real-time graph optimization recalculates paths around traffic incidents, construction zones, and dynamic no-fly areas. Cloud-scale orchestration enables thousand-vehicle fleet coordination for same-day e-commerce fulfillment.
AI routing commands the steepest expansion trajectory; GPS navigation provides the foundational layer.
End User:
Customer archetype shapes service level agreements, payload specifications, and margin structures.
- Retailers:Grocery chains and big-box operators deploy mixed fleets for click-and-collect and home delivery. Kroger and Albertsons pilot programs in Texas prioritize temperature-controlled compartments for frozen goods.
- E-commerce Platforms:Pure-play online marketplaces demand sub-one-hour delivery windows and dense drop-point networks. Amazon Prime Air and Walmart DroneUp operations concentrate around micro-fulfillment centers within 10-mile radii of suburban households.
- Logistics Providers:Third-party carriers integrate autonomous assets into existing hub-and-spoke networks. FedEx and UPS trials focus on residential route segments with lowest human driver efficiency.
- Food Delivery Services:Meal and grocery platforms prioritize thermal retention and spill prevention over speed. DoorDash and Uber Eats sidewalk robot deployments target university dining halls and dense apartment complexes.
Food delivery services drive highest trip frequency; logistics providers capture largest per-route volume.
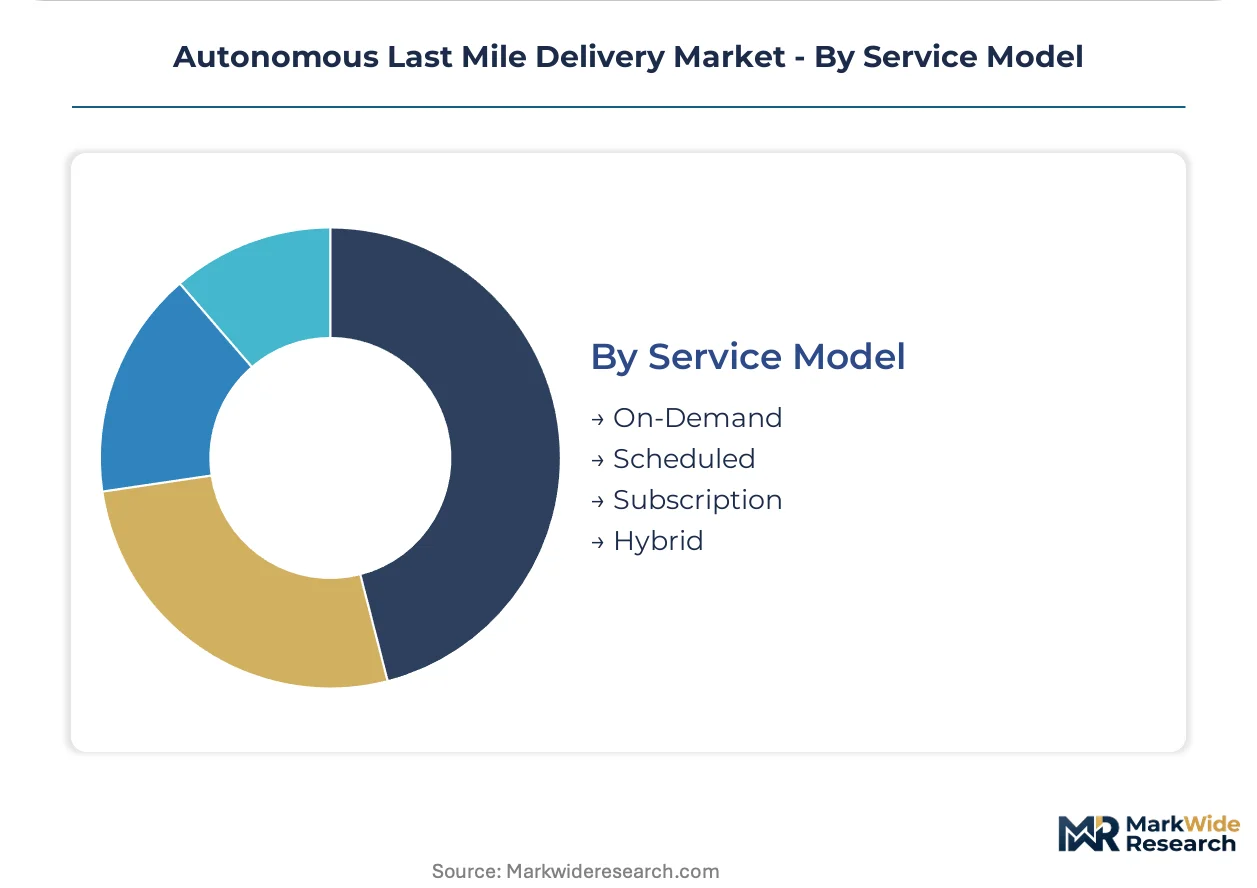
Service Model:
Contract structure determines fleet utilization rates and capital recovery timelines.
- On-Demand:Immediate dispatch upon order placement commands premium pricing for urgent medical, food, and retail scenarios. Utilization volatility requires excess fleet capacity during peak hours.
- Scheduled:Pre-booked delivery windows enable route batching and density optimization. Pharmaceutical and meal-kit verticals favor morning and evening slot predictability.
- Subscription:Flat-fee unlimited delivery programs lock in recurring revenue and predictable demand patterns. Amazon Prime and Walmart+ memberships subsidize autonomous fleet amortization across high-frequency users.
- Hybrid:Blended models combine subscription base loads with on-demand surge capacity. German and Japanese operators deploy this structure to balance utilization during off-peak periods.
Subscription models anchor fleet planning; hybrid structures maximize asset turns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, accepting premium autonomous delivery fees for reliability guarantees, while price-sensitive markets in India and Brazil prioritize cost minimization over service speed.
United States
Suburban e-commerce density and permissive state-level pilot programs drive fleet deployment acceleration. FAA Part 135 certification unlocks beyond-visual-line-of-sight drone operations across Texas and North Carolina corridors. The Phoenix-Mesa-Chandler metro area hosts concentrated autonomous van testing without human safety driver mandates.
China
Urban micro-fulfillment center saturation and last-mile labor cost inflation push platform operators toward robotic substitution. MIIT autonomous vehicle testing frameworks govern deployment permissions in designated smart city zones. Shenzhen and Hangzhou anchor the densest sidewalk robot and autonomous van pilot concentrations.
Germany
Grocery subscription density and congestion charging in urban cores make autonomous fleet economics attractive for mid-market retailers. KBA type-approval requirements and EU AI Act conformity assessments shape product liability frameworks. Berlin and Munich concentrate third-party operator partnerships with domestic supermarket chains.
Japan
Aging courier workforce demographics and rural pharmacy access gaps create dual demand vectors for automated delivery. METI safety standards and local ordinance harmonization efforts streamline municipal permitting. Tokyo's Shibuya ward and Osaka's Kita district host the highest sidewalk robot trip frequencies.
United Arab Emirates
Luxury retail fulfillment expectations and government smart city investment programs subsidize premium autonomous service trials. MOHAP drone delivery guidelines and Dubai Civil Aviation Authority frameworks enable cross-emirate corridor development. Dubai Silicon Oasis and Abu Dhabi's Masdar City integrate autonomous logistics into planned district infrastructure.
Autonomous Last Mile Delivery Market Vendor Landscape
Capability concentration sits with specialized autonomy developers; scale advantage sits with integrated e-commerce platforms. The market structures around three tiers: cloud-scale orchestrators with captive demand, pure-play robotics vendors licensing fleet management software, and legacy logistics carriers retrofitting autonomous assets into existing networks. Dominant competitive moves include strategic partnerships between retailers and autonomy providers, plus vertical integration of routing AI into proprietary fulfillment stacks.
Within the cloud-scale orchestrator tier, Amazon exemplifies platform economics through logistics infrastructure integration. Among pure-play ground robotics specialists, Nuro and Starship Technologies occupy positions representing divergent regulatory strategies—roadway-certified vehicle deployment versus sidewalk robot density. These three entities anchor the competitive archetype spectrum from integrated demand-capture to specialized autonomy supply.
| Leading Market Players |
|---|
| Amazon |
| Starship Technologies |
| Nuro |
| JD.com |
| Kiwibot |
| UPS |
| Flirtey |
| Serve Robotics |
| Zipline |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese cathode material processing exposes fleet operators to input cost volatility that compresses margin spreads between premium certified deployments and economy-tier pilot programs while forcing supply chain regionalization investments.
Pricing Analysis
After-sales revenue from fleet-management software subscriptions and predictive maintenance contracts drives lifetime value beyond hardware margins. Pricing stratifies across FAA Part 135 certified operators, state-permitted pilot programs, and campus-limited sidewalk robot tiers. Certification level and cloud-orchestration capability separate premium from standard pricing. Cost compression in the hardware-only vendor tier is intensifying because platform licensing economics concentrate margin capture with integrated operators. Mid-market retailers exhibit highest price sensitivity; healthcare logistics buyers show lowest elasticity for temperature-controlled pharmaceutical delivery.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for lithium-ion battery procurement. Cathode material processing clusters in China, South Korea, and Japan; autonomous vehicle compute hardware sources from Taiwan and the United States. Lithium carbonate, nickel sulfate, and high-density silicon anodes constitute critical input dependencies. Single-source vulnerability in rare earth magnet supply for drive motors compounds geopolitical exposure. Distribution runs through tier-one autonomy developers to fleet operators, with component vendors increasingly locked into white-label supply roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of FAA Part 135 certified operators with proven beyond-visual-line-of-sight track records creates asymmetric returns for parties that secure regulatory clearance and dense route data first.
For Market Incumbents: Build data network effects through exclusive micro-fulfillment center partnerships that lock in launch infrastructure access. Deepen vertical integration into proprietary routing AI to prevent margin migration to software licensors. Counter emerging pure-play robotics vendors by securing municipal permitting relationships before ordinance fragmentation hardens. Prioritize certification investment in Arizona and Texas corridors where safety driver mandates lapse earliest. For New Entrants and Emerging Players: Build out rural healthcare logistics networks where temperature-controlled pharmaceutical demand exceeds traditional courier reach and regulatory barriers are lower than urban airspace. Campus and corporate park sidewalk robot deployments offer the most penetrable segment due to localized permitting and predictable terrain. Target university dining contracts as anchor demand for fleet utilization before expanding to adjacent municipal corridors. Pursue white-label fleet operation partnerships with mid-market grocery chains lacking in-house autonomy expertise. For Investors and Strategic Acquirers: FAA Part 135 certification milestones reshape the acquisition landscape by separating scalable platform operators from perpetual pilot-phase ventures. Long-term viability favors entities with captive demand streams and cloud-scale orchestration infrastructure over hardware-only vendors facing component commoditization. Acquisition target archetypes include specialized autonomy developers with proven safety datasets and municipal permitting relationships. Watch NHTSA safety assessment completion timelines as the critical inflection signal for roadway autonomous van commercialization readiness.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 135 Certification Pursuit | Beyond-visual-line-of-sight approval unlocks suburban route density economics in Texas and North Carolina corridors. |
| Micro-Fulfillment Center Partnership | Exclusive launch infrastructure access within five-mile residential radii secures dedicated handoff points for fleet deployment. |
| Proprietary Routing AI Development | In-house graph optimization prevents margin capture migration to third-party software licensors and cloud orchestrators. |
| Municipal Permitting Relationship Buildout | Early city-level agreements before ordinance fragmentation hardens create localized competitive moats against later entrants. |
| Rural Healthcare Corridor Development | Temperature-controlled pharmaceutical delivery networks address white-space demand beyond traditional courier operational reach. |
Methodological Framework
Operator-level perspectives from fleet operations directors, autonomy software engineers, municipal permitting officials, and logistics procurement managers anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FAA certification databases, NHTSA safety assessment filings, EU U-space regulatory frameworks, and customs trade data for lithium-ion battery inputs. Bottom-up unit economic modeling across delivery modalities triangulated against top-down market sizing from e-commerce fulfillment density trends.
Scenario-bracketing framed analytical outputs across the projection horizon, with baseline, accelerated certification, and regulatory delay pathways informing range estimates. Segmentation dimensions modeled include delivery modality, autonomy technology stack, end-user vertical, and service model contract structure. CAGRs derived from route density elasticity analysis and fleet utilization curves. Forecast inputs incorporated battery cost decline trajectories and municipal permitting timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive certification acceleration by Amazon or Nuro would shift outcomes toward earlier beyond-visual-line-of-sight penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Retail Logistics Market