
 Ocean Freight Forwarding Market | 2026-2036
Ocean Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Ocean Freight Forwarding Market Insights
New container terminal expansions along Vietnam's Cai Mep-Thi Vai corridor is realigning Southeast Asian export flows away from traditional Chinese load ports. DSV Global Transport and Logistics leverages its integrated air-sea platform to capture project cargo moving through emerging manufacturing zones. Kuehne + Nagel sustains dominance in pharmaceutical reefer forwarding through certified cold-chain infrastructure at major transshipment hubs. Sinotrans anchors intra-Asia volume through its state-backed port access and bonded warehousing network.
Ocean freight forwarding encompasses the coordination of cargo movement across international waters through carrier contracting, documentation management, and multimodal interchange, typically operating within vessel capacities ranging from 1,800 TEU feeders to 24,000 TEU ultra-large container vessels sailing at 16-22 knots. The service orchestrates supply chain continuity for manufacturers and distributors by consolidating fragmented shipper volumes into economically viable container lots and managing customs compliance across jurisdictions. Full Container Load shipping captures the dominant value pool due to direct carrier relationships and lower per-unit handling overhead, while Less than Container Load services compete on consolidation density and frequency of sailing schedules. Reefer container forwarding generates premium margins from temperature-validated pharmaceutical and perishable cargo flows, though dry container movements still constitute the volume base across major trade lanes.
The International Maritime Organization enforces carbon intensity indicator ratings that penalize inefficient vessels, redirecting carrier procurement toward dual-fuel methanol and LNG-capable tonnage. Customs authorities in the United States, European Union, and China impose divergent advance manifest filing deadlines and security screening protocols that shape forwarder technology investments and staffing models. Stakeholders must monitor carrier alliance restructuring and emission compliance deadlines to avoid stranded capacity commitments or surcharged routings.
Market Dynamics
The International Maritime Organization's carbon intensity indicator ratings are forcing carriers to retrofit existing fleets or absorb penalties, compressing forwarder margins while rerouting cargo through slower-steaming lanes with extended transit times.
Growth Catalysts
- Dual-fuel vessel procurement mandates:The IMO's net-zero framework is accelerating carrier orders for methanol-capable tonnage, creating demand for specialized project cargo forwarding and port infrastructure coordination.
- E-commerce fulfillment consolidation:Direct-to-consumer brands are pooling fragmented volumes into consolidated ocean freight blocks, expanding forwarder revenue from mid-market shippers previously priced out of FCL contracts.
- Pharmaceutical cold-chain expansion:Temperature-validated reefer services for biologics and vaccines are commanding premium rates as healthcare manufacturers diversify sourcing across multiple production geographies.
Market Restraints
- Bunker fuel cost volatility:Low-sulfur marine gas oil prices swing with crude benchmarks, eroding forwarder contract profitability when carrier surcharges lag spot market movements.
- Carrier alliance concentration:Three vessel-sharing agreements control over 80% of transpacific capacity, limiting forwarder negotiating leverage and contract flexibility.
- Port infrastructure bottlenecks:Terminal automation delays at Los Angeles and Long Beach extend dwell times, inflating demurrage exposure and working capital requirements.
Strategic Opportunities
- Vietnam manufacturing corridor expansion:New container terminals at Cai Mep-Thi Vai are capturing electronics and textile volumes diverting from traditional Chinese load ports.
- Digital freight platform integration:API-connected booking systems are collapsing quote-to-cargo cycles from days to hours, enabling forwarders to capture spot market share from legacy broker networks.
- EU Green Deal compliance services:Carbon footprint verification and emissions reporting tools are emerging as billable advisory offerings for shippers facing CSRD disclosure requirements.
Industry Challenges
- Customs harmonization complexity:Divergent advance manifest filing deadlines between US CBP, EU ICS2, and China GACC force forwarders to maintain redundant compliance teams and technology stacks.
- Reefer technician scarcity:Certified cold-chain engineers capable of validating pharmaceutical temperature excursions command salaries exceeding general logistics roles by 40%, constraining service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocean Freight Forwarding Market |
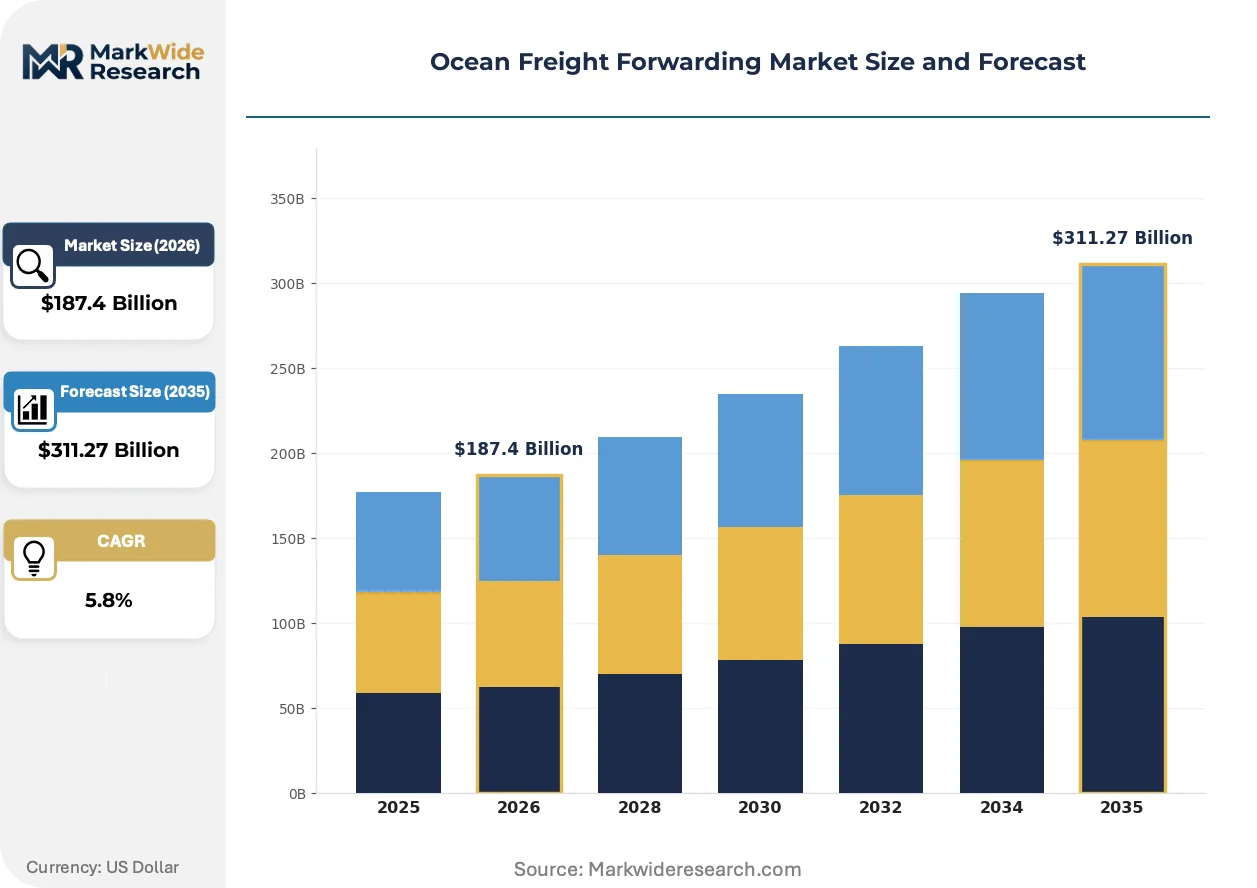
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consolidation, Documentation, Customs Clearance, Warehousing Container Type: Dry Container, Reefer Container, Flat Rack, Open-Top Container Shipping Mode: Full Container Load, Less than Container Load, Break Bulk, Roll-On/Roll-Off End User: E-commerce, Retail, Manufacturing, Agriculture |
| Companies Covered | DSV Global Transport and Logistics, DB Schenker, Sinotrans, Expeditors International, Nippon Express, Kuehne + Nagel, CEVA Logistics, LX Pantos, DHL Global Forwarding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocean Freight Forwarding Market Trends and Innovations
Digitalization is compressing traditional forwarding workflows while regulatory pressure and buyer behavior shifts are fragmenting legacy service models into specialized, technology-enabled offerings.
Blockchain-enabled bill-of-lading platforms are overtaking paper documentation for high-value cargo flows. Pharmaceutical shippers and automotive manufacturers are piloting smart contracts for automatic release upon IoT-verified delivery confirmation. This distributed ledger infrastructure is compressing dispute resolution cycles from weeks to hours while reducing fraud exposure in letter-of-credit transactions.
REACH chemical registration requirements in the European Union are forcing forwarders to expand hazardous materials classification capabilities. The regulation mandates detailed substance data for containerized chemical shipments, compelling logistics providers to hire certified dangerous goods specialists or cede this cargo to chemical-industry captive forwarders. Pharmaceutical and specialty chemical lanes into Rotterdam and Hamburg are seeing the most pronounced compliance-driven vendor switching.
Shippers are unbundling freight management from customs brokerage, selecting specialized providers for each function rather than accepting bundled forwarder packages. Large retail importers are building in-house ocean procurement teams while outsourcing only documentation and compliance to third parties. This disintermediation is most advanced among North American apparel brands with direct factory relationships in Bangladesh and Vietnam.
Ocean Freight Forwarding Market Segmentation
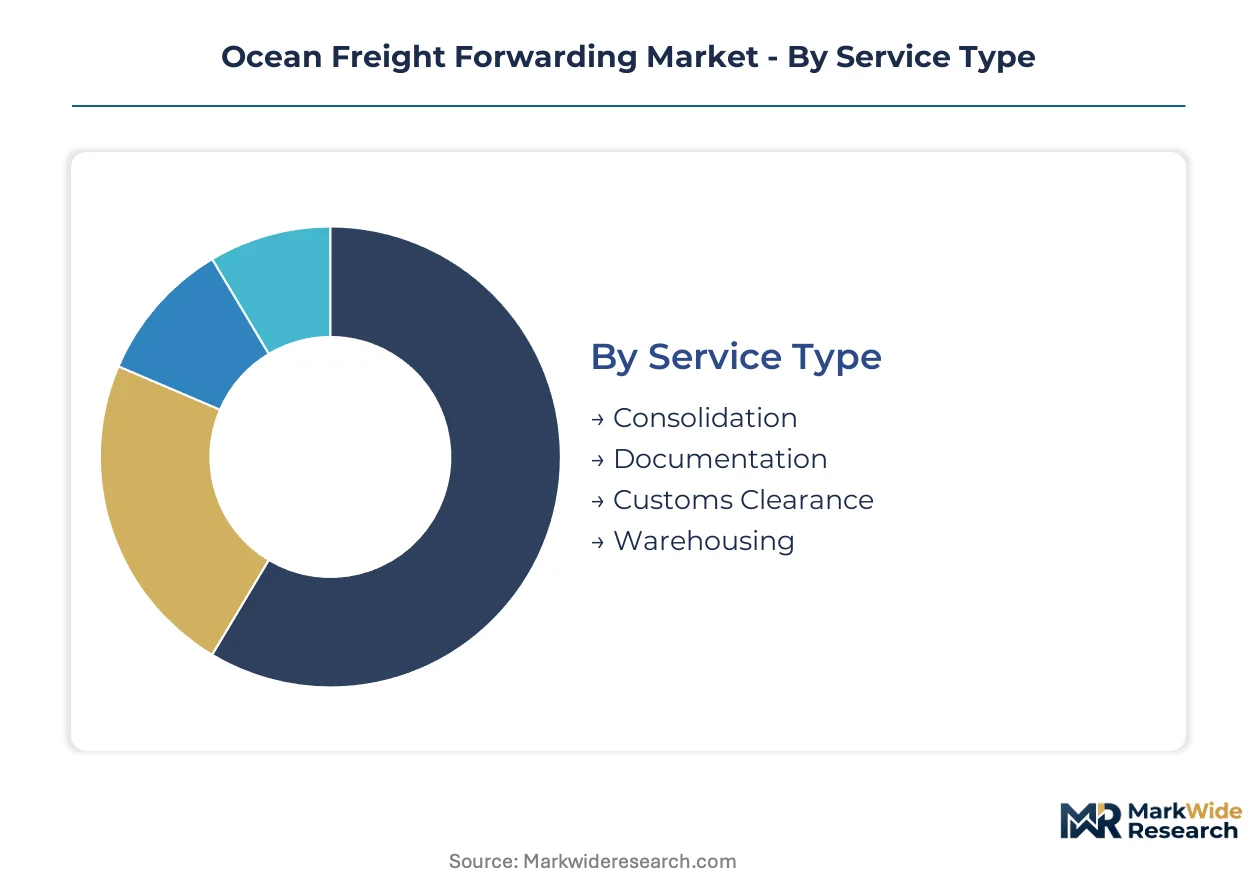
Ocean freight forwarding segments reflect distinct operational capabilities, capital intensity, and margin profiles. Shippers select service tiers based on cargo characteristics, regulatory complexity, and supply chain velocity requirements rather than price alone.
Service Type:
Forwarders upgrade service portfolios as vessel operators retrofit fleets for IMO carbon intensity compliance, extending transit times and amplifying demand for documentation precision.
- Consolidation:Combines fragmented shipper volumes into economically viable container lots through feeder vessel coordination and deconsolidation at destination ports. Demand concentrates among mid-market e-commerce brands pooling shipments from Shenzhen and Ho Chi Minh City toward Los Angeles, driven by direct-to-consumer brands bypassing traditional retail distribution.
- Documentation:Manages bills of lading, certificates of origin, and letter-of-credit compliance across divergent national filing protocols. Procurement teams at German automotive manufacturers are unbundling this function from bundled forwarder packages, selecting specialized documentation providers with blockchain-enabled platforms.
- Customs Clearance:Navigates advance manifest filing deadlines imposed by US CBP, EU ICS2, and China GACC security screening requirements.
- Warehousing:Provides bonded storage and cross-dock facilities at transshipment hubs, with state-backed operators dominating port-adjacent real estate in Asia.
Consolidation sits at the top of the volume ranking, with Documentation climbing the fastest as shippers unbundle compliance from freight management.
Container Type:
Container selection determines thermal management capabilities, out-of-gauge handling requirements, and per-unit slot cost economics across trade lanes.
- Dry Container:Standard twenty-foot and forty-foot boxes handle non-perishable manufactured goods, electronics, and textiles across 90% of ocean freight volume. Electronics exporters from Vietnam's Cai Mep-Thi Vai corridor are expanding dry container commitments as manufacturing shifts from traditional Chinese load ports.
- Reefer Container:Temperature-controlled units maintain pharmaceutical and perishable cargo integrity through integrated genset power and remote monitoring. Biologics manufacturers are diversifying production across multiple geographies, amplifying demand for certified cold-chain validation at Rotterdam and Singapore transshipment hubs.
- Flat Rack:Collapsible side walls accommodate out-of-gauge machinery, project cargo, and heavy industrial equipment.
- Open-Top Container:Removable tarpaulin roofs enable top-loading of bulk commodities and tall cargo exceeding standard door heights.
Dry Container generates the highest absolute volume, with Reefer Container expanding most quickly on pharmaceutical cold-chain diversification.
Shipping Mode:
Mode selection balances cargo density, schedule reliability, and carrier contract leverage against inventory carrying costs and working capital constraints.
- Full Container Load:Direct shipper-carrier contracts for exclusive container use, capturing dominant value through lower per-unit handling overhead and priority stowage. North American apparel brands with direct factory relationships in Bangladesh are building in-house FCL procurement teams while outsourcing documentation functions.
- Less than Container Load:Forwarder-consolidated volumes sharing container space, competing on sailing frequency and deconsolidation velocity. Mid-market direct-to-consumer brands previously priced out of FCL contracts are pooling fragmented volumes into consolidated ocean freight blocks.
- Break Bulk:Individual pieces of cargo loaded separately rather than containerized, serving project cargo and oversized industrial shipments.
- Roll-On/Roll-Off:Wheeled cargo driven onto specialized vessel decks, dominating automotive and heavy equipment movements.
Full Container Load commands the largest revenue pool, with Less than Container Load gaining share fastest among e-commerce fulfillment networks.
End User:
End-user verticals impose distinct service requirements around velocity, compliance documentation, and seasonal volume volatility.
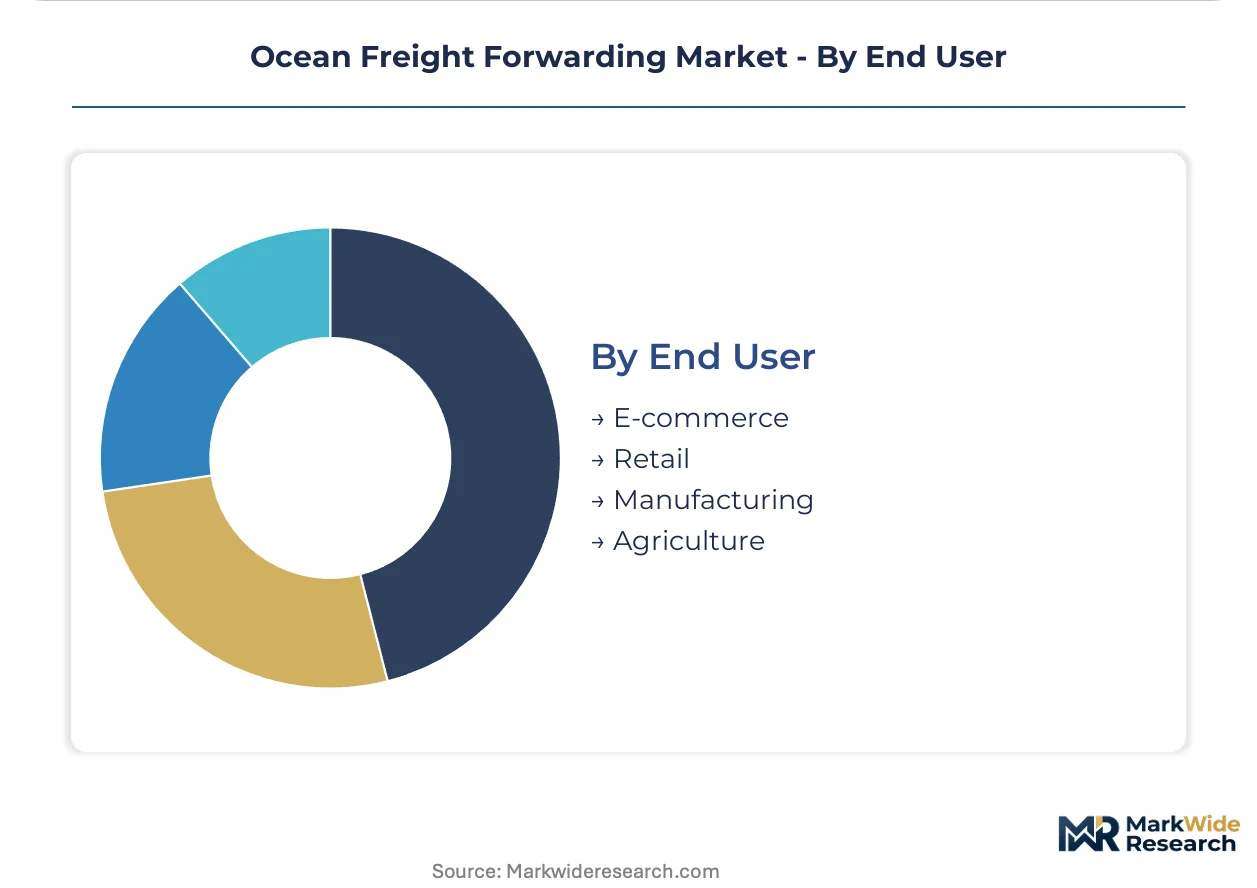
- E-commerce:Direct-to-consumer fulfillment networks requiring consolidated ocean blocks, last-mile deconsolidation, and returns logistics infrastructure. Platforms are expanding reliance on consolidated ocean freight services as air cargo rates compress margins on cross-border parcels.
- Retail:Seasonal inventory replenishment with strict landed-cost targets and promotional calendar alignment. Large importers are unbundling freight management from customs brokerage, selecting specialized providers for each function.
- Manufacturing:Just-in-time component flows and project cargo coordination for capital equipment installation.
- Agriculture:Perishable commodity movements with harvest-window timing and phytosanitary certification requirements.
Manufacturing anchors absolute volume throughput, with E-commerce expanding most quickly on fulfillment network globalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China processes higher container throughput than any other nation, yet Vietnam's Cai Mep-Thi Vai corridor is capturing electronics volumes that previously moved through Shanghai and Shenzhen. Carrier alliance networks and IMO carbon regulations are reshaping route economics across every major trade lane.
United States
Transpacific import demand from Los Angeles and Long Beach drives carrier capacity allocation decisions. US CBP enforces 24-hour advance manifest filing deadlines through its Automated Targeting System. Retail importers in the Southeast are building regional distribution centers near Savannah and Charleston to bypass West Coast congestion.
China
State-backed port operators dominate bonded warehousing and intra-Asia feeder coordination. MEE dual carbon goals are accelerating methanol-fuel terminal infrastructure at Ningbo-Zhoushan. Manufacturing clusters in the Pearl River Delta are diversifying final assembly toward Vietnam while maintaining component sourcing through Shenzhen.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg unbundle documentation from bundled forwarder packages. ECHA REACH compliance mandates detailed substance data for chemical container shipments. Hamburg's container terminal operators are investing in shore power infrastructure for IMO-aligned vessel calls.
Vietnam
Electronics exporters from Ho Chi Minh City and Binh Duong province are expanding dry container commitments as manufacturing shifts from China. The country's national shipping regulator coordinates with IMO frameworks on carbon intensity reporting. Cai Mep-Thi Vai terminal expansions are capturing textile and consumer electronics volumes with direct transpacific sailings.
Singapore
Pharmaceutical reefer transshipment commands premium margins at PSA terminals with certified cold-chain validation. The Maritime and Port Authority aligns national regulations with IMO carbon intensity indicators. Biologics manufacturers are diversifying production geography, amplifying demand for temperature-validated container handling at the city-state's hub facilities.
Ocean Freight Forwarding Market Competitive Landscape
European logistics conglomerates anchor the premium service tier; Asia-Pacific specialists hold volume positions through state-affiliated port access. Three vessel-sharing agreements control over 80% of transpacific capacity, compressing forwarder negotiating leverage. Strategic archetypes include integrated air-sea platform operators, pharmaceutical cold-chain validators, and bonded warehousing network controllers. Competitive moves concentrate on digital freight platform integration and project cargo coordination in emerging manufacturing corridors.
Among European-based forwarders, Kuehne + Nagel and DB Schenker occupy positions within the premium documentation and compliance tier. DSV Global Transport and Logistics exemplifies the integrated air-sea platform archetype through its project cargo capabilities. Sinotrans anchors the state-backed port access segment with bonded warehousing network dominance. These three represent distinct strategic positioning vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| DSV Global Transport and Logistics |
| DB Schenker |
| Sinotrans |
| Expeditors International |
| Nippon Express |
| Kuehne + Nagel |
| CEVA Logistics |
| LX Pantos |
| DHL Global Forwarding |
| Others |
Pricing and Supply Chain Analysis
IMO carbon intensity indicator ratings gate qualified vessel supply and premium-tier pricing access, compressing forwarder margins on non-compliant routings while rewarding certified low-emission services with rate premiums. Shippers face bifurcated procurement economics where validated green-lane contracts command sustained price elevation against volatile spot-market alternatives.
Pricing Analysis
Capacity additions in Vietnam's Cai Mep-Thi Vai corridor are reshaping price floors on Asia-North America sailings, introducing competitive tension against legacy Chinese load-port premiums. Contract-based long-term offtake dominates, with price differentiation driven by IMO compliance certification and volume scale commitments. Cost compression in standard-tier services is intensifying because carrier alliance concentration limits forwarder negotiating leverage. Mid-market direct-to-consumer brands exhibit highest price sensitivity, while pharmaceutical shippers with cold-chain requirements demonstrate lowest elasticity.
Supply Chain Analysis
Workforce scarcity for certified reefer technicians in Vietnam, Bangladesh, and China's Pearl River Delta constrains service expansion at transshipment hubs. Supply concentrates in China, Vietnam, and Singapore, with container manufacturing and vessel procurement drawing from steel, genset power units, and specialized coatings. Single-source vulnerability runs through concentrated carrier alliance networks controlling transpacific slot allocation. Distribution runs through bonded warehousing networks at port-adjacent facilities, with state-backed operators dominating Asian hub real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ocean freight forwarding operates as a regulatory compounder where IMO net-zero deadlines and carbon intensity enforcement are accelerating carrier fleet turnover and forwarder technology investment cycles.
For Market Incumbents: Cement dominance in pharmaceutical reefer forwarding through certified cold-chain infrastructure investment at Rotterdam and Singapore hubs. Deepen backward integration into bonded warehousing networks across Vietnam's manufacturing corridor to capture electronics volume diversion from China. Defend against digital-native freight platforms by accelerating API-connected booking system deployment.
For New Entrants and Emerging Players: Digital freight matching platforms offer technology-first wedge opportunity, collapsing quote-to-cargo cycles from days to hours. Target mid-market e-commerce consolidation services between Ho Chi Minh City and Los Angeles, where incumbent forwarders maintain legacy cost structures. Pursue EU Green Deal compliance advisory as billable service entry point, leveraging emissions reporting tools for CSRD-aligned shippers.
For Investors and Strategic Acquirers: Roll-up economics work for regional documentation specialists because customs harmonization complexity forces redundant compliance technology investments across fragmented forwarder networks. Five-to-ten year viability favors consolidators with integrated air-sea capabilities and project cargo coordination expertise. Monitor carrier alliance restructuring announcements as inflection signal for stranded capacity risk and rerouting surcharge exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Vessel Procurement | IMO methanol-capable tonnage mandates redirect carrier capital toward compliant fleet renewal. |
| Digital Platform Integration | API-connected booking systems collapse procurement cycles and capture spot-market share from legacy brokers. |
| Cold-Chain Infrastructure Expansion | Certified pharmaceutical reefer validation at Singapore and Rotterdam commands sustained premium pricing. |
| Vietnam Corridor Capacity Buildout | Cai Mep-Thi Vai terminal expansions capture electronics volumes diverting from Chinese load ports. |
| EU Compliance Service Development | Carbon footprint verification tools address CSRD disclosure requirements for European importer clients. |
Research Methodology
Multiple input streams — carrier procurement executives, forwarder operations directors, shipper supply chain managers, and port terminal operators — were reconciled against customs filing databases, IMO regulatory filings, and vessel charter rate indices. Primary interviews with pharmaceutical logistics leads and e-commerce fulfillment planners were validated through secondary analysis of carrier alliance capacity announcements and bonded warehousing network disclosures. Bottom-up volume modeling and top-down trade-flow triangulation were cross-referenced for convergence.
Historical throughput patterns at Los Angeles, Long Beach, Shanghai, and Rotterdam were cross-referenced against panel input from carrier network planners and freight rate negotiators. Segmentation dimensions modeled include service type, container category, shipping mode, and end-user vertical across the projection horizon. CAGRs were derived from trade-lane volume trajectories and carrier capacity deployment schedules, with fuel cost volatility and regulatory compliance timelines incorporated as scenario inputs.
The model holds under sustained IMO enforcement and gradual fleet retrofitting; deviation in carbon pricing acceleration or alliance dissolution would shift capacity allocation assumptions. Forecasts reflect documented base conditions around carrier procurement cycles and forwarder technology adoption curves. Material deviation in bunker fuel cost trajectories or customs harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Last Mile Delivery Transportation Market