
 Morocco Freight and Logistics Market | 2026-2036
Morocco Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Freight and Logistics Market Foresight
Aftermarket service revenue is fragmenting across Morocco's freight corridors as shippers unbundle port handling from inland distribution. DHL Express Maroc leverages its Casablanca hub to control express last-mile networks. Timar anchors domestic land freight through its extensive Moroccan road fleet. SEKO Logistics Morocco differentiates via specialized e-commerce fulfillment for European fashion brands.
Morocco freight and logistics encompasses the planning, execution, and control of goods movement across road, sea, air, and intermodal networks, typically involving containerized cargo handling at temperatures between minus 25 and plus 25 degrees Celsius for temperature-sensitive flows. Its primary commercial purpose is reducing dwell time and inventory carrying costs for manufacturers and retailers operating between Europe and West Africa. Land freight dominates volume throughput on the Tangier-Casablanca-Agadir axis, while express delivery records the fastest expansion as Moroccan e-commerce platforms scale cross-border fulfillment. Third-party logistics captures the deepest margin pools by consolidating fragmented shipper demand into shared warehousing and transport assets.
Morocco's national customs administration operates the PortNet electronic single-window, while the country's transport ministry enforces axle-load regulations and driver hour limits on international road corridors. These frameworks shape market access by mandating real-time cargo tracking and digital customs pre-clearance for all containerized imports. Stakeholders must monitor how forthcoming sustainability mandates from European trading partners will reshape fuel and emissions standards for Moroccan fleet operators serving EU-bound routes.
Market Dynamics
PortNet single-window digitization is compressing customs clearance cycles from days to hours, forcing freight operators to rewire their operational cadence around real-time data flows rather than document-based batch processing.
Growth Catalysts
- Automotive just-in-time mandates:Tangier-Med zone manufacturers now require synchronized parts delivery windows measured in hours, pulling specialized contract logistics investment into the northern corridor.
- EU Green Deal compliance pressure:European supermarket chains sourcing Moroccan produce are demanding auditable cold-chain carbon footprints, accelerating reefer fleet renewal and solar-powered warehouse deployment.
- PortNet pre-clearance protocols:Morocco's customs administration mandates digital cargo manifests 24 hours pre-arrival, eliminating physical inspection bottlenecks at Casablanca and Agadir terminals.
Market Restraints
- Refrigerant input cost volatility:EU F-Gas Regulation phase-downs are spiking hydrofluorocarbon prices for Moroccan reefer operators, squeezing margins on agri-export routes.
- Axle-load enforcement fragmentation:Morocco's transport ministry applies divergent weight limits across Casablanca-Settat versus Marrakech-Safi corridors, complicating fleet standardization for national carriers.
- Driver hour compliance gaps:International road corridor regulations lack real-time tachograph integration with domestic enforcement systems, creating liability exposure on EU-bound routes.
Strategic Opportunities
- E-commerce fulfillment infrastructure:Cross-border fashion platforms are unbundling European warehousing from last-mile Moroccan delivery, creating demand for Casablanca-based bonded sorting centers.
- Agri-export corridor densification:Souss-Massa citrus and berry producers are consolidating around shared cold-chain pooling models, opening multi-user temperature-controlled facilities in Chtouka Aït Baha.
- Renewable-powered fleet conversion:Morocco's solar and wind generation capacity is enabling electric truck pilot programs on the Tangier-Casablanca highway, aligning with EU CBAM border carbon adjustments.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems from disparate OEMs resist unified API connectivity with PortNet tracking mandates, forcing middleware development costs onto mid-sized operators.
- Certified reefer technician scarcity:Advanced temperature-control maintenance skills concentrate in Casablanca and Tangier, leaving Agadir and Laâyoune operators dependent on fly-in specialist contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Freight and Logistics Market |
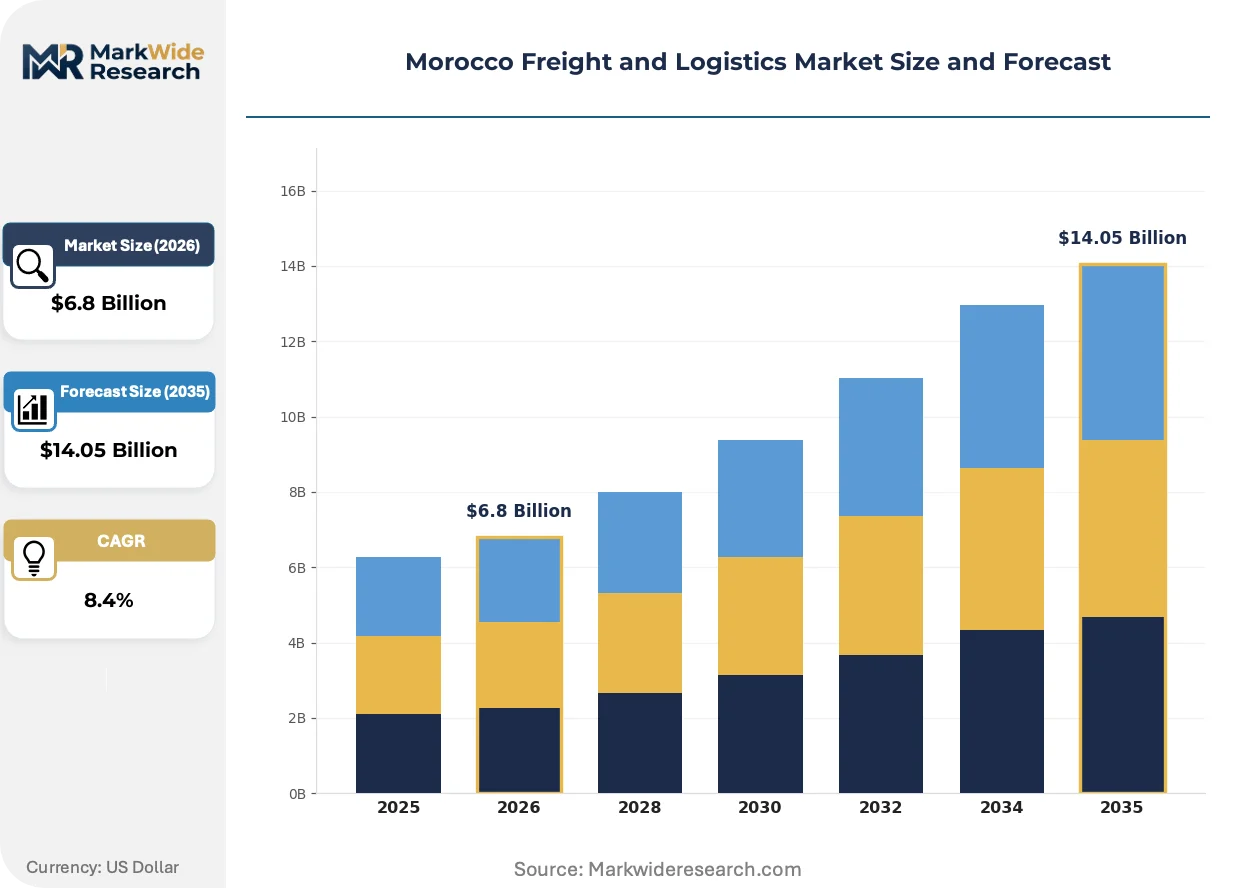
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Land Freight, Sea Freight, Air Freight, Express Delivery Client Type: Manufacturers, Retailers, E-commerce, Wholesalers Logistics Solution: Third-Party Logistics, Fourth-Party Logistics, Supply Chain Management, Transportation Management Technology: Warehouse Management Systems, Fleet Management Software, Tracking Solutions, Robotics |
| Companies Covered | Rhenus Logistics, Open Sky Logistics, SNTL Group, Transglory, JAZ Marine, DHL Express Maroc, SEKO Logistics Morocco, Shine Line International Shipping Morocco, Timar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Freight and Logistics Market Shifts & Advancements
Digitization is collapsing the information lag between port gates and inland distribution nodes, enabling synchronous coordination previously impossible under paper-based clearance regimes.
Blockchain-enabled cargo documentation is virtualizing bill-of-lading transfer and customs declaration workflows. Moroccan citrus exporters and European supermarket procurement teams are piloting distributed-ledger traceability to eliminate duplicate paper handling. This virtualization is compressing title transfer latency from days to minutes, enabling just-in-time produce loading directly from packing stations to reefer vessels.
EU CSRD sustainability reporting mandates are forcing Moroccan logistics providers to deploy emissions monitoring hardware across their fleets. The directive requires scope-three disclosure from EU-headquartered retailers sourcing Moroccan goods. Agri-export cold-chain operators serving Carrefour and Auchan procurement networks are responding by retrofitting telematics with fuel-consumption analytics and refrigerant leak detection sensors.
Shippers are unbundling port handling from inland distribution contracts, fragmenting vendor relationships that previously consolidated under single 3PL agreements. Moroccan garment manufacturers exporting to Zara and H&M are now sourcing drayage, warehousing, and express last-mile as separate procurement categories. This pattern is most visible in Casablanca-Settat, where specialized e-commerce fulfillment providers are displacing traditional freight forwarders on fashion-forward delivery lanes.
Morocco Freight and Logistics Market Segmentation
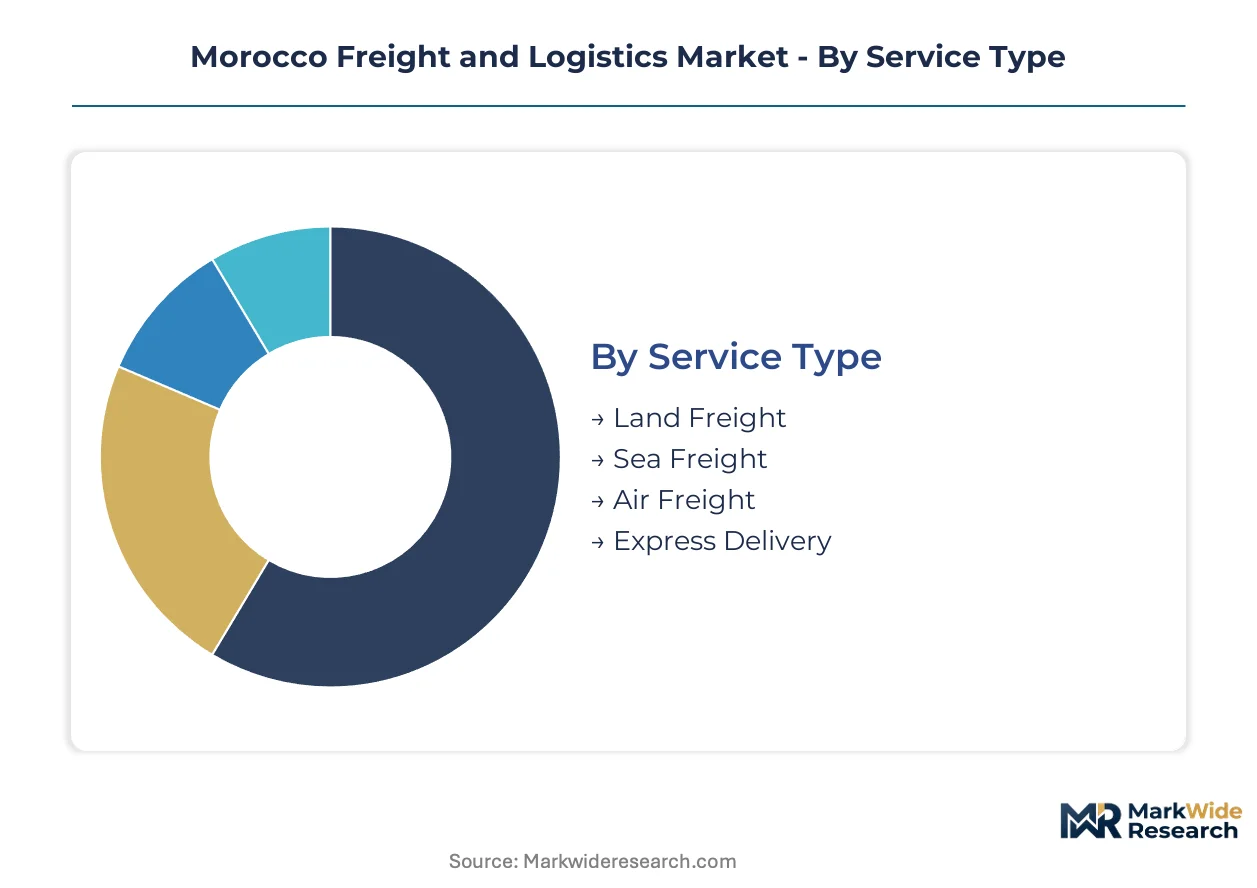
Freight and logistics segmentation in Morocco reveals how service intensity, client sophistication, and technology adoption create distinct margin pools across the Tangier-Casablanca-Agadir corridor. Each dimension shapes capital deployment and operational cadence differently for operators navigating PortNet digitization mandates.
Service Type:
After-sales service intensity varies sharply across transport modes, with scheduled maintenance contracts and real-time exception handling defining profitability tiers.
- Land Freight:Road haulage commands volume leadership through heavy-duty fleets operating on the Tangier-Casablanca-Agadir axis. Demand concentrates among automotive manufacturers at Tangier-Med requiring synchronized just-in-time parts delivery measured in hours, pulling specialized contract logistics investment northward.
- Sea Freight:Containerized cargo handling at Casablanca and Agadir terminals dominates value throughput for agri-export corridors serving European supermarkets. PortNet pre-clearance protocols now mandate digital manifests 24 hours pre-arrival, eliminating physical inspection bottlenecks and compressing dwell time.
- Air Freight:Temperature-sensitive pharmaceuticals and high-value electronics move through Mohammed V International, with perishables requiring minus 25 to plus 25 degrees Celsius control.
- Express Delivery:Cross-border e-commerce platforms are scaling last-mile networks fastest, with Casablanca-based bonded sorting centers capturing unbundled procurement from European fashion brands.
By volume, Land Freight leads. By growth pace, Express Delivery is expanding most quickly.
Client Type:
Cost tier differentiation separates capital-intensive manufacturers from margin-sensitive retailers, with procurement sophistication determining logistics provider selection criteria.
- Manufacturers:Automotive and electronics producers at Tangier-Med and Casablanca-Settat anchor demand for synchronized inbound parts logistics and outbound finished goods distribution.
- Retailers:European supermarket chains sourcing Moroccan produce demand auditable cold-chain carbon footprints under EU Green Deal compliance pressure, accelerating reefer fleet renewal.
- E-commerce:Cross-border fashion platforms are unbundling European warehousing from Moroccan last-mile delivery, creating demand for specialized fulfillment infrastructure.
- Wholesalers:Traditional distribution intermediaries in Marrakech-Safi and Fès-Meknès corridors consolidate fragmented agricultural and consumer goods flows.
Manufacturers generate the highest contract values. E-commerce clients are climbing the fastest as procurement unbundling accelerates.
Logistics Solution:
Margin concentration tracks asset ownership depth, with integrated control over warehousing and transport yielding superior returns than brokerage-style arrangements.
- Third-Party Logistics:Asset-heavy providers consolidate fragmented shipper demand into shared warehousing and transport assets, capturing the deepest margin pools through multi-user facility economics.
- Fourth-Party Logistics:Non-asset integrators orchestrate complex supply chains for multinational manufacturers, with demand concentrating among automotive OEMs requiring end-to-end visibility.
- Supply Chain Management:Strategic consulting and network optimization services target mid-sized exporters seeking PortNet compliance and EU CBAM readiness.
- Transportation Management:Software-enabled freight brokerage and route optimization serve spot-market shippers on the Casablanca-Agadir corridor.
Third-Party Logistics holds the largest revenue base. Fourth-Party Logistics is gaining share fastest as manufacturers outsource strategic network design.
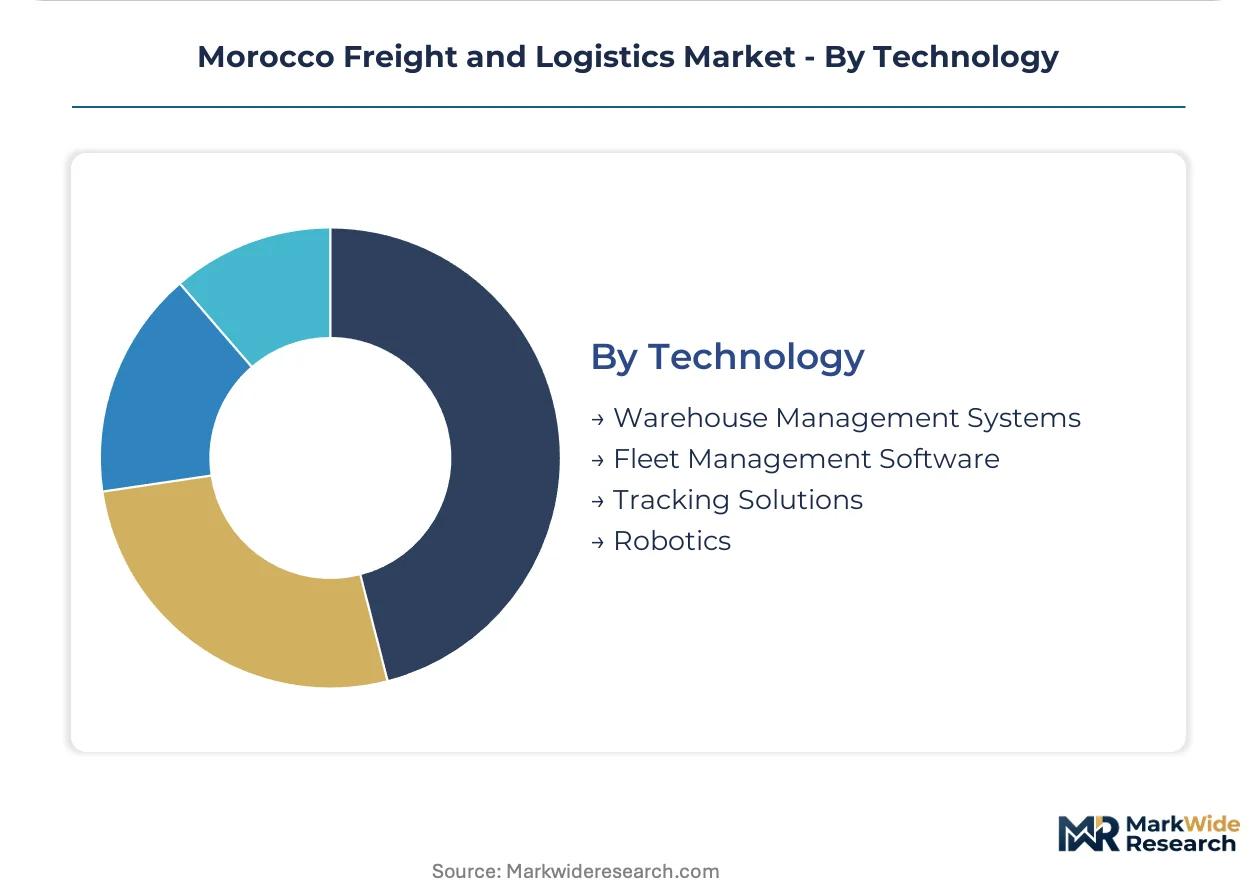
Technology:
Supply concentration in Casablanca and Tangier shapes technology adoption geography, with legacy system integration costs burdening mid-sized operators outside these clusters.
- Warehouse Management Systems:Real-time inventory control and order fulfillment automation serve e-commerce fulfillment centers and agri-export cold storage facilities.
- Fleet Management Software:Telematics integration with PortNet tracking mandates faces complexity from disparate OEM legacy systems, forcing middleware development costs onto operators.
- Tracking Solutions:GPS and RFID cargo monitoring enables synchronous coordination between port gates and inland distribution nodes under digitized clearance regimes.
- Robotics:Automated picking and sorting systems pilot in Casablanca-Settat bonded warehouses serving cross-border fashion fulfillment.
Warehouse Management Systems dominate current deployment. Robotics is expanding most quickly as labor costs rise in urban fulfillment centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shippers along the Tangier-Casablanca corridor demonstrate the least price elasticity, absorbing premium rates for synchronized automotive parts delivery, while agri-exporters in Souss-Massa operate on thinner margins where transport costs directly determine European supermarket contract viability.
Tangier-Tetouan-Al Hoceima
Tangier-Med automotive manufacturers demand just-in-time parts logistics measured in hours, not days. PortNet pre-clearance protocols from Morocco's customs administration mandate digital manifests 24 hours pre-arrival. Renault and Stellantis supplier parks cluster around the port complex, pulling specialized contract logistics investment into reefer warehousing and synchronized inbound distribution.
Casablanca-Settat
European fashion brands unbundle warehousing from Moroccan last-mile delivery, creating demand for bonded sorting centers. The transport ministry enforces axle-load regulations and driver hour limits on international road corridors. Mohammedia and Casablanca terminals handle containerized agri-exports requiring minus 25 to plus 25 degrees Celsius control for European supermarket chains.
Marrakech-Safi
Pharmaceutical manufacturers and citrus consolidators compete for reefer capacity on EU-bound routes. Divergent weight limits across Casablanca-Settat versus Marrakech-Safi corridors complicate fleet standardization for national carriers. Chichaoua and Safi serve as transshipment nodes where mid-sized operators face middleware development costs for PortNet telematics integration.
Souss-Massa
Citrus and berry producers consolidate around shared cold-chain pooling models to offset refrigerant cost volatility from EU F-Gas Regulation phase-downs. Chtouka Aït Baha hosts multi-user temperature-controlled facilities where solar-powered warehouse deployment accelerates under EU Green Deal compliance pressure. Fly-in reefer technician contracts from Casablanca burden operators during peak harvest windows.
Laâyoune-Sakia El Hamra
Fisheries and phosphate logistics generate bulk cargo flows with lower service intensity requirements. Real-time tachograph integration gaps with domestic enforcement systems create liability exposure on EU-bound routes. Dakhla port expansion targets trans-African corridor development, though certified cold-chain maintenance skills remain concentrated in northern urban centers.
Morocco Freight and Logistics Market Competitive Landscape
Capability concentration sits with specialized contract logistics providers mastering PortNet digitization and automotive just-in-time protocols; scale advantage sits with diversified freight conglomerates controlling national road fleets and bonded warehousing networks. The market structures around three archetypes: asset-heavy 3PL operators consolidating fragmented shipper demand, express delivery specialists capturing e-commerce fulfillment growth, and maritime-forwarding hybrids linking Tangier-Med to European distribution hubs. Dominant competitive moves include fleet renewal for EU CBAM alignment and middleware development to bridge legacy telematics with customs tracking mandates.
Within the diversified conglomerate tier, Timar anchors domestic land freight through its extensive Moroccan road fleet, while DHL Express Maroc leverages its Casablanca hub to control express last-mile networks. SEKO Logistics Morocco occupies a position among specialized fulfillment providers differentiating via e-commerce infrastructure for European fashion brands. These three exemplify how geographic footprint breadth and service vertical depth determine competitive positioning under PortNet digitization.
| Leading Market Players |
|---|
| Rhenus Logistics |
| Open Sky Logistics |
| SNTL Group |
| Transglory |
| JAZ Marine |
| DHL Express Maroc |
| SEKO Logistics Morocco |
| Shine Line International Shipping Morocco |
| Timar |
| Others |
Supply & Pricing Matrix
Tangier-Med port capacity expansion is compressing dwell-time premiums and redistributing pricing power toward inland distribution operators controlling bonded warehousing networks. PortNet digitization has collapsed customs clearance margins, forcing freight providers to capture value through synchronized automotive parts delivery and cold-chain service tiers rather than document-handling arbitrage.
Pricing Analysis
After-sales service contracts for reefer fleet maintenance generate lifetime value multiples exceeding transactional freight rates by binding agri-exporters to multi-year technical support agreements. Three-tier pricing structure across premium, standard, and economy levels separates synchronized just-in-time automotive logistics from spot-market agri-export haulage and wholesale consolidation services. Pricing pressure stems from EU F-Gas Regulation phase-downs spiking refrigerant input costs for temperature-controlled operators. E-commerce fashion platforms exhibit lowest price sensitivity, absorbing premium rates for Casablanca-based bonded sorting, while Souss-Massa citrus consolidators face margin compression where transport costs determine European supermarket contract viability.
Supply Chain Analysis
Upstream feedstock for Morocco's logistics fleet centers on European and Asian OEM supply chains for reefer units, telematics hardware, and electric truck powertrains. Diesel and refrigerant inputs draw from regional refining capacity in Spain and Saudi Arabia, while solar panel arrays for warehouse power feed from Chinese manufacturing clusters. Single-source vulnerability concentrates in advanced temperature-control compressors sourced from German and Japanese suppliers. Distribution runs through hub-and-spoke networks anchored at Casablanca-Settat bonded facilities, with spoke density thinning toward Laâyoune-Sakia El Hamra corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward European supermarket procurement teams and automotive OEMs as shipper consolidation around Tangier-Med and Casablanca-Settat reduces fragmentation. This concentration demands auditable carbon footprints and real-time visibility, squeezing mid-sized operators lacking PortNet integration depth.
For Market Incumbents: Pre-empt margin erosion by securing exclusive reefer technician training partnerships with Casablanca technical institutes before fly-in specialist costs peak during harvest windows. Backward integration into solar-powered warehouse assets locks in energy cost advantages under EU CBAM border adjustments. DHL Express Maroc and Timar demonstrate how national fleet scale combined with customs digitization mastery defends position against regional challengers. For New Entrants and Emerging Players: Mid-sized e-commerce fulfillment gaps in Marrakech-Safi and Fès-Meknès represent the most penetrable entry point, where European fashion brands seek alternatives to Casablanca-Settat congestion. Agri-export corridor densification in Chtouka Aït Baha offers second-mover advantage through shared cold-chain pooling models. Go-to-market positioning should lead with PortNet pre-clearance certification and EU Green Deal compliance tooling rather than rate undercutting. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized contract logistics providers mastering automotive just-in-time protocols and temperature-controlled agri-export corridors. Long-term viability across the analysis window favors asset-heavy 3PL operators with captive warehousing networks over freight brokerage models exposed to spot-market volatility. Acquisition targets should demonstrate middleware capabilities bridging legacy telematics with customs tracking mandates. The signal to watch is European retailer CSRD disclosure acceleration forcing scope-three emissions accountability onto Moroccan logistics partners.| Strategic Initiative | Industry Significance |
|---|---|
| Reefer Fleet Electrification | Electric truck pilots on Tangier-Casablanca highway align with EU CBAM carbon border adjustments. |
| PortNet Middleware Development | Unified API connectivity resolves telematics fragmentation burdening mid-sized operators outside Casablanca clusters. |
| Solar-Powered Warehouse Deployment | Renewable generation capacity in Chtouka Aït Baha offsets EU Green Deal compliance costs for cold-chain operators. |
| Certified Technician Training Programs | Localized reefer maintenance skills reduce fly-in contract dependency during Souss-Massa peak harvest windows. |
| Bonded Sorting Center Expansion | Casablanca-Settat facilities capture unbundled procurement from cross-border fashion platforms serving Zara and H&M networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs administration protocols, transport ministry enforcement records, and EU regulatory filings to validate PortNet digitization impacts and F-Gas Regulation cost transmission. Primary interviews engaged fleet operations directors at national road carriers, procurement managers at Tangier-Med automotive suppliers, cold-chain logistics heads at agri-export cooperatives, and customs brokerage principals across Casablanca and Agadir terminals. Secondary sources included Morocco's national customs administration PortNet documentation, transport ministry axle-load enforcement circulars, EU CSRD and CBAM regulatory texts, and refrigerated transport OEM technical specifications. Bottom-up service revenue modeling triangulated against top-down corridor throughput estimates.
Forecast inputs incorporate service type segmentation by transport mode, client type differentiation between manufacturers and retailers, logistics solution tiering across 3PL and 4PL models, and technology adoption curves for warehouse management systems and fleet telematics. Volume and value outputs reflect analytical framework application across the projection horizon, with CAGRs derived from trend extrapolation of PortNet clearance acceleration, e-commerce fulfillment infrastructure buildout, and EU sustainability mandate compliance costs. Industry-specific inputs include reefer fleet renewal cycles, solar warehouse deployment timelines, and electric truck pilot program scaling assumptions.
Stress conditions across refrigerant price volatility, axle-load enforcement fragmentation, and driver hour compliance gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PortNet pre-clearance adoption rates, European retailer CSRD disclosure timelines, and Moroccan renewable energy capacity expansion. Quarterly review of EU F-Gas Regulation phase-down schedules, PortNet API integration certification rates, and electric truck pilot performance metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market