
 Europe B2C Legal Services Market | 2026-2036
Europe B2C Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe B2C Legal Services Market Insights
The EU AI Act is rebalancing the cost-of-entry calculus for automated legal advisory platforms entering consumer markets. Linklaters LLP leverages its regulatory expertise to navigate emerging AI governance frameworks for retail legal products. Clifford Chance LLP anchors its B2C expansion through technology-led service design targeting individual clients. DLA Piper competes by extending its digital legal infrastructure across multiple European jurisdictions.
Europe B2C legal services encompass professional advisory and representation delivered directly to individual consumers rather than corporate entities, spanning document automation, dispute resolution, and compliance guidance through both physical and digital channels. The sector relies on licensed practitioner networks, encrypted client portals, and jurisdiction-specific procedural knowledge to resolve matters ranging from tenancy conflicts to inheritance planning. Family law and consumer rights segments lead current service volumes, while subscription engagement models capture the fastest expansion as clients seek predictable cost structures for ongoing legal needs. Pay-per-consultation arrangements retain strong positions in immigration and criminal defense, where matter complexity and episodic demand patterns limit recurring revenue potential.
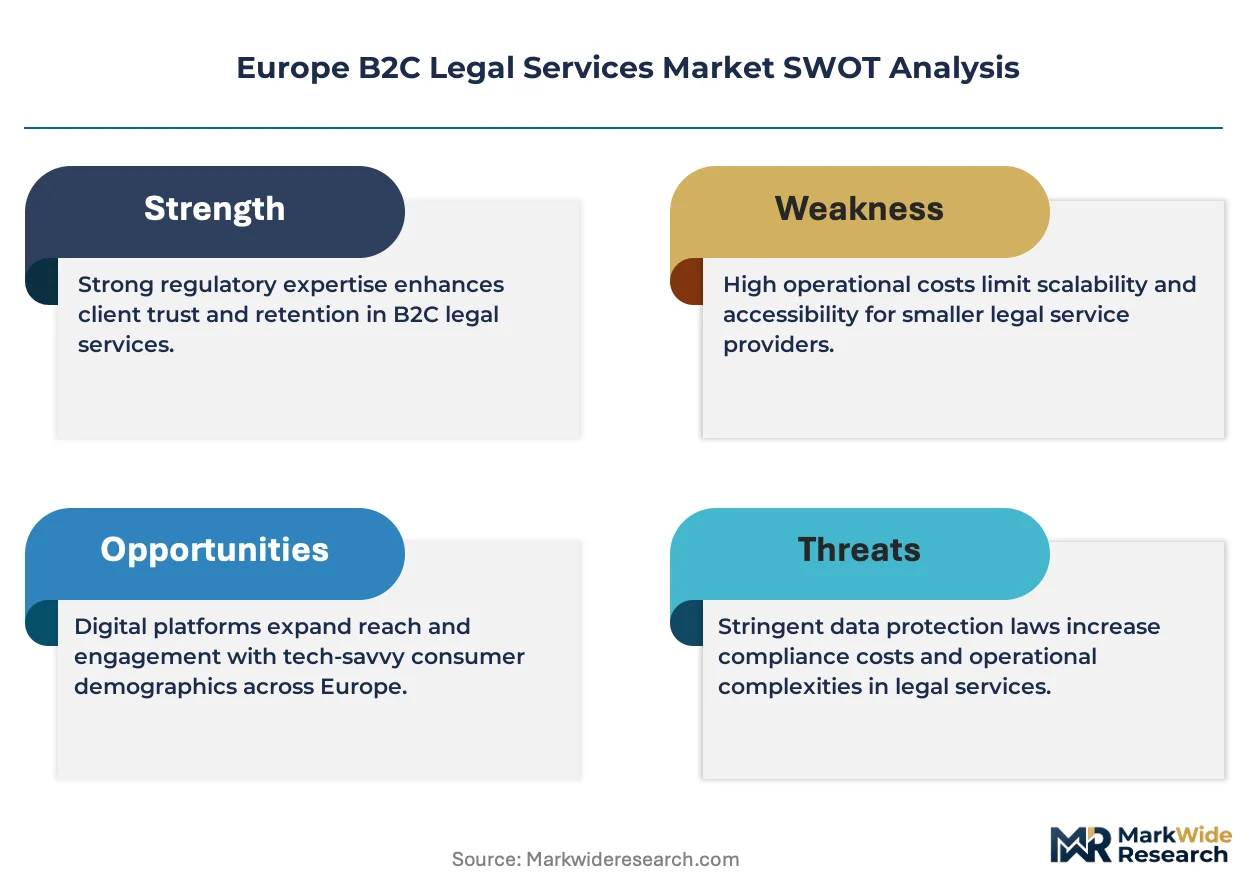
GDPR and the EU AI Act impose strict data handling and algorithmic transparency obligations on firms deploying automated legal tools, while CE marking requirements for certain legal-tech hardware components add compliance layers. EMA and national bar associations across France, Germany, and Italy enforce professional conduct standards that restrict how non-lawyer platforms participate in consumer legal markets. Stakeholders must monitor how regulatory divergence between member states affects cross-border service scalability and platform licensing economics.
Market Dynamics
The EU AI Act is compressing compliance timelines for automated legal advisory platforms while fragmenting licensing requirements across member states. National bar associations in Germany, France, and Italy impose divergent professional conduct standards that reshape platform economics.
Growth Catalysts
- Subscription engagement models:Individual clients in the United Kingdom and Germany favor predictable cost structures for ongoing family law and tenancy matters, displacing traditional hourly billing.
- GDPR-mandated data portability:Consumer rights platforms leverage encrypted client portal requirements to build trust and reduce client acquisition friction.
- CE marking pathways:Legal-tech hardware components gain market access through harmonized conformity assessment, reducing multi-jurisdiction launch costs.
Market Restraints
- Algorithmic transparency mandates:The EU AI Act imposes documentation burdens on machine-learning document automation tools, raising development costs for retail-facing products.
- Licensed practitioner scarcity:Qualified family law specialists concentrate in London, Paris, and Munich, constraining platform scaling in Southern and Eastern Europe.
- Non-lawyer participation caps:French and Italian bar association rules restrict ownership and management roles for technology investors, limiting capital inflows.
Strategic Opportunities
- Cross-border inheritance planning:Mobile EU citizens in Spain and Portugal generate unmet demand for multilingual estate documentation and tax coordination.
- Integration of blockchain verification with smart contracts:Automated will execution and property transfer records reduce notarization bottlenecks in Germany and the Netherlands.
- CSRD-aligned compliance guidance:Individual shareholders and small investors seek accessible interpretation of sustainability disclosure rules affecting their holdings.
Industry Challenges
- Multi-jurisdiction qualification requirements:Platforms serving EU-wide client bases must maintain separate bar admissions or partnership structures in each target country.
- Legacy case management system integration:Established firms in France and Germany face technical debt when connecting encrypted consumer portals to decades-old internal databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe B2C Legal Services Market |
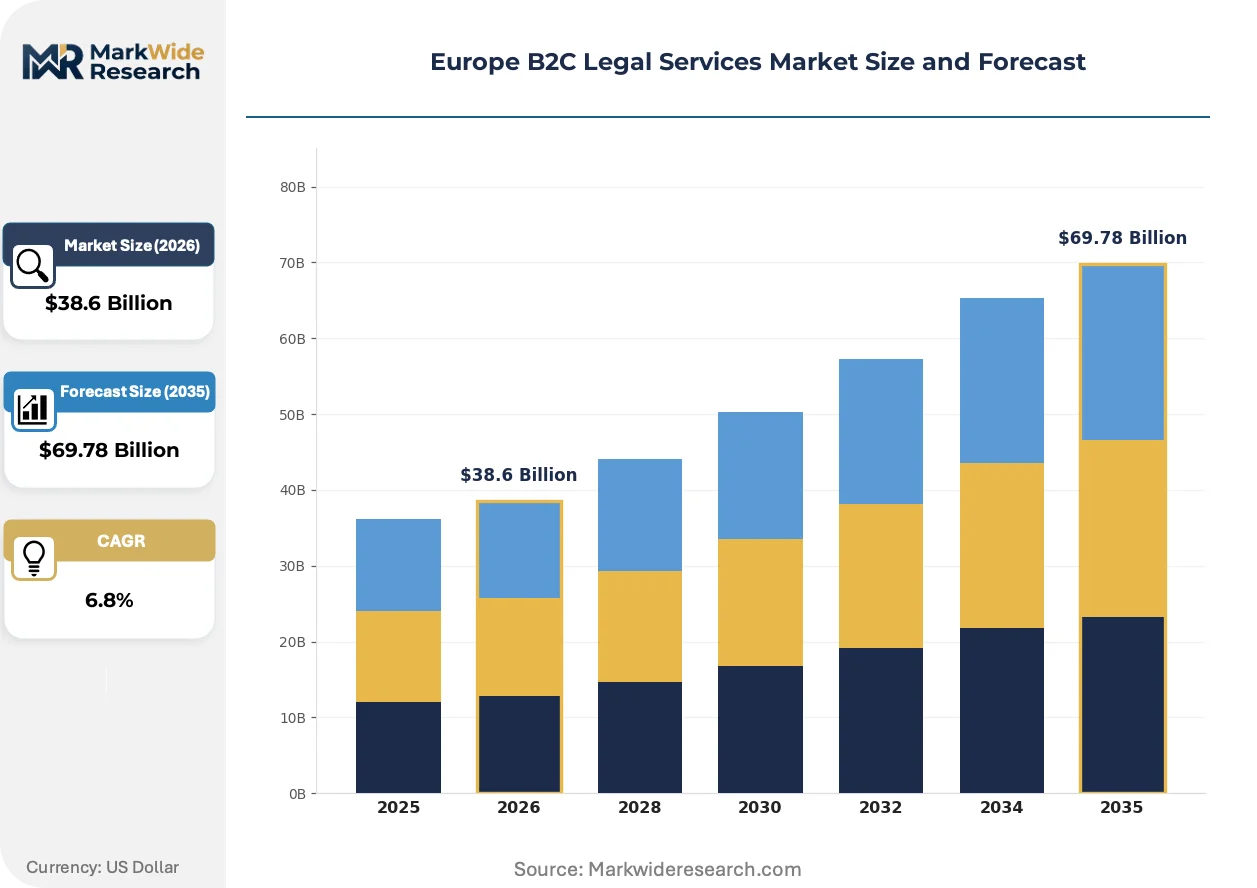
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Family Law, Criminal Defense, Consumer Rights, Debt Recovery Client Type: Individual Clients, Small Businesses, Non-profit Organizations, Entrepreneurs Engagement Model: Retainer, Pay-per-Consultation, Subscription, Contingency Fee Legal Field: Real Estate, Immigration, Employment, Intellectual Property |
| Companies Covered | Linklaters LLP, DLA Piper, Clifford Chance LLP, CMS Legal Services EEIG, Hogan Lovells, Allen & Overy LLP, Baker McKenzie, Bird & Bird LLP, Freshfields Bruckhaus Deringer LLP, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe B2C Legal Services Market Trends and Innovations
Automated legal assistance is fragmenting along regulatory fault lines while consumer expectations shift toward instantaneous, transparent service delivery. Platform architecture decisions now precede market entry strategy.
Natural language processing engines trained on civil code corpora are unifying document generation and preliminary legal research into single-interaction workflows. Solo practitioners and small firms in the United Kingdom adopt these tools within six months of launch. The technology is unifying previously separate service tiers, compressing price differentiation between basic templates and solicitor-reviewed outputs.
The EU AI Act's risk classification system for legal advisory algorithms triggers divergent compliance pathways across member states. High-risk system designations in France and Germany mandate human-in-the-loop architectures that increase operational overhead. Consumer rights platforms targeting multiple jurisdictions respond by segmenting product offerings, deploying fully automated tools only in lower-risk regulatory environments.
Client acquisition through traditional referral networks is losing ground to search-optimized digital channels and embedded finance partnerships. Family law and immigration segments see the strongest channel rotation, with subscription platforms capturing initial consultations previously routed through solicitor directories. This behavioral shift is most visible in urban United Kingdom markets, where digital-native clients under forty bypass established professional networks entirely.
Europe B2C Legal Services Market Segmentation
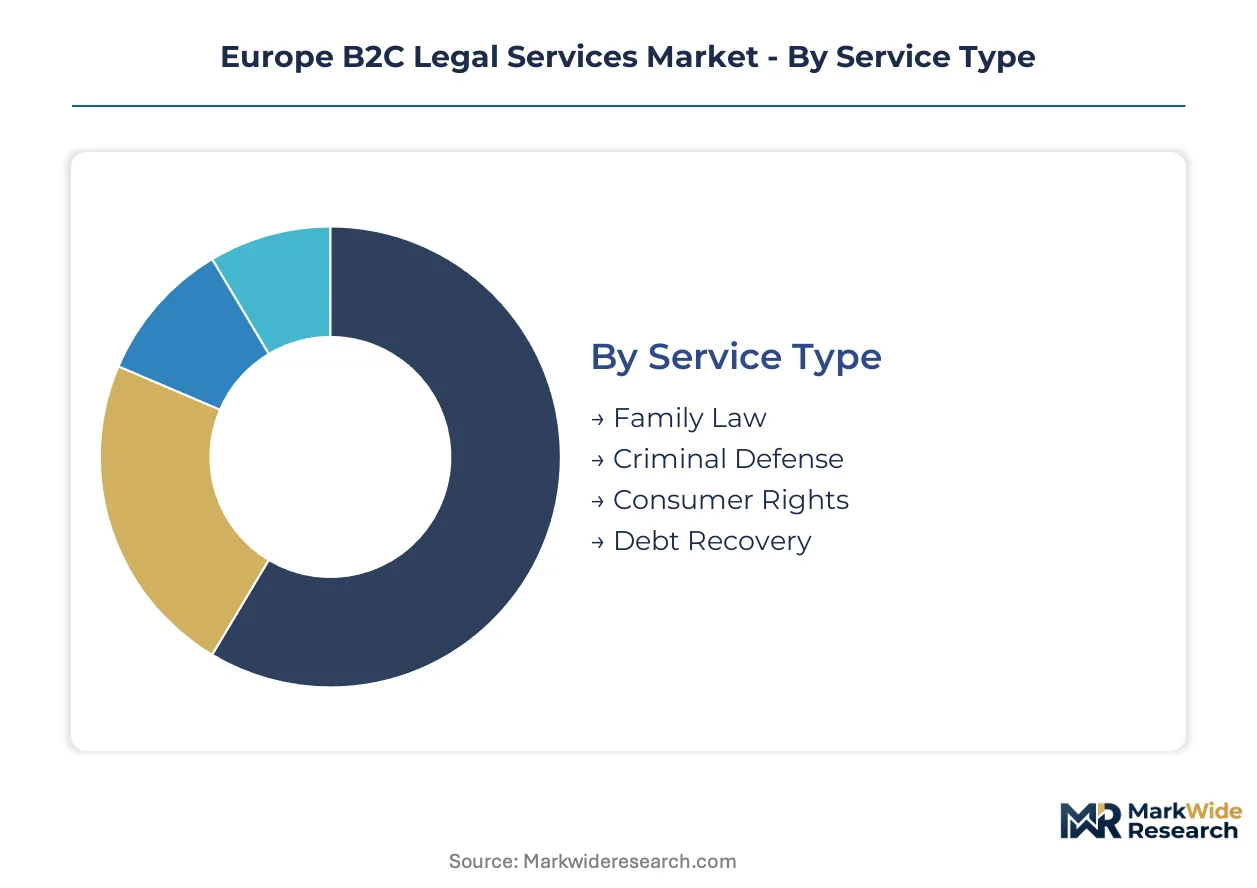
Segmentation in the Europe B2C legal services market reveals how distinct client needs and regulatory constraints reshape platform economics. Service providers must align delivery architecture with engagement preferences and matter complexity to capture sustainable revenue pools.
Service Type:
Client urgency and emotional stakes drive selection patterns across service categories, with episodic crises commanding premium pricing against ongoing advisory relationships.
- Family Law:Divorce proceedings, custody arrangements, and inheritance disputes require jurisdiction-specific procedural expertise. Demand concentrates in Germany and the United Kingdom where subscription models for ongoing matrimonial matters displace traditional hourly billing amid GDPR-mandated document portability requirements.
- Criminal Defense:Episodic, high-stakes matters with severe reputation consequences. Pay-per-consultation dominates in France and Italy where legal aid thresholds and bar association restrictions on non-lawyer ownership limit platform scaling in Southern Europe.
- Consumer Rights:Automated dispute resolution tools leverage encrypted client portals to reduce acquisition friction. GDPR compliance requirements reshape how firms deliver algorithmic transparency for retail-facing products.
- Debt Recovery:Contingency arrangements align provider incentives with recovery outcomes. Small claims automation in the Netherlands and Belgium reduces notarization bottlenecks through smart contract integration.
Family law leads on scale; consumer rights gains share fastest through digital-first delivery.
Client Type:
Volume concentration and price sensitivity diverge sharply across client sophistication tiers, with predictable legal needs enabling subscription economics.
- Individual Clients:Digital-native consumers under forty in urban United Kingdom markets bypass solicitor directories entirely. Search-optimized channels and embedded finance partnerships capture initial consultations previously routed through professional networks.
- Small Businesses:Employment and contract review needs generate recurring advisory relationships. German Mittelstand firms favor retainer structures for predictable cost management.
- Non-profit Organizations:Limited budgets drive demand for templated governance documents and volunteer-pro-bono hybrid models.
- Entrepreneurs:Intellectual property and incorporation services concentrate in Lisbon and Barcelona startup clusters. Cross-border structuring needs outpace local practitioner availability.
Individual clients dominate transaction volume; entrepreneurs exhibit steepest expansion trajectory amid mobility-driven demand.
Engagement Model:
Cash flow predictability and matter duration determine model selection, with subscription economics favored where legal needs extend across multiple quarters.
- Retainer:Traditional hourly billing persists in complex criminal and immigration matters where episodic demand patterns defy recurring revenue structures. French bar association rules reinforce practitioner-controlled relationship economics.
- Pay-per-Consultation:Immediate access for urgent matters commands premium pricing. United Kingdom platforms capture market share through transparent fixed-fee scheduling.
- Subscription:Predictable cost structures for ongoing family law and tenancy matters displace legacy billing in Germany. GDPR-mandated data portability requirements reduce client switching costs.
- Contingency Fee:Outcome-aligned compensation dominates debt recovery and certain personal injury segments. Regulatory caps on percentage recoveries vary across member states.
Retainer arrangements retain revenue concentration; subscription models climb the fastest as platform infrastructure matures.
Legal Field:
Regulatory complexity and cross-border mobility patterns reshape demand geography, with multilingual capabilities determining platform competitiveness.
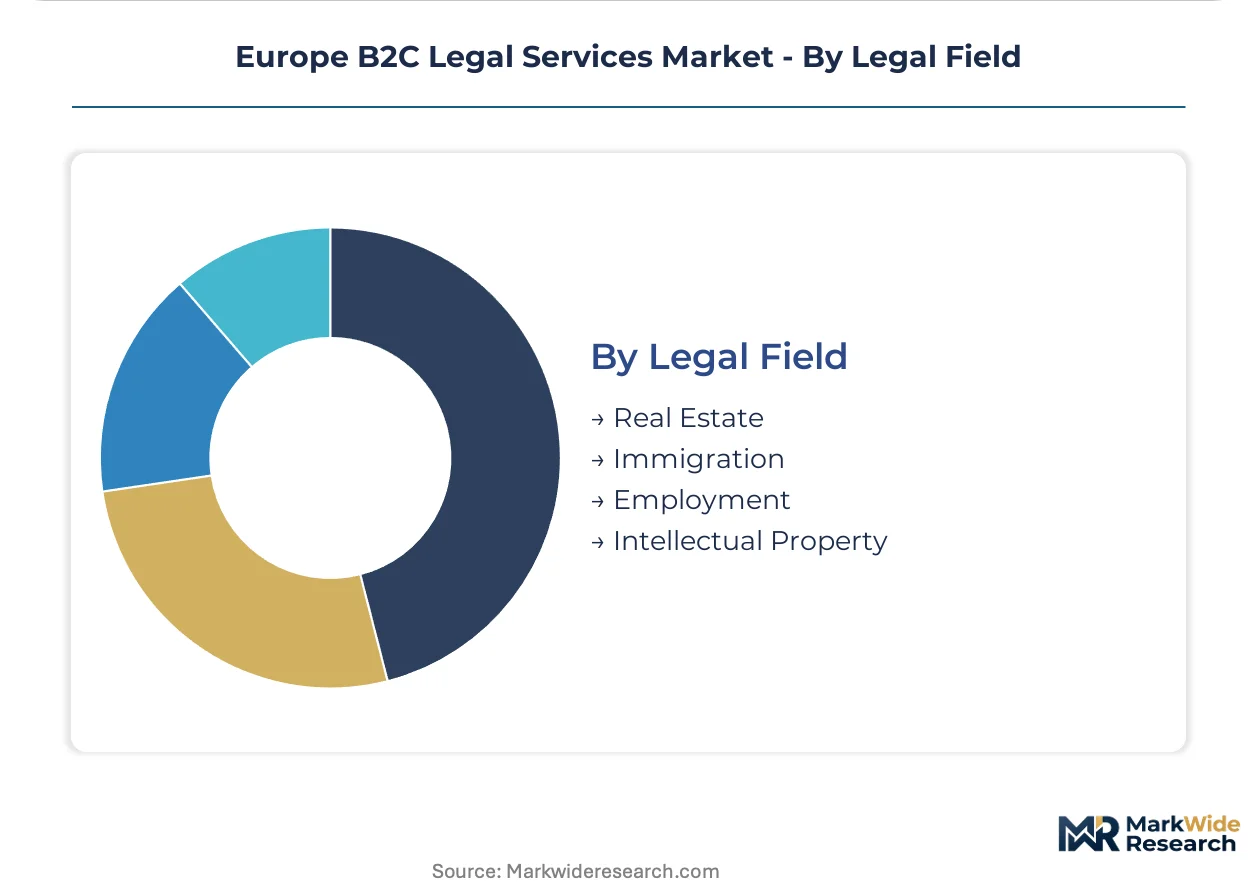
- Real Estate:Tenancy disputes and property transfers require localized notarization knowledge. Blockchain verification reduces bottlenecks in German and Dutch land registries.
- Immigration:Mobile EU citizens in Spain and Portugal generate unmet demand for multilingual documentation. Episodic complexity limits recurring revenue potential.
- Employment:Remote work arrangements and cross-border hiring reshape advisory needs. CSRD-aligned compliance guidance attracts individual shareholders interpreting sustainability disclosure rules.
- Intellectual Property:Startup formation and trademark registration concentrate in Lisbon and Barcelona. Platform licensing economics fragment across national IP office requirements.
Real estate anchors revenue stability; immigration exhibits fastest volume growth amid mobility acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed family law specialists concentrate in London, Paris, and Munich, anchoring platform scalability across Northern Europe while Southern and Eastern markets face persistent practitioner shortages.
United Kingdom
Digital-native consumers under forty in urban centers bypass traditional solicitor directories entirely. GDPR-mandated data portability requirements reduce client switching costs for subscription platforms. London anchors the highest concentration of family law specialists deploying automated document generation tools.
Germany
Mittelstand firms and individual clients favor predictable retainer structures for tenancy and employment matters. CE marking pathways for legal-tech hardware components streamline multi-jurisdiction product launches. Munich and Frankfurt house the densest networks of consumer-facing legal technology infrastructure.
France
Bar association restrictions on non-lawyer ownership and management roles constrain capital inflows to technology platforms. ANSM and national professional conduct standards enforce strict boundaries on automated advisory services. Paris maintains dominance in complex matrimonial and inheritance dispute resolution.
Spain
Mobile EU citizens in Madrid and Barcelona generate unmet demand for multilingual estate documentation and cross-border tax coordination. Episodic immigration complexity limits recurring revenue potential for subscription models. Catalan legal technology clusters experiment with blockchain-verified property transfer records.
Netherlands
Small claims automation and smart contract integration reduce notarization bottlenecks in tenancy and debt recovery segments. Dutch land registries pioneer blockchain verification for property transactions. Amsterdam serves as a regulatory sandbox for algorithmic transparency compliance under EU AI Act frameworks.
Europe B2C Legal Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where scale advantages fragment along regulatory fault lines. The vendor base separates into three strategic archetypes: legacy full-service firms extending consumer-facing digital infrastructure, technology-native platforms built around subscription economics, and hybrid models combining licensed practitioner networks with automated document tools. M&A activity concentrates on acquiring encrypted client portal capabilities and jurisdiction-specific bar admissions, while strategic partnerships with embedded finance providers reshape client acquisition channels.
Within the legacy firm tier, Linklaters LLP, Clifford Chance LLP, and DLA Piper exemplify divergent responses to B2C market entry. Linklaters anchors its positioning through regulatory expertise navigation, Clifford Chance occupies a technology-led service design position, and DLA Piper represents multi-jurisdictional digital infrastructure extension. Each exemplifies how traditional partnership structures adapt to consumer market economics without abandoning core corporate advisory heritage.
| Leading Market Players |
|---|
| Linklaters LLP |
| DLA Piper |
| Clifford Chance LLP |
| CMS Legal Services EEIG |
| Hogan Lovells |
| Allen & Overy LLP |
| Baker McKenzie |
| Bird & Bird LLP |
| Freshfields Bruckhaus Deringer LLP |
| Others |
Pricing and Supply Chain Analysis
GDPR-mandated data portability requirements are forcing platforms to rebuild encrypted client portal infrastructure, compressing margins for providers lacking scale economies while advantaging subscription-native competitors with pre-existing compliance architecture. This demand-side specification shift is fragmenting pricing power across legacy hourly-billing firms and digital-first entrants.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across European B2C legal markets. Subscription models for ongoing family law and tenancy matters command predictable revenue streams in Germany and the United Kingdom, while pay-per-consultation arrangements retain premium pricing in episodic criminal defense and immigration segments. Price differentiation rests on algorithmic transparency certification under EU AI Act frameworks and jurisdiction-specific bar admission depth. Cost compression in automated document generation is intensifying because machine-learning training expenses and human-in-the-loop compliance overhead are rising in parallel. Individual clients under forty in urban United Kingdom markets exhibit lowest price sensitivity due to embedded finance partnerships reducing perceived transaction friction, whereas small businesses in Southern Europe remain most price-conscious amid limited legal-tech penetration.
Supply Chain Analysis
Licensed practitioner scarcity in London, Paris, and Munich is constraining platform scaling across Northern Europe while Southern and Eastern markets face persistent talent pipeline gaps. Supply concentration draws from Germany, the United Kingdom, and France for family law specialists, with Netherlands and Belgium contributing disproportionately to smart contract and blockchain verification technical talent. Raw material dependencies center on encrypted cloud infrastructure, natural language processing engines trained on civil code corpora, and jurisdiction-specific procedural knowledge databases. Single-source vulnerability runs through concentrated bar admission networks in France and Italy where non-lawyer ownership restrictions limit capital inflows. Distribution runs through search-optimized digital channels and embedded finance partnerships, displacing traditional solicitor directories in client acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European B2C legal services constitute a late-cycle quality story as individual clients migrate toward premium specifications around algorithmic transparency and cross-border qualification depth. This demand shift favors providers with pre-built compliance architecture and multi-jurisdiction bar networks.
For Market Incumbents: Acquire encrypted client portal capabilities and jurisdiction-specific bar admissions to defend against technology-native subscription platforms. Prioritize backward integration into natural language processing engine development to reduce third-party licensing costs. Build capacity in Spanish and Portuguese multilingual estate documentation to capture mobile EU citizen demand before specialized entrants consolidate these segments. For New Entrants and Emerging Players: The price-point gap between premium human-in-the-loop advisory and economy-tier automated templates offers white-space entry in mid-market family law automation. Target cross-border inheritance planning for mobile EU citizens in Spain and Portugal where local practitioner availability lags demand. Deploy regulatory sandbox positioning in Amsterdam and Barcelona to accelerate EU AI Act compliance validation before scaling across member states. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid models combining licensed practitioner networks with automated document tools, particularly those holding multi-jurisdiction bar admissions. Long-term viability over the five-to-ten year window hinges on CE marking pathway expertise and GDPR-mandated data portability infrastructure depth. Monitor divergence in national bar association rules on non-lawyer ownership as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Bar Admissions | Multi-jurisdiction qualification unlocks cross-border service scalability under fragmented EU regulatory frameworks. |
| Platform Integration with Embedded Finance | Partnerships with fintech providers reduce client acquisition friction in United Kingdom urban markets. |
| Regulatory Sandbox Participation | Amsterdam and Barcelona sandboxes accelerate EU AI Act algorithmic transparency compliance validation timelines. |
| Backward Integration into NLP Development | In-house civil code corpus training reduces third-party licensing costs for document automation tools. |
| Geographic Expansion into Southern Europe | Practitioner scarcity in Spain and Portugal creates first-mover advantage in multilingual estate documentation. |
Research Methodology
Coverage spans Western Europe, Northern Europe, and Southern Europe, with primary inputs from each regional cluster combined with secondary validation. Primary interviews engaged legal technology executives, family law practitioners, bar association regulatory affairs leads, and embedded finance partnership managers. Secondary sources included GDPR implementation guidance documents, EU AI Act risk classification frameworks, national bar association professional conduct standards, and encrypted client portal technical specifications. Bottom-up practitioner network analysis and top-down platform revenue modeling were triangulated to derive market estimates.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, client sophistication tier, engagement model economics, and jurisdiction-specific regulatory cluster. CAGRs were derived from practitioner density trends, digital channel penetration rates, and subscription platform scaling velocities. Forecast inputs incorporated EU AI Act implementation timelines and national bar association rule evolution patterns.
Caveats apply where regulatory divergence between member states or algorithmic transparency mandate revisions could materially shift the outlook. Forecasts reflect assumptions around licensed practitioner supply elasticity and technology platform capital access under existing ownership restrictions. Material deviation in EU AI Act enforcement intensity or bar association liberalization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Islamic Finance Market
Financial Services
Online Lottery Market
Financial Services
Europe E-Brokerages Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Canada Credit Cards Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
North America B2C Legal Services Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Intermediary Service Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Latin America Factoring Services Market
Financial Services
North America Trade Finance Market
Financial Services
Cash Logistics Market