
 Global Business Management Consulting Service Market | 2026-2036
Global Business Management Consulting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Management Consulting Service Market Analysis
Generative AI integration is reshaping how consulting firms deliver strategic recommendations and automate diagnostic workflows. Accenture plc leverages its technology services division to embed AI-driven insights across client engagements. McKinsey & Company sustains its competitive edge through proprietary analytics platforms that accelerate problem-solving timelines. Deloitte anchors its growth in regulatory and risk advisory, competing directly with traditional strategy houses on complex transformation programs.
Business management consulting services encompass structured advisory engagements that apply analytical frameworks, industry benchmarks, and change-management protocols to improve organizational performance, operational efficiency, and strategic positioning. These services typically deploy cross-functional teams combining domain specialists, data scientists, and implementation coaches to translate recommendations into executable outcomes. Strategy consulting commands the highest fee premiums due to board-level access and long-term client relationships, while IT consulting is expanding fastest as enterprises modernize legacy infrastructure. Operational consulting occupies the largest volume share across manufacturing and retail verticals, where margin pressure sustains demand for cost-reduction programs. Financial advisory maintains stable demand cycles tied to M&A activity and capital restructuring needs.
The EU AI Act and GDPR compliance requirements are reshaping advisory demand across European client portfolios, with regulators mandating algorithmic transparency and data governance audits. The SEC's climate disclosure rules and the US Federal Trade Commission's merger guidelines are expanding the scope of financial and strategy consulting engagements for American corporations. ISO 27001 and SOC 2 certification requirements are becoming standard pre-qualification criteria for consulting vendors serving regulated industries. Stakeholders must monitor how jurisdictional regulatory divergence creates specialized advisory niches that favor firms with multi-market compliance expertise.
Market Dynamics
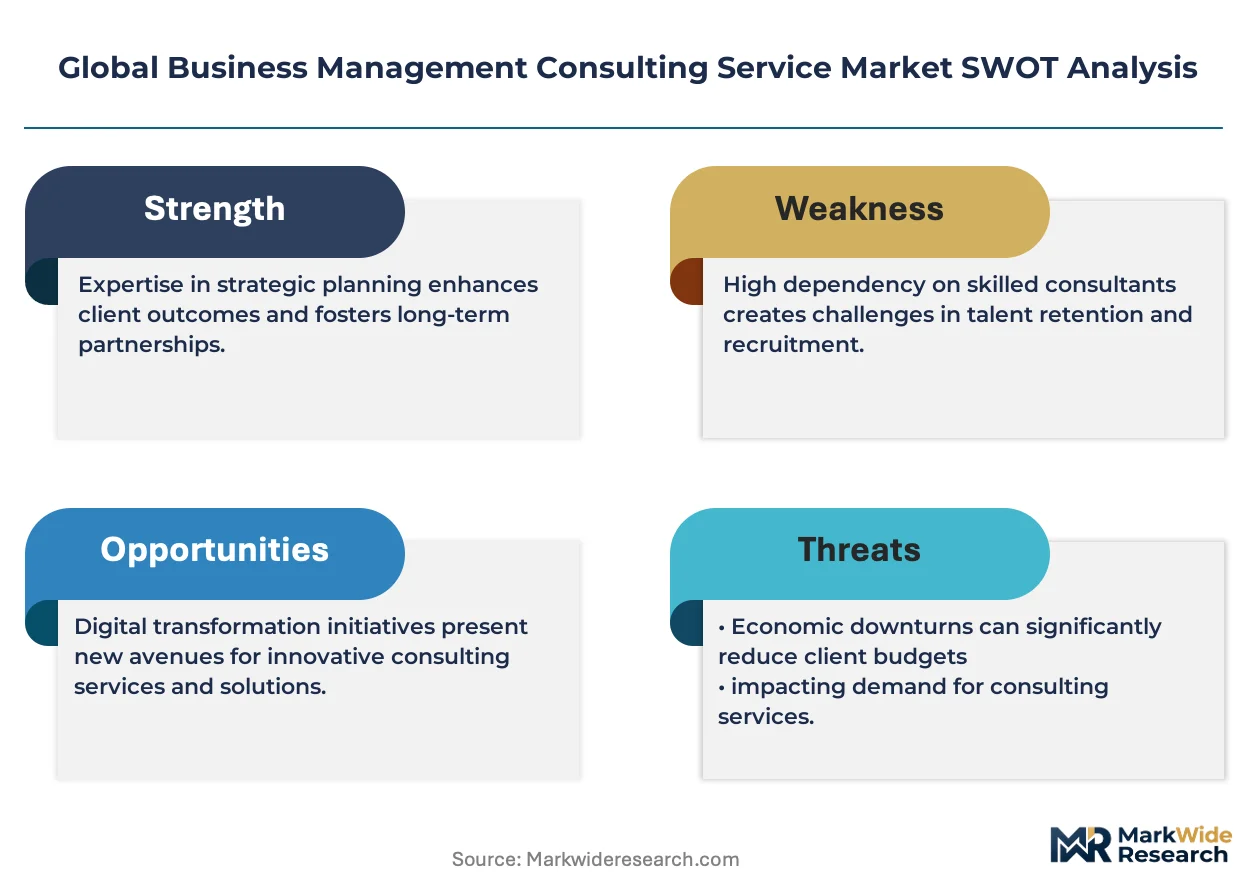
Generative AI deployment is compressing project timelines and forcing consulting firms to restructure engagement economics around automated diagnostics rather than hourly labor.
Growth Catalysts
- EU AI Act Compliance Mandates:European corporations require algorithmic transparency audits and data governance frameworks, creating sustained advisory demand across Frankfurt, Paris, and Amsterdam financial centers.
- Healthcare Operational Modernization:Hospital systems deploy patient flow analytics and administrative automation, driving recurring engagements for process redesign and change management.
- US Technology Sector Premium Spending:Silicon Valley and Seattle-based clients commission high-margin strategy work for market entry, pricing architecture, and competitive intelligence.
Market Restraints
- Technical Talent Scarcity:Firms compete for data scientists and AI implementation specialists, inflating compensation costs and compressing project margins.
- Client In-House Capabilities:Large enterprises build internal strategy functions and analytics units, substituting previously outsourced advisory work.
- Regulatory Fragmentation Costs:Divergent SEC climate disclosure rules, EU CSRD requirements, and emerging Asia-Pacific ESG standards force multi-jurisdictional compliance overhead.
Strategic Opportunities
- India Manufacturing Consulting:PLI scheme incentives and industrial corridor development generate demand for operational excellence and supply chain restructuring advisory.
- Generative AI + Cloud Convergence:Firms that combine large language model deployment with legacy system migration capture integrated transformation budgets.
- Japan METI Decarbonization Roadmaps:Corporate net-zero commitments under national dual carbon goals open energy transition and circular economy advisory niches.
Industry Challenges
- ISO 27001 Certification Timelines:Consulting vendors serving healthcare and financial clients face extended pre-qualification periods for information security audits.
- Knowledge Codification Barriers:Senior partner expertise remains difficult to transfer to junior staff, limiting scale and creating project quality variance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Management Consulting Service Market |
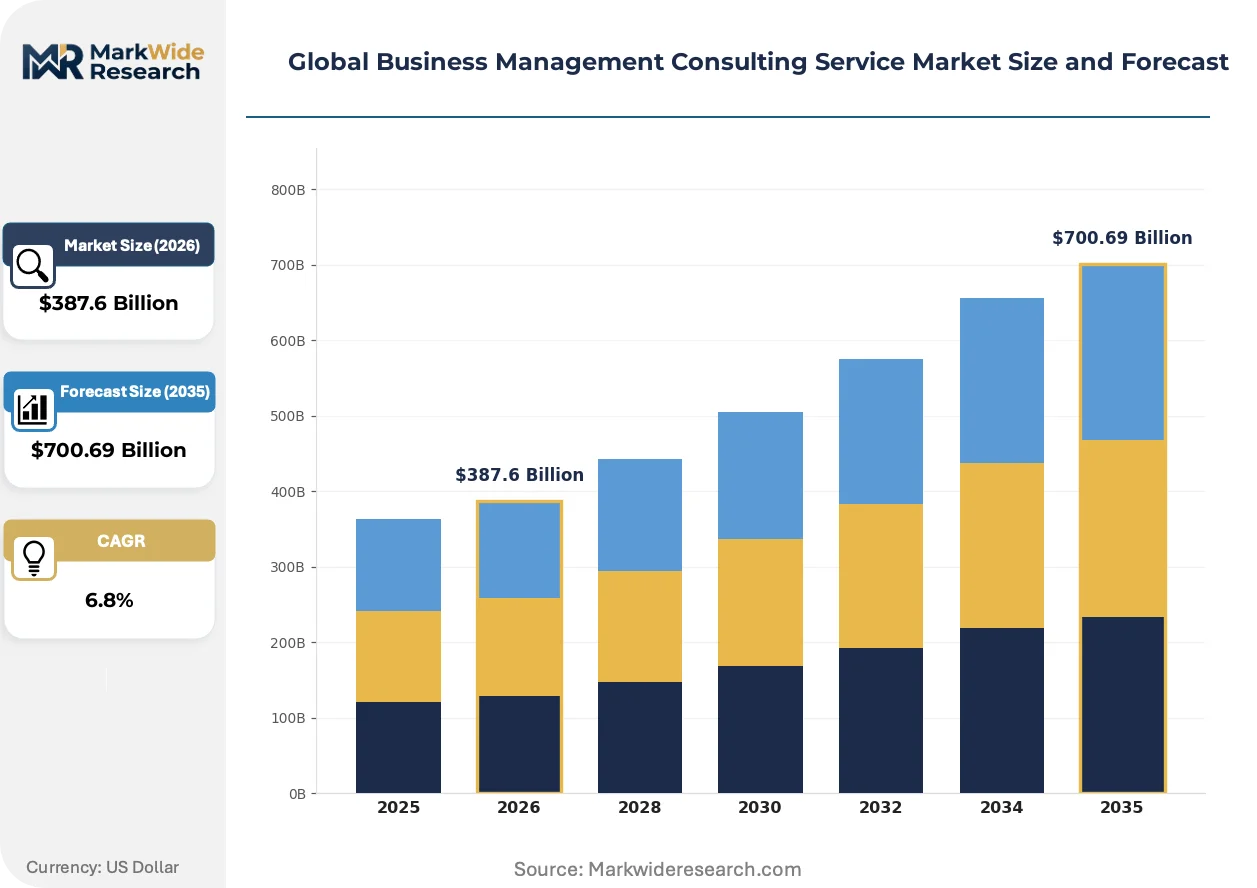
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Operational Consulting, Strategy Consulting, Financial Advisory, IT Consulting Client Type: Corporations, Government Agencies, Non-Profits, Startups Engagement Type: Long-Term Projects, Short-Term Assignments, Workshops, Advisory Services Industry Vertical: Healthcare, Telecommunications, Manufacturing, Retail |
| Companies Covered | Accenture plc, McKinsey & Company, Boston Consulting Group, Deloitte, Bain & Company, PricewaterhouseCoopers, KPMG, Ernst & Young, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Management Consulting Service Market Emerging Trajectories
Advisory delivery models are fragmenting as automation compresses diagnostic phases and clients demand executable implementation over static recommendations.
Generative AI co-pilots are virtualizing the traditional analyst tier by automating research synthesis, financial modeling, and presentation generation. Mid-market clients now access previously enterprise-grade analytical capabilities at reduced fee structures. This compression is virtualizing the pyramid model that historically sustained partner-to-analyst leverage ratios.
CSRD sustainability reporting mandates are forcing European corporations to commission integrated assurance over environmental metrics, social governance disclosures, and supply chain due diligence. The directive requires double materiality assessments that bridge financial and impact accounting. Industrial conglomerates in Germany and France are responding by embedding consultants directly into finance and risk functions rather than commissioning standalone projects.
Fixed-fee outcome contracting is displacing time-and-materials billing across transformation programs, transferring delivery risk to advisory firms. Technology sector buyers in the United States are pioneering this shift, tying vendor compensation to measurable operational improvements. This reconfiguration demands that consultants invest in proprietary IP and implementation tooling to protect margins under performance-based terms.
Global Business Management Consulting Service Market Segmentation
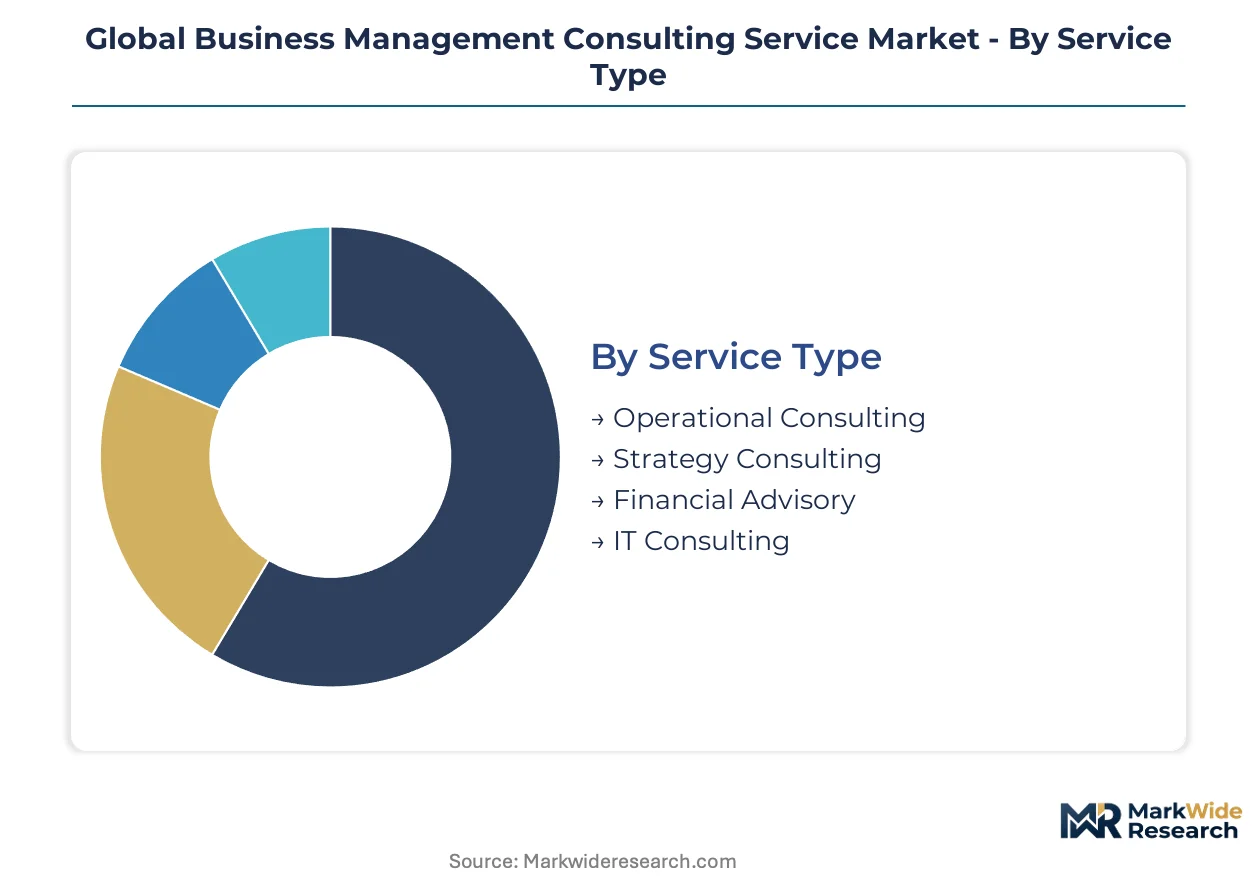
Consulting engagements vary dramatically in duration and renewal patterns, with operational retainers cycling quarterly while strategy mandates often span multi-year horizons. Understanding these velocity differences helps vendors calibrate staffing models and revenue forecasting.
Service Type:
Operational consulting turns over fastest with monthly billing cycles, while strategy consulting locks in the longest engagement tenures through board-level relationships.
- Strategy Consulting:Board-facing advisory on market positioning, M&A targeting, and competitive intelligence. US technology sector clients in Silicon Valley and Seattle sustain premium fee structures for pricing architecture and market entry planning.
- Operational Consulting:Process redesign, cost reduction programs, and supply chain optimization deploying cross-functional implementation teams. Manufacturing and retail verticals in Germany and India drive recurring demand under sustained margin pressure.
- Financial Advisory:Capital restructuring, due diligence, and transaction support tied to M&A cycles. Demand concentrates in London and New York financial centers with regulatory complexity around SEC climate disclosure integration.
- IT Consulting:Legacy modernization, cloud migration, and systems integration. Enterprises across Japan and Singapore commission these services to meet METI digital transformation targets and Smart Nation infrastructure mandates.
Operational consulting anchors the volume base while IT consulting gains share at the steepest rate.
Client Type:
Government procurement cycles stretch 18-24 months, compressing margins through compliance overhead, while startup engagements close fastest but carry highest churn risk.
- Corporations:Large enterprises with dedicated procurement functions and multi-year vendor management frameworks. French and German industrial conglomerates embed consultants directly into finance functions under CSRD integrated assurance requirements.
- Startups:Venture-backed companies seeking rapid scaling support with compressed decision timelines. Israeli and UAE technology clusters commission pricing and go-to-market advisory on fixed-fee outcome contracts.
- Government Agencies:Public sector bodies with mandated competitive bidding and extended pre-qualification under ISO 27001 and SOC 2 certification requirements.
- Non-Profits:Mission-driven organizations prioritizing cost efficiency over premium advisory, often accessing pro bono or reduced-rate consulting through corporate social responsibility programs.
Corporations anchor the volume base while startups expand most quickly as venture funding concentrates in advisory-intensive scaling phases.
Engagement Type:
Workshops deliver immediate revenue recognition with minimal resource lock-in, whereas long-term projects require partner-level commitment and carry concentration risk.
- Short-Term Assignments:Targeted diagnostics and rapid assessments typically concluding within 4-8 weeks. Healthcare systems in the United States deploy these for patient flow analytics with quick-turn operational recommendations.
- Long-Term Projects:Multi-phase transformation programs spanning 12-36 months with dedicated team embedding. Japanese corporations commission these for METI-aligned decarbonization roadmaps and circular economy restructuring.
- Workshops:Intensive facilitated sessions generating immediate deliverables and training outcomes. Indian manufacturing clients utilize these for PLI scheme compliance and operational excellence kickoffs.
- Advisory Services:Ongoing retainer relationships providing on-call expertise without defined project scopes. European corporations maintain these for EU AI Act compliance monitoring and algorithmic governance updates.
Long-term projects anchor the volume base while advisory services climb the fastest as regulatory complexity sustains recurring demand.
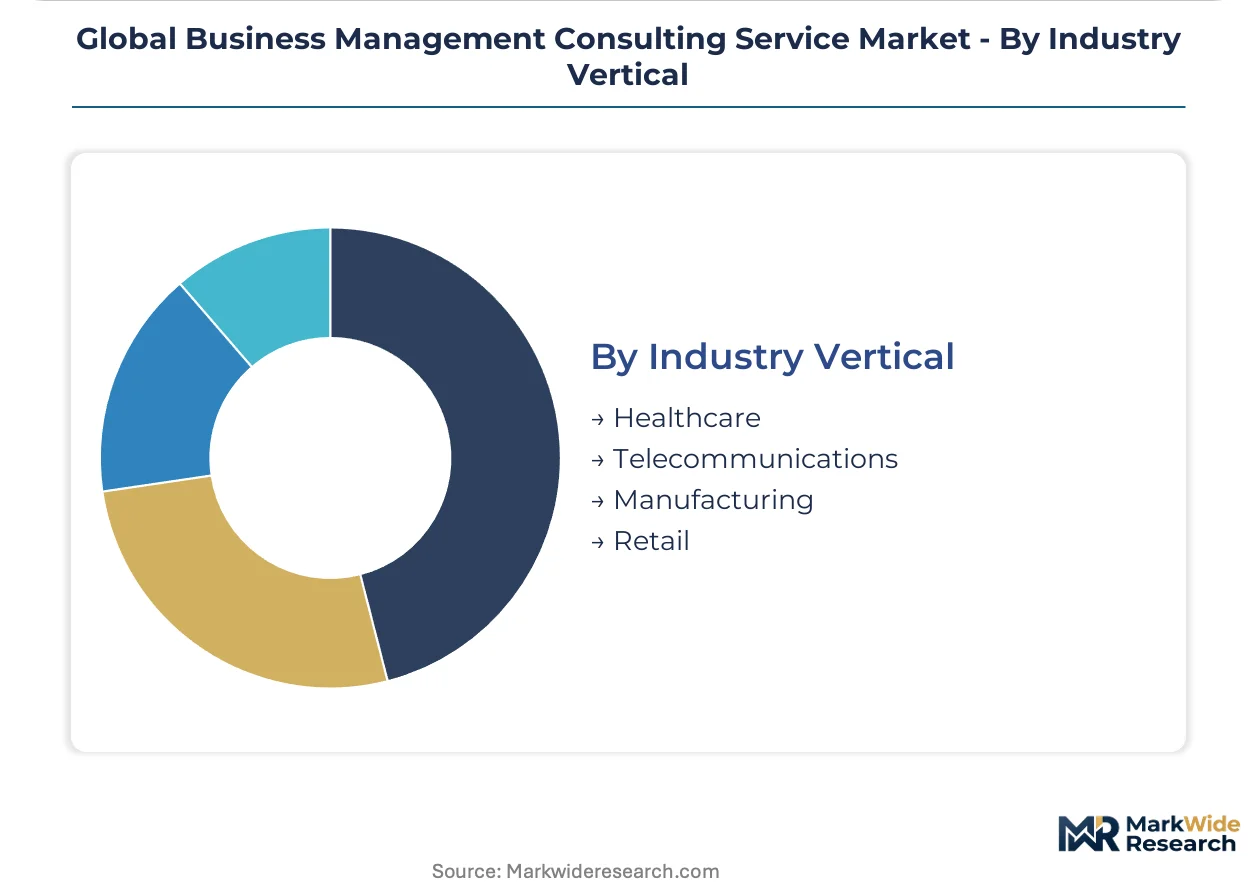
Industry Vertical:
Healthcare consulting renews annually through regulatory compliance mandates, while telecommunications contracts extend 3-5 years tied to infrastructure investment cycles.
- Healthcare:Hospital systems and pharmaceutical companies requiring operational modernization and regulatory navigation. US health systems expand patient flow analytics and administrative automation under HIPAA compliance frameworks.
- Manufacturing:Industrial producers seeking operational excellence and supply chain resilience. German automotive and machinery clusters drive demand for Industry 4.0 transformation and ESG reporting integration.
- Retail:Consumer-facing businesses optimizing omnichannel operations and margin management. French and UK retailers commission cost-reduction programs amid inflationary pressure and inventory complexity.
- Telecommunications:Network operators modernizing infrastructure and navigating spectrum policy. Singapore and South Korean carriers invest in 5G deployment advisory and digital service platform development.
Manufacturing anchors the volume base while healthcare shows the steepest expansion trajectory as operational consulting penetrates hospital administrative functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology sector buyers in Silicon Valley and Seattle anchor premium demand for strategy advisory, while healthcare systems and industrial conglomerates sustain operational consulting volumes across Frankfurt, Mumbai, and Tokyo financial centers.
United States
SEC climate disclosure rules and FTC merger guidelines expand advisory scopes for financial and strategy engagements. HIPAA compliance frameworks drive patient flow analytics demand among hospital systems. Silicon Valley technology clients commission high-margin pricing architecture and competitive intelligence work.
Germany
CSRD sustainability reporting mandates force industrial conglomerates to embed consultants directly into finance functions. EU AI Act algorithmic transparency requirements create compliance advisory demand across Frankfurt and Munich financial centers. Automotive and machinery clusters in Baden-Württemberg drive Industry 4.0 transformation engagements.
India
PLI scheme incentives and industrial corridor development generate operational excellence advisory demand. RBI and SEBI regulatory complexity sustains financial restructuring engagements. Manufacturing clients in Maharashtra and Gujarat utilize workshops for supply chain restructuring and compliance kickoffs.
Japan
METI decarbonization roadmaps and dual carbon goals open energy transition advisory niches. Digital transformation targets under Smart Nation infrastructure mandates expand IT consulting contracts. Corporations in Tokyo and Osaka commission multi-phase circular economy restructuring programs.
United Kingdom
GDPR and emerging AI governance requirements sustain data governance audit demand. Cost-reduction programs among inflation-pressured retailers in London and Southeast England drive operational consulting volumes. Financial advisory concentrates in London tied to M&A cycle complexity.
Global Business Management Consulting Service Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered engagement economics. The vendor base stratifies between premium strategy houses, technology-anchored integrators, and audit-rooted advisory networks. Three archetypes dominate: proprietary analytics platforms, regulatory compliance specialists, and AI-augmented implementation firms. Competitive moves center on fixed-fee outcome contracting and generative AI co-pilot deployment to restructure labor leverage ratios.
Within the premium strategy tier, McKinsey & Company and Boston Consulting Group exemplify board-facing advisory archetypes anchored in proprietary methodologies. Among technology-anchored integrators, Accenture plc occupies a position combining cloud migration capabilities with AI-driven diagnostic tools. Deloitte represents the audit-rooted network archetype, competing on regulatory and risk advisory across complex transformation programs.
| Leading Market Players |
|---|
| Accenture plc |
| McKinsey & Company |
| Boston Consulting Group |
| Deloitte |
| Bain & Company |
| PricewaterhouseCoopers |
| KPMG |
| Ernst & Young |
| Capgemini |
| Others |
Supply Flow & Price Mechanics
Partner-level talent concentration in London, New York, and Frankfurt directly determines where fee premiums accumulate across the consulting value chain, with senior expertise scarcity anchoring margin pools in these financial centers while delivery labor arbitrage shifts execution tiers to lower-cost geographies.
Pricing Analysis
Cost-plus contracts with named partner utilization indexation dominate premium strategy engagements, while fixed-fee outcome structures displace time-and-materials billing across transformation programs. Three-tier pricing structure across premium strategy houses, technology-anchored integrators, and audit-rooted advisory networks reflects certification depth and board-level access differentiation. Pricing pressure stems from client in-house capability building and generative AI automation of diagnostic phases. Startup buyers exhibit highest price sensitivity, while Fortune 500 technology sector clients sustain premium tolerance for competitive intelligence and pricing architecture mandates.
Supply Chain Analysis
Tariff exposure between India and client markets in North America and Europe dominates supply chain risk planning for delivery center configurations. Talent supply concentrates in India, Poland, and the Philippines for analytics and implementation tiers, while partner-grade expertise draws from the United Kingdom, United States, and Germany. Raw material dependencies span specialized data infrastructure, proprietary AI training frameworks, and ISO 27001 certification audit capacity. Single-source vulnerability sits with cloud hyperscaler platforms hosting client data environments. Distribution runs through direct enterprise sales teams, channel partnerships with technology vendors, and embedded advisory relationships within audit networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI co-pilots and client in-house strategy functions constitute a dual substitution threat that incumbent advisory firms must navigate through capability differentiation and implementation depth.
For Market Incumbents: Entrench proprietary analytics platforms and implementation tooling to defend margin position under fixed-fee outcome contracting pressure. Deepen partner-grade expertise transfer mechanisms to junior staff, addressing knowledge codification barriers that limit scale. Vertical integration into cloud migration and AI deployment capabilities captures integrated transformation budgets that pure strategy houses cannot access. For New Entrants and Emerging Players: Build out specialized compliance advisory niches around EU AI Act algorithmic transparency and CSRD sustainability reporting mandates where multi-jurisdictional expertise creates barriers. Target mid-market manufacturing clients in India and Southeast Asia with workshop-based operational excellence offerings. Pursue channel partnerships with technology vendors to access enterprise procurement frameworks without direct sales infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier operational consultancies seeking exit liquidity as fixed-fee pressure compresses returns. Long-term viability hinges on AI-augmented delivery models that restructure labor economics across the analysis window. Monitor client procurement committee composition shifts toward CFO and CIO dominance as inflection signal for implementation-heavy advisory demand.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Co-Pilot Deployment | Automates research synthesis and financial modeling, compressing project timelines for McKinsey and Accenture engagements. |
| Fixed-Fee Outcome Contracting | Transfers delivery risk to advisory firms, demanding proprietary IP investment to protect margins under performance terms. |
| EU AI Act Compliance Practice Buildout | Captures algorithmic transparency audit demand across Frankfurt and Paris financial centers under regulatory mandate. |
| India Delivery Center Expansion | Supports PLI scheme advisory growth while lowering execution cost structure for operational consulting tiers. |
| CSRD Integrated Assurance Capability | Embeds consultants directly into German and French industrial conglomerate finance functions under double materiality requirements. |
Methodological Framework
A standing panel of consulting firm partners, client procurement executives, regulatory affairs specialists, and technology integration leads provided ongoing calibration across primary fieldwork. This study combined structured interviews with these stakeholders against secondary validation from SEC filings, EU regulatory disclosure databases, and hyperscaler partnership announcements. Bottom-up engagement volume modeling and top-down market sizing triangulated outputs across service type, client vertical, and geographic demand clusters.
Scenario-bracketing around generative AI adoption velocity and regulatory enforcement intensity framed the projection horizon. Segmentation dimensions modeled include service type, client size tier, engagement duration pattern, and regional regulatory framework cluster. CAGRs were derived from weighted average growth assumptions across these segments, with inputs from partner hiring trajectories, client budget allocation surveys, and compliance mandate implementation timelines.
Stress conditions across AI automation penetration rates, talent compensation inflation, and regulatory divergence patterns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about client in-house capability substitution and technology vendor competitive entry. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Debt Settlement Solution Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Virtual Account Management Software Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
UK Islamic Finance Market
Financial Services
Check Cashing Services Market
Financial Services
Europe E-Brokerages Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Germany Factoring Services Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
South Korea Trade Finance Market
Financial Services
China Supply Chain Financing Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
China Financial Services Software Market