
 Latin America Factoring Services Market | 2026-2036
Latin America Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Factoring Services Market Insights
Bank-fintech partnership channels across Latin America are tilting toward embedded finance models that embed factoring directly into enterprise resource planning workflows. BNP Paribas leverages its regional trade finance infrastructure to anchor multi-currency receivable programs for corporates with cross-border exposure. BTG Pactual specializes in high-volume domestic factoring for Brazilian industrial clients, while HSBC Group competes through integrated supply chain finance offerings linked to Asia-Latin America trade corridors.
Factoring services constitute a form of receivables finance in which a financial entity purchases outstanding invoices from a seller at a discount, typically advancing 70-90% of face value within 24-72 hours and assuming collection responsibility depending on the structure. The mechanism accelerates cash conversion cycles for businesses with elongated payment terms from buyers, substituting for traditional collateral-backed lending in credit-constrained environments. Non-recourse factoring commands premium pricing due to credit risk transfer but remains concentrated among large enterprise clients with investment-grade counterparties, while recourse factoring dominates volume among SMEs where the originating seller retains default exposure. Invoice discounting without notification to debtors sustains margin pools in established manufacturing verticals where supplier-buyer relationships resist transparency.
Brazil's central bank and Mexico's CNBV enforce electronic invoice validation standards that shape origination authenticity requirements across domestic factoring platforms. Chile's financial market regulator and Argentina's central bank impose capital adequacy and consumer protection frameworks that constrain fintech entrants while creating compliance barriers for cross-border portfolio expansion. Stakeholders must monitor how open banking API standards and real-time payment infrastructure deployments alter receivable verification costs and competitive positioning across national boundaries.
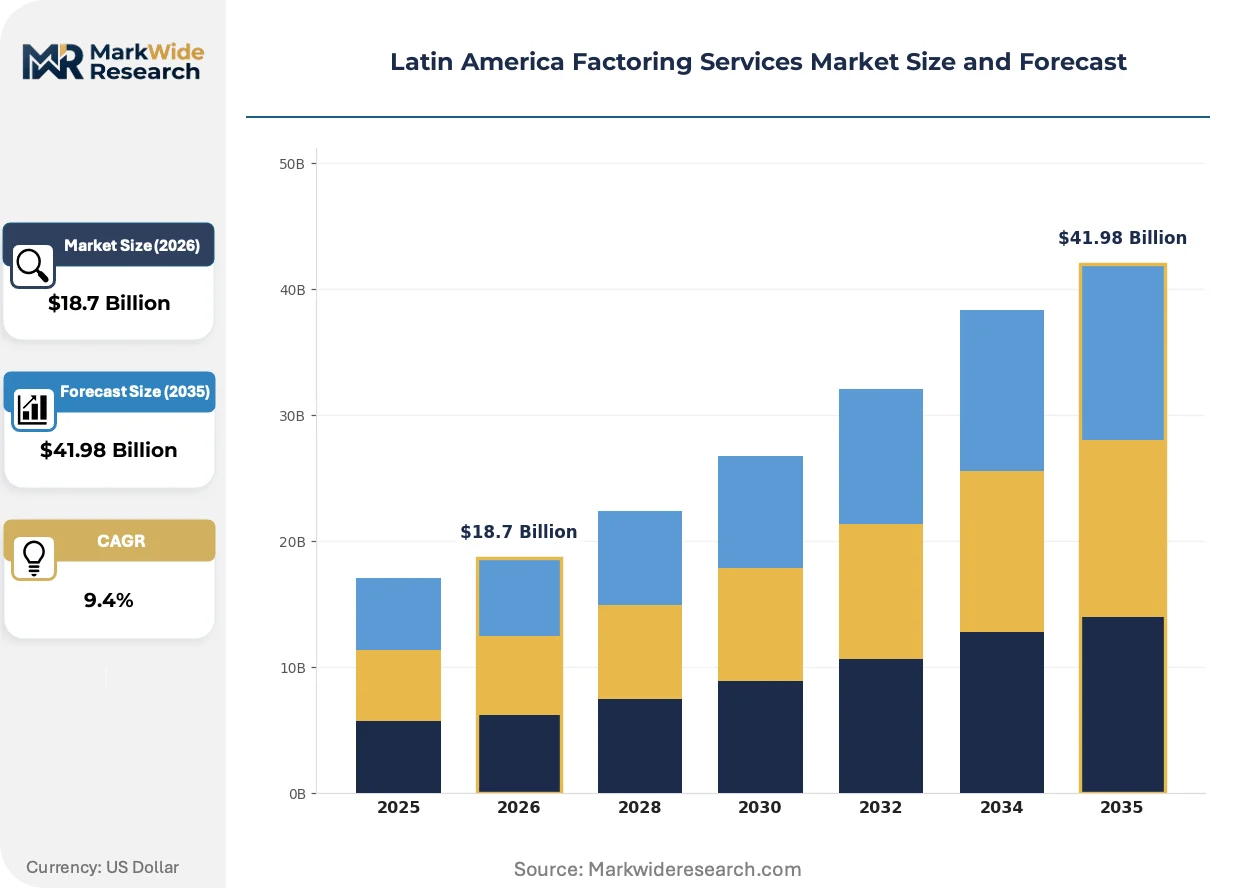
Market Dynamics
Electronic invoice validation frameworks across Brazil, Mexico, and Chile are compressing origination timelines and forcing traditional banks to rebuild underwriting infrastructure around real-time receivable verification.
Growth Catalysts
- CNBV electronic invoicing mandates:Mexico's securities regulator mandates standardized e-invoice formats that reduce documentation friction for cross-border receivable programs.
- SME liquidity compression:Elongated payment terms from large industrial buyers in Brazil's manufacturing corridor accelerate adoption of invoice-backed working capital.
- API-enabled verification:Open banking interfaces in Chile reduce receivable authentication costs for digital origination platforms serving mid-market clients.
Market Restraints
- Recourse structure concentration:Credit risk retention by originating sellers limits pricing power among SME-focused platforms in Argentina's inflationary environment.
- Cross-border portfolio friction:Argentina's central bank capital controls create settlement delays for multi-currency factoring programs spanning Mercosur trade corridors.
- Invoice fraud exposure:Double-financing risks in paper-based legacy systems persist in Colombian agricultural supply chains lacking centralized registry infrastructure.
Strategic Opportunities
- Peruvian mining supply chains:Underpenetrated receivable finance in Andean extractive industries offers volume expansion for platforms with commodity-linked underwriting.
- Embedded ERP integration:Direct origination through enterprise resource planning workflows captures transaction data upstream of invoice generation.
- Real-time payment rails:Brazil's Pix instant settlement infrastructure enables same-day advance disbursement, compressing cash conversion cycles for domestic factoring.
Industry Challenges
- Credit assessment talent scarcity:Shortage of underwriters familiar with SME cash-flow analysis in Mexico's northern industrial states constrains platform scaling.
- Legacy system integration complexity:Core banking infrastructure at regional lenders requires costly middleware development to interface with fintech origination engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Factoring Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Invoice Discounting, Supply Chain Finance Customer Type: SMEs, Large Enterprises, Corporates, Public Sector Industry Vertical: Manufacturing, Retail, Construction, Transportation Transaction Size: Small, Medium, Large, Enterprise |
| Companies Covered | BTG Pactual, Barclays Plc, BNP Paribas, HSBC Group, Deutsche Factoring Bank, FINAMCO, Hitachi Capital (UK) PLC, Accion International, Expocredit, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Factoring Services Market Trends and Innovations
Receivable finance platforms across Latin America are converging on automated underwriting pipelines that ingest alternative data streams beyond traditional credit bureau scores, compressing origination from days to hours.
Blockchain-based invoice registries are hybridizing with existing electronic invoicing infrastructure to create immutable receivable provenance records. Brazilian industrial distributors with cross-border exposure are piloting these systems to prevent double-pledging fraud. The technology is hybridizing recourse and non-recourse structures by enabling dynamic credit risk transfer based on real-time buyer payment behavior.
Chile's financial market regulator has mandated API standardization for receivable verification that interfaces directly with central tax authority databases. This policy eliminates manual document submission for domestic factoring origination. Manufacturing exporters in Santiago's metropolitan region are restructuring working capital programs to exploit these streamlined authentication protocols.
Buyer-side procurement platforms are unbundling payment term extensions from supplier financing, creating direct origination channels that bypass traditional banking intermediaries. Large retailers in São Paulo's consumer goods corridor now embed pre-approved factoring offers within purchase order workflows. This behavioral shift is most visible among Brazilian automotive parts suppliers negotiating with multinational assembly plants.
Latin America Factoring Services Market Segmentation
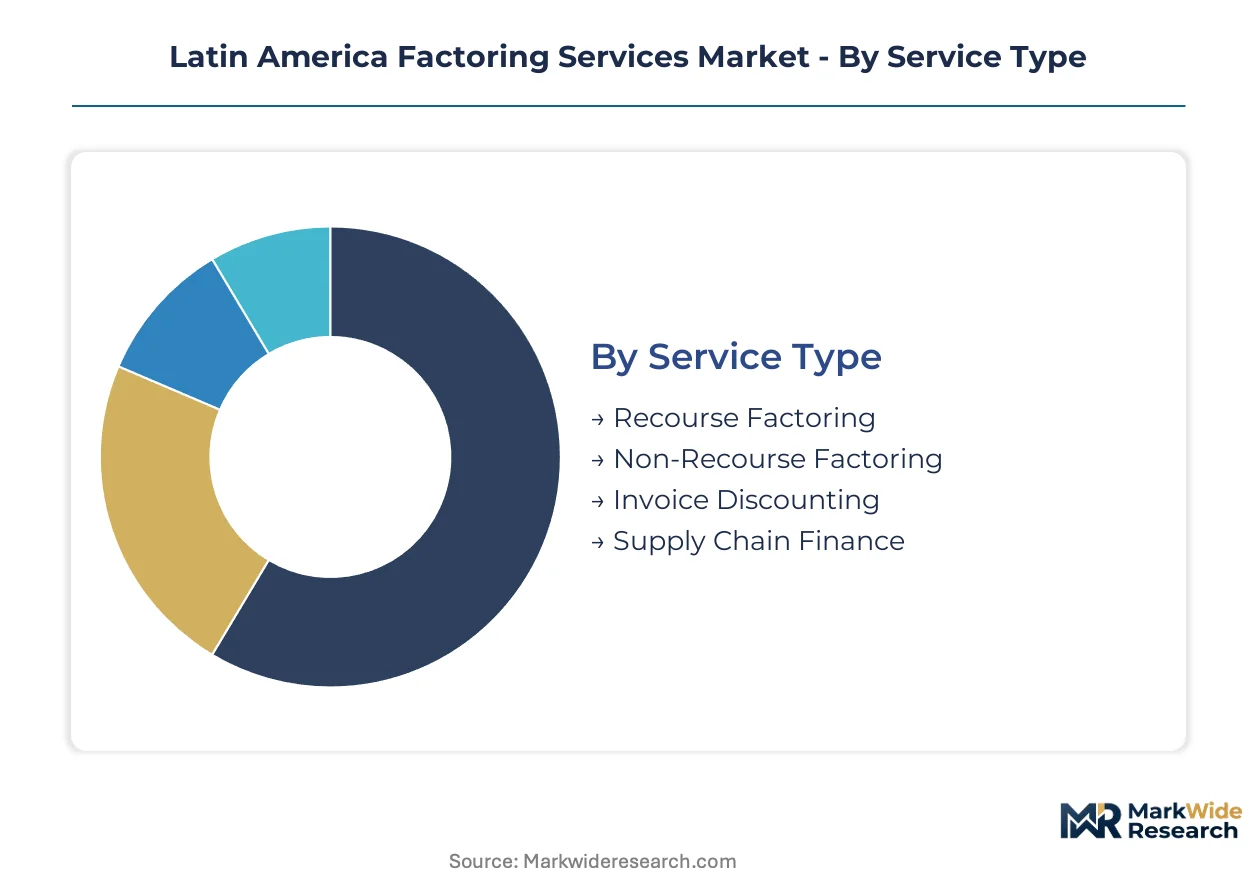
Factoring services in Latin America fragment across risk transfer mechanisms, client scale, and industry application. Each dimension shapes origination infrastructure, pricing power, and platform technology requirements differently across Brazil, Mexico, and Chile.
Service Type:
Recourse structures dominate SME liquidity provision while non-recourse offerings concentrate among investment-grade corporate relationships.
- Recourse Factoring:Sellers retain buyer default exposure, enabling platforms to price aggressively for mid-market Brazilian manufacturers with thin margins. Central bank e-invoice validation in São Paulo's industrial corridor compresses verification costs for high-volume domestic programs.
- Non-Recourse Factoring:Credit risk transfers entirely to the factor, commanding premium spreads justified by buyer creditworthiness assessment. Chilean regulators mandate capital reserves that constrain fintech entrants from competing with bank-led programs for large enterprise clients.
- Invoice Discounting:Confidential structures preserve supplier-buyer relationships in Mexico's northern industrial states where transparency risks contract renegotiation.
- Supply Chain Finance:Reverse factoring anchored to buyer credit ratings extends payment terms while accelerating supplier cash conversion.
Established volume favors recourse structures; emerging adoption favors supply chain finance.
Customer Type:
Client scale determines origination channel economics and regulatory compliance intensity across national markets.
- SMEs:Fragmented demand across Argentina's inflationary environment drives platform specialization in automated underwriting pipelines. API-enabled verification reduces acquisition costs for Chilean fintechs serving mid-market manufacturing clients.
- Large Enterprises:Multi-currency receivable programs require bank infrastructure for cross-border settlement. BNP Paribas anchors regional trade finance capabilities for corporates with Asia-Latin America exposure.
- Corporates:Embedded ERP integration captures transaction data upstream of invoice generation, compressing origination timelines.
- Public Sector:Government payment term standardization creates predictable receivable profiles with sovereign risk characteristics.
SME liquidity compression accelerates fastest; corporate embedded finance climbs the fastest.
Industry Vertical:
Sector cash conversion cycles and buyer concentration shape factoring penetration depth.
- Manufacturing:Brazil's automotive parts suppliers leverage e-invoice frameworks for domestic recourse programs with 24-48 hour advance timelines.
- Retail:Large São Paulo retailers embed pre-approved factoring within procurement workflows, unbundling payment terms from supplier financing.
- Construction:Extended project milestones and retention clauses create receivable maturity mismatches that limit standard factoring applicability.
- Transportation:Fleet operators in Mexico's northern corridor utilize freight bill factoring against confirmed delivery documentation.
Manufacturing concentration sustains volume leadership; retail procurement digitization gains share fastest.
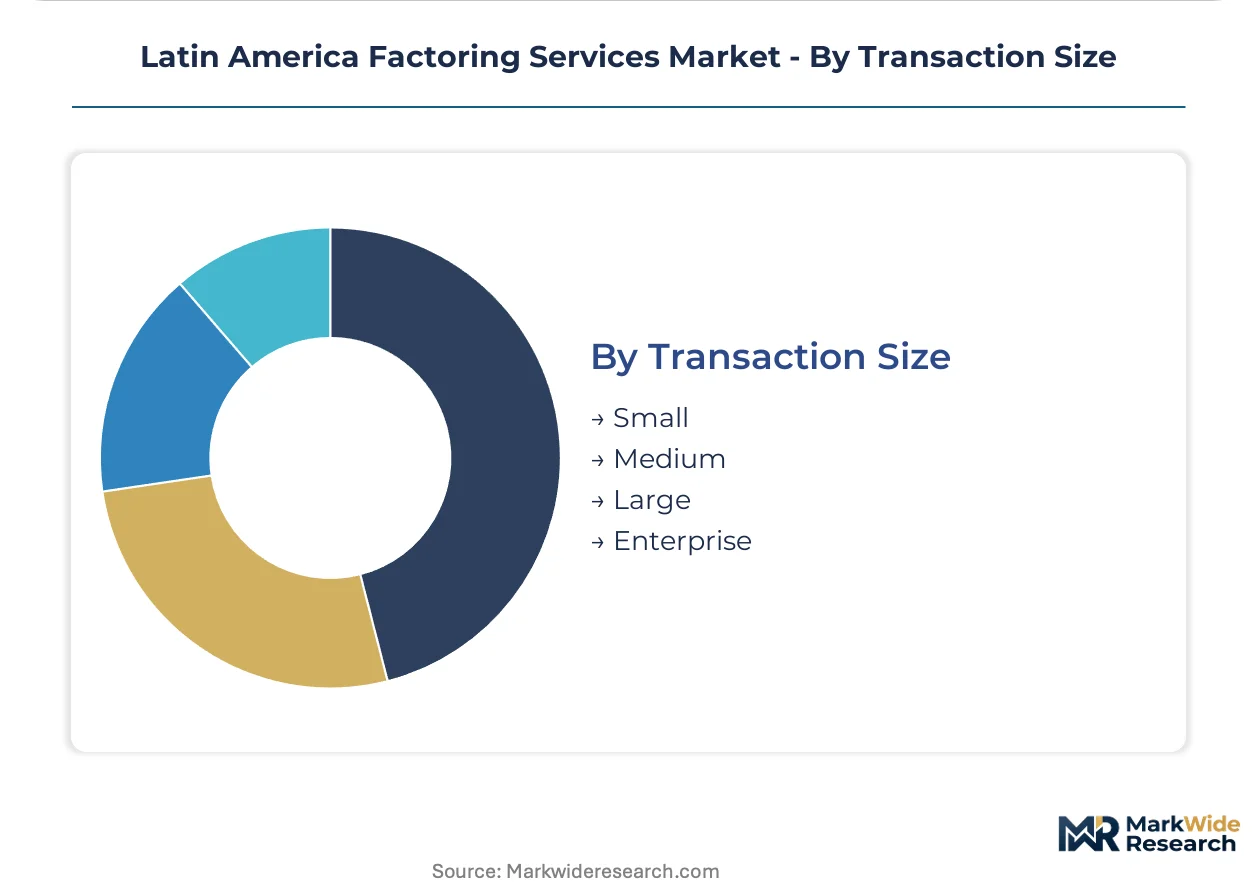
Transaction Size:
Deal scale segments origination technology requirements and risk management infrastructure.
- Small:Automated decision engines process sub-threshold applications without manual underwriting intervention.
- Medium:Chilean mid-market platforms combine alternative data streams with traditional bureau scores for hybrid assessment.
- Large:Dedicated relationship management justifies customized advance rates and collection protocols.
- Enterprise:Multi-jurisdictional programs require compliance with Brazil's central bank, Mexico's CNBV, and Chile's financial market regulator frameworks simultaneously.
Medium transaction automation expands most quickly; enterprise multi-currency complexity sustains premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's central bank anchors the dominant geography through electronic invoice validation standards that compress origination timelines across São Paulo's industrial corridor.
Brazil
SME liquidity compression from elongated payment terms accelerates invoice-backed working capital demand. The central bank's e-invoice framework mandates real-time receivable verification for domestic factoring platforms. Automotive parts suppliers in São Paulo's manufacturing belt leverage 24-48 hour advance structures against validated electronic invoices.
Mexico
Cross-border trade receivables in northern industrial states require faster liquidity conversion for supplier cash flow stability. CNBV electronic invoicing mandates standardize documentation formats for cross-border receivable programs. Manufacturing clusters in Nuevo León and Baja California restructure working capital around streamlined authentication protocols.
Chile
API-enabled verification through open banking interfaces reduces receivable authentication costs for mid-market platforms. The financial market regulator mandates API standardization interfacing directly with central tax authority databases. Manufacturing exporters in Santiago's metropolitan region exploit these streamlined protocols for domestic factoring origination.
Argentina
Inflationary pressures drive platform specialization in automated underwriting pipelines for fragmented SME demand. The central bank imposes capital controls creating settlement delays for multi-currency programs spanning Mercosur corridors. Agricultural supply chains in Buenos Aires province retain paper-based legacy systems with double-financing exposure risks.
Colombia
Freight bill factoring against confirmed delivery documentation serves fleet operators in key logistics corridors. The national tax authority's electronic invoicing rollout progresses without centralized registry infrastructure for agricultural receivables. Coffee and flower exporters in Antioquia and Valle del Cauca face persistent invoice fraud exposure in legacy verification systems.
Latin America Factoring Services Market Competitive Landscape
Global banking conglomerates and specialized domestic platforms split the market along cross-border capability versus high-volume domestic execution. The vendor base concentrates around trade finance infrastructure holders and fintech-enabled originators with automated underwriting pipelines. Two strategic archetypes dominate: multinational banks with multi-currency settlement networks, and regional specialists with deep local receivable verification relationships. Competitive moves center on embedded ERP integration partnerships and real-time payment rail connectivity.
Among global banking archetypes, BNP Paribas and HSBC Group anchor multi-currency receivable programs for corporates with cross-border exposure, while BTG Pactual exemplifies the domestic specialist model focused on high-volume Brazilian industrial clients. These three entities occupy distinct positioning vectors—international trade finance infrastructure, integrated supply chain finance offerings, and concentrated local market depth—without overlapping strategic territory.
| Leading Market Players |
|---|
| BTG Pactual |
| Barclays Plc |
| BNP Paribas |
| HSBC Group |
| Deutsche Factoring Bank |
| FINAMCO |
| Hitachi Capital (UK) PLC |
| Accion International |
| Expocredit |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Chile's mid-market factoring segment drives aggressive advance-rate competition among digital originators while compressing margins for traditional bank-led programs across the Andean corridor. This utilization imbalance shapes supplier consolidation incentives and pricing discipline simultaneously.
Pricing Analysis
Brazil-Mexico price spreads for non-recourse factoring exceed those for recourse structures by substantial margins, reflecting buyer credit assessment complexity. Three-tier pricing structure across premium non-recourse, standard recourse, and economy invoice discounting levels dominates the market. Pricing pressure stems from API-enabled verification cost compression in Chile's open banking environment. SMEs in Argentina's inflationary economy exhibit highest price sensitivity; large enterprises with investment-grade counterparties show lowest.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina dominates supply chain risk calculations for cross-border receivable programs spanning Mercosur corridors. Geographic supply concentration centers on Brazil, Mexico, and Chile as the three primary origination hubs. Raw material dependencies include electronic invoice validation infrastructure, credit bureau data feeds, and real-time payment rail connectivity. Single-source vulnerability characterizes Brazil's Pix settlement dominance for same-day advances. Distribution runs through bank-fintech partnership channels and embedded ERP integration pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a cyclical recovery anchored to central bank electronic invoice modernization cycles across the region's three largest economies.
For Market Incumbents: Insulate core receivable portfolios from fintech disintermediation by deepening ERP integration partnerships with São Paulo manufacturing clusters. Accelerate certification investment for Chile's API standardization mandates. Vertical integration into real-time payment rails preserves advance-rate pricing power against API-native competitors.
For New Entrants and Emerging Players: Peruvian mining supply chains and Colombian agricultural corridors represent the most penetrable entry points for commodity-linked underwriting specialization. Target mid-market transportation operators in Mexico's northern freight corridors with freight bill factoring against confirmed delivery documentation. Go-to-market execution should anchor to embedded procurement platform partnerships rather than direct bank channel competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated underwriting platforms with Chilean open banking API connectivity. Long-term viability favors acquisition targets combining domestic verification depth with cross-border settlement capability. Monitor Brazil's central bank e-invoice framework expansion as the primary inflection indicator for regional platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded ERP Integration | Direct origination through SAP and Oracle workflows captures transaction data upstream of invoice generation in São Paulo manufacturing. |
| API Standardization Compliance | Chile's financial market regulator mandates eliminate manual document submission for domestic factoring origination. |
| Real-Time Payment Rail Connectivity | Brazil's Pix infrastructure enables same-day advance disbursement, compressing cash conversion cycles for domestic programs. |
| Blockchain Invoice Registry Pilot | Hybrid systems with existing e-invoice infrastructure prevent double-pledging fraud among Brazilian industrial distributors. |
| Cross-Border Settlement Infrastructure | Multi-currency receivable programs require bank infrastructure for Asia-Latin America trade corridor exposure. |
Research Methodology
Cross-validation between primary interviews with factoring platform executives and secondary analysis of central bank regulatory filings anchors the qualitative findings. Stakeholder engagement spans chief risk officers at regional banks, fintech origination heads, SME finance directors in São Paulo and Nuevo León, and trade finance specialists at multinational institutions. Secondary sources include Brazil's central bank e-invoice statistics, Mexico's CNBV fintech licensing records, Chile's financial market regulator API standards documentation, and customs trade data for cross-border receivable flows. Bottom-up transaction volume estimates triangulate against top-down banking sector asset growth across the analysis window.
Calibration against historical electronic invoice adoption curves and real-time payment infrastructure deployment timelines shapes the projection framework. Segmentation dimensions model service type, customer scale, industry vertical, and transaction size across national regulatory clusters. CAGRs derive from regression analysis of origination volume against macroeconomic liquidity indicators and SME credit gap estimates. Industry-specific inputs include central bank e-invoice validation penetration rates and open banking API adoption curves.
Macroeconomic conditions sit as an overlay; deviation in Brazilian industrial output, Mexican peso volatility, or Argentine inflation trajectories would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory framework stability and payment infrastructure continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
United States Payroll Services Market
Financial Services
Account Aggregators Market
Financial Services
Silver Economy Market
Financial Services
Cash Flow Market
Financial Services
Billing and Revenue Management Market
Financial Services
South Korea Factoring Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Solar Powered ATM Market
Financial Services
Commercial Debt Collection Software Market
Financial Services
Pawn Shop Market
Financial Services
ATM Software Market
Financial Services
Germany E-Brokerage Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Mobile Notary Service Market