
 Africa Factoring Services Market | 2026-2036
Africa Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Factoring Services Market Insights
Receivables-based working capital solutions is rewriting how African SMEs access liquidity outside traditional collateral requirements. Afreximbank anchors pan-African trade finance corridors through its specialized factoring facilities. FirstRand Bank leverages its retail banking footprint to originate invoice-discounting volumes at scale. Société Générale competes through correspondent banking ties with Francophone West African institutions.
Factoring services constitute a form of accounts-receivable financing wherein a financial entity purchases unpaid invoices at a discount, assuming collection risk or providing advance liquidity against future payment streams, typically operating on 30- to 120-day commercial terms. Recourse factoring dominates transaction volumes across African markets due to lower pricing and reduced capital charges for originators. Non-recourse factoring is gaining traction among export-oriented SMEs seeking balance-sheet protection against buyer default. Supply chain finance occupies the premium margin tier as anchor buyers extend approved-payable financing to tiered supplier bases.
South Africa's Financial Sector Conduct Authority and Nigeria's Central Bank govern licensing and capital adequacy for domestic factoring operations, while the Afreximbank Model Law on Secured Transactions harmonizes cross-border receivables perfection across signatory states. Kenya's Capital Markets Authority has introduced guidelines for digital lending platforms that directly affect invoice-discounting fintech channels. Stakeholders must monitor regulatory divergence between common-law and OHADA civil-law jurisdictions as this friction determines enforceability of cross-border assignment mechanisms.
Market Dynamics
Digital KYC protocols and mobile money rails are compressing origination costs for invoice-discounting providers, enabling penetration into previously unbanked SME segments across the continent.
Growth Catalysts
- Mobile money integration:M-Pesa and comparable platforms in Kenya, Nigeria, and Ghana enable real-time disbursement and repayment tracking, collapsing traditional settlement timelines from days to minutes.
- Afreximbank Model Law on Secured Transactions:This harmonized framework across signatory states streamlines cross-border receivables perfection, reducing legal uncertainty for pan-African factoring operations.
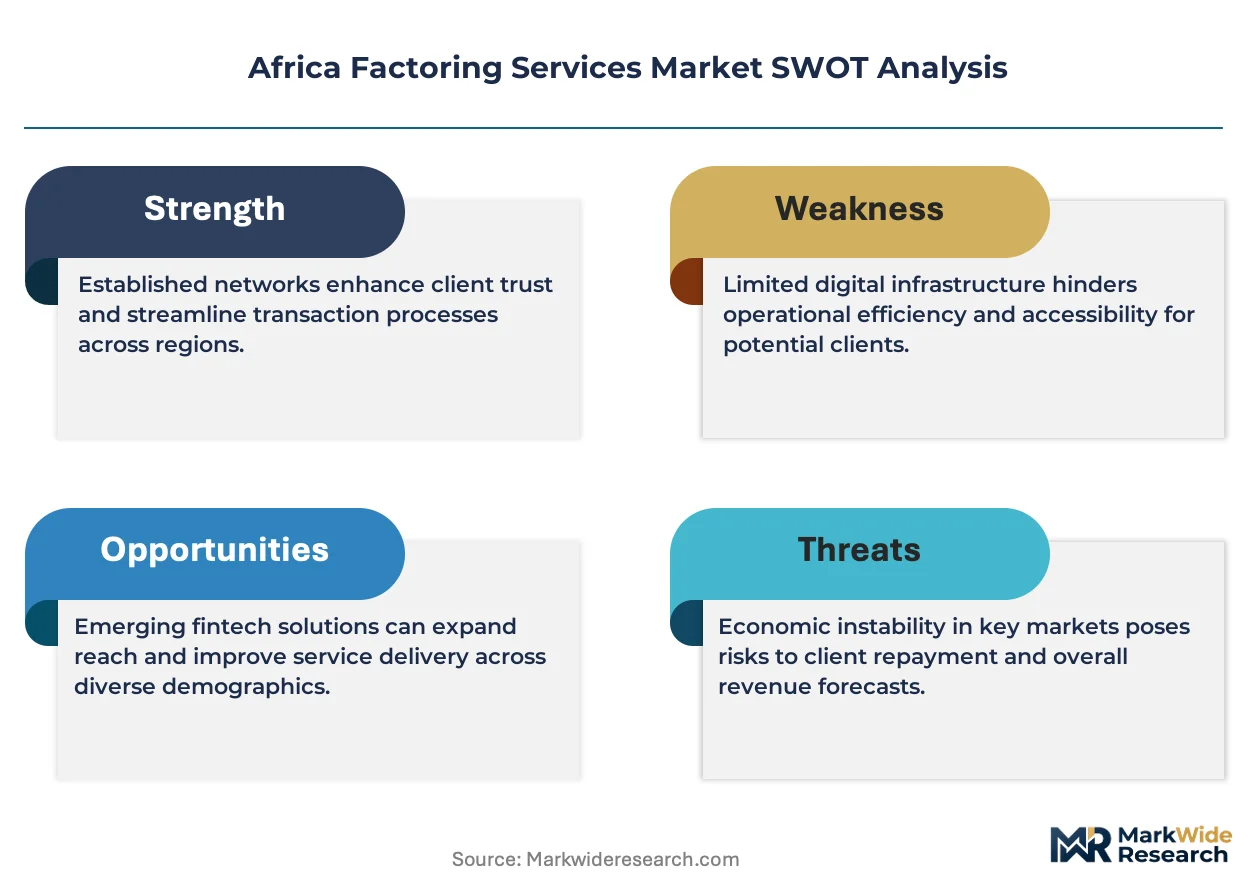
- SME working capital gaps:Traditional collateral requirements exclude vast swaths of African traders; receivables-based financing unlocks liquidity tied up in 30- to 120-day commercial invoices.
Market Restraints
- Buyer credit information scarcity:Limited centralized credit bureaus in Francophone West Africa and parts of East Africa elevate default assessment costs for non-recourse factoring structures.
- Currency volatility:Naira, Kenyan shilling, and Ghana cedi fluctuations compress margins on cross-border invoice portfolios and complicate hedging for foreign-denominated receivables.
- Legal system divergence:Common-law assignment mechanisms in Nigeria and Kenya conflict with OHADA civil-law frameworks in Côte d'Ivoire and Senegal, fragmenting enforceability standards.
Strategic Opportunities
- Ethiopia's banking liberalization:Opening of the financial sector to private and foreign participation creates first-mover advantage for factoring entrants before domestic competition matures.
- Supply chain finance digitization:Integration of blockchain-based invoice verification with existing ERP systems allows anchor buyers to extend approved-payable financing deep into tiered supplier bases.
- Export credit agency partnerships:Collaboration with national ECAs covering South African, Nigerian, and Egyptian exporters enables non-recourse structures previously uneconomical at private risk pricing.
Industry Challenges
- Data science talent scarcity:Shortage of credit risk modelers familiar with African SME cash flow patterns limits automated underwriting scale-up outside South Africa and Kenya.
- Legacy core banking integration:Domestic banks in secondary markets operate on decades-old IT infrastructure, complicating API connectivity for digital factoring platforms seeking partnership distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Factoring Services Market |
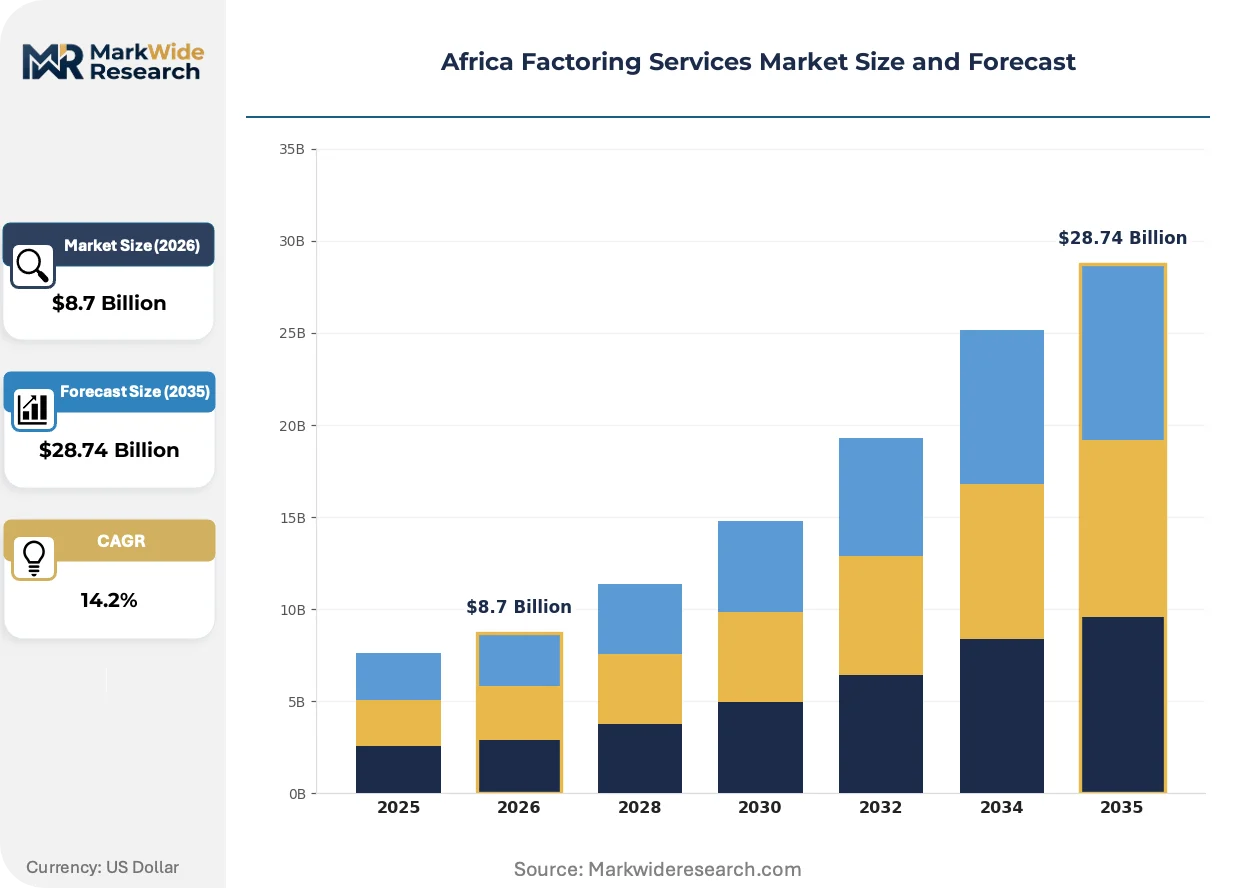
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-recourse Factoring, Invoice Discounting, Supply Chain Finance End User: SMEs, Corporations, Startups, Enterprises Industry Vertical: Manufacturing, Wholesale Trade, Retail, Services Financial Instrument: Receivables Financing, Trade Finance, Working Capital Loans, Others |
| Companies Covered | NMB Bank, BNP Paribas, Afreximbank, HSBC Group, Deutsche Bank, FirstRand Bank, Société Générale, Velotrade, Stanbic Bank, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Factoring Services Market Trends and Innovations
Technology convergence between alternative data scoring and mobile disbursement infrastructure is rewriting origination economics for receivables financing across the continent.
Machine learning models trained on mobile money transaction histories, utility payment patterns, and logistics data are rendering obsolete traditional collateral-based credit assessment for African SME lending. Fintech originators in Lagos and Nairobi deploy these tools to underwrite nano-invoices below $500, a segment banks historically ignored. The compression in customer acquisition costs is enabling unit economics that support sustainable expansion into peri-urban and rural trading corridors.
Kenya's Capital Markets Authority guidelines for digital lending platforms impose capital buffers and disclosure requirements on invoice-discounting channels operating through mobile apps. The regulation forces platform operators to segregate client funds and publish standardized pricing, elevating compliance costs for thinly capitalized entrants. Established players with existing banking partnerships absorb these requirements more efficiently, accelerating consolidation toward regulated balance-sheet lenders.
Anchor buyers in Nigerian agriculture and South African retail are unbundling working capital support from traditional supplier relationships, directly financing tiered vendor bases through dynamic discounting platforms. Procurement teams at these large corporates now treat early payment as a yield instrument rather than a commercial concession. This behavior shift is most visible in Gauteng and Lagos industrial zones, where supplier finance programs have displaced conventional 90-day open-account terms for mid-sized vendors.
Africa Factoring Services Market Segmentation
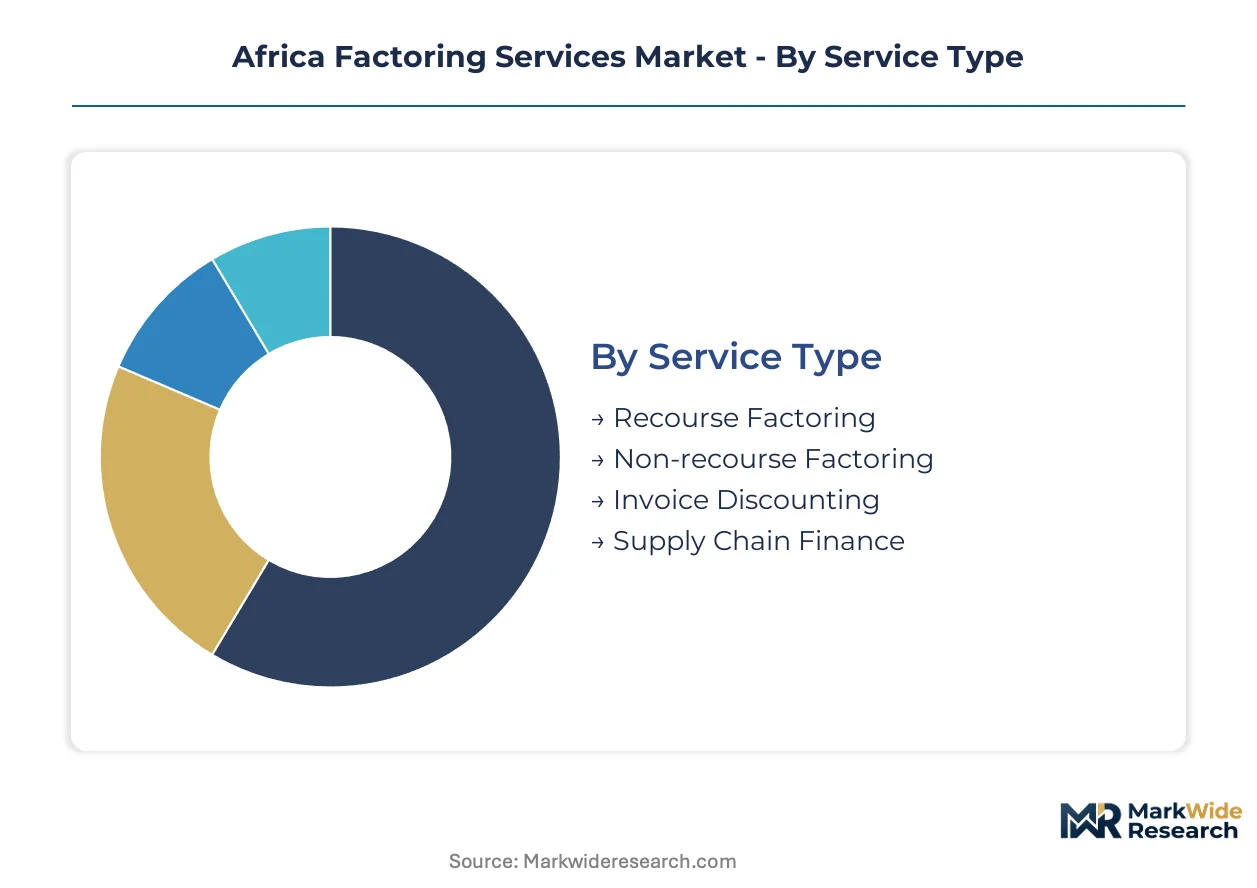
Service differentiation in African factoring correlates directly with after-sales collection intensity and buyer credit monitoring requirements. Providers structure offerings around who bears default risk and how deeply they embed into client cash conversion cycles.
Service Type:
After-sales collection intensity separates recourse from non-recourse structures, determining pricing spreads and capital allocation across provider balance sheets.
- Recourse Factoring:The seller retains buyer default risk, allowing providers to price advances at narrower spreads and hold lower regulatory capital. Nigerian and Kenyan banks dominate transaction volumes through this structure, using it to serve established SME trading relationships without deep credit bureau coverage.
- Non-recourse Factoring:The factor assumes full buyer default risk, commanding premium pricing that reflects intensive credit assessment of underlying obligors. South African providers lead here, leveraging sophisticated corporate credit data to protect export-oriented SME clients against buyer insolvency.
- Invoice Discounting:Confidential financing where the seller retains collection responsibility, functioning as secured lending against receivable pools rather than true factoring. Ghanaian agricultural traders favor this for supplier relationship preservation.
- Supply Chain Finance:Anchor-buyer-led programs extending approved-payable financing to tiered vendors, with reverse factoring structures that monetize large corporate credit ratings for SME liquidity.
Recourse factoring holds the largest share; momentum sits with supply chain finance as anchor buyers digitize vendor programs.
End User:
Cost tier segmentation reflects origination economics, with automated underwriting enabling penetration below traditional banking minimums.
- SMEs:Fragmented trading businesses with invoice sizes from $500 to $50,000, historically excluded by collateral requirements. Mobile money rails and alternative data scoring now unlock this segment across Lagos, Nairobi, and Accra trading corridors.
- Corporations:Mid-sized enterprises with annual turnover above $10 million, seeking multi-currency receivables programs across intra-African trade lanes. These clients drive demand for cross-border assignment mechanisms under Afreximbank Model Law jurisdictions.
- Startups:Venture-backed technology and logistics ventures with limited operating history but predictable revenue streams. Kenyan fintech lenders have developed specialized products for this cohort using real-time transaction data.
- Enterprises:Large domestic and multinational corporations with complex subsidiary structures requiring centralized liquidity management. South African mining and retail groups dominate this tier, using factoring as treasury optimization rather than core funding.
Corporations anchor current volumes; startups are expanding most quickly as digital platforms collapse acquisition costs.
Industry Vertical:
Application concentration tracks trade finance infrastructure maturity, with manufacturing and wholesale trade dominating where invoice verification systems exist.
- Manufacturing:Capital-intensive production with extended supplier payment terms, generating predictable receivable streams. Nigerian cement and South African automotive suppliers represent core demand clusters.
- Wholesale Trade:Import-dependent distribution with high invoice velocity and thin margins requiring working capital efficiency. East African agricultural commodity traders exemplify this vertical's financing intensity.
- Retail:Seasonal inventory builds and promotional financing needs, with South African formal retail chains driving supply chain finance adoption.
- Services:Professional and logistics services with intangible collateral, historically underserved but now accessible through contract-based invoice verification.
Wholesale trade holds the largest share; services are gaining share fastest as digitization enables contract monetization.
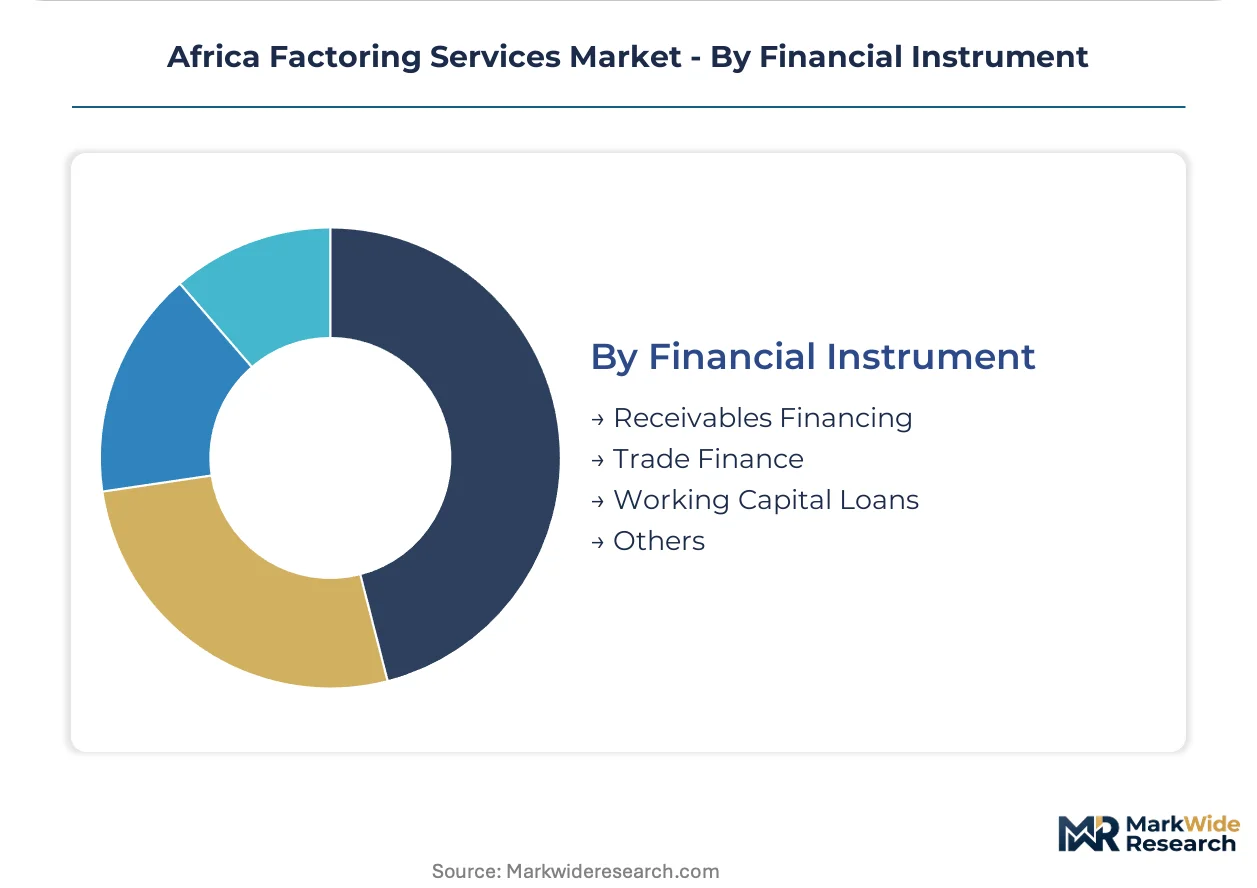
Financial Instrument:
Margin structure varies by instrument maturity, with short-dated receivables financing commanding tighter spreads than structured trade finance.
- Receivables Financing:Direct purchase or lending against specific invoices, the foundational product across all African markets. Kenyan mobile-integrated platforms have compressed origination costs dramatically in this category.
- Trade Finance:Documentary and open-account instruments supporting cross-border transactions, dominated by Afreximbank facilities and commercial bank letters of credit.
- Working Capital Loans:General-purpose liquidity facilities secured by receivable pools rather than specific invoices, functioning as revolving credit with borrowing base certificates.
- Others:Forfaiting, export credit insurance-linked structures, and hybrid instruments blending factoring with supply chain finance elements.
Receivables financing holds the largest share; trade finance shows the steepest expansion trajectory as intra-African commerce accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factoring providers cluster in markets with mature trade finance infrastructure and digital payment rails. Nigeria, South Africa, Kenya, Ghana, and Egypt generate the bulk of transaction volumes due to concentrated SME trading corridors and progressive regulatory frameworks.
Nigeria
Domestic invoice discounting surges among Lagos-based commodity traders facing 90-day payment cycles. The Central Bank of Nigeria governs licensing and capital adequacy for non-bank financial institutions offering receivables financing. Kano's agricultural wholesale markets anchor northern expansion as cotton and sesame exporters adopt mobile-verified invoice platforms.
South Africa
Sophisticated corporate credit data enables non-recourse structures for export-oriented manufacturing SMEs. The Financial Sector Conduct Authority mandates disclosure standards and conduct rules for factoring intermediaries. Gauteng's industrial zones concentrate supply chain finance adoption as mining and retail anchor buyers digitize vendor payment programs.
Kenya
M-Pesa integration collapses disbursement timelines for micro-invoice financing below $500. The Capital Markets Authority imposes capital buffers and client fund segregation on digital lending platforms operating invoice-discounting channels. Nairobi's technology corridor drives startup-focused receivables products using real-time transaction data.
Ghana
Cocoa and gold exporters drive demand for foreign-currency receivables financing against Euro-denominated contracts. The Bank of Ghana regulates capital requirements for domestic factoring operations under broader non-bank financial institution frameworks. Accra-Tema port corridor traders adopt confidential invoice discounting to preserve supplier relationships.
Egypt
Import-dependent manufacturing SMEs leverage factoring against letters of credit to bridge working capital gaps. The Central Bank of Egypt supervises factoring companies under specialized non-bank financial services licensing introduced in recent years. Alexandria's textile and food processing clusters represent emerging demand pockets as digital verification tools penetrate traditional trading networks.
Africa Factoring Services Market Competitive Landscape
Pan-African development banks and international commercial lenders split the market between policy-driven trade finance and profit-motivated receivables origination. Tier-1 global banks, regional banking groups, and specialized fintech platforms constitute three strategic archetypes. Consolidation accelerates through correspondent banking partnerships and API-based distribution agreements with mobile money operators.
Within the development bank tier, Afreximbank anchors cross-border receivables perfection across signatory states. Among regional banking groups, FirstRand Bank and Société Générale occupy positions reflecting their respective retail footprints in Southern Africa and Francophone West Africa. These named entities exemplify how geographic coverage and regulatory relationships determine competitive positioning.
| Leading Market Players |
|---|
| NMB Bank |
| BNP Paribas |
| Afreximbank |
| HSBC Group |
| Deutsche Bank |
| FirstRand Bank |
| Société Générale |
| Velotrade |
| Stanbic Bank |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Ethiopian factoring infrastructure drives premium pricing for first-mover providers while compressing margins in oversaturated Nigerian corridors where mobile-enabled competition intensifies. The divergence between frontier-market scarcity and mature-market saturation shapes both supplier entry decisions and buyer procurement strategies across the continent.
Pricing Analysis
The Afreximbank Model Law on Secured Transactions dictates the pricing tier structure by harmonizing cross-border receivables perfection costs across signatory states. Recourse factoring commands narrower spreads reflecting seller-retained default risk, while non-recourse structures price at substantial premiums due to intensive buyer credit assessment. Price differentiation rests on after-sales collection intensity and mobile money integration depth. Pricing pressure stems from M-Pesa-enabled fintech entrants collapsing origination costs in Kenyan micro-invoice segments. SMEs with invoice sizes below $2,000 exhibit highest price sensitivity, whereas South African mining groups treat supply chain finance as treasury yield instruments with minimal elasticity.
Supply Chain Analysis
FirstRand Bank, Société Générale, and Afreximbank hold dominant origination capacity across Southern Africa, Francophone West Africa, and pan-African corridors respectively. Supply concentrates in Nigeria, South Africa, and Kenya where trade finance infrastructure maturity enables scalable receivables purchasing. Raw material dependencies include mobile money transaction data, alternative credit scoring algorithms, and ERP integration modules for invoice verification. Single-source vulnerability runs through M-Pesa's disbursement rails in East African markets where platform downtime halts real-time settlement. Distribution runs through correspondent banking partnerships with domestic lenders and API-based integration with mobile network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile money integration and digital KYC protocols are disrupting traditional collateral-based lending, creating asymmetric growth opportunities for technology-enabled receivables providers against legacy banking infrastructure.
For Market Incumbents: Entrench market position through backward integration into mobile money disbursement infrastructure and exclusive data partnerships with MNOs. FirstRand Bank and Société Générale should deepen API connectivity with domestic banks in secondary markets to preempt fintech distribution capture. Threat from Kenyan and Nigerian digital lending platforms with automated underwriting mandates immediate defensive investment in machine learning credit models. For New Entrants and Emerging Players: Ethiopia's banking liberalization represents the most penetrable white-space opportunity before domestic competition matures. Target agricultural wholesale corridors in Kano and cotton export networks where mobile-verified invoice platforms remain undeployed. Go-to-market angle should anchor on supply chain finance partnerships with anchor buyers in Nigerian cement and South African retail, leveraging reverse factoring structures to monetize corporate credit ratings for tiered vendor liquidity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among supply chain finance providers with embedded anchor-buyer relationships and multi-year vendor program contracts. Long-term viability favors platforms combining balance-sheet lending licenses with proprietary alternative data scoring capabilities. Acquisition target archetype: Kenyan or Nigerian fintech originators with demonstrated mobile money integration and regulatory capital buffers meeting Capital Markets Authority requirements. Signal to watch is regulatory divergence between common-law and OHADA jurisdictions affecting cross-border assignment enforceability.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Money Infrastructure Partnership | API integration with M-Pesa and comparable platforms collapses disbursement timelines from days to minutes. |
| Alternative Data Scoring Development | Machine learning models trained on utility payments and logistics data render traditional collateral obsolete for SME underwriting. |
| Cross-Border Regulatory Harmonization | Afreximbank Model Law adoption reduces legal uncertainty for pan-African receivables perfection and assignment. |
| Anchor Buyer Supply Chain Programs | Reverse factoring structures monetize FirstRand Bank and Société Générale credit ratings for tiered vendor financing. |
| Digital KYC Protocol Deployment | Automated identity verification compresses customer acquisition costs for previously unbanked SME segments. |
Research Methodology
Initial hypotheses were tested against primary input from factoring operations executives, mobile money platform engineers, SME trade finance officers, and central bank non-bank financial institution supervisors and refined through secondary validation. Sources included Afreximbank trade finance disclosures, Central Bank of Nigeria regulatory circulars, Kenya Capital Markets Authority digital lending guidelines, and pan-African mobile money transaction reports. Bottom-up invoice volume estimates from Lagos, Nairobi, and Johannesburg trading corridors were triangulated against top-down banking sector receivables financing data.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompass service type differentiation, end-user cost tier, industry vertical concentration, and financial instrument maturity structure. CAGRs were derived from invoice velocity growth rates, mobile money penetration curves, and SME working capital gap estimates. Industry-specific inputs included M-Pesa transaction volume trajectories, Afreximbank Model Law adoption timelines, and Ethiopian banking sector liberalization progress.
The forecast holds incumbent behavior within observed patterns; aggressive technology investment by Kenyan fintech platforms or accelerated Ethiopian market entry by South African banking groups would shift outcomes. Regulatory fragmentation between common-law assignment mechanisms and OHADA civil-law frameworks poses specific revision risk. Quarterly review of mobile money transaction growth, central bank factoring licensing activity, and anchor buyer supply chain program launches is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
South Korea Factoring Services Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
South Korea Trade Finance Market
Financial Services
Australia Online Gambling Market
Financial Services
Treasury Management Market
Financial Services
ATM Management Service Market
Financial Services
Mobile Notary Service Market
Financial Services
Global Management Consulting Services Market
Financial Services
Commodity Trade Finance Market
Financial Services
Global Treasury Software Market
Financial Services
Intermediary Service Market
Financial Services
White Glove Services Market
Financial Services
Virtual Account Management Software Market
Financial Services
North America Management Consulting Services Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Global Power Bank Rental Service Market