
 Outsource Debt Collection Services Market | 2026-2036
Outsource Debt Collection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outsource Debt Collection Services Market Insights
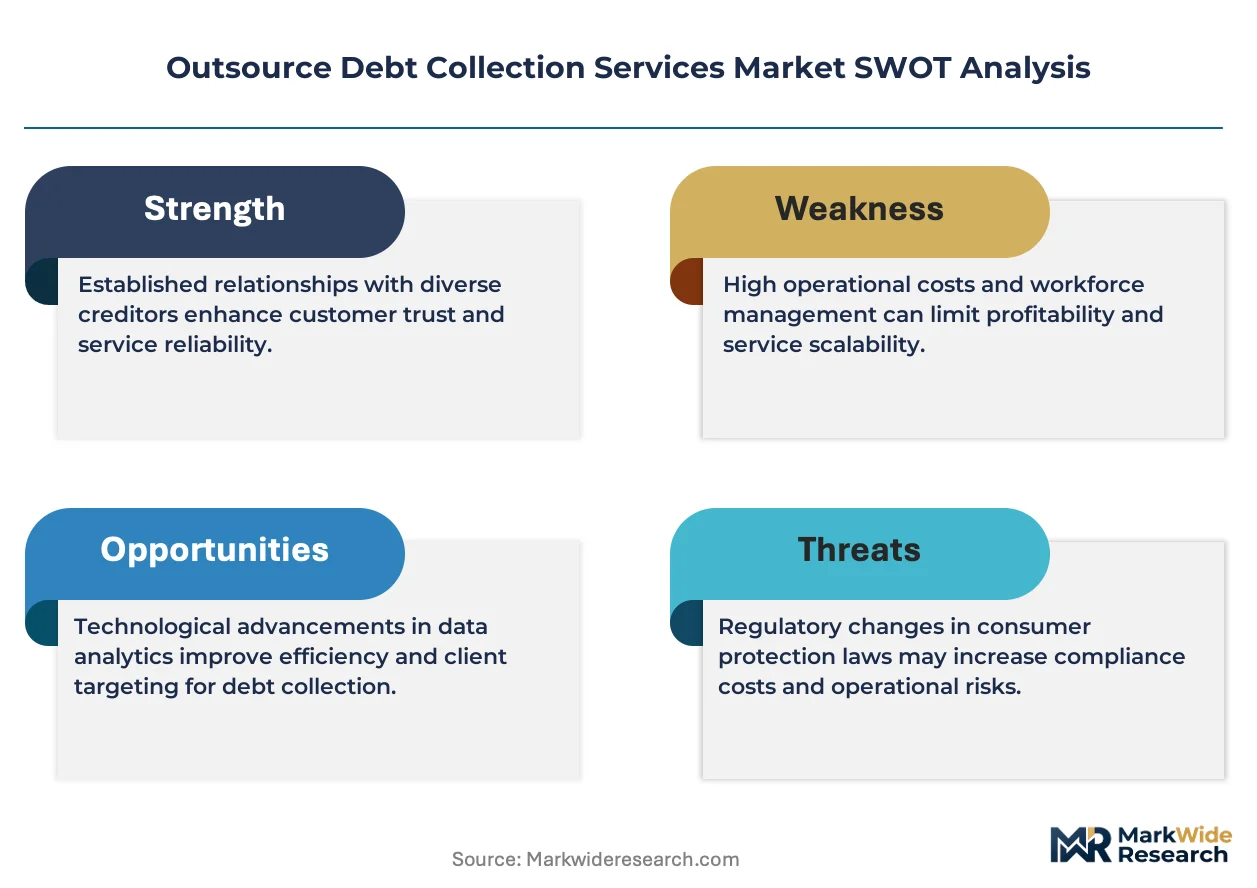
India's business process outsourcing sector is pivoting toward specialized debt recovery operations, building dedicated agent pools and compliance infrastructure for international clients. Encore Capital Group leverages predictive analytics and machine-learning scoring models to sustain recovery rates across credit card and consumer loan portfolios. PRA Group anchors its position through geographic diversification, operating collection centers across the Americas and Europe. Intrum AB differentiates via integrated credit management services that span prevention, monitoring, and recovery stages.
Outsource debt collection services encompass the delegation of receivables recovery to external specialists who employ systematic contact protocols, legal escalation pathways, and credit bureau reporting to extract payment from delinquent accounts. These services functionally replace or supplement internal collection departments, reducing fixed labor costs while applying scaled expertise to accounts across varying delinquency stages. Third-party collection and early stage recovery command the largest service volumes, though digital platform channels are expanding fastest as compliance constraints limit phone-based outreach. Financial institutions represent the most concentrated customer type by contract value, while contingency-based engagement models dominate revenue structures due to their performance-aligned incentive architecture.
The Consumer Financial Protection Bureau enforces debt collection conduct standards in the United States, while the EU's General Data Protection Regulation restricts personal data usage in contact strategies across European operations. India's Reserve Bank issues guidelines on fair practices for lenders and their collection agents, shaping outsourcing eligibility and vendor qualification requirements. Stakeholders must monitor regulatory divergence across operating jurisdictions while calibrating technology investments between automation efficiency and human intervention for complex negotiations.
Market Dynamics
Compliance automation platforms are compressing the operational gap between regulatory mandates and collection efficiency, forcing agencies to rebuild infrastructure around consent management and contact frequency controls rather than volume-based dialing.
Growth Catalysts
- Unsecured Lending Expansion:Credit card and buy-now-pay-later origination volumes in the United States, the United Kingdom, and India are generating fresh receivables pipelines requiring external recovery expertise.
- GDPR-Driven Infrastructure Investment:European collection operations are modernizing data governance frameworks to satisfy cross-border personal data transfer restrictions, creating vendor upgrade cycles.
- Machine-Learning Scoring:Predictive analytics engines are segmenting accounts by propensity-to-pay, enabling precision resource allocation across early-stage and late-stage recovery workflows.
Market Restraints
- Telephone Consumer Protection Act Friction:The TCPA's autodialer restrictions and consent documentation requirements are elevating legal exposure for voice-based outreach campaigns in the United States.
- Agent Labor Concentration:Fluent bilingual collectors with financial services domain expertise concentrate in Manila, Pune, and Mexico City, creating wage inflation and turnover vulnerability.
- Substitute Channel Displacement:Self-service digital payment portals and lender-managed early-stage SMS programs are capturing recoverable accounts before third-party assignment.
Strategic Opportunities
- Small-Business Receivables:B2B collection services for mid-market enterprises remain underpenetrated relative to consumer debt, with fragmented in-house operations creating outsourcing conversion potential.
- India's Offshore Scale:The Reserve Bank of India's fair practices code is maturing vendor qualification standards, positioning Indian BPOs for higher-value international contract tiers.
- AI-Enabled Voice Analytics:Real-time sentiment analysis converging with natural language processing is opening compliance-auditable alternatives to traditional call monitoring.
Industry Challenges
- Licensed Collector Pipeline:State-level collection agency licensing requirements in the United States create multi-jurisdiction compliance complexity and talent onboarding delays.
- Legacy System Integration:Core banking and loan servicing platforms at financial institutions often lack API-ready architectures, complicating real-time data exchange with external collection vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsource Debt Collection Services Market |
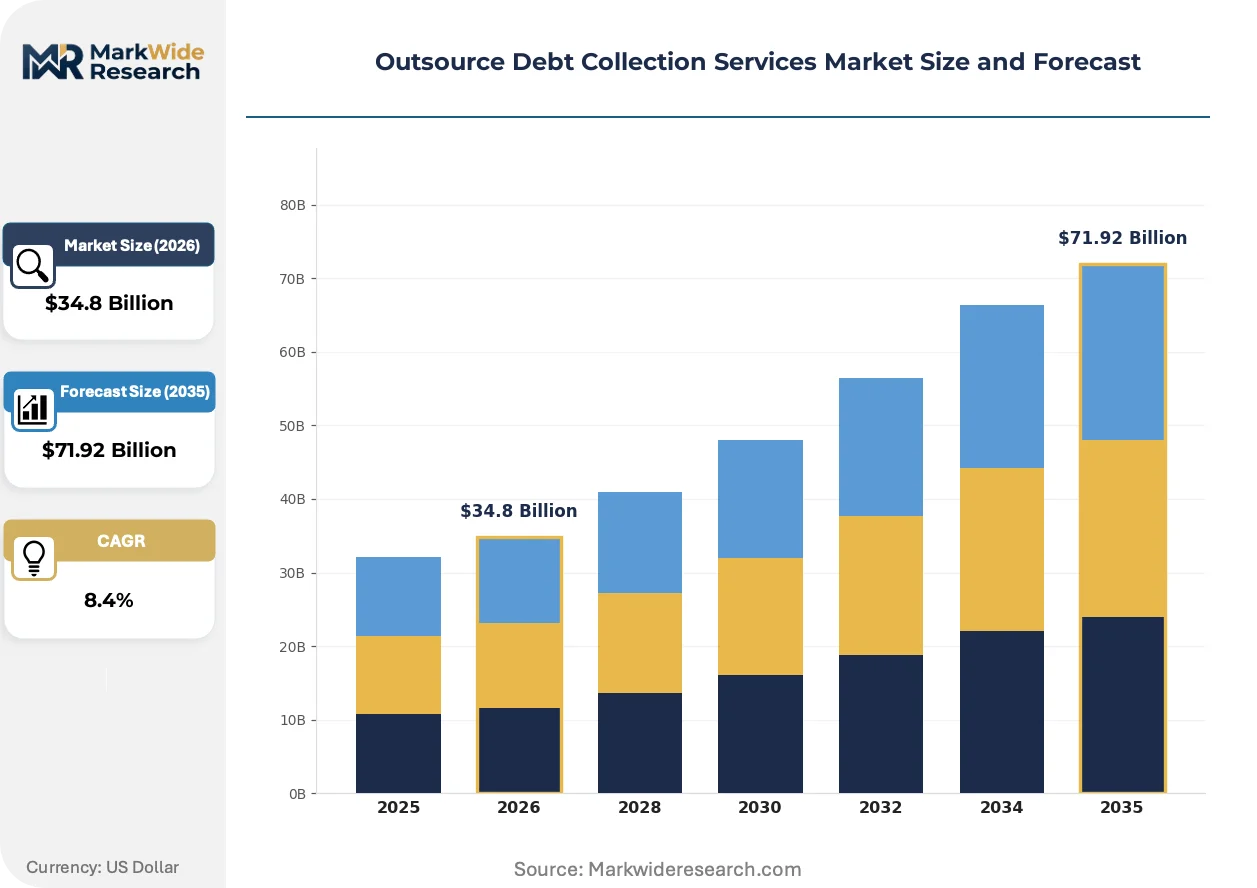
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $71.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: First-Party Collection, Third-Party Collection, Early Stage Recovery, Late Stage Recovery, Skip Tracing Customer Type: Small Businesses, Large Enterprises, Financial Institutions, Telecommunication Providers, Utilities Engagement Model: Contingency Based, Retainer Based, Flat Fee, Hourly Billing Channel: Phone Collection, Email Collection, SMS Collection, Postal Mail Collection, Digital Platforms |
| Companies Covered | Encore Capital Group, PRA Group, IC System, Atradius Collections, Fair Capital, Summit A/R, Intrum AB, EOS Group, Alorica Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsource Debt Collection Services Market Trends and Innovations
Digital-first contact protocols are displacing traditional phone-centric recovery models, with channel diversification and automation depth becoming the primary axes of competitive differentiation.
Conversational AI platforms are overtaking scripted interactive voice response systems in early-stage account engagement. Major credit card issuers in the United States are deploying these tools for payment arrangement negotiations. The technology is compressing cost-per-contact metrics while expanding compliant contact windows beyond traditional calling hours.
Europe's Digital Services Act and existing GDPR enforcement are tightening algorithmic transparency requirements for automated decision-making in debt recovery. Collection agencies operating across Germany, France, and Spain must now document scoring model logic for regulatory examination. Consumer finance subsidiaries are responding by segregating EU data processing within regional cloud infrastructure.
Contingency pricing structures face pressure from fixed-fee hybrid models as large financial institutions seek cost predictability. Tier-one banks in the United Kingdom are piloting monthly retainer arrangements with performance bonuses tied to net recovery rates rather than gross collections. This shift is most visible in credit card and personal loan portfolios where charge-off timing is standardized.
Outsource Debt Collection Services Market Segmentation
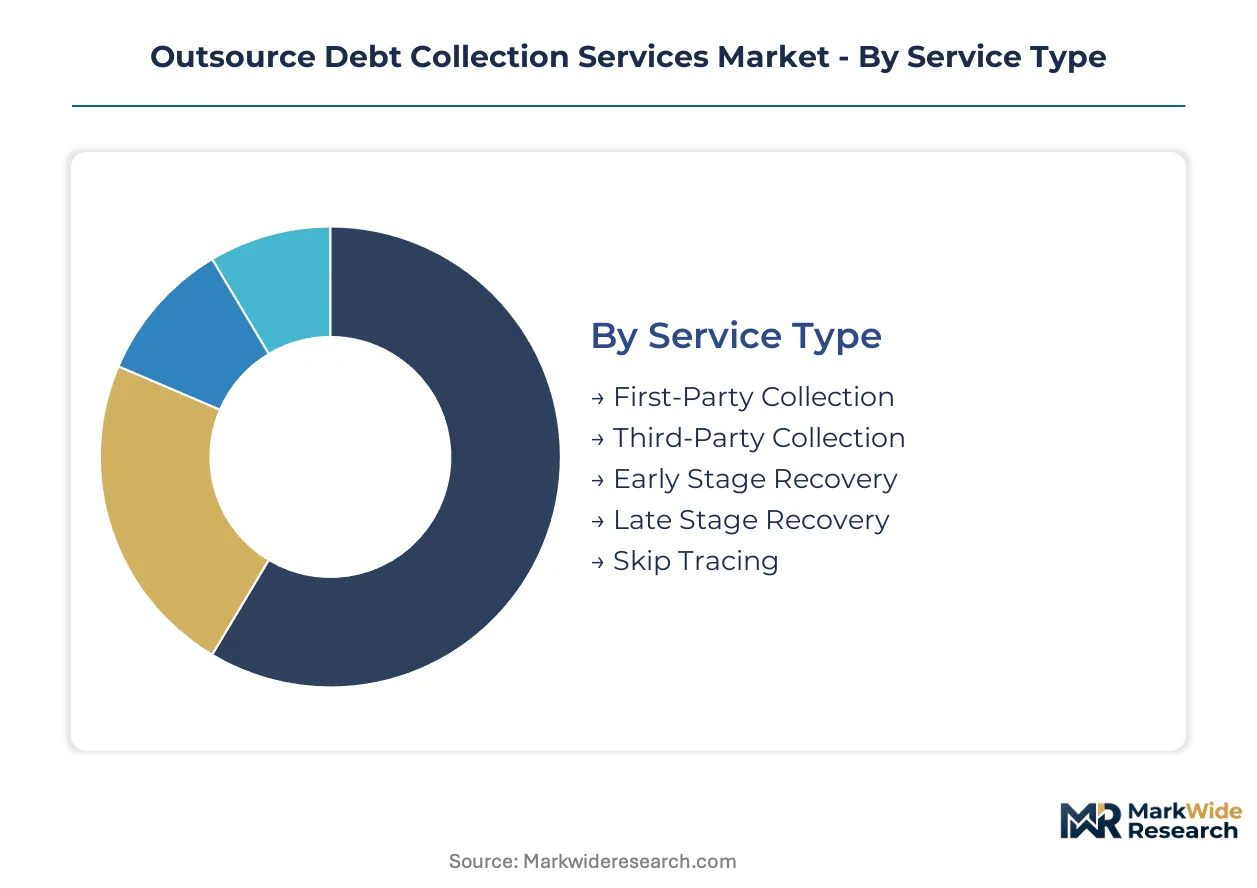
Debt collection outsourcing fragments across service intensity, client scale, and contact methodology. Each dimension shapes vendor capability requirements and contract economics differently.
Service Type:
Service intensity separates buyers by how early they intervene and how aggressively they pursue recovery.
- Third-Party Collection:External agencies assume full recovery responsibility after charge-off, deploying licensed collectors and legal escalation pathways. Financial institutions in the United States assign these portfolios under contingency arrangements, with TCPA compliance constraints limiting autodialer deployment.
- Early Stage Recovery:Pre-charge-off intervention uses systematic contact protocols to cure delinquencies before severe credit damage. Credit card issuers concentrate demand here, driven by regulatory pressure to demonstrate borrower assistance efforts before default.
- First-Party Collection:Outsourced agents operate under the lender's brand identity, preserving customer relationships while externalizing labor costs.
- Late Stage Recovery:Post-litigation or aged-debt pursuit requires specialized legal networks and asset location capabilities.
- Skip Tracing:Locating debtors who have changed residence or employment uses proprietary data aggregators and credit bureau interfaces.
Volume sits with Third-Party Collection; growth tilts toward Early Stage Recovery.
Customer Type:
Contract scale and sophistication requirements diverge sharply across buyer categories.
- Financial Institutions:Banks and non-bank lenders generate the largest contract values through multi-year outsourcing agreements spanning credit card, auto loan, and mortgage portfolios. India's RBI fair practices code shapes vendor qualification standards for international assignments.
- Large Enterprises:Mid-market B2B receivables operations create conversion opportunities as fragmented in-house teams face wage inflation in Pune and Manila talent markets.
- Small Businesses:Lower invoice volumes and limited negotiation leverage produce spot-contract relationships rather than strategic partnerships.
- Telecommunication Providers:High-volume, low-balance consumer arrears require automated workflow integration with billing systems.
- Utilities:Regulated service obligations limit collection aggressiveness, favoring early-stage cure programs over litigation.
Revenue concentrates with Financial Institutions; expansion is steepest among Large Enterprises.
Engagement Model:
Payment structure determines risk allocation between client and vendor.
- Contingency Based:Agencies earn percentage of gross collections, aligning incentives with recovery outcomes. United Kingdom tier-one banks are piloting hybrid structures adding fixed retainers for cost predictability.
- Flat Fee:Predictable costs appeal to utilities and telecommunication providers with standardized portfolio characteristics.
- Retainer Based:Monthly fees with performance bonuses suit early-stage recovery where cure rates are harder to attribute.
- Hourly Billing:Legal-intensive late-stage recovery and skip tracing use time-based arrangements for complex case work.
Contingency Based commands transaction volume; Retainer Based is gaining share fastest.
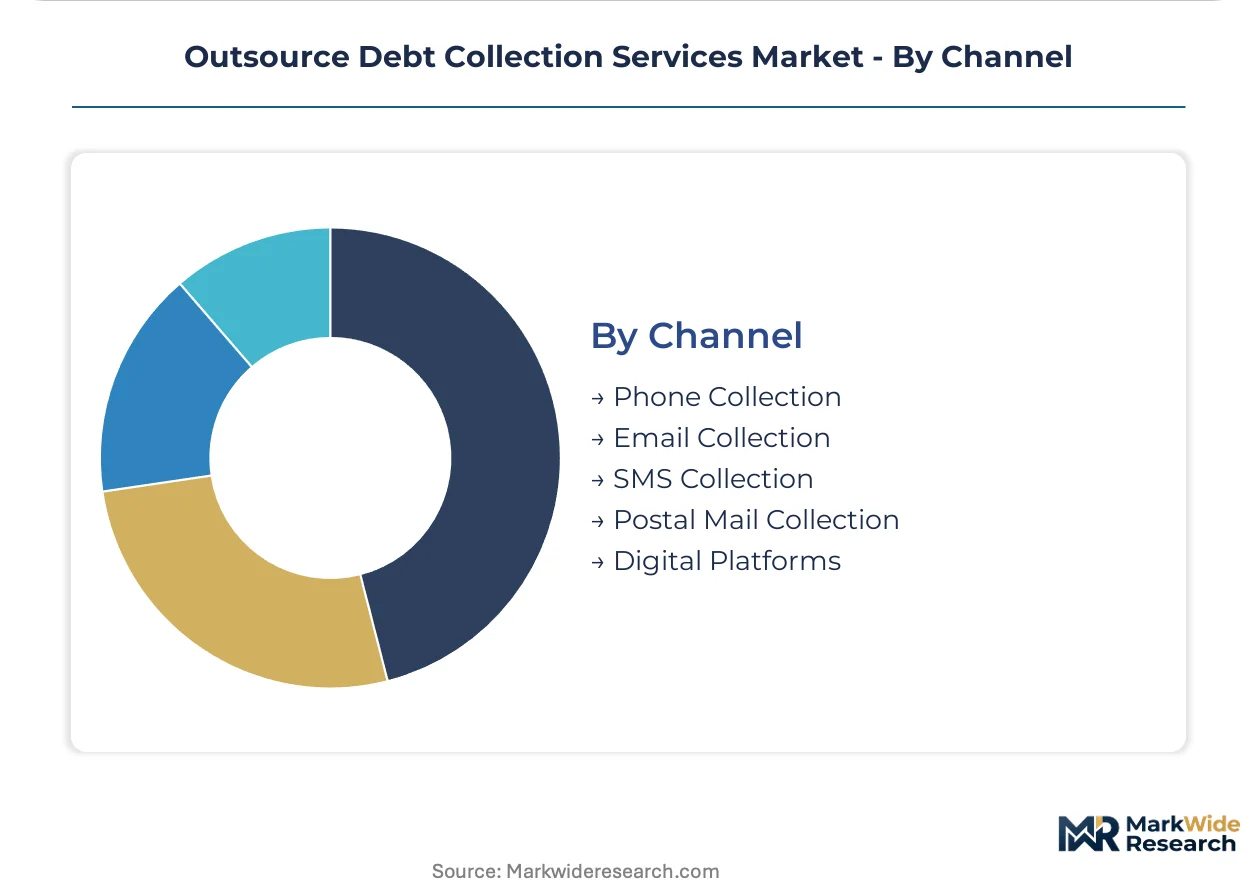
Channel:
Contact modality selection reflects compliance constraints and debtor demographic profiles.
- Digital Platforms:Self-service portals and conversational AI enable 24/7 payment arrangement without human agent involvement. Major United States credit card issuers deploy these tools to compress cost-per-contact metrics.
- SMS Collection:Text-based outreach expands compliant contact windows beyond TCPA-restricted calling hours, though consent documentation requirements are tightening.
- Phone Collection:Voice negotiation remains essential for complex hardship arrangements and high-balance commercial recoveries.
- Email Collection:GDPR-driven infrastructure investment in Europe has modernized data governance for electronic contact.
- Postal Mail Collection:Physical notice requirements persist for certain legal milestones and demographic segments with limited digital access.
Phone Collection retains the largest assignment volume; Digital Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unsecured lending origination in the United States, the United Kingdom, and India generates the primary feedstock for outsourced recovery operations, while compliance infrastructure investments concentrate in financial centers with stringent consumer protection mandates.
United States
Credit card charge-off volumes and buy-now-pay-later receivables sustain demand for third-party collection services. The Consumer Financial Protection Bureau enforces conduct standards under the Fair Debt Collection Practices Act, while the Telephone Consumer Protection Act restricts autodialer deployment. Dallas and San Antonio host major agency operations serving national financial institutions.
United Kingdom
Tier-one banks pilot hybrid retainer-based contracts for cost predictability in credit card and personal loan recovery. The Financial Conduct Authority regulates collection practices alongside GDPR data governance requirements. London-based operations coordinate European collections while Manchester and Glasgow centers handle high-volume consumer outreach.
India
The Reserve Bank of India's fair practices code shapes vendor qualification standards for international assignments. Business process outsourcing clusters in Pune and Hyderabad build dedicated agent pools with financial services domain expertise. Mumbai anchors compliance infrastructure for cross-border data handling.
Germany
GDPR enforcement and the Digital Services Act tighten algorithmic transparency requirements for automated scoring models. The Federal Financial Supervisory Authority oversees credit management practices. Frankfurt and Munich host integrated credit management operations spanning prevention through recovery stages.
Spain
Consumer finance subsidiaries segregate EU data processing within regional cloud infrastructure to satisfy cross-border transfer restrictions. The Spanish Data Protection Agency examines collection agency scoring logic. Barcelona and Madrid centers specialize in late-stage recovery with legal escalation networks.
Outsource Debt Collection Services Market Competitive Landscape
Global majors compete with regional champions across geographic diversification and compliance infrastructure depth. The market structures around scale-driven recovery platforms, integrated credit management providers, and specialized early-stage cure specialists. Tier-one players pursue M&A to build legal network density, while mid-tier agencies invest in conversational AI to compress cost-per-contact metrics.
Within the predictive analytics tier, Encore Capital Group exemplifies machine-learning scoring deployment across consumer loan portfolios. PRA Group occupies a position emphasizing geographic diversification across the Americas and Europe. Intrum AB anchors the integrated services archetype spanning prevention through recovery stages.
| Leading Market Players |
|---|
| Encore Capital Group |
| PRA Group |
| IC System |
| Atradius Collections |
| Fair Capital |
| Summit A/R |
| Intrum AB |
| EOS Group |
| Alorica Inc. |
| Others |
Pricing and Supply Chain Analysis
Horizontal consolidation among collection agencies in the United States, United Kingdom, and India anchors both supply positioning and pricing power. Tier-one vendors leverage scale economies across multi-jurisdiction operations to command premium contingency rates, while mid-tier competitors absorb margin compression through automation investment.
Pricing Analysis
Service bundling separates compliance infrastructure inclusion from unbundled legal escalation pricing. Three-tier pricing structure across premium, standard, and economy levels aligns with recovery stage complexity and agent expertise tiers. Price differentiation rests on GDPR-compliant data governance certification and machine-learning scoring capability. Cost compression in the standard tier is intensifying because self-service digital portals displace voice-based outreach. Small businesses exhibit highest price sensitivity; tier-one banks demonstrate lowest.
Supply Chain Analysis
Regional distribution of agent talent follows hub-and-spoke patterns centered on Manila, Pune, and Mexico City. Geographic supply concentrates in India, the Philippines, and Mexico. Raw material inputs draw from licensed collector training pipelines, conversational AI software licenses, and credit bureau data feeds. Single-source vulnerability concentrates in fluent bilingual agent pools with financial services domain expertise. Distribution runs through direct outsourcing contracts with financial institutions and enterprise B2B receivables managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase where conversational AI displaces scripted interactive voice response systems. Legacy phone-centric recovery models face structural displacement from digital-first contact protocols.
For Market Incumbents: Hedge against substitute channel displacement by deepening proprietary machine-learning scoring capabilities and securing exclusive legal network density in high-recovery jurisdictions. TCPA compliance automation represents a critical defensive investment as regulatory exposure escalates. Vertical integration into cloud-based compliance infrastructure protects margin position against pure-play digital challengers.
For New Entrants and Emerging Players: AI-enabled voice analytics offers the most penetrable entry vector for mid-tier agencies seeking differentiation from established scale players. Target B2B receivables for mid-market enterprises where fragmented in-house operations create outsourcing conversion potential. A direct-to-financial-institution SaaS pricing model bypasses contingency-based competitive intensity.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated credit management platforms seeking geographic expansion. Long-term viability favors vendors with demonstrated GDPR and TCPA compliance infrastructure across multiple jurisdictions. The signal to watch is tier-one bank adoption of hybrid retainer-based contracts displacing pure contingency structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Platform Deployment | Encore Capital Group compresses cost-per-contact metrics while expanding compliant contact windows beyond TCPA restrictions. |
| GDPR Infrastructure Investment | Intrum AB segregates EU data processing within regional cloud infrastructure to satisfy cross-border transfer restrictions. |
| Legal Network Density Expansion | PRA Group builds recovery capability across the Americas and Europe through geographic diversification. |
| Hybrid Pricing Model Pilot | United Kingdom tier-one banks test monthly retainer arrangements with performance bonuses tied to net recovery rates. |
| B2B Receivables Market Entry | Mid-market enterprise outsourcing conversion potential exceeds consumer debt penetration rates across Pune and Manila talent markets. |
Research Methodology
Trade association filings, regulatory enforcement databases, and financial institution procurement records formed the secondary backbone of this study. Primary interviews with collection agency operations directors, compliance officers at financial institutions, BPO vendor qualification leads, and credit bureau data product managers combined with secondary validation. Bottom-up triangulation across service type, customer segment, and engagement model dimensions anchored volume estimates; top-down cross-checks against unsecured lending origination data ensured consistency.
Historical trendline analysis of charge-off volumes and outsourcing penetration rates established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation across service intensity tiers, client scale categories, and contact methodology channels, with recovery rate differentials by delinquency stage as an industry-specific dimension. CAGRs derived from regression analysis of origination volume growth, regulatory constraint intensity, and automation adoption curves.
The model holds under stable unsecured lending origination and regulatory enforcement intensity; deviation in TCPA litigation volume or GDPR penalty escalation would shift trajectory. Forecasts reflect documented assumptions about technology adoption rates and labor cost inflation in offshore talent markets. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
India Security Brokerage Market
Financial Services
Online Investment Platform Market
Financial Services
Currency Management Market
Financial Services
Mobile Notary Public Market
Financial Services
Reconciliation Software Market
Financial Services
North America Management Consulting Services Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Reverse Factoring Market
Financial Services
Cash Flow Market
Financial Services
Europe Factoring Services Market
Financial Services
E-Brokerage Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
South Korea Financial Services Software Market
Financial Services
ATM Management Service Market