
 Injection Blow Molding Machine Market | 2026-2036
Injection Blow Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Blow Molding Machine Market Foresight
The divergence between premium pharmaceutical-grade systems and commodity packaging equipment is hardening around validation protocols, cleanroom compatibility, and cycle-time precision. Bekum sustains its position through deep specialization in multi-layer barrier containers for sensitive drug formulations. Jomar Corporation anchors North American supply with vertically integrated machine and mold production for narrow-neck pharmaceutical bottles. Wilmington Machinery differentiates via all-electric platforms targeting medical OEMs requiring ISO 15378-compliant output.
An injection blow molding machine forms hollow plastic articles by injecting a preform around a core rod, then transferring this preform to a blow station where compressed air inflates it against a mold cavity, typically achieving wall thickness tolerances within 0.1 mm for pharmaceutical and cosmetic applications. Electric and hybrid technology segments are capturing margin pools as energy costs and cleanroom noise standards push converters away from conventional hydraulic architectures; meanwhile, two-stage systems dominate high-volume packaging while single-stage configurations retain preference for complex multi-material pharmaceutical designs where parison programming demands tight process integration.
FDA enforces container closure integrity and extractables-leachables testing under USP standards, compelling machine builders to validate material contact surfaces and purge-system efficacy. EMA's Annex 1 revision on sterile manufacturing elevates requirements for particulate control, directly shaping blow molding equipment specifications in European pharmaceutical supply chains. REACH restrictions on plasticizers and additives further constrain material selections for EU-bound medical packaging. Stakeholders must monitor how evolving pharmacopeial standards and carbon-border adjustments reshape capital equipment specifications and regional sourcing strategies.
Market Dynamics
Electric and hybrid architectures are displacing hydraulic systems as energy costs and cleanroom noise standards harden equipment specifications across pharmaceutical and cosmetic packaging lines.
Growth Catalysts
- EMA Annex 1 Revision:Sterile manufacturing mandates for particulate control are compelling European converters to upgrade blow molding equipment for container closure integrity compliance.
- Glass-to-plastic conversion:Pharmaceutical packagers are adopting blow molded containers for sterile liquid storage as barrier polymer technologies mature for sensitive drug formulations.
- All-electric platforms:Medical OEMs requiring ISO 15378-compliant output are specifying servo-driven machines that eliminate hydraulic oil contamination risks in cleanroom environments.
Market Restraints
- Specialized steel and servo motor costs:Precision components for pharmaceutical-grade systems face input price volatility from concentrated East Asian electronics supply chains.
- REACH plasticizer restrictions:EU additive constraints limit material selections for medical packaging bound for European markets, narrowing formulation flexibility.
- Validation timeline compression:FDA container closure integrity and extractables-leachables testing extends equipment qualification periods before revenue generation.
Strategic Opportunities
- Biologic drug packaging expansion:Single-use blow molded containers for cell and gene therapies represent underpenetrated demand within sterile liquid storage applications.
- India pharmaceutical manufacturing:CDSCO quality mandates and export-oriented production clusters create equipment upgrade cycles for domestic machine builders to capture.
- Carbon border adjustments:EU carbon pricing mechanisms on imported plastics incentivize regional machine sourcing and energy-efficient electric platform adoption.
Industry Challenges
- Multi-layer parison programming expertise:Complex barrier container production requires scarce process engineers capable of integrating injection and blow stage parameters.
- Legacy hydraulic fleet retrofit costs:Converters face capital intensity decisions between upgrading existing machines versus greenfield electric platform investments.
- ISO 15378 certification timelines:Medical packaging equipment validation creates extended sales-to-commissioning cycles that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Blow Molding Machine Market |
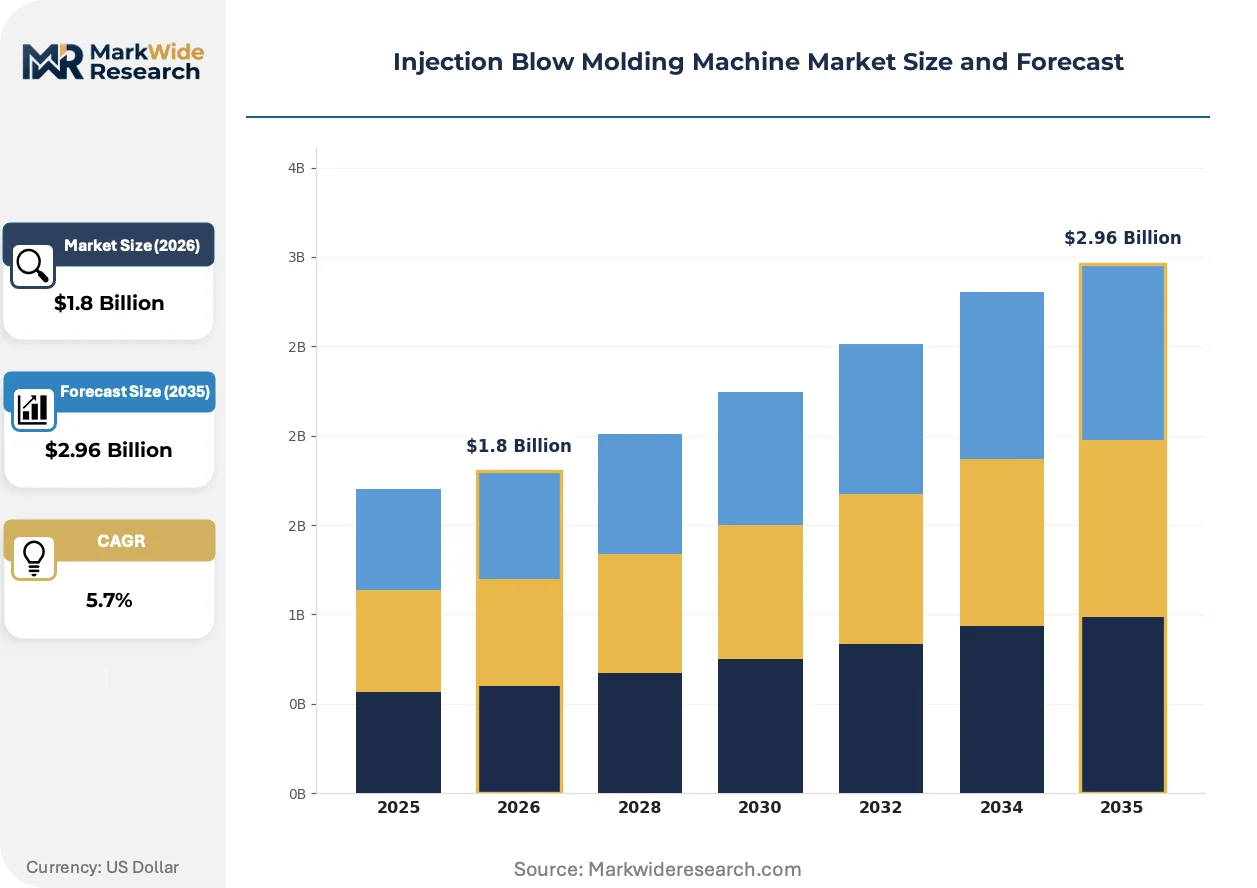
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Two-Stage, Automatic, Semi-Automatic End User: Consumer Goods, Pharmaceuticals, Automotive, Packaging Material: Polyethylene, Polypropylene, Polyethylene Terephthalate, PVC Technology: Conventional, Electric, Hybrid, Others |
| Companies Covered | Wilmington Machinery, Bekum, Jomar Corporation, Ningbo Vaino Machine Equipment, Bestar Blow Molding Machinery, Pet All Manufacturing, Kautex, Tango Machinery, Meccanoplastica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Blow Molding Machine Market Shifts & Advancements
Process integration between injection and blow stages is tightening as pharmaceutical tolerances compress below 0.1 mm wall thickness variance, while regulatory validation protocols reshape equipment specification workflows.
All-electric servo architectures are rewriting power transmission economics in cleanroom environments. Medical device OEMs in Germany and Switzerland are specifying these platforms to eliminate hydraulic oil vapor risks while achieving sub-5-second cycle times. The technology is compressing energy consumption differentials between premium pharmaceutical systems and commodity packaging equipment.
REACH restrictions on plasticizers and additives are constraining material selections for EU-bound medical packaging. EMA's Annex 1 sterile manufacturing revision elevates particulate control requirements that directly shape blow molding equipment specifications. European pharmaceutical supply chains are responding by mandating purge-system efficacy documentation and material contact surface validation from machine builders.
Equipment specification decisions increasingly centralize with pharmaceutical quality assurance departments rather than procurement functions. Medical packaging converters in the United States are unbundling after-sales service contracts from capital purchases to align validation support with FDA inspection cycles. This behavioral shift is most visible among sterile liquid drug manufacturers facing intensified USP container closure integrity enforcement.
Injection Blow Molding Machine Market Segmentation
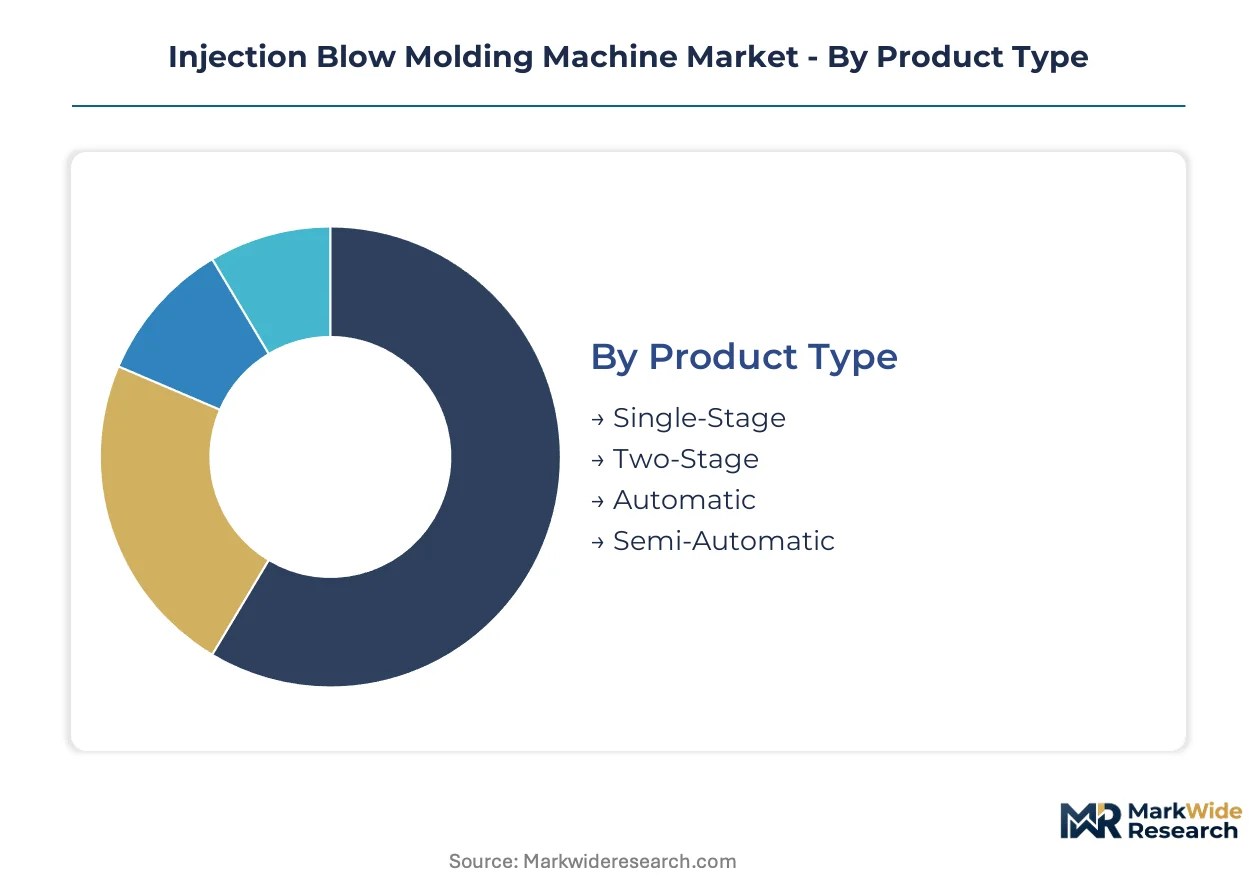
Segmentation in injection blow molding equipment reflects divergent capital intensity and validation requirements across pharmaceutical, automotive, and packaging converters. Equipment specification workflows increasingly centralize with quality assurance departments rather than procurement functions as FDA and EMA regulations harden.
Product Type:
Volume production favors two-stage configurations while premium pharmaceutical applications demand single-stage integration for parison precision control.
- Single-Stage:Injection and blow molding occur in one continuous process on a unified machine platform, enabling wall thickness control within 0.1 mm. Demand concentrates in German and Swiss pharmaceutical packaging clusters serving sterile liquid drug manufacturers under EMA Annex 1 particulate mandates.
- Two-Stage:Preform injection and blow molding operate as separate processes, allowing independent optimization of each stage. High-volume packaging converters in China deploy these systems for commodity bottle production where cycle time economics outweigh precision requirements.
- Automatic:Fully automated material handling and process control reduce labor exposure in cleanroom environments.
- Semi-Automatic:Operator intervention remains required for preform transfer and quality inspection, limiting deployment to lower-volume specialty applications.
Mature deployment sits with Two-Stage systems. Newer deployment is concentrated in Single-Stage configurations for barrier container production.
End User:
Application-driven specification splits between validated pharmaceutical systems and throughput-focused packaging equipment.
- Pharmaceuticals:Container closure integrity requirements under USP standards demand validated purge systems and material contact surface documentation. FDA extractables-leachables testing extends qualification timelines for sterile liquid storage applications.
- Packaging:Cosmetic and food container producers prioritize cycle time compression and energy efficiency over validation protocols. German converters serving premium cosmetic brands specify all-electric platforms for cleanroom noise compliance.
- Consumer Goods:Household product manufacturers favor hybrid architectures balancing capital cost against operational flexibility.
- Automotive:Fluid reservoir and ducting applications require specialized multi-layer barrier configurations for fuel system compatibility.
Pharmaceuticals command the steepest expansion trajectory as glass-to-plastic conversion accelerates for biologic drug storage.
Material:
Polymer selection constrains equipment specification through melt rheology and barrier property requirements.
- Polyethylene Terephthalate:Dominates pharmaceutical and beverage packaging with excellent clarity and barrier performance. REACH plasticizer restrictions in EU markets constrain additive flexibility for medical-grade PET formulations.
- Polypropylene:Chemical resistance and autoclave sterilization compatibility drive demand in pharmaceutical closures and diagnostic containers. US converters specify PP for single-use blow molded containers in cell therapy applications.
- Polyethylene:HDPE and LDPE variants serve commodity packaging where cost minimization dominates specification.
- PVC:Declining share in medical applications due to DEHP plasticizer concerns under EU REACH and US FDA guidance.
Polyethylene Terephthalate anchors established pharmaceutical packaging lines. Polypropylene is gaining share fastest in single-use biologic drug containers.
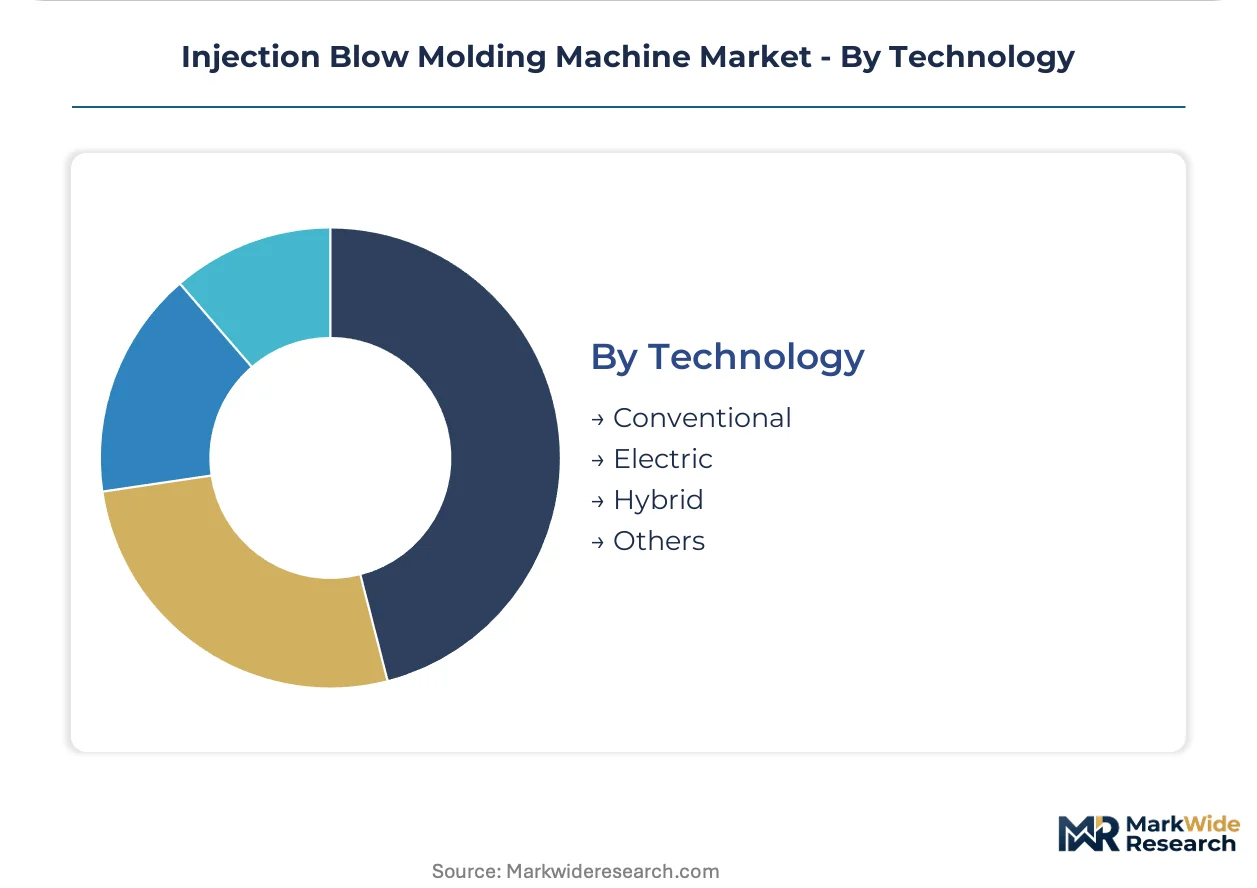
Technology:
Power transmission architecture determines cleanroom suitability and energy cost exposure.
- Electric:Servo-driven clamping and injection units eliminate hydraulic oil vapor risks while achieving sub-5-second cycle times. Swiss and German medical OEMs specify these platforms for ISO 15378-compliant output.
- Hybrid:Combines electric injection with hydraulic blow molding, offering intermediate capital cost and energy efficiency. Chinese packaging converters favor this architecture for mid-volume cosmetic bottle production.
- Conventional:Full hydraulic systems face displacement as energy costs and cleanroom noise standards harden equipment specifications.
- Others:Emerging servo-pneumatic and all-electric blow station configurations target niche medical applications.
Conventional hydraulic technology retains installed base dominance. Electric platforms represent the fastest-climbing segment as carbon border adjustments incentivize energy-efficient equipment sourcing in Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's precision molding corridor anchors Asia-Pacific pharmaceutical packaging equipment demand, with the Yangtze River Delta serving as the primary nexus for sterile liquid container production and cleanroom-compliant machine deployment.
United States
New Jersey and North Carolina pharmaceutical clusters drive demand for ISO 15378-validated systems as sterile drug manufacturers convert from glass to barrier polymer containers. FDA container closure integrity enforcement under USP standards compels equipment upgrades across contract packaging organizations. Wilmington Machinery anchors domestic supply from its North Carolina base, serving medical OEMs requiring all-electric platforms.
Germany
Baden-Württemberg's medical technology corridor concentrates demand for single-stage systems achieving sub-0.1 mm wall thickness precision. EMA Annex 1 revision on sterile manufacturing particulate control shapes equipment specifications for European pharmaceutical supply chains. Freiburg and Stuttgart house specialized converters serving Swiss and German biologic drug manufacturers.
China
Zhejiang and Jiangsu provinces dominate two-stage system deployment for high-volume cosmetic and beverage packaging. NMPA alignment with international pharmacopeial standards is tightening validation requirements for domestic pharmaceutical equipment. Ningbo Vaino Machine Equipment represents regional fabricators expanding from commodity packaging into medical-grade system development.
Switzerland
Basel's pharmaceutical headquarters economy generates concentrated demand for barrier container systems serving biologic drug storage. Swissmedic regulations on extractables-leachables testing extend equipment qualification timelines for sterile liquid applications. The Basel-Liestal corridor hosts precision molding specialists supplying Novartis and Roche packaging operations.
India
Maharashtra and Gujarat pharmaceutical manufacturing zones are upgrading equipment to meet CDSCO quality mandates for export-oriented production. The country's national pharmaceutical regulator is harmonizing standards with FDA and EMA requirements, compelling machine replacement cycles. Ahmedabad and Mumbai house domestic converters transitioning from manual to automated blow molding for sterile formulations.
Injection Blow Molding Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth, cleanroom compatibility, and cycle-time precision dimensions. The vendor base organizes into three tiers: pharmaceutical-grade specialists commanding extended sales cycles, mid-market hybrid providers serving cosmetic converters, and commodity fabricators competing on capital cost for beverage packaging. Strategic archetypes include vertically integrated machine-mold builders, electric platform specialists, and regional champions with localized service networks. Dominant competitive moves center on M&A for validation expertise acquisition and geographic expansion into pharmaceutical manufacturing clusters.
Among Germany-based precision specialists, Bekum occupies a position exemplifying multi-layer barrier container expertise for sensitive drug formulations. Wilmington Machinery anchors North American supply with its Delaware-registered operations representing all-electric platform development for medical OEM compliance requirements. Jomar Corporation exemplifies the vertically integrated archetype, with its New Jersey-based operations representing combined machine and mold production capabilities for narrow-neck pharmaceutical bottle applications.
| Leading Market Players |
|---|
| Wilmington Machinery |
| Bekum |
| Jomar Corporation |
| Ningbo Vaino Machine Equipment |
| Bestar Blow Molding Machinery |
| Pet All Manufacturing |
| Kautex |
| Tango Machinery |
| Meccanoplastica |
| Others |
Supply & Pricing Matrix
Specialized servo motor and precision steel component costs cascade from concentrated East Asian electronics supply chains through three distinct equipment pricing tiers, with pharmaceutical-grade systems commanding substantial premiums over commodity packaging machines due to validation depth and cleanroom compatibility requirements.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for premium pharmaceutical-grade systems, with pricing stratifying across ISO 15378-certified, CE-marked, and standard industrial tiers. Certification grade and after-sales service bundling drive price differentiation between tiers. Cost compression in standard industrial equipment intensifies as Chinese fabricators expand capacity. Commodity beverage packaging converters exhibit highest price sensitivity, while sterile drug manufacturers prioritize validation assurance over capital cost.
Supply Chain Analysis
ISO 15378 and FDA material contact surface qualifications gate supplier entry, elongating vendor onboarding timelines for pharmaceutical-grade component sourcing. Precision servo motors and specialized mold steels draw from Japan, Germany, and South Korea. Single-source vulnerability concentrates in high-torque servo drive assemblies. Distribution runs through regional machine builders with captive service networks for validation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with FDA container closure integrity and EMA Annex 1 particulate mandates erecting formidable barrier-to-entry moats that favor incumbents with validated quality systems and documented purge-system efficacy.
For Market Incumbents: Cement market position through backward integration into precision mold manufacturing and captive validation consulting services. Threat from emerging Chinese fabricators with NMPA-aligned quality systems demands preemptive capacity expansion in India and Southeast Asia. Certification investment in dual FDA-EMA compliance capabilities represents the critical defensive lever.
For New Entrants and Emerging Players: Launch via equipment-as-a-service models targeting mid-volume cosmetic converters in Eastern Europe and Latin America. Single-use biologic drug packaging applications present the most penetrable white space. Go-to-market angle should emphasize rapid ISO 15378 certification support bundled with capital-light leasing structures.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated machine-mold builders with established pharmaceutical customer relationships in Germany and Switzerland. Long-term viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. Watch for CDSCO enforcement harmonization with FDA standards as the inflection signal for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Validation Expertise Acquisition | Absorbing specialized consulting firms accelerates FDA container closure integrity compliance timelines. |
| All-Electric Platform Development | Servo-driven architectures eliminate hydraulic contamination risks for ISO 15378 cleanroom requirements. |
| Regional Service Network Expansion | Localized validation support aligns equipment commissioning with EMA Annex 1 inspection cycles. |
| Multi-Layer Barrier Technology Licensing | Patented parison programming capabilities differentiate offerings for sensitive biologic drug formulations. |
| Pharmaceutical Cluster Geographic Expansion | Proximity to Basel and New Jersey packaging corridors reduces sales-to-commissioning cycles. |
Research Methodology
Multi-period observation of equipment shipment volumes, validation timeline durations, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with blow molding plant engineers, pharmaceutical packaging procurement leads, FDA regulatory consultants, and aftermarket service heads. Secondary validation drew from FDA warning letter databases, EMA inspection deficiency reports, customs machinery trade records, and SEC filings of disclosed pharmaceutical packaging capital expenditures. Bottom-up equipment unit economics triangulated against top-down pharmaceutical packaging demand projections.
Segment-weighting across technology architecture, end-use application, and regional regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions included machine configuration, cleanroom compatibility tier, material handling automation level, and geographic manufacturing cluster. CAGRs were derived from regression analysis of historical capital expenditure patterns against pharmaceutical production capacity expansion. Industry-specific forecast inputs encompassed glass-to-plastic conversion rates for sterile liquid storage and REACH plasticizer restriction implementation timelines.
Regulatory enforcement intensity shifts, raw material cost volatility in precision electronics, and carbon border adjustment implementation pace are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA container closure integrity inspection frequency or EMA Annex 1 particulate mandate enforcement scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Flow Pack Machine Market