
 Global Blow Fill Seal Equipment Market | 2026-2036
Global Blow Fill Seal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blow Fill Seal Equipment Market Analysis
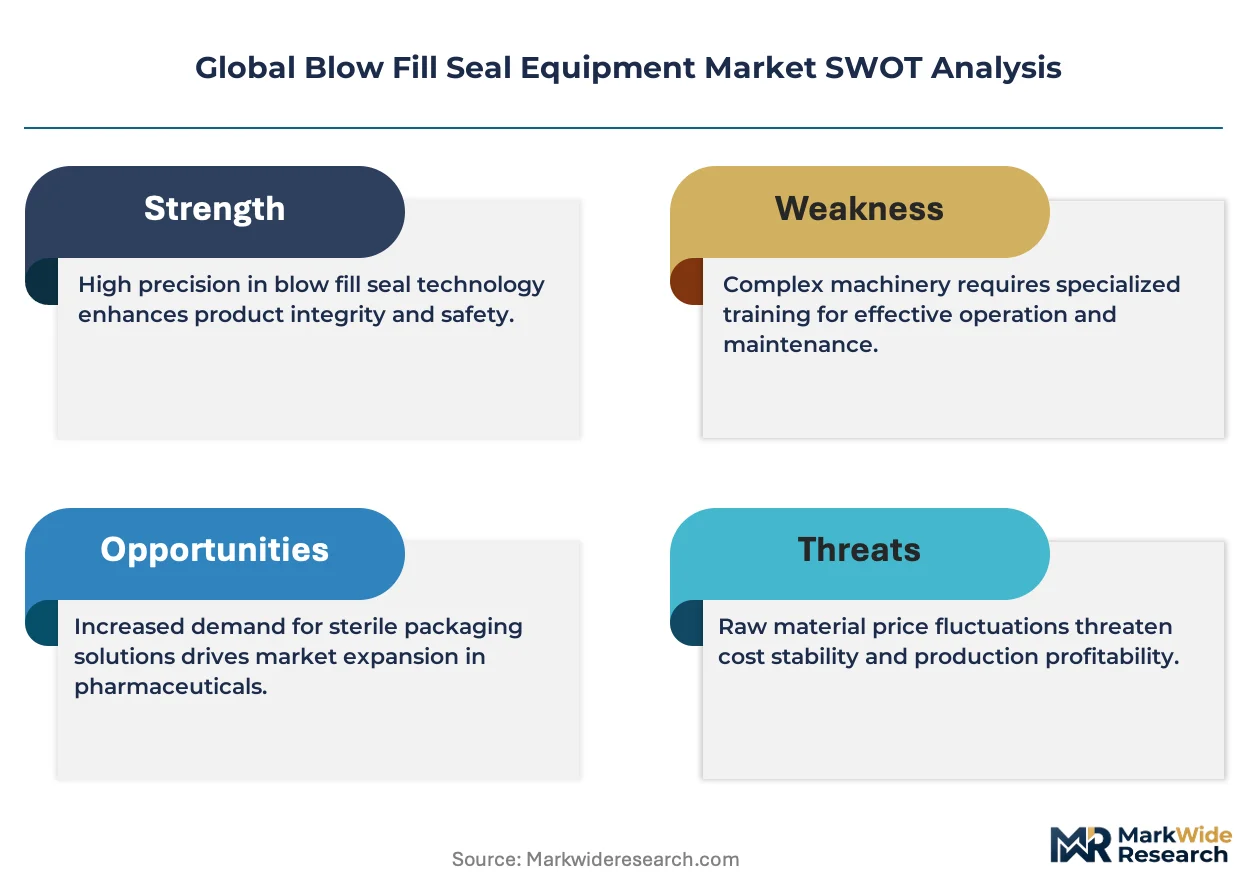
ISO 15378 certification for primary packaging materials is unwinding the competitive landscape, forcing equipment builders to validate every heat-seal parameter and polymer grade. Rommelag leverages its decades of blow fill seal process knowledge to dominate high-throughput pharmaceutical vial systems. Catalent, Inc. sustains global contract manufacturing demand by operating BFS lines across multiple FDA-inspected facilities. Weiler Engineering anchors North American supply with specialized equipment for ophthalmic and respiratory drug packaging.
Blow fill seal equipment forms, fills, and seals plastic containers in a single continuous operation within a classified cleanroom environment, typically processing polyethylene or polypropylene resins at temperatures between 160°C and 180°C to create sterile primary packaging for liquid pharmaceuticals. The technology eliminates human intervention during aseptic processing, reducing contamination risk compared to conventional filling lines. Pharmaceutical application demand leads the market as parenteral and ophthalmic drug makers replace glass with polymer containers for breakage resistance and design flexibility. Automated systems represent the fastest-growing technology segment as manufacturers replace manual and hybrid lines to meet EU GMP Annex 1 revisions on contamination control strategy.
FDA enforcement of sterile drug manufacturing guidelines and the EU's MDR requirements for packaging traceability shape equipment specifications and validation protocols on both sides of the Atlantic. EMA's updated GMP Annex 1 mandates continuous viable and non-viable particle monitoring, pushing buyers toward advanced robotics with integrated environmental sensing. China's NMPA alignment with PIC/S standards accelerates domestic pharmaceutical producers toward international-grade BFS installations. Stakeholders must monitor regulatory convergence between FDA, EMA, and NMPA on polymer extractables testing, as harmonized standards will determine which equipment platforms achieve multi-territory qualification without costly retrofit.
Market Dynamics
EU GMP Annex 1 revisions on contamination control strategy are compressing buyer timelines and forcing pharmaceutical manufacturers toward fully automated blow fill seal lines with integrated environmental monitoring systems.
Growth Catalysts
- EMA GMP Annex 1 Mandate:European pharmaceutical manufacturers must demonstrate continuous viable and non-viable particle monitoring during aseptic processing, accelerating replacement of manual BFS lines with robotic systems.
- India PLI Scheme for Drug Production:Domestic contract manufacturers are expanding sterile filling capacity under production-linked incentives, creating equipment demand for high-throughput polyethylene vial systems.
- Polymer Extractables Testing Harmonization:Convergence between FDA, EMA, and NMPA standards on container closure integrity validation is enabling multi-territory qualification from single equipment platforms.
Market Restraints
- Specialized Polymer Supply Concentration:Medical-grade polyethylene and polypropylene resin production concentrates among a limited set of European and North American petrochemical suppliers, exposing equipment buyers to input cost volatility.
- ISO 15378 Certification Burden:Primary packaging material validation requirements force equipment builders to document every heat-seal parameter and polymer grade, extending commissioning timelines.
- Glass Vial Substitution Resistance:Parenteral drug makers with established glass filling infrastructure face high switching costs and regulatory re-qualification requirements when evaluating polymer alternatives.
Strategic Opportunities
- Brazil ANVISA Alignment:Latin America's largest pharmaceutical market is adopting PIC/S standards, opening demand for international-grade BFS installations previously limited to FDA-inspected facilities.
- Respiratory Drug Packaging Expansion:Nebulizer solution and inhalation product manufacturers are specifying blow fill seal technology for unit-dose polymer containers with precise dosing geometry.
- Continuous Manufacturing Convergence:Integration of BFS equipment with upstream bioprocessing and downstream packaging automation is creating demand for modular, skid-mounted production lines.
Industry Challenges
- Aseptic Processing Engineer Scarcity:Qualified personnel capable of validating blow fill seal heat-seal parameters and troubleshooting polymer flow dynamics remain concentrated among legacy equipment users.
- Legacy Line Integration Complexity:Pharmaceutical manufacturers with existing filling infrastructure face technical friction when retrofitting automated BFS systems into established cleanroom layouts and building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blow Fill Seal Equipment Market |
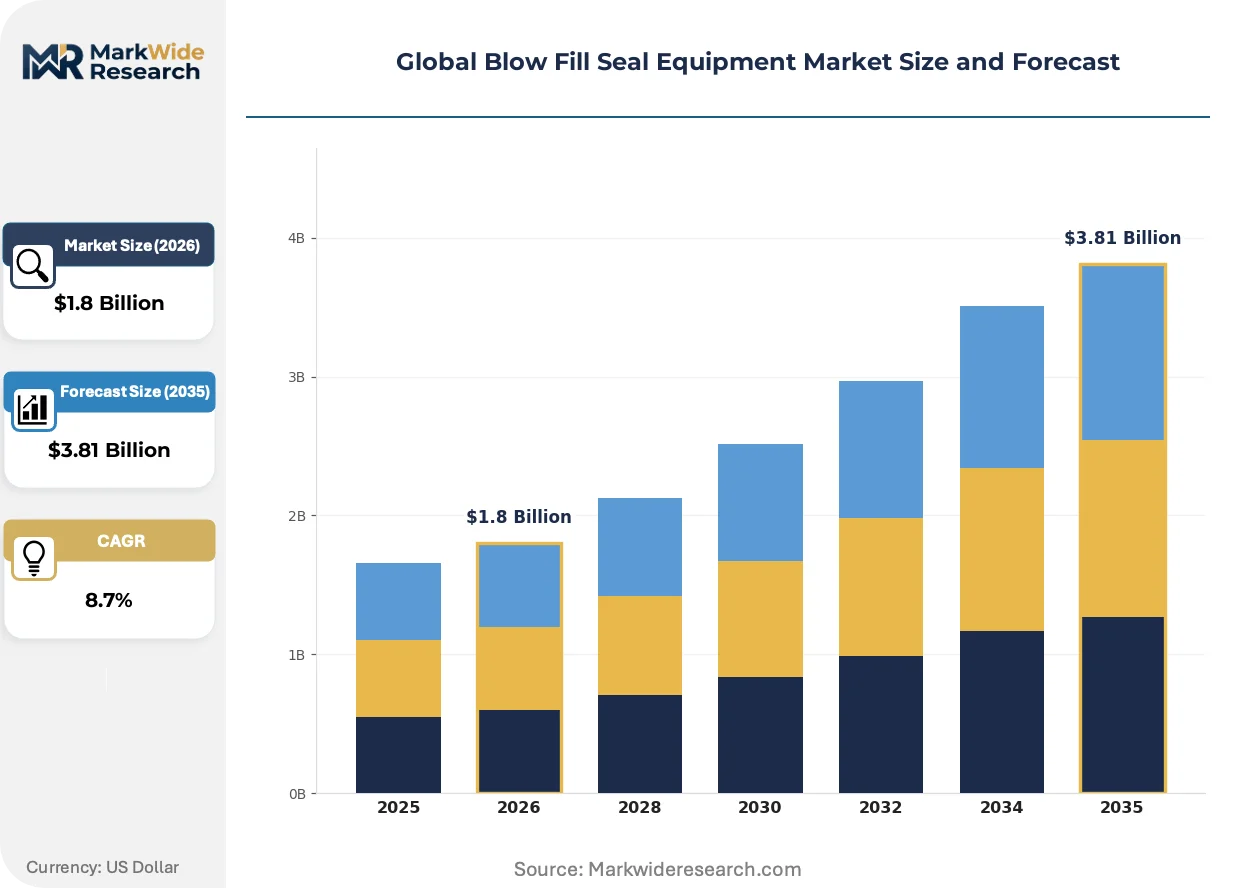
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Bottles, Ampoules Application: Pharmaceutical, Food & Beverage, Cosmetics, Nutraceutical End User: Pharmaceutical Companies, Contract Manufacturers, Research Labs, Biotech Firms Technology: Automated Systems, Hybrid Systems, Manual Systems, Advanced Robotics |
| Companies Covered | Rommelag, Catalent, Inc., Unither Pharmaceuticals, Weiler Engineering, Curida AS, Recipharm, Brevetti Angela, Unipharma LLC, Pharmapack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blow Fill Seal Equipment Market Emerging Trajectories
Regulatory pressure on contamination control is fragmenting equipment architectures and forcing convergence between blow fill seal automation and real-time environmental sensing technologies.
Multi-cavity mold technology is fragmenting the traditional throughput-versus-flexibility tradeoff in pharmaceutical packaging equipment. High-volume parenteral drug manufacturers in Germany and Switzerland are adopting 12-cavity and 16-cavity rotary systems that maintain rapid changeover capability for different vial geometries. This capability compression is eroding the historical segmentation between dedicated high-speed lines and flexible mid-volume platforms.
REACH regulation amendments on polymer additive disclosure are forcing equipment builders to validate processing windows for additive-free medical-grade resins. European pharmaceutical manufacturers must now document extractables profiles for every heat history experienced during container formation. Blow fill seal systems with precision temperature control across extrusion, molding, and sealing stations are capturing preference in EMA-regulated facilities.
Buyer consolidation among contract development and manufacturing organizations is compressing equipment procurement cycles and shifting negotiation leverage toward multi-site fleet standardization. Large CDMOs with facilities across India, Ireland, and Singapore are specifying identical BFS platforms to simplify validation transfer and spare parts inventory. This concentration dynamic favors equipment builders with global service networks and standardized control architectures.
Global Blow Fill Seal Equipment Market Segmentation
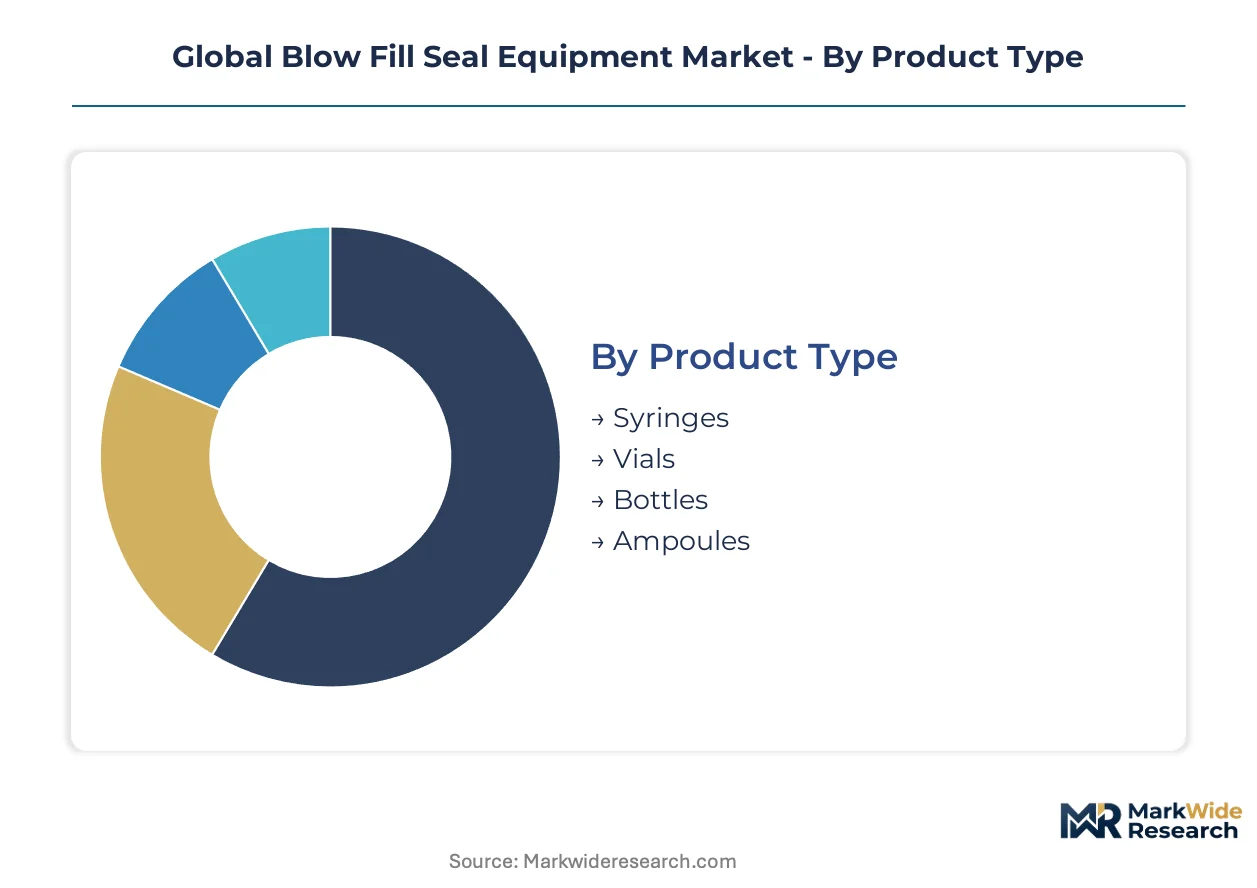
Blow fill seal equipment purchasing decisions split across container geometry, regulatory compliance burden, and automation intensity. Equipment specifications diverge sharply between sterile pharmaceutical applications and less demanding food or cosmetic packaging.
Product Type:
Syringes and vials flow through pharmaceutical contract manufacturing channels, while bottles and ampoules serve broader institutional and retail distribution.
- Syringes:Single-use polymer syringes require precision dosing geometry and integrated needle-shield compatibility. Demand concentrates among German and Swiss parenteral drug manufacturers seeking glass-alternative delivery systems for biologics.
- Vials:Small-volume polyethylene containers dominate ophthalmic and respiratory drug packaging with breakage resistance superior to glass. Indian contract manufacturers under CDSCO oversight are expanding vial-format capacity for export markets.
- Bottles:Larger-format containers serve oral liquid pharmaceuticals and nutritional supplements with simpler sterility requirements.
- Ampoules:Unit-dose polymer ampoules seal with tear-off tips for emergency and field-use medications.
Vials dominate installed base. Syringes are where expansion concentrates.
Application:
Cost tiers separate validated pharmaceutical systems from standard equipment serving less regulated industries.
- Pharmaceutical:Aseptic processing for parenteral, ophthalmic, and inhalation products demands ISO 15378-compliant equipment with full extractables documentation. EMA GMP Annex 1 revisions are compressing timelines for automated line upgrades across European facilities.
- Food & Beverage:Extended-shelf-life dairy and juice packaging employs simplified BFS configurations without pharmaceutical-grade environmental monitoring.
- Cosmetics:Single-use serum and essence ampoules drive demand for compact, flexible systems with rapid mold changeover.
- Nutraceutical:Probiotic and liquid supplement packaging bridges food and pharmaceutical specifications with moderate validation requirements.
Pharmaceutical applications command premium pricing. Cosmetics and nutraceuticals are climbing the fastest as brand owners adopt unit-dose formats.
End User:
Volume concentration varies by customer type, with contract manufacturers driving fleet standardization across multiple sites.
- Pharmaceutical Companies:In-house sterile filling operations at large drug makers specify customized, high-throughput lines integrated with upstream bioprocessing.
- Contract Manufacturers:CDMOs with FDA and EMA-inspected facilities are standardizing on identical BFS platforms across India, Ireland, and Singapore to simplify validation transfer.
- Research Labs:Clinical trial material production requires small-batch flexibility with rapid product changeover.
- Biotech Firms:Emerging biologics developers favor modular, skid-mounted systems for pipeline products with uncertain commercial scale.
Contract manufacturers dominate current order books. Biotech firms represent the steepest expansion trajectory as cell and gene therapy pipelines mature.
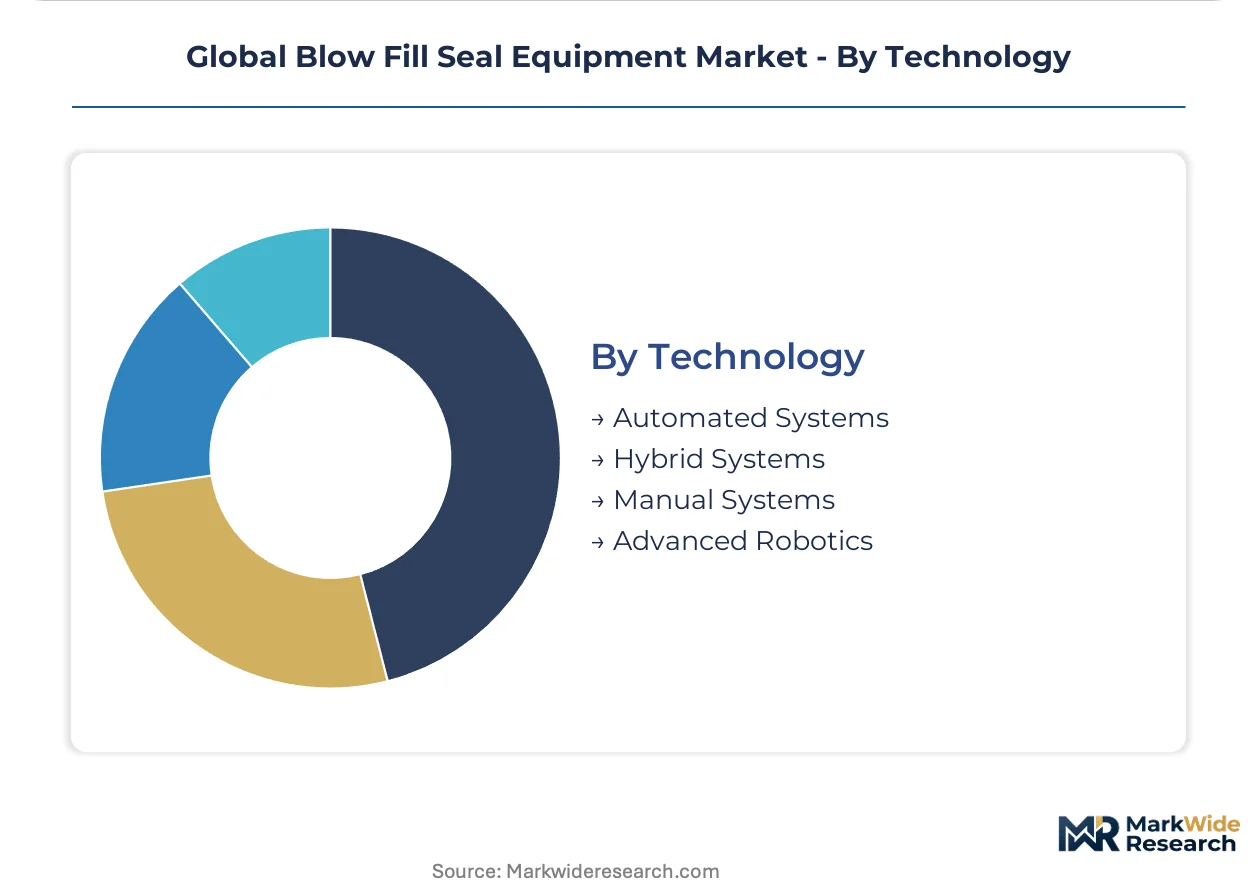
Technology:
Supply concentration among European and North American equipment builders shapes technology adoption patterns.
- Automated Systems:Continuous operation with robotic container handling and integrated environmental monitoring meets EU GMP Annex 1 contamination control mandates. German manufacturers anchor supply for high-throughput pharmaceutical installations.
- Advanced Robotics:Vision-guided systems with real-time particle sensing and adaptive process control capture preference in new EMA-regulated facilities.
- Hybrid Systems:Semi-automated configurations balance throughput and flexibility for mid-volume pharmaceutical and nutraceutical producers.
- Manual Systems:Operator-dependent lines persist in emerging markets with limited capital availability and less stringent regulatory oversight.
Automated systems dominate installed base. Advanced robotics is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for drug production is redirecting sterile filling investment toward contract manufacturing clusters, while EMA GMP Annex 1 revisions compress European upgrade timelines. Equipment procurement concentrates where regulatory stringency and pharmaceutical production scale intersect.
Germany
High-throughput parenteral drug manufacturers in Baden-Württemberg and Bavaria are replacing legacy glass filling lines with multi-cavity BFS systems. EMA GMP Annex 1 mandates on continuous particle monitoring are accelerating robotic line adoption. Stuttgart anchors European equipment supply with Rommelag and specialized automation engineering clusters.
United States
Ophthalmic and respiratory drug packagers are specifying BFS technology for unit-dose polymer containers with precise dosing geometry. FDA enforcement of sterile drug manufacturing guidelines shapes validation protocols for new installations. North Carolina and New Jersey pharmaceutical corridors concentrate contract manufacturing demand across multiple FDA-inspected CDMO facilities.
India
Domestic contract manufacturers under CDSCO oversight are expanding sterile filling capacity for export markets. The PLI scheme for drug production subsidizes high-throughput polyethylene vial system procurement. Gujarat and Maharashtra pharmaceutical clusters anchor equipment demand from emerging CDMOs seeking EMA and FDA qualification.
Switzerland
Biologics developers favor modular BFS configurations for pipeline products with uncertain commercial scale. Swissmedic alignment with PIC/S standards enables seamless multi-territory qualification. Basel and Zurich pharmaceutical corridors concentrate precision drug packaging engineering and polymer container innovation.
China
NMPA convergence with international standards is accelerating domestic pharmaceutical producers toward international-grade BFS installations. Yangtze River Delta manufacturers are retrofitting cleanroom infrastructure to accommodate automated aseptic processing lines. Shanghai and Suzhou clusters concentrate sterile drug production capacity expansion under upgraded regulatory oversight.
Global Blow Fill Seal Equipment Market Vendor Landscape
Player mix skews toward European precision engineering specialists with decades of process knowledge and North American application-focused fabricators. The competitive structure concentrates around three strategic archetypes: German-origin high-throughput system builders, US-based specialized equipment developers, and emerging Asian contract manufacturers integrating captive BFS capacity. Dominant competitive moves include multi-site fleet standardization by large CDMOs and precision temperature control technology licensing for EMA-regulated facilities.
Within the European specialist tier, Rommelag and Weiler Engineering occupy positions as archetype anchors for distinct application vectors. Rommelag exemplifies the high-throughput pharmaceutical vial system builder with deep process knowledge accumulated across decades of BFS equipment supply. Weiler Engineering represents the North American specialized fabricator focused on ophthalmic and respiratory drug packaging configurations. Catalent, Inc. sits within the contract manufacturing integrator archetype, sustaining equipment demand through multi-facility BFS line operations rather than equipment supply itself.
| Leading Market Players |
|---|
| Rommelag |
| Catalent, Inc. |
| Unither Pharmaceuticals |
| Weiler Engineering |
| Curida AS |
| Recipharm |
| Brevetti Angela |
| Unipharma LLC |
| Pharmapack |
| Others |
Supply Flow & Price Mechanics
ISO 15378 certification for primary packaging materials gates both supplier qualification and price stratification simultaneously, forcing equipment buyers to absorb validation documentation costs while vendors capture premiums for compliant platforms. Medical-grade resin specifications and heat-seal parameter traceability create tiered procurement economics where EMA-regulated facilities pay substantial markups over emerging-market installations.
Pricing Analysis
Cost-plus contracts with medical-grade polyethylene resin indexation dominate equipment procurement between German builders and pharmaceutical manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates fully automated Annex 1-compliant systems from hybrid configurations and manual lines. Pricing pressure stems from Indian contract manufacturers negotiating fleet-standardization discounts for multi-site CDMO rollouts. Emerging market buyers exhibit highest price sensitivity; Swiss and German biologics developers show lowest.
Supply Chain Analysis
Strategic stockpiling of medical-grade polypropylene resin characterizes European equipment builders hedging against petrochemical supply volatility, while Asian buyers favor just-in-time procurement with shorter inventory cycles. Raw material supply concentrates in Germany, Belgium, and the Netherlands among specialized polymer compounders. Component fabrication draws from Italian automation engineering clusters and Swiss precision temperature-control specialists. Single-source vulnerability runs through medical-grade resin additive suppliers. Distribution feeds from regional service hubs co-located with pharmaceutical manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA GMP Annex 1 revisions on contamination control strategy constitute a high-growth disruption, compressing replacement timelines for manual lines and expanding the addressable market for robotic BFS platforms by an order of magnitude across European pharmaceutical corridors.
For Market Incumbents: Compound process knowledge advantages by licensing precision temperature-control IP to EMA-regulated facilities while building captive service networks in Gujarat and Maharashtra pharmaceutical clusters. Defend against modular skid-mounted system entrants by embedding advanced robotics with real-time particle sensing as standard configurations rather than premium upgrades. For New Entrants and Emerging Players: Anchor in Brazil ANVISA alignment with PIC/S standards as the most penetrable regulatory opening, targeting Latin American contract manufacturers previously excluded from FDA-inspected supply chains. Pursue respiratory drug packaging applications for nebulizer solution unit-dose containers where dosing geometry specifications favor specialized engineering over incumbent scale advantages. For Investors and Strategic Acquirers: EU MDR requirements for packaging traceability reshape the acquisition landscape toward equipment builders with validated extractables documentation libraries and multi-territory qualification track records. Long-term viability favors precision engineering specialists with backward integration into polymer processing know-how. Watch NMPA-PIC/S convergence completion as the signal for Chinese domestic equipment replacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Fleet Standardization | CDMOs across India, Ireland, and Singapore specify identical BFS platforms to simplify validation transfer. |
| Precision Temperature Control Licensing | Equipment builders license validated processing windows for additive-free medical-grade resins to EMA-regulated facilities. |
| Modular Skid-Mounted System Development | Biotech firms favor flexible configurations for pipeline products with uncertain commercial scale requirements. |
| Continuous Manufacturing Integration | Upstream bioprocessing convergence creates demand for automated lines with downstream packaging automation. |
| Regional Service Network Expansion | German manufacturers establish captive service hubs in Gujarat and Maharashtra pharmaceutical clusters. |
Methodological Framework
Cross-validation between primary interviews with BFS equipment engineers and regulatory affairs specialists and secondary validation through FDA 483 observation databases, EMA GMP inspection records, and CDSCO manufacturing facility registrations anchors the qualitative findings. Plant managers at contract manufacturing organizations, procurement leads at pharmaceutical companies, aftermarket service heads at equipment builders, and polymer resin technical directors contributed field perspectives. Bottom-up installed base enumeration triangulates against top-down pharmaceutical production capacity assessments across the analysis window.
Sensitivity analysis around resin price volatility and regulatory enforcement intensity frames the quantitative outputs. Segmentation dimensions modeled include container geometry, automation intensity, application sterility tier, and regional regulatory cluster alignment. CAGRs derive from equipment replacement cycle compression under Annex 1 mandates and capacity expansion trajectories under India's PLI scheme. Forecast inputs incorporate polymer extractables testing harmonization progress and multi-cavity mold technology adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EMA enforcement intensity and resin supply stability; material deviation would warrant model refresh. Revision becomes warranted when NMPA-PIC/S convergence timelines or Brazil ANVISA implementation thresholds cross materiality boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Folding Gluing Machines Market