
 Recombinant Hormone Market | 2026-2036
Recombinant Hormone Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Hormone Market Analytics
Chinese biologics manufacturing capacity is hardening as domestic CDMOs expand microbial and mammalian expression platforms for hormone production. Novo Nordisk A/S anchors European supply through its integrated fermentation and purification infrastructure in Denmark. Eli Lilly and Company leverages decades of rDNA insulin expertise to sustain pricing power in diabetes segments. Merck competes through its biosimilar portfolio, extending reach into cost-sensitive hospital formularies.
Recombinant hormones are therapeutic proteins produced via recombinant DNA technology in engineered host cells, typically requiring post-translational glycosylation for biological activity and stability. These molecules replace or supplement endogenous hormone deficiencies across metabolic, reproductive, and hematological disorders. Insulin dominates product-type revenue due to massive diabetes prevalence, while growth hormone commands premium positioning in pediatric endocrinology despite smaller patient volumes. Fertility treatments represent the fastest-expanding application segment as delayed childbearing and reimbursed access protocols broaden. Subcutaneous delivery mode leads convenience-driven adoption, though intravenous routes persist for erythropoietin in dialysis settings.
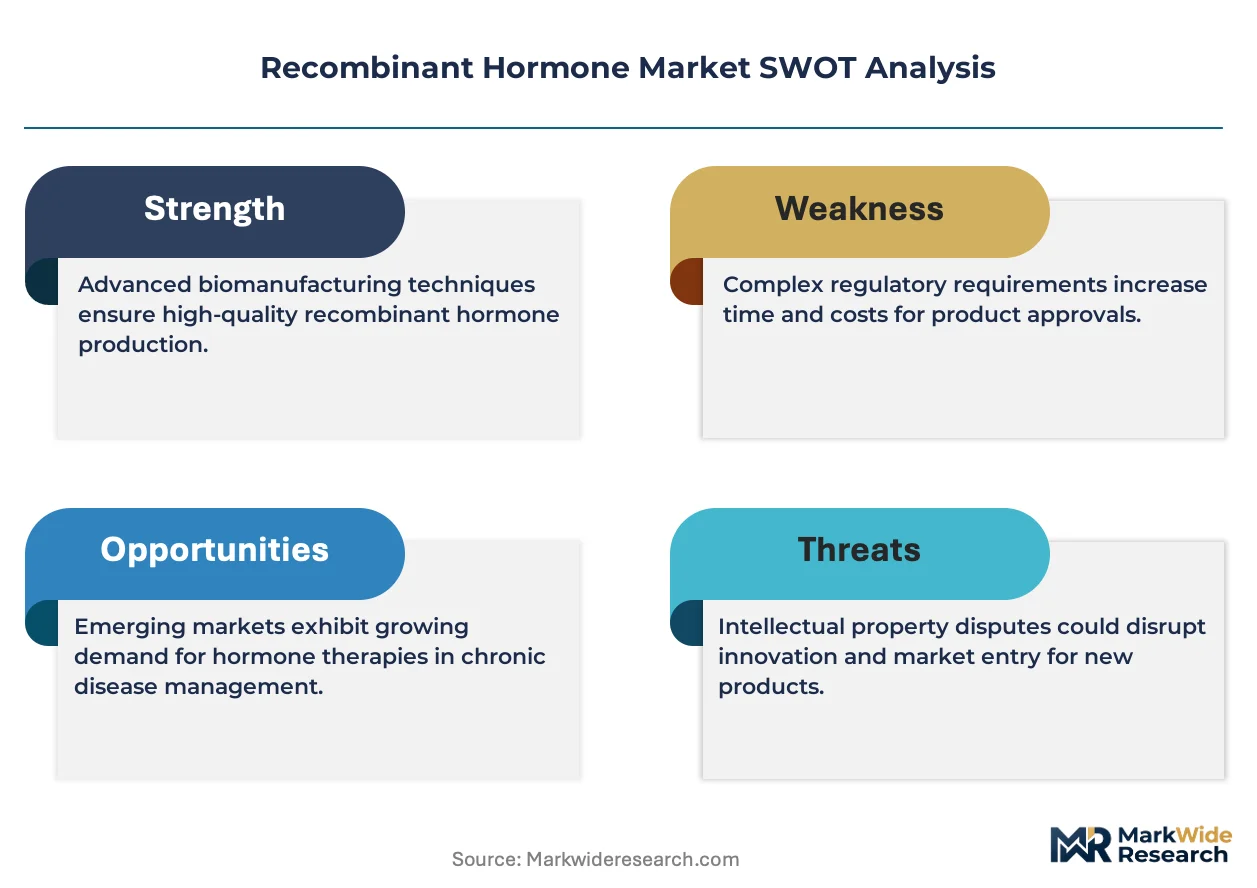
FDA biosimilar guidelines and EMA's scientific advice framework shape development timelines and interchangeability standards for recombinant hormone entrants. BIS certification requirements in India and China's NMPA biologics registration rules govern import substitution and local manufacturing scale-up. Stakeholders must monitor evolving pharmacovigilance obligations and real-world evidence mandates that determine post-market authorization durability.
Market Dynamics
FDA's biosimilar approval pathway under the Biologics Price Competition and Innovation Act is compressing exclusivity periods for originator molecules while accelerating competitive entry dynamics across therapeutic categories.
Growth Catalysts
- Assisted reproductive technology expansion:Fertility clinics in the United States and Western Europe are scaling hormone protocols for in-vitro fertilization cycles, broadening the addressable patient base for gonadotropin products.
- EMA's scientific advice framework:Early regulatory engagement is shortening development timelines for biosimilar hormone developers, reducing technical uncertainty and capital at risk.
- Microbial expression platform maturation:Chinese CDMOs are hardening manufacturing capacity for recombinant insulin and growth hormone, enabling cost-competitive supply for emerging markets.
Market Restraints
- Plasmid DNA supply concentration:Critical raw material production clusters in the United States and Germany, creating single-source vulnerability for fermentation-based hormone manufacturing.
- Cold chain infrastructure gaps:Temperature-controlled distribution networks remain underdeveloped across Sub-Saharan Africa and parts of Southeast Asia, limiting product stability reach.
- Interchangeability designation barriers:FDA's heightened pharmacovigilance requirements for automatic substitution are extending time-to-market for biosimilar entrants beyond initial approval.
Strategic Opportunities
- Pediatric endocrinology underpenetration:Growth hormone deficiency diagnosis rates in India and Brazil lag developed-market benchmarks by 60-70%, representing latent demand activation potential.
- Subcutaneous auto-injector convergence:Combination of recombinant hormone formulations with wearable delivery devices is opening adherence-monitoring revenue streams in diabetes and fertility segments.
- Japan's PMDA Sakigake designation:Expedited review pathway for innovative biologics is attracting first-in-class hormone developers seeking premium pricing and early reimbursement.
Industry Challenges
- Glycosylation engineering expertise scarcity:Post-translational modification optimization for hormone bioactivity requires specialized cell-line development talent concentrated at a handful of academic and industrial centers.
- Multi-product facility validation complexity:Switching between recombinant hormone campaigns demands extensive cleaning validation and regulatory filing updates, constraining operational flexibility.
- Reference product drift monitoring:Originators modify manufacturing processes over product lifecycles, complicating biosimilar analytical comparability exercises and forcing repeated bridging studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Hormone Market |
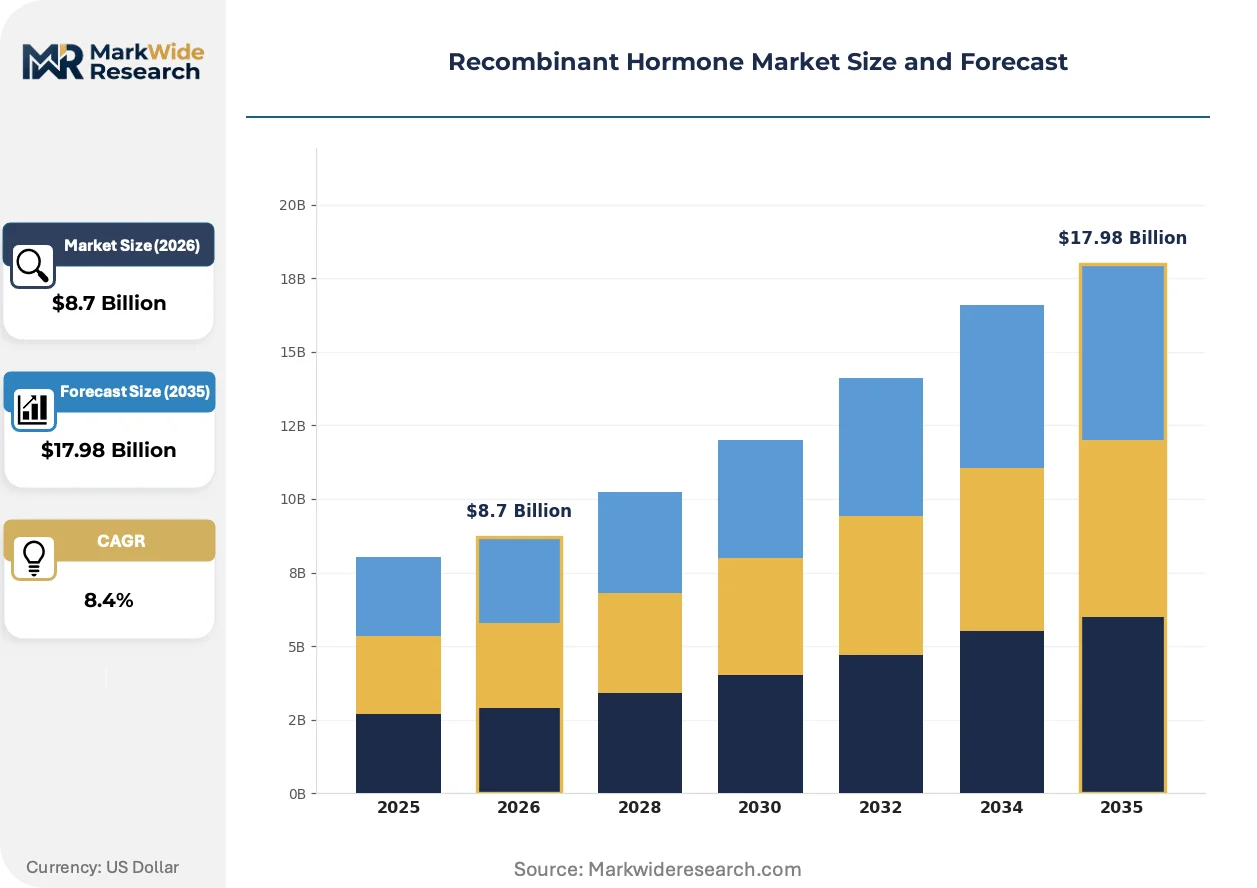
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Growth Hormone, Erythropoietin, Follicle Stimulating Hormone Application: Diabetes Management, Growth Disorders, Anemia Treatment, Fertility Treatments End User: Hospitals, Clinics, Homecare Settings, Pharmacies Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral |
| Companies Covered | Merck, Novo Nordisk A/S, Eli Lilly and Company, Ipsen Pharma, Novartis AG, Ferring Pharmaceuticals, Pfizer, Biocon, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Hormone Market Evolving Landscape
Continuous manufacturing modalities and single-use bioreactor systems are displacing traditional batch fermentation across hormone production facilities, compressing capital intensity and enabling rapid product changeovers.
Continuous bioprocessing technology is integrating perfusion-based cell culture with real-time quality monitoring to sustain high-density hormone expression over extended production runs. Specialty endocrinology practices and hospital systems in Germany and the United States are adopting these supply streams for insulin and growth hormone procurement. The shift is integrating upstream and downstream operations into unified production trains, reducing facility footprint requirements and batch-to-batch variability.
EMA's revised biosimilar guidelines for recombinant proteins are mandating expanded immunogenicity surveillance and real-world evidence collection post-authorization. Developers must now commit to multi-year patient registries and periodic safety reporting beyond standard pharmacovigilance obligations. Pediatric growth hormone and fertility hormone segments face the steepest compliance burden, with several sponsors extending development timelines to accommodate enhanced clinical data packages.
Hospital formulary consolidation is compressing supplier rosters as integrated delivery networks centralize endocrinology procurement decisions across multi-site systems. Group purchasing organizations are displacing individual physician practice purchasing in the United States, extracting volume-based concessions from recombinant hormone manufacturers. This concentration is most visible in diabetes care, where three national GPOs now influence insulin analog access for over 40% of acute-care beds.
Recombinant Hormone Market Segmentation
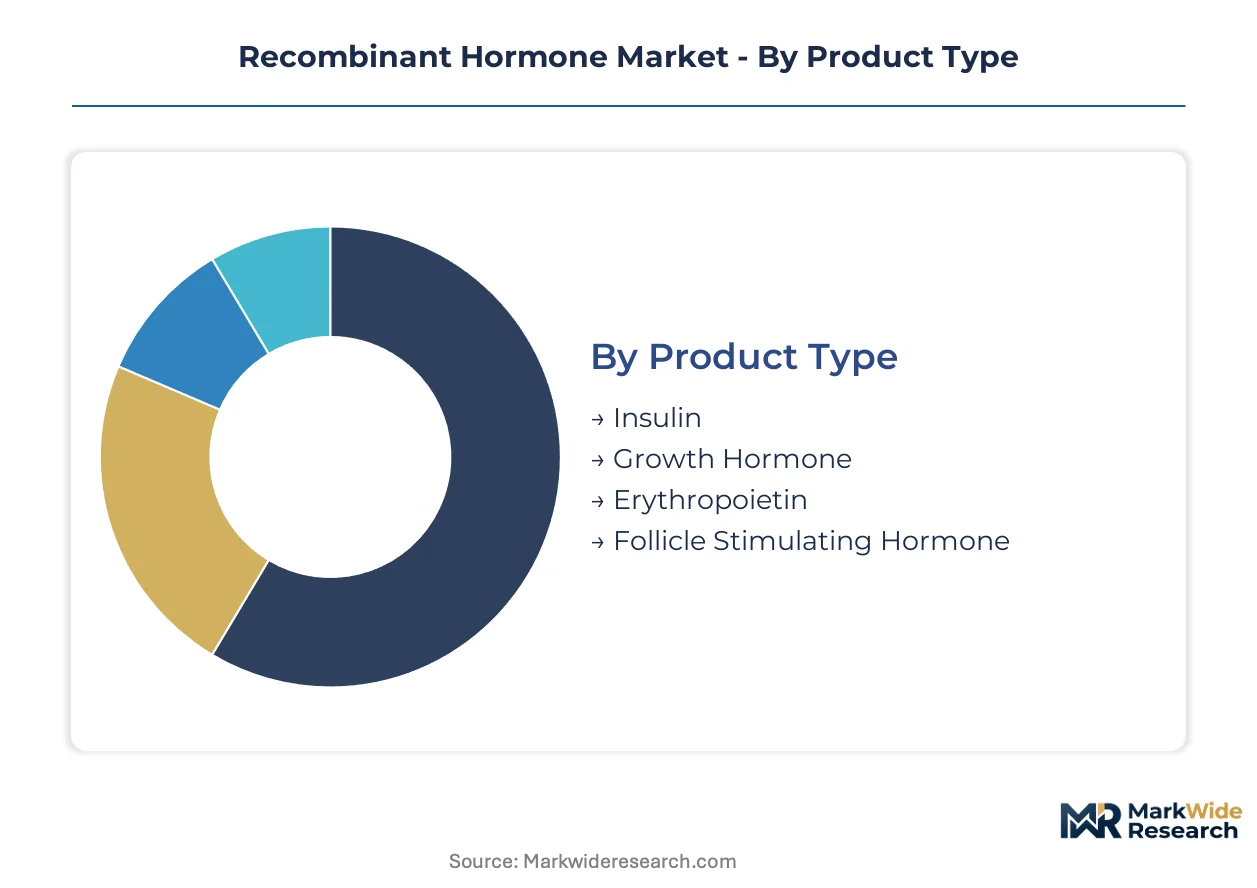
Recombinant hormone procurement patterns diverge sharply across therapeutic categories and care settings. Product lifecycle dynamics and patient acuity levels create distinct upgrade cycles that reshape vendor priorities and channel economics.
Product Type:
Replacement cycles accelerate where biosimilar entry compresses originator exclusivity, forcing portfolio rebalancing toward next-generation formulations.
- Insulin:Recombinant insulin analogs incorporate amino acid substitutions that modify pharmacokinetic profiles for basal and prandial coverage. Demand concentrates in United States integrated delivery networks where three national group purchasing organizations control access for over 40% of acute-care beds, extracting volume-based concessions from manufacturers.
- Growth Hormone:Somatotropin variants require post-translational glycosylation for metabolic stability and receptor binding affinity. Pediatric endocrinology practices in Germany and the United States drive premium procurement despite smaller patient volumes, sustained by delayed diagnosis activation in India and Brazil.
- Erythropoietin:Glycoprotein hormone stimulating red blood cell production in renal anemia.
- Follicle Stimulating Hormone:Gonadotropin products for ovarian stimulation protocols in assisted reproductive technology.
Volume placements concentrate in Insulin; the faster expansion belongs to Follicle Stimulating Hormone.
Application:
Cost tier stratification separates acute intervention protocols from chronic maintenance regimens with divergent reimbursement durability.
- Diabetes Management:Long-acting and rapid-acting insulin analogs dominate therapeutic protocols for Type 1 and Type 2 diabetes. Procurement is shifting toward subcutaneous auto-injector convergence in United States specialty practices, opening adherence-monitoring revenue streams.
- Fertility Treatments:Controlled ovarian stimulation protocols require precise gonadotropin dosing across multiple IVF cycles. Demand is climbing the fastest in United States and Western Europe fertility clinics scaling hormone protocols as delayed childbearing and reimbursed access protocols broaden the addressable patient base.
- Growth Disorders:Pediatric and adult growth hormone deficiency replacement therapy.
- Anemia Treatment:Erythropoiesis-stimulating agent administration in dialysis-dependent chronic kidney disease.
Reimbursement stability favors Diabetes Management; patient activation potential is steepest in Fertility Treatments.
End User:
Channel margin structures reward direct hospital procurement over fragmented retail pharmacy distribution.
- Hospitals:Inpatient and outpatient endocrinology departments administer intravenous erythropoietin and manage acute metabolic complications. Centralized formulary decisions across multi-site systems in the United States compress supplier rosters and displace individual physician practice purchasing.
- Homecare Settings:Self-administered subcutaneous insulin and growth hormone delivery. Convenience-driven adoption concentrates in United States and Western Europe where wearable delivery devices integrate with recombinant hormone formulations for adherence monitoring.
- Clinics:Fertility and endocrinology specialty outpatient facilities.
- Pharmacies:Retail and specialty pharmacy dispensing for maintenance therapy refills.
Procurement scale advantages accumulate to Hospitals; the adherence innovation frontier sits with Homecare Settings.
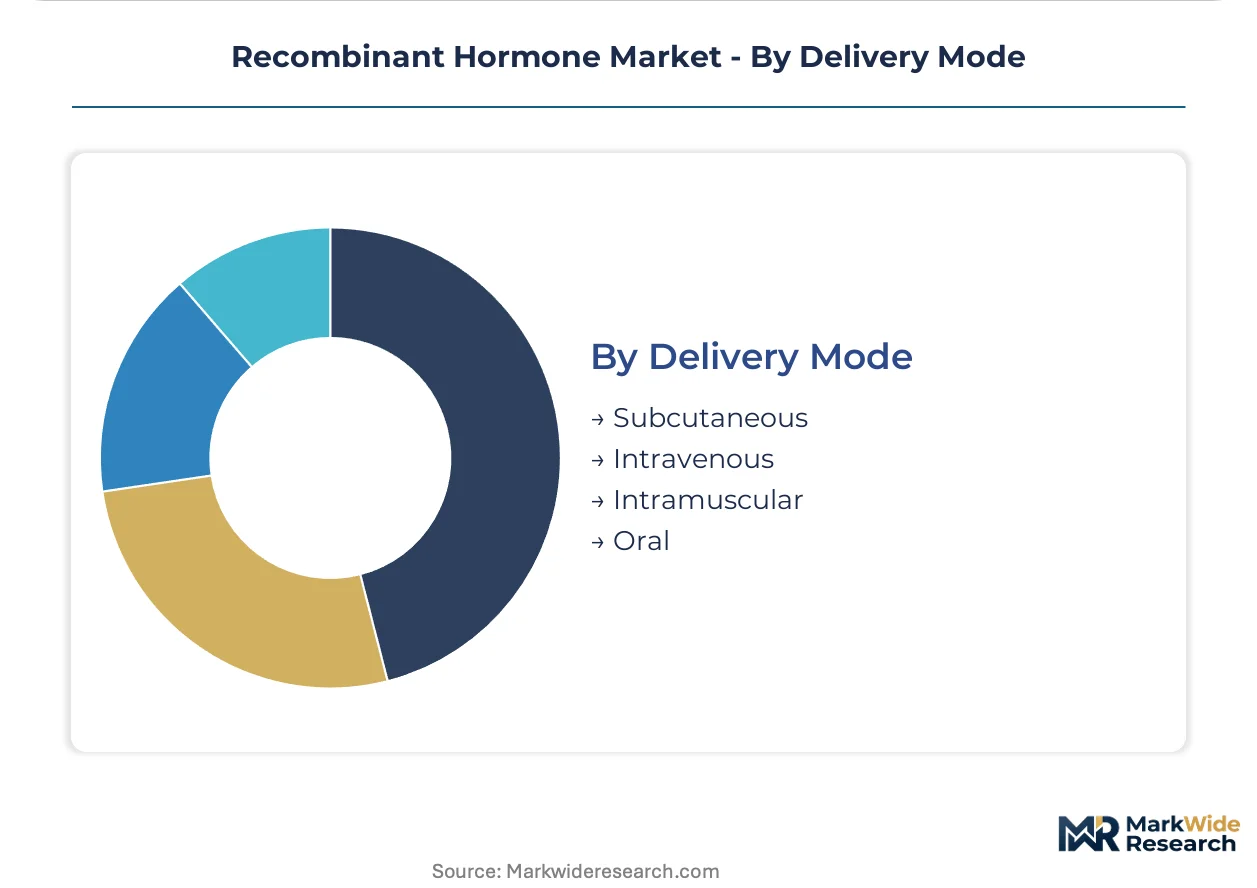
Delivery Mode:
Patient convenience preferences and pharmacokinetic requirements create irreversible shifts away from facility-dependent administration.
- Subcutaneous:Primary route for insulin analogs and growth hormone, enabled by pen-injector and pump technologies. Convenience-driven adoption leads in diabetes and fertility segments as Chinese CDMOs harden manufacturing capacity for recombinant formulations.
- Intravenous:Erythropoietin administration in dialysis settings requires clinical supervision for iron status monitoring and cardiovascular risk management. Demand persists in hospital-based nephrology units despite cold chain infrastructure gaps across Sub-Saharan Africa limiting product stability reach.
- Intramuscular:Depot formulations for extended-release hormone delivery.
- Oral:Emerging delivery technologies bypassing gastrointestinal degradation barriers.
Patient preference momentum favors Subcutaneous; clinical necessity preserves Intravenous in renal care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasmid DNA production clusters in the United States and Germany anchor upstream supply security for recombinant hormone fermentation, while downstream formulation capacity concentrates in Denmark, Switzerland, and India.
United States
Specialty endocrinology practices and hospital systems drive premium-volume procurement of recombinant growth hormone and insulin analogs. FDA's biosimilar approval pathway under the Biologics Price Competition and Innovation Act accelerates competitive entry dynamics. Greater Boston harbors contract development and manufacturing organizations scaling microbial expression platforms for hormone production.
Germany
Pediatric endocrinology practices sustain premium positioning for somatotropin variants despite smaller patient volumes. EMA's scientific advice framework shortens development timelines for biosimilar hormone developers, reducing technical uncertainty. The Rhine-Ruhr metropolitan region concentrates multi-product biologics facilities requiring extensive cleaning validation between recombinant hormone campaigns.
Denmark
Integrated fermentation and purification infrastructure supports European supply continuity for insulin and growth hormone. Novo Nordisk A/S anchors production gravity through captive manufacturing assets. Copenhagen's biologics cluster specializes in post-translational glycosylation engineering for metabolic stability optimization.
India
Domestic CDMOs expand microbial and mammalian expression platforms for cost-competitive hormone supply to emerging markets. BIS certification requirements govern import substitution and local manufacturing scale-up. Hyderabad and Bangalore host contract manufacturers building cold chain distribution networks to address Sub-Saharan Africa infrastructure gaps.
China
NMPA biologics registration rules shape local manufacturing scale-up and import substitution trajectories for recombinant formulations. The Yangtze River Delta concentrates single-use bioreactor system deployment for continuous manufacturing modalities. Shanghai-based facilities integrate perfusion-based cell culture with real-time quality monitoring for extended production runs.
Recombinant Hormone Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory expertise, producing a tiered structure where integrated pharmaceutical conglomerates hold formulation advantages while specialized biologics contractors capture cost-sensitive volume. The vendor base separates into three strategic archetypes: originator innovators with decades of rDNA expertise, biosimilar specialists exploiting abbreviated approval pathways, and emerging-market manufacturers leveraging CDMO partnerships for technology access. Dominant competitive moves include backward integration into plasmid DNA supply and geographic expansion through regional distribution alliances.
Among European-anchored originators, Novo Nordisk A/S and Merck occupy positions exemplifying integrated fermentation infrastructure and biosimilar portfolio breadth respectively. Eli Lilly and Company represents the rDNA insulin heritage archetype, sustaining pricing power through decades of manufacturing experience. These three entities collectively illustrate how regulatory engagement depth and captive production assets determine competitive durability across therapeutic categories.
| Leading Market Players |
|---|
| Merck |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Ipsen Pharma |
| Novartis AG |
| Ferring Pharmaceuticals |
| Pfizer |
| Biocon |
| Roche |
| Others |
Value Network & Pricing Analysis
Captive fermentation infrastructure in Denmark and Switzerland anchors both supply security and pricing power for originator hormone manufacturers, insulating premium-tier portfolios from biosimilar cost compression while forcing contract manufacturers in India and China to compete on volume concessions alone.
Pricing Analysis
Warranty and cold-chain integrity bundling separates originator insulin and growth hormone offerings from unbundled biosimilar alternatives, with full temperature-controlled logistics included in premium contracts. Three-tier pricing structure across originator, authorized biosimilar, and non-interchangeable copy tiers reflects FDA interchangeability designation status and EMA scientific advice pathway completion. Cost compression in the biosimilar tier intensifies as Chinese CDMOs harden microbial expression capacity for emerging market supply. Hospital group purchasing organizations exhibit the sharpest price sensitivity, while pediatric endocrinology practices maintain lowest sensitivity due to clinical familiarity premiums.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network procurement in the United States, while specialty pharmacy distribution serves fertility clinic and homecare segments. Plasmid DNA production clusters in the United States and Germany, with downstream formulation capacity concentrating in Denmark, Switzerland, and India. Critical inputs include mammalian cell lines, microbial expression vectors, and glycosylation-modifying enzymes. Single-source vulnerability in plasmid supply creates concentration risk for fermentation-based manufacturing. Distribution runs through temperature-controlled logistics partners with validated cold chain protocols for biologic stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA's heightened pharmacovigilance requirements for interchangeability designation erect a regulatory moat that rewards players with capital reserves to sustain multi-year patient registries.
For Market Incumbents: Anchor pricing power through backward integration into plasmid DNA supply and captive glycosylation engineering expertise, while defending against biosimilar entrants by accelerating pediatric indication expansions that demand extended clinical data packages. Prioritize formulary lock-in with United States group purchasing organizations before interchangeability designations proliferate. For New Entrants and Emerging Players: Fertility clinics in Southeast Asia represent the most penetrable buyer archetype, with underdeveloped cold chain infrastructure and delayed regulatory harmonization creating temporary shelter from originator competition. Pursue CDMO partnerships with Chinese manufacturers to access microbial expression platforms, then leverage cost advantages to secure hospital tender contracts in price-sensitive emerging markets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated pharmaceutical conglomerates seeking biosimilar portfolio breadth, with IPO viability constrained by EMA's expanded immunogenicity surveillance mandates. Target acquisition candidates with validated post-translational modification capabilities and established FDA correspondence histories. Monitor PMDA Sakigake designation awards as early indicators of premium pricing potential in Japan.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA interchangeability designation accelerates automatic substitution eligibility for biosimilar entrants. |
| Manufacturing Scale-Up | Single-use bioreactor deployment in Yangtze River Delta facilities compresses capital intensity for hormone production. |
| Backward Integration | In-house plasmid DNA production insulates against United States and Germany supply concentration risk. |
| Hospital System Partnership | Integrated delivery network formulary contracts secure volume commitments across multi-site procurement. |
| Reimbursement Strategy | EMA real-world evidence commitments determine post-authorization durability for pediatric growth hormone indications. |
Research Methodology
Document review covered FDA biosimilar approval filings, EMA scientific advice correspondence, ClinicalTrials.gov hormone therapy entries, and hospital formulary databases, complemented by interviews with regulatory affairs leads at biosimilar developers, formulary directors at United States group purchasing organizations, and procurement managers at fertility clinic networks. Secondary validation drew from CMS Medicare reimbursement data, patent expiration records, and CDMO capacity announcements. Bottom-up patient volume estimates and top-down market sizing were triangulated to constrain projection variance.
Cross-referencing historical biosimilar adoption curves against expert panel input on interchangeability designation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to documented patient population expansions and reimbursement access protocol changes. Forecast inputs incorporated assisted reproductive technology cycle growth rates and diabetes prevalence trajectories by geography.
Revisions become necessary when FDA interchangeability standards shift, EMA immunogenicity requirements expand, or plasmid DNA supply disruptions materialize across United States and German production clusters. Forecasts reflect assumptions about regulatory pathway stability and cold chain infrastructure development rates. Periodic stress-testing of base assumptions against biosimilar approval velocity and hospital consolidation trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market