
 Vo5g Market | 2026-2036
Vo5g Market Size, Share, and Industry Trends Forecast 2026-2036
Vo5g Market Analytics
Enterprise manufacturing is collapsing the historical dominance of telecom operators as the primary Vo5G buyer archetype. Nokia Corporation leverages its private wireless heritage to anchor industrial campus deployments. Samsung Electronics competes through end-to-end silicon-to-system integration for latency-critical applications. Ericsson AB dominates European standard-setting bodies while extending its cloud-native core portfolio for hybrid network architectures.
Voice over 5G (Vo5G) refers to packetized voice services delivered over standalone 5G New Radio infrastructure using IMS-based core networks, with QoS mechanisms targeting sub-50ms latency for carrier-grade call completion. The technology replaces circuit-switched fallback dependencies and enables simultaneous voice-data sessions at gigabit throughput rates. Network slicing deployments lead commercial rollout because carriers can isolate voice traffic with guaranteed bandwidth tiers. Edge computing integration represents the fastest-growing technology segment as it positions media processing closer to subscribers. Private network installations command premium margin pools due to customized SLA requirements and dedicated spectrum leases.
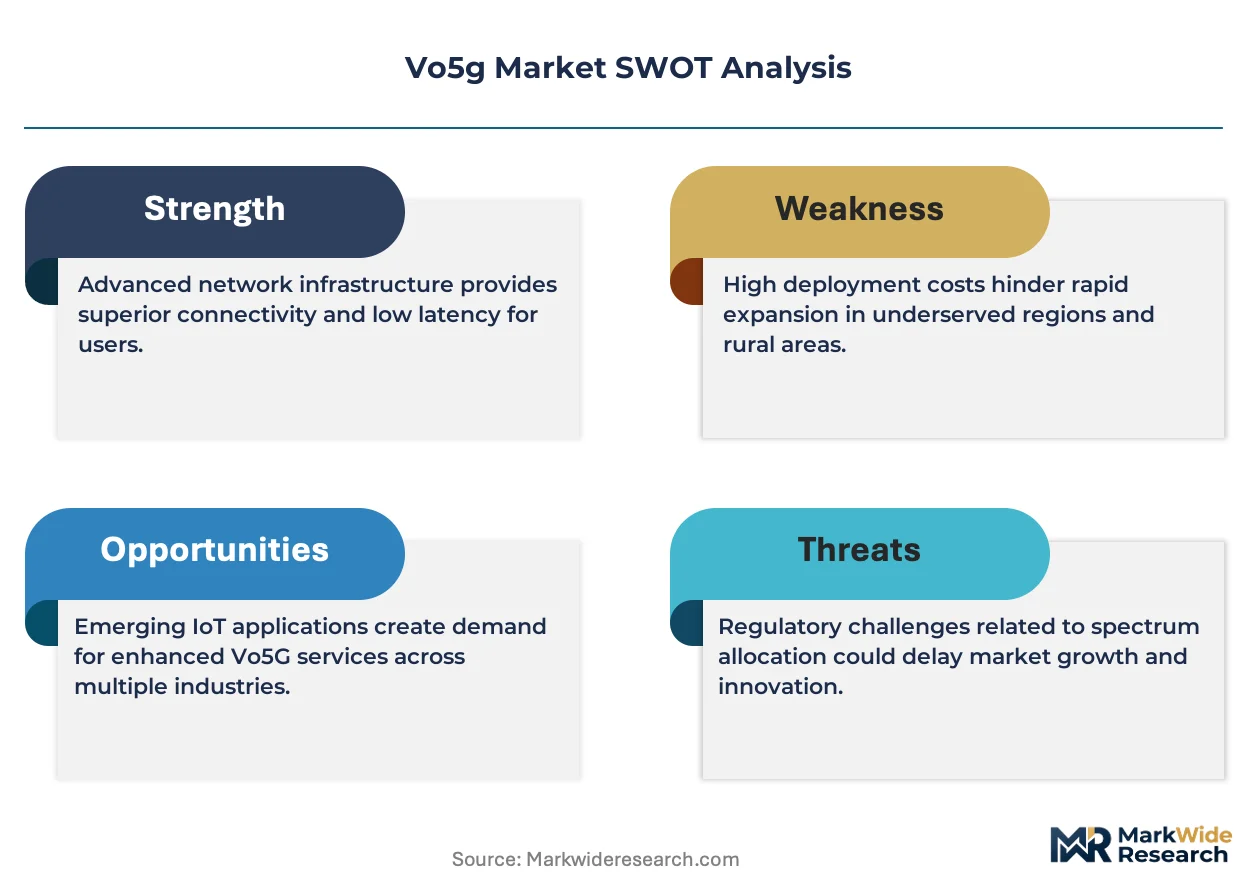
The FCC governs spectrum auctions and open RAN interoperability mandates in the United States, while ETSI and the EU AI Act shape European infrastructure security certification and automated network governance standards. These frameworks compel vendors to engineer modular, audit-ready architectures that accelerate procurement cycles for regulated industries. Stakeholders must monitor spectrum harmonization decisions and private network licensing windows to calibrate deployment timelines against compliance readiness.
Market Dynamics
Standalone 5G New Radio infrastructure is collapsing circuit-switched voice dependencies across carrier networks, forcing IMS core modernization and edge computing investments that reshape vendor procurement priorities.
Growth Catalysts
- EU AI Act compliance mandates:European infrastructure security certification requirements accelerate audit-ready modular architecture adoption among regulated industries.
- Industrial automation demand:Manufacturing end users deploy private Vo5G networks for latency-critical campus connectivity with customized SLA guarantees.
- FCC spectrum auctions:United States open RAN interoperability mandates drive modular vendor procurement cycles and accelerate deployment timelines.
Market Restraints
- Silicon supply concentration:Advanced 5G chipset fabrication depends on concentrated East Asian foundry capacity, creating input volatility risk.
- Legacy IMS integration friction:Circuit-switched fallback dependencies persist in rural coverage zones, complicating pure packet-voice transitions.
- Private spectrum licensing delays:National regulators in key markets slow dedicated frequency allocation for industrial campus deployments.
Strategic Opportunities
- German industrial corridor expansion:Deutsche Telekom anchors early commercial Vo5G deployments, creating reference architectures for automotive and machinery sectors.
- Edge computing convergence:Media processing relocation toward subscriber proximity opens new infrastructure service revenue pools.
- Network slicing monetization:Guaranteed bandwidth tier isolation enables premium voice service packaging for enterprise buyers.
Industry Challenges
- IMS core talent scarcity:Packet voice engineering expertise concentrates among legacy telecom vendors, constraining operator hiring pipelines.
- Multi-vendor interoperability certification:Open RAN disaggregation creates complex testing matrices that prolong deployment validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vo5g Market |
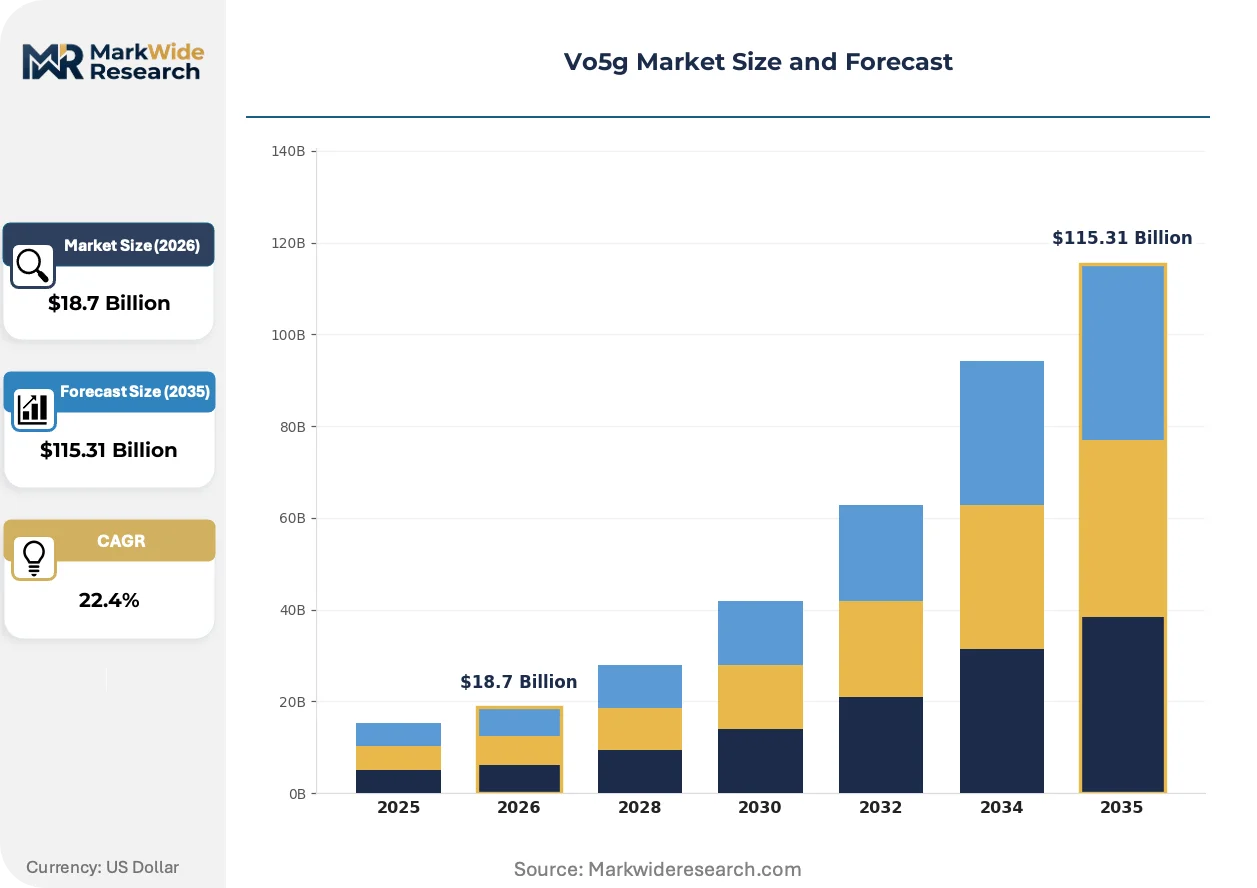
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Private Network, Public Network, Hybrid Network, Cloud-based Application: Smart Cities, Autonomous Vehicles, Industrial Automation, Remote Healthcare Technology: Network Slicing, Edge Computing, Massive MIMO, NFV End User: Telecommunications, Healthcare, Transportation, Manufacturing |
| Companies Covered | Ericsson AB, Nokia Corporation, Huawei Technologies Co., Ltd., Samsung Electronics Co., Ltd., ZTE Corporation, Qualcomm Incorporated, AT&T Inc., Deutsche Telekom AG, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vo5g Market Evolving Landscape
Vo5G infrastructure is fragmenting traditional telecom vendor hierarchies through software-defined disaggregation and edge-native processing architectures.
Cloud-native IMS core software is decomposing monolithic voice platform architectures into containerized microservices. Tier-one carriers in Germany and South Korea adopt these disaggregated stacks for faster feature deployment cycles. This decomposition is compressing incumbent vendor maintenance revenue streams while opening subscription-based software opportunities.
The FCC's open RAN interoperability mandates in the United States force modular interface disclosure across radio units, distributed units, and centralized units. Equipment vendors restructure R&D roadmaps to comply with O-RAN Alliance specifications ahead of procurement eligibility deadlines. Rural carriers and neutral host operators benefit most from multi-vendor mixing flexibility.
Enterprise manufacturing buyers now specify outcome-based network availability contracts rather than capital-intensive hardware purchases. System integrators and telecom operators compete to own these performance-guaranteed relationships. Germany's automotive sector leads this behavioral shift, with machinery producers demanding 99.999% voice availability SLAs tied to production line continuity.
Vo5g Market Segmentation
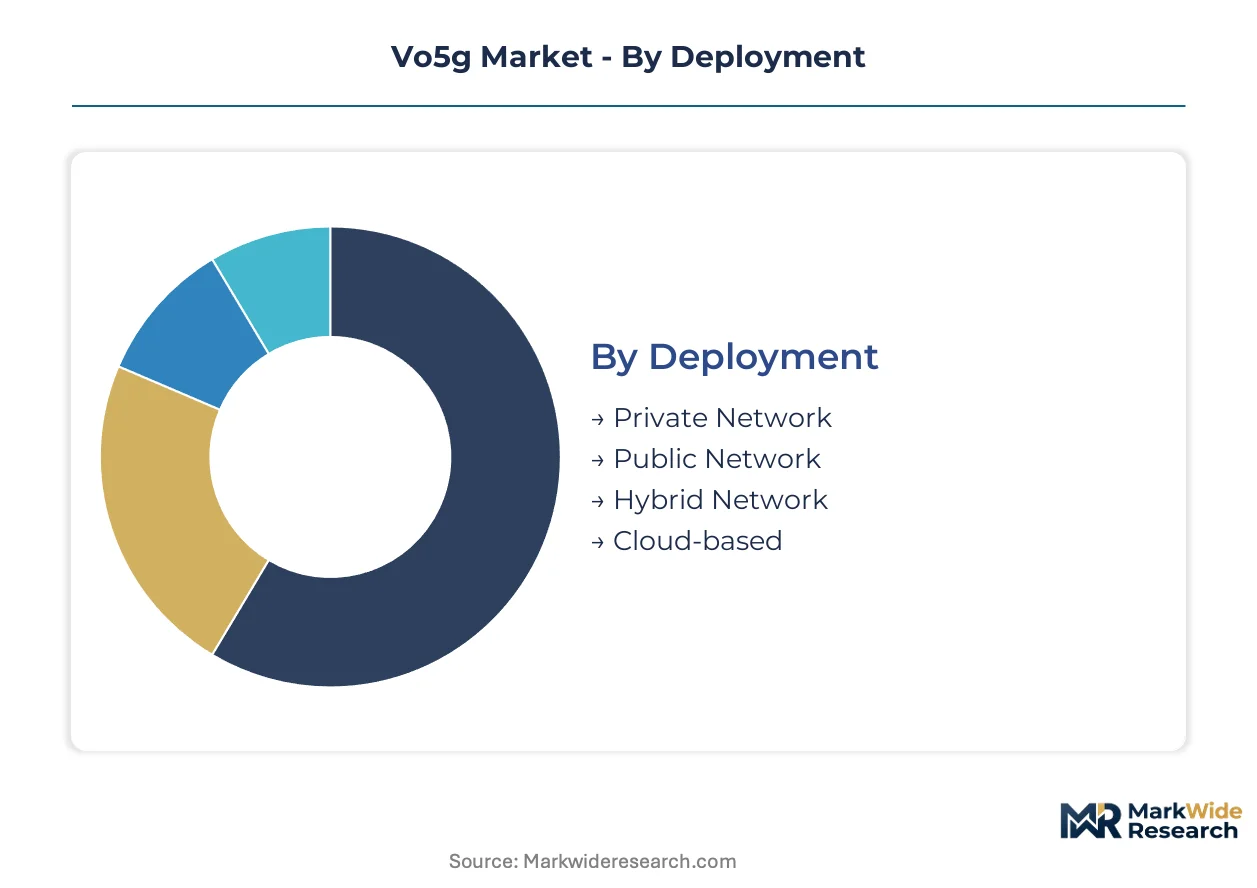
Vo5G market segmentation reveals how infrastructure choices, application requirements, and regulatory environments interact to determine procurement patterns. Each dimension carries distinct compliance obligations and performance benchmarks that shape vendor selection criteria.
Deployment:
FCC spectrum licensing in the United States and EU AI Act infrastructure certification in Europe create divergent cost and compliance profiles across deployment modes.
- Private Network:Dedicated spectrum allocations with customized SLA enforcement support industrial campus requirements for sub-50ms latency guarantees. Manufacturing end users in Germany's automotive corridors prioritize these deployments for production line continuity, though national regulators slow frequency allocation timelines.
- Public Network:Carrier-operated infrastructure leverages existing IMS core investments and scales through standardized QoS tiers. Deutsche Telekom anchors early commercial rollouts in European urban centers where population density justifies capital deployment.
- Hybrid Network:Combines private campus coverage with public network fallback for seamless mobility.
- Cloud-based:Centralized orchestration reduces on-premise hardware footprints through virtualized core functions.
Public network deployments handle the majority of subscriber throughput; private network installations are gaining share fastest among enterprise manufacturing buyers.
Application:
Latency tolerance and availability requirements stratify applications into distinct procurement categories with specialized vendor ecosystems.
- Industrial Automation:Machinery producers demand 99.999% voice availability tied to continuous production operations. South Korean electronics manufacturers and German automotive suppliers drive specification standards for deterministic packet delivery.
- Smart Cities:Municipal infrastructure projects integrate Vo5G into multi-service platforms spanning emergency response, traffic management, and utility coordination. ETSI security certification requirements shape European procurement frameworks.
- Autonomous Vehicles:Vehicle-to-everything communication protocols require guaranteed bandwidth isolation through network slicing.
- Remote Healthcare:HIPAA-compliant session handling and FDA-registered device interoperability dominate United States deployment criteria.
Industrial automation commands premium pricing tiers; smart cities applications are expanding most quickly through municipal infrastructure stimulus programs.
Technology:
Standardization maturity and interoperability certification burdens determine technology adoption velocity across carrier and enterprise environments.
- Network Slicing:Isolated virtual network instances with guaranteed bandwidth tiers enable simultaneous voice-data sessions at gigabit rates. Tier-one carriers deploy slicing first due to existing orchestration platform investments and 3GPP Release 16 compliance readiness.
- Edge Computing:Media processing relocation toward subscriber proximity compresses round-trip latency for latency-critical applications. Manufacturing campuses in Germany and South Korea anchor early commercial deployments.
- Massive MIMO:Spectral efficiency gains through antenna array densification support high-density venue coverage.
- NFV:Virtualized network function decomposition accelerates feature deployment cycles through cloud-native architectures.
Network slicing dominates current carrier deployment volumes; edge computing exhibits the steepest expansion trajectory as enterprise manufacturing buyers specify outcome-based availability contracts.
End User:
Procurement authority and technical specification control vary sharply across end-user categories, reshaping traditional vendor-customer relationships.
- Telecommunications:Traditional carrier buyers specify network-wide availability with IMS core modernization requirements. These customers retain procurement volume leadership but face margin compression from enterprise self-provisioning trends.
- Manufacturing:Industrial campus operators now bypass carriers to negotiate directly with system integrators for private network ownership. Germany's machinery sector leads this behavioral shift toward performance-guaranteed relationships.
- Healthcare:Hospital systems and telemedicine platforms prioritize HIPAA-compliant session handling with FDA-registered device integration.
- Transportation:Logistics operators and public transit authorities specify vehicle-to-infrastructure voice coordination with seamless handoff capabilities.
Telecommunications end users maintain the largest installed base; manufacturing end users are displacing carrier dominance fastest through direct private network procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for advanced 5G silicon clusters in Taiwan and South Korea, while carrier infrastructure deployment concentrates in Germany, the United States, and South Korea where spectrum allocation frameworks have matured fastest.
United States
Enterprise manufacturing campuses and neutral host operators drive private network procurement for industrial automation. The FCC mandates open RAN interoperability disclosure across radio units, distributed units, and centralized units ahead of procurement eligibility windows. Detroit automotive corridors and Houston petrochemical complexes anchor early commercial Vo5G deployments with customized SLA enforcement.
Germany
Machinery producers demand 99.999% voice availability tied to continuous production line operations. The EU AI Act compels infrastructure security certification and automated network governance standards for audit-ready modular architectures. Bavaria and Baden-Württemberg automotive suppliers negotiate directly with system integrators for private network ownership, bypassing traditional carrier relationships.
South Korea
Electronics manufacturers and tier-one carriers adopt cloud-native IMS core software for faster feature deployment cycles. The national regulator accelerates private spectrum licensing for industrial campus deployments under automated governance frameworks. Seoul Capital Area and Busan-Ulsan electronics clusters lead commercial rollouts of edge computing integration for latency-critical media processing.
Japan
Automotive and robotics sectors specify deterministic packet delivery for vehicle-to-everything communication protocols. METI shapes infrastructure investment priorities through standardization mandates and spectrum harmonization decisions. Nagoya automotive corridors and Kanto manufacturing belts deploy network slicing for guaranteed bandwidth isolation in hybrid public-private architectures.
China
Smart city municipal projects and industrial automation platforms integrate Vo5G into multi-service emergency response and utility coordination systems. MIIT governs spectrum allocation and equipment certification through GB standards and dual carbon compliance frameworks. Yangtze River Delta and Pearl River Delta urban centers scale public network slicing deployments through existing orchestration platform investments.
Vo5g Market Competitive Landscape
Concentration sits with legacy telecom infrastructure vendors that retain IMS core expertise and carrier relationships. The vendor base spans three tiers: integrated system providers with end-to-end portfolios, specialized radio access network fabricators, and cloud-native software entrants. Strategic moves center on modular architecture disclosure for open RAN compliance and edge computing partnership structures for enterprise manufacturing penetration.
Within the integrated system tier, Ericsson AB and Nokia Corporation exemplify European heritage vendors with standard-setting body influence and cloud-native core portfolios. Samsung Electronics Co., Ltd. anchors the East Asian fabrication cluster with silicon-to-system integration capabilities. These three entities represent divergent geographic supply chain configurations and regulatory compliance specializations across FCC, EU AI Act, and MIIT jurisdictions.
| Leading Market Players |
|---|
| Ericsson AB |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| Qualcomm Incorporated |
| AT&T Inc. |
| Deutsche Telekom AG |
| NEC Corporation |
| Others |
Value Network & Pricing Analysis
Advanced 5G silicon fabrication scale economies in Taiwan and South Korea compress unit costs for radio access network equipment while simultaneously concentrating supply-side pricing power among foundry operators. This dual concentration elevates price floors for IMS core modernization projects and forces equipment vendors to absorb margin compression or pass costs downstream to carrier and enterprise buyers.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating carrier-grade network slicing deployments from mid-tier hybrid architectures and economy-tier cloud-based virtualized cores. Price differentiation hinges on certification level—EU AI Act audit-ready modular architectures command premiums against FCC open RAN baseline compliance—and customization depth for industrial campus SLA guarantees. Pricing pressure stems from manufacturing end users negotiating direct system integrator relationships that bypass traditional carrier markup structures. Enterprise buyers exhibit highest price sensitivity in cloud-based deployment evaluations, while telecommunications operators absorbing IMS core modernization costs show lowest sensitivity due to stranded asset avoidance imperatives.
Supply Chain Analysis
Inventory lead times for advanced 5G chipsets stretch procurement cycles as foundry capacity allocation prioritizes high-margin AI accelerator silicon over telecommunications infrastructure components. Geographic supply concentration centers on Taiwan for leading-edge radio frequency front-end modules, South Korea for memory and system-on-chip integration, and China for passive component and printed circuit board assembly. Raw material dependencies encompass gallium nitride substrates for power amplifiers, high-purity silicon wafers, and rare earth elements for antenna array magnetic components. Single-source vulnerability pervades sub-6GHz and mmWave filter supply where Murata and Qualcomm dominate patented topologies. Distribution runs through tier-one carrier procurement consortiums in Germany and the United States, with direct OEM relationships gaining share among South Korean electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vo5G infrastructure sits in early-cycle expansion as manufacturing end users displace carrier procurement dominance through direct private network ownership, with EU AI Act compliance mandates accelerating audit-ready modular architecture adoption ahead of regulatory deadlines.
For Market Incumbents: Consolidate IMS core expertise through targeted hiring of packet voice engineering talent from distressed telecom vendors, while anchoring cloud-native microservices portfolios against open RAN disaggregation threats. Ericsson and Nokia must defend European standard-setting body influence against Samsung's silicon-to-system integration push. Capacity addition in German industrial corridors anchors reference architecture credibility for automotive sector replication. Certification investment in EU AI Act automated network governance standards accelerates procurement eligibility for regulated manufacturing buyers. For New Entrants and Emerging Players: Cloud-native IMS core software layers where Ericsson and Nokia maintain legacy maintenance revenue concentration present immediate white-space opportunity. Edge computing media processing partnerships with South Korean electronics manufacturers offer the most penetrable entry vector given their cloud-native adoption velocity. Target outcome-based network availability contracts in Germany's Baden-Württemberg machinery sector where incumbent carrier relationships are actively dissolving. Go-to-market positioning as system integrator-owned performance guarantees rather than hardware vendors captures manufacturing procurement behavioral shifts. For Investors and Strategic Acquirers: Specialized radio access network software vendors with O-RAN Alliance specification compliance and established German automotive sector relationships represent priority acquisition targets. Long-term viability framing centers on 5G-Advanced and 6G standard evolution windows where IMS core expertise retains irreplaceable value against pure-play cloud-native entrants. Watch FCC spectrum auction timing and private network licensing velocity as inflection indicators for manufacturing demand acceleration versus carrier infrastructure refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Core Migration | Containerized microservices compress feature deployment cycles for Deutsche Telekom and SK Telecom. |
| Open RAN Interoperability Certification | O-RAN Alliance compliance unlocks FCC procurement eligibility for neutral host operators. |
| Edge Computing Partnership Structure | Media processing relocation captures outcome-based contracts from German machinery producers. |
| Private Spectrum Licensing Navigation | National regulator engagement accelerates industrial campus deployment timelines against competitor delays. |
| EU AI Act Compliance Investment | Automated network governance certification opens regulated manufacturing procurement channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network planning executives at tier-one carriers, procurement leads at German automotive suppliers, IMS core engineering directors, private network system integrators, and regulatory affairs specialists navigating FCC and EU AI Act compliance pathways. Secondary validation drew from 3GPP release documentation, ETSI security certification standards, FCC spectrum auction records, SEC equipment vendor filings, and national regulator private licensing databases. Bottom-up deployment volume estimates triangulated against top-down infrastructure capex projections from carrier financial disclosures.
Across the analysis window, the forecasting framework modeled deployment mode segmentation against application latency requirements, technology standardization maturity, and end-user procurement authority shifts. Segmentation dimensions encompassed private-public-hybrid-cloud deployment architectures, industrial automation-smart city-autonomous vehicle-remote healthcare application tiers, network slicing-edge computing-massive MIMO-NFV technology trajectories, and telecommunications-manufacturing-healthcare-transportation end-user categories. CAGRs derived from carrier infrastructure rollout schedules, manufacturing capital expenditure surveys, and regulator spectrum allocation timelines. Industry-specific inputs included IMS core modernization project backlogs and private network SLA contract velocity.
Forecasts assume regulatory continuity in FCC open RAN mandates and EU AI Act infrastructure certification regimes; material policy shifts in spectrum allocation frameworks or automated network governance standards would require re-modeling. Silicon supply concentration risk, legacy circuit-switched fallback dependencies, and multi-vendor interoperability certification delays constitute specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Video Encoder Market
Others
Canada Laser Hair Removal Market
Others
Global Contactless Biometrics Technology Market
Others
Hip Tendinitis Market
Others
Nonlinear Editing System Market
Others
Industrial Hooters Market
Others
Coalescing Filter Market
Others
Composite Copper Foil Production Equipment Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Global Cosmetovigilance Market
Others
Versatile Video Coding Market
Others
5G Tester Market
Others
Android STB and TV Market
Others
Japan Indoor LBS Market
Others
Binoculars Market
Others
Smart Home Controller Market