
 Rainbow Flatware/Cutlery Market | 2026-2036
Rainbow Flatware/Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Rainbow Flatware/Cutlery Market Analytics
Artisan metal-finishing expertise is reorganizing production capacity across the rainbow flatware sector as PVD coating specialists become scarce relative to order volumes. Oneida Limited leverages its century-old manufacturing infrastructure to sustain volume production of iridescent stainless steel lines. WMF Group anchors European supply through its in-house electropolishing and vapor deposition capabilities. Zwilling J.A. Henckels differentiates via precision forging expertise applied to thin-gauge rainbow-finish knives with superior edge retention.
Rainbow flatware and cutlery denotes eating and serving utensils featuring interference-color surface treatments—typically titanium-nitride or oxide layers 0.3–2.0 microns thick deposited through physical vapor deposition onto stainless steel substrates—engineered for both corrosion resistance and visual distinction in hospitality and residential settings. The material dimension shows stainless steel commanding the premium tier due to PVD compatibility and dishwasher durability, while plastic and acrylic alternatives occupy price-sensitive party supply channels with shorter replacement cycles. Forks and spoons lead volume within product type classifications, though serving utensils generate disproportionate margin contribution from boutique hospitality procurement.
FDA food-contact substance notifications govern colorant migration limits for coated flatware marketed in the United States, while REACH restrictions on hexavalent chromium and nickel release rates constrain European formulation choices. ECHA substance evaluations are accelerating substitution toward titanium-based coating chemistries that satisfy both regulatory frameworks. Stakeholders must monitor evolving dishwasher-durability testing protocols and coating adhesion standards as these technical specifications increasingly determine wholesale eligibility across major retail and hospitality distribution channels.
Market Dynamics
PVD coating capacity scarcity is restructuring competitive advantage across the rainbow flatware sector, forcing manufacturers to secure captive vapor deposition infrastructure or face exclusion from premium hospitality procurement channels.
Growth Catalysts
- REACH titanium-chemistry substitution:ECHA substance evaluations accelerate reformulation away from hexavalent chromium coatings, opening qualified supplier slots for titanium-nitride specialists in European hospitality supply chains.
- Experiential dining procurement:North American boutique hotels and chef-driven restaurants specify iridescent tableware for Instagram-native presentation formats, converting flatware from commodity to branded experience component.
- Social media entertaining:Residential consumers in Germany, Japan, and the United States prioritize aesthetic kitchenware visibility, driving replacement cycles for coordinated serveware collections.
Market Restraints
- PVD equipment concentration:Vapor deposition system manufacturing concentrates among German and Japanese capital equipment suppliers, creating 12-18 month lead times for capacity expansion.
- Nickel release thresholds:REACH Annex XVII nickel migration limits constrain substrate alloy selection, disqualifying cost-competitive 200-series stainless grades from European food-contact applications.
- Acrylic substitution in party supply:Single-use iridescent plastic flatware captures price-sensitive event catering, compressing addressable market for durable coated metal alternatives in disposable-use occasions.
Strategic Opportunities
- Dishwasher-durability certification gaps:Absence of unified coating adhesion testing protocols creates first-mover advantage for suppliers establishing proprietary 500+ cycle validation standards with major retail buyers.
- Gradient-finish serving utensil white space:Boutique hospitality procurement underweights spoons and forks relative to margin-rich serving pieces, opening specialized SKU development for sommelier and chef-table presentations.
- Japan METI circular material incentives:National subsidy frameworks for durable goods with verified end-of-life recyclability reward PVD-coated 18/10 stainless over disposable alternatives in institutional procurement.
Industry Challenges
- Artisan metal-finishing talent scarcity:Electropolishing and vapor deposition technician pipelines lag order volume growth, forcing wage inflation at coating subcontractors.
- FDA notification timeline compression:Food-contact substance notification review cycles for novel colorant chemistries extend 18-24 months, delaying product launches for reformulated coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rainbow Flatware/Cutlery Market |
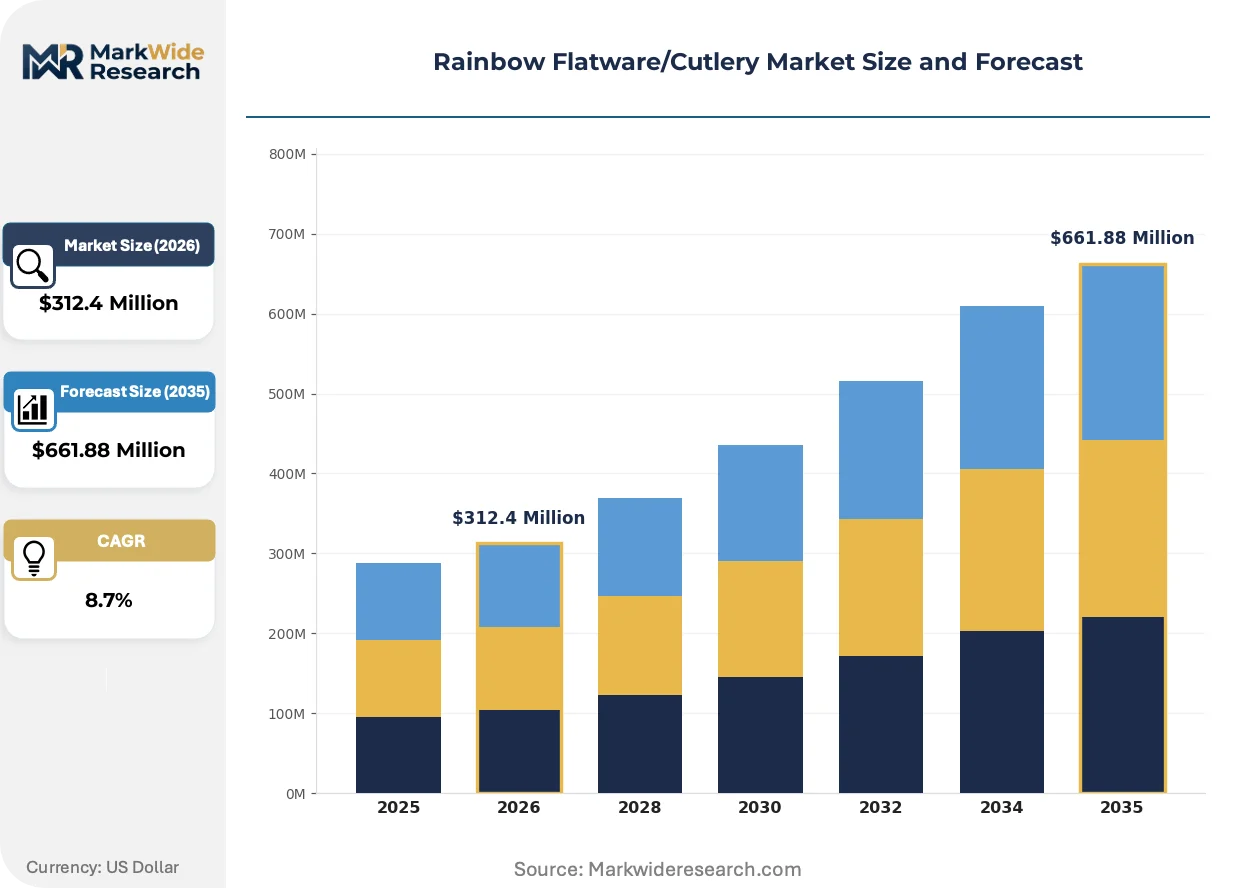
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forks, Knives, Spoons, Serving Utensils Material: Stainless Steel, Plastic, Bamboo, Acrylic Color Finish: Metallic, Glossy, Matte, Gradient Use Case: Home Use, Party Supplies, Catering, Outdoor Events |
| Companies Covered | Elyon Tableware, Snb Enterprises Private Limited, Iqra Home Collection, Berglander Inc., Fine Arts Overseas, Oneida Limited, Lenox Corporation, WMF Group, Zwilling J.A. Henckels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rainbow Flatware/Cutlery Market Evolving Landscape
Coating chemistry evolution and procurement model fragmentation are simultaneously expanding performance boundaries and complicating supplier qualification protocols across rainbow flatware manufacturing.
Multi-layer oxide deposition is decomposing the trade-off between color saturation and corrosion resistance in titanium-based PVD systems. German hospitality suppliers now specify 1.5-2.0 micron coating stacks for coastal venue deployments. This thickness threshold is decomposing legacy single-layer process economics and compressing viable supplier pools to capital-intensive operations.
REACH authorization list expansion is tightening hexavalent chromium exemptions for decorative coatings on food-contact articles. European manufacturers face 2026 sunset dates for legacy colorant formulations in several member states. Mid-tier suppliers without titanium-nitride process validation are accelerating facility upgrades to maintain wholesale eligibility with EEA distributors.
Direct-to-hotel procurement platforms are disintermediating traditional tableware distributors for property-level replenishment orders. Boutique hospitality groups in California and New York now specify coating batch consistency requirements directly with manufacturers. This channel compression rewards suppliers with in-house quality documentation systems over those dependent on distributor-managed specifications.
Rainbow Flatware/Cutlery Market Segmentation
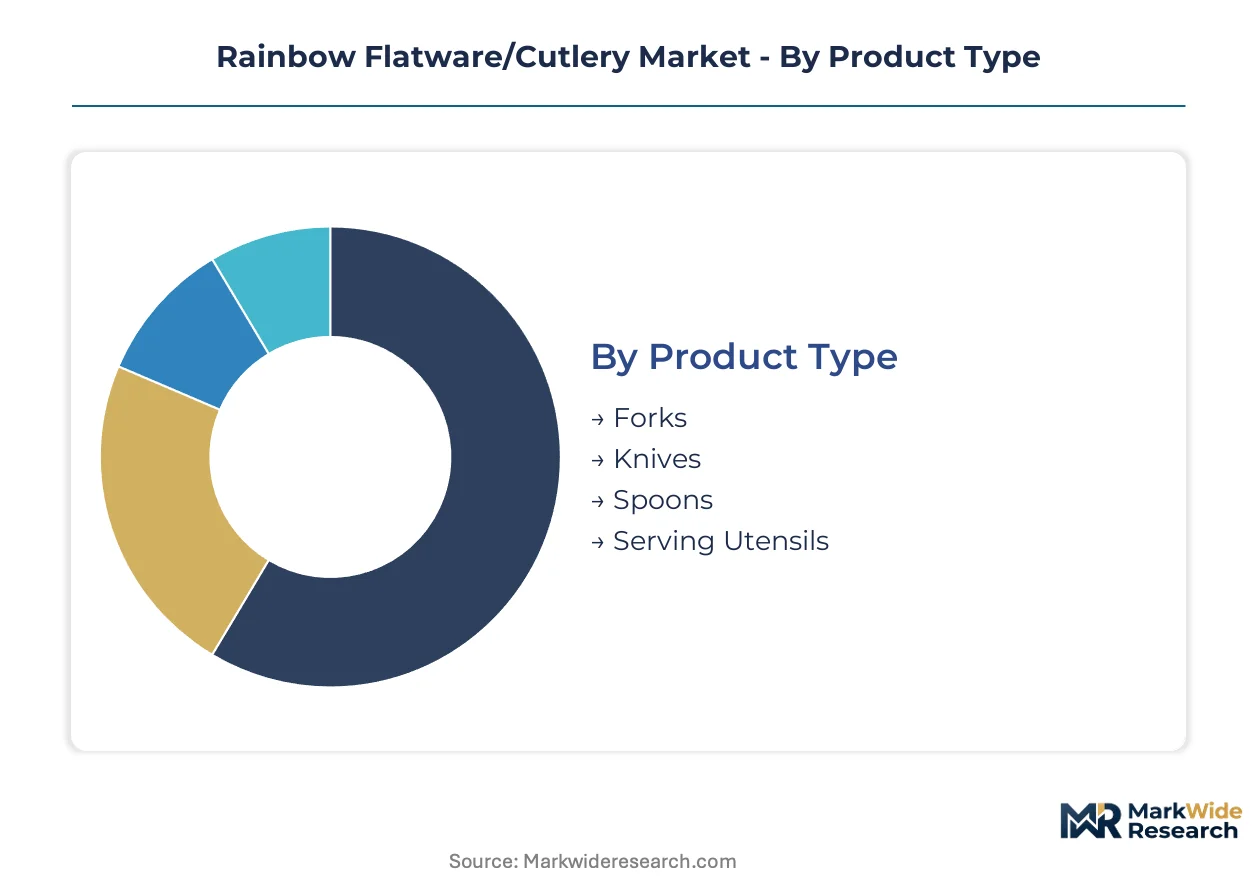
Rainbow flatware segmentation reveals divergent supply chain configurations across material tiers and finish technologies. PVD-coated stainless steel routes through German and Japanese capital equipment networks, while plastic and acrylic alternatives source from injection-molding clusters with shorter lead times and lower regulatory exposure.
Product Type:
Forks and spoons dominate export volumes to North American hospitality buyers, whereas serving utensils concentrate in domestic procurement for European boutique hotels and chef-table venues. Knives split between export-led premium forged lines and locally sourced stamped alternatives for residential replacement cycles.
- Forks:Four-tine designs with 18/10 stainless substrates receive standard PVD treatment for dishwasher durability. Demand clusters in United States experiential dining procurement, where Instagram-native presentation formats drive coordinated tableware specifications.
- Knives:Precision-forged blades with thin-gauge rainbow finishes require specialized edge-retention engineering that only captive PVD operations can deliver. German hospitality supply chains prioritize these for chef-table presentations where cutting performance must match visual distinction.
- Spoons:Deep-bowl soup and dessert variants occupy high-volume residential channels in Japan and Germany, where social media entertaining elevates aesthetic serveware visibility.
- Serving Utensils:Sommelier and buffet pieces generate disproportionate margin contribution from boutique hospitality procurement despite lower unit volumes.
Forks hold the largest share; momentum sits with serving utensils as margin-rich hospitality procurement expands.
Material:
Cost tier stratification separates capital-intensive PVD-compatible metals from price-sensitive disposables, with mid-tier bamboo occupying sustainability-positioned niches.
- Stainless Steel:18/10 and 18/8 grades with titanium-nitride PVD compatibility anchor premium tier production. REACH nickel release thresholds constrain alloy selection, disqualifying cost-competitive 200-series grades from European food-contact applications.
- Plastic:Single-use iridescent injection-molded pieces capture price-sensitive event catering in United States party supply channels with compressed replacement cycles.
- Bamboo:Lacquered and heat-treated variants appeal to sustainability-positioned residential buyers in Germany and Japan seeking alternatives to petroleum-based disposables.
- Acrylic:Transparent and opaque iridescent finishes occupy disposable-use occasions where metal durability carries no premium.
Stainless steel commands value concentration; bamboo climbs fastest on sustainability credentials.
Color Finish:
Application requirements dictate finish selection, with hospitality venues specifying multi-layer oxide stacks that residential channels rarely demand.
- Metallic:Titanium-nitride interference layers deliver the signature rainbow spectrum through controlled oxide thickness. German coastal venues now specify 1.5-2.0 micron coating stacks for corrosion resistance in salt-air environments.
- Glossy:High-reflectance topcoats maximize light interaction for social media photography. Japanese residential buyers prioritize these for visible kitchenware collections.
- Matte:Diffused surface treatments reduce fingerprint visibility and glare in professional kitchen environments.
- Gradient:Color-transition effects require precision deposition control that only established PVD specialists can achieve, creating supply scarcity for boutique hospitality specifications.
Metallic finishes dominate volume; gradient applications expand most quickly as experiential dining procurement intensifies.
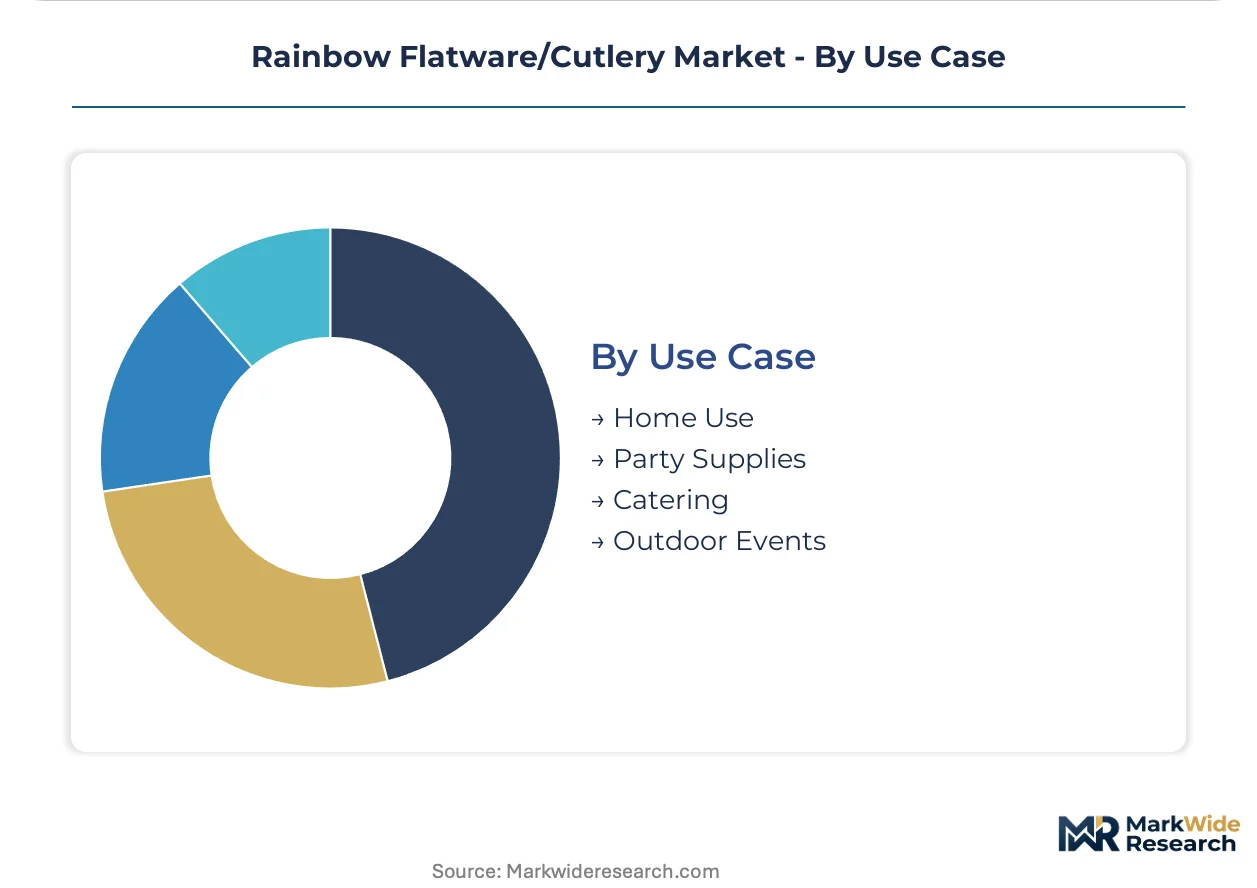
Use Case:
Customer type fragmentation separates durable goods procurement with extended replacement cycles from single-use channels with immediate replenishment patterns.
- Home Use:Coordinated serveware collections for social media-driven entertaining drive replacement cycles in United States, Germany, and Japan residential segments. Consumers prioritize aesthetic visibility over utilitarian durability.
- Party Supplies:Single-use and limited-durability flatware serves price-sensitive event catering where disposal economics outweigh lifecycle cost considerations.
- Catering:Commercial foodservice operations balance durability requirements against loss rates, often selecting mid-tier stainless or reinforced plastic alternatives.
- Outdoor Events:Festival and wedding venues specify lightweight, transportable options with sufficient visual distinction for photographed occasions.
Home use captures the greatest value pool; catering shows steepest expansion trajectory as experiential dining formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospitality procurement prioritizes chef-table presentation formats, while Japanese residential buyers emphasize visible kitchenware collections for social media documentation. United States demand splits between experiential dining venues and home entertaining segments, creating divergent specification requirements across these three major consumption centers.
United States
Instagram-native presentation formats at boutique hotels and chef-driven restaurants drive iridescent tableware specifications. FDA food-contact substance notifications govern colorant migration limits for coated flatware marketed domestically. California and New York hospitality groups now specify coating batch consistency requirements directly with manufacturers, bypassing traditional distributors.
Germany
Experiential dining procurement at boutique hotels and coastal venues specifies multi-layer oxide coating stacks for salt-air corrosion resistance. REACH Annex XVII nickel migration limits constrain substrate alloy selection, disqualifying cost-competitive grades from food-contact applications. Solingen's metal-finishing cluster anchors European supply through established electropolishing and vapor deposition infrastructure.
Japan
Residential consumers prioritize aesthetic kitchenware visibility for social media-driven entertaining, accelerating replacement cycles for coordinated serveware. METI circular material incentives reward durable goods with verified end-of-life recyclability, favoring PVD-coated stainless over disposable alternatives. Osaka-based hospitality suppliers concentrate procurement for visible tableware collections in luxury venue segments.
United Kingdom
Boutique hospitality groups in London specify gradient-finish serving utensils for sommelier and chef-table presentations. ECHA substance evaluations accelerate reformulation toward titanium-based coating chemistries that satisfy REACH frameworks. Sheffield's historical metalworking cluster maintains specialized finishing expertise for premium flatware specifications.
France
Luxury hotel procurement in Paris and Provence drives demand for iridescent serving pieces with margin-rich positioning. EU Green Deal circularity requirements shape material selection toward durable, recyclable substrates. Lyon-based hospitality distributors coordinate specifications between coastal venues and inland boutique properties.
Rainbow Flatware/Cutlery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the rainbow flatware sector, with PVD coating capabilities determining tier placement. Stainless steel fabricators with captive vapor deposition infrastructure command premium hospitality procurement channels, while coating-dependent subcontractors face volume constraints. Three archetypes dominate: century-old tableware houses with legacy finishing expertise, German precision metalworkers with in-house electrochemical capabilities, and Asian contract manufacturers serving price-sensitive residential segments. Competitive moves concentrate on securing PVD equipment allocation and establishing proprietary dishwasher-durability certification standards with major retail buyers.
Among heritage-anchored manufacturers, Oneida Limited exemplifies the integrated leader archetype through its century-old manufacturing infrastructure sustaining volume production of iridescent stainless steel lines. WMF Group occupies a parallel position in European supply through its in-house electropolishing and vapor deposition capabilities. Zwilling J.A. Henckels represents the precision-forging specialist tier, applying thin-gauge finishing expertise to rainbow-finish knives where edge retention must match visual distinction.
| Leading Market Players |
|---|
| Elyon Tableware |
| Snb Enterprises Private Limited |
| Iqra Home Collection |
| Berglander Inc. |
| Fine Arts Overseas |
| Oneida Limited |
| Lenox Corporation |
| WMF Group |
| Zwilling J.A. Henckels |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between hospitality procurement groups and PVD coating specialists lock in both titanium-nitride capacity allocation and price visibility across 12-18 month equipment lead times. This contract structure insulates premium flatware manufacturers from spot volatility in German and Japanese capital equipment markets while committing buyers to volume minimums that sustain coating subcontractor wage inflation.
Pricing Analysis
Project-based capacity reservations dominate premium tier procurement as hospitality groups secure coating batch consistency guarantees directly with manufacturers. Price differentiation rests on PVD layer thickness certification and REACH-compliant titanium-chemistry validation, with gradient-finish serving utensils commanding premium positioning over standard metallic flatware. Cost compression in mid-tier stamped knives is intensifying because acrylic substitution in party supply channels erodes metal flatware addressable market. Event catering buyers exhibit highest price sensitivity; boutique chef-table venues demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of 18/10 stainless substrate dominates procurement patterns as REACH nickel release thresholds constrain alloy selection and disqualify 200-series alternatives. Supply concentrates in Germany's Solingen finishing cluster, Japan's Osaka-based hospitality suppliers, and China's injection-molding networks for acrylic disposables. Raw material dependencies draw from Swedish stainless steel mills, German vapor deposition equipment manufacturers, and Chinese titanium pigment processors. Single-source vulnerability runs through Japanese PVD system suppliers. Distribution runs through direct-to-hotel procurement platforms disintermediating traditional tableware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization list expansion for hexavalent chromium coatings constitutes a regulatory inflection accelerating titanium-nitride chemistry substitution and reshaping competitive qualification requirements across European supply chains.
For Market Incumbents: Shield market position through captive PVD infrastructure acquisition or long-term equipment offtake commitments before coating capacity scarcity deepens. Certification investment in proprietary 500+ cycle dishwasher-durability validation creates wholesale eligibility barriers against coating-dependent subcontractors facing volume constraints from artisan metal-finishing talent scarcity. For New Entrants and Emerging Players: Lead with gradient-finish serving utensil specialization targeting boutique hospitality procurement's margin-rich white space in sommelier and chef-table presentations. Japan's METI circular material incentives offer the most penetrable institutional channel for durable PVD-coated stainless alternatives. Go-to-market execution should leverage direct procurement platform relationships bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with in-house electropolishing and vapor deposition capabilities over coating-dependent assembly operations. Long-term viability over a 5-10 year window rests on regulatory compliance moats and equipment captive supply. Acquisition targets should demonstrate validated titanium-nitride process documentation and established quality documentation systems. The signal to watch is FDA food-contact substance notification timeline compression for novel colorant chemistries as product launch delays reshape competitive pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive PVD Infrastructure Acquisition | Secures coating capacity allocation against 12-18 month equipment lead times from German and Japanese suppliers. |
| Proprietary Dishwasher-Durability Certification | Establishes wholesale eligibility barriers with major retail buyers through validated 500+ cycle adhesion standards. |
| Gradient-Finish Serving Utensil Development | Captures margin-rich boutique hospitality procurement underweighting spoons and forks relative to presentation pieces. |
| Direct-to-Hotel Platform Integration | Bypasses traditional distributor markups as California and New York hospitality groups specify batch consistency directly. |
| REACH Titanium-Chemistry Reformulation | Maintains European wholesale eligibility as ECHA substance evaluations accelerate hexavalent chromium substitution deadlines. |
Research Methodology
A spread of perspectives from PVD coating technicians, hospitality procurement directors, stainless steel mill account managers, and FDA regulatory consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from flatware manufacturers, ECHA substance evaluation databases, FDA food-contact substance notification records, and customs trade data tracking titanium-nitride equipment imports. Bottom-up demand modeling across hospitality and residential segments triangulated with top-down market sizing from capital equipment shipment records.
Segmentation dimensions modeled include material substrate grade, color finish technology, product type classification, use case channel, and regional regulatory cluster across the projection horizon. CAGRs were derived from equipment capacity expansion pipelines, hospitality procurement survey data, and replacement cycle analysis for coordinated serveware collections. Industry-specific forecast inputs incorporated PVD coating thickness specification trends and dishwasher-durability testing protocol evolution.
Forecasts assume regulatory continuity in FDA food-contact substance review timelines and REACH authorization list implementation; material policy shifts would require re-modeling of product launch pacing and chemistry reformulation costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
North America Kitchen Furniture Market